
 US Anti-Snoring Devices and Snoring Surgery Market | 2026-2036
US Anti-Snoring Devices and Snoring Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
US Anti-Snoring Devices and Snoring Surgery Market Intelligence
Modular product configurations is decoupling device sales from traditional bundled sleep-study packages, letting patients purchase mandibular advancement devices and nasal dilators directly through dental practices or online channels. ResMed Inc. leverages its integrated digital health platform to sustain recurring revenue from CPAP adherence monitoring. SomnoMed Ltd. anchors its position through specialized dental partnerships that control fitting and adjustment workflows for oral appliances.
Anti-snoring devices and snoring surgery encompass mechanical, electronic, and surgical interventions designed to maintain upper airway patency during sleep, with mandibular advancement devices typically constructed from medical-grade thermoplastic polymers that permit incremental jaw repositioning across millimeter-calibrated adjustment ranges. The primary commercial purpose centers on reducing pharyngeal airway collapse to eliminate or attenuate snoring and associated obstructive sleep apnea symptoms. Mandibular advancement devices and custom dental appliances capture disproportionate margin pools due to lower capital requirements and direct-to-patient accessibility through dental practices, while surgical procedures and radiofrequency ablation segments serve refractory cases with higher reimbursement thresholds but concentrated provider capacity. Nasal devices occupy a mature, price-sensitive tier where commoditization pressures limit differentiation beyond material comfort and fit precision.
FDA 510(k) clearance requirements and HIPAA privacy mandates shape product development timelines and data-handling protocols for connected sleep devices, with the former dictating clinical evidence standards and the latter constraining cloud-based therapy monitoring architectures. State dental board regulations across California, New York, and Texas govern scope-of-practice boundaries for oral appliance fitting, creating fragmented channel access that manufacturers must navigate through credentialed provider networks. Stakeholders should monitor evolving Medicare Local Coverage Determinations for home sleep testing and oral appliance therapy, as these reimbursement decisions will reshape patient funnel economics and provider investment priorities.
Market Dynamics
FDA 510(k) clearance streamlining for mandibular advancement devices is compressing product development timelines and eroding incumbent advantages in oral appliance categories. This regulatory acceleration is redistributing competitive leverage toward dental-specialized manufacturers with established provider networks.
Growth Catalysts
- Home sleep testing expansion:Medicare Local Coverage Determinations for unattended polysomnography are expanding diagnostic access beyond traditional sleep lab infrastructure. This broadens the patient funnel for downstream device and surgical interventions.
- Obesity-driven airway collapse:Elevated body mass index prevalence in Texas, Florida, and California generates sustained demand for both non-invasive mandibular devices and uvulopalatopharyngoplasty procedures.
- Thermoplastic polymer customization:Medical-grade copolyester and nylon variants with millimeter-calibrated adjustability improve device tolerance and reduce abandonment rates.
Market Restraints
- Surgical capacity concentration:Board-certified otolaryngologists performing hypoglossal nerve stimulation and maxillomandibular advancement cluster in major metropolitan corridors, creating access bottlenecks for rural and exurban patients.
- CPAP residual efficacy:Continuous positive airway pressure retains gold-standard status for moderate-to-severe obstructive sleep apnea, limiting oral appliance capture in severe-case segments.
- HIPAA cloud architecture constraints:Privacy mandates impose data-handling protocols that increase development costs for connected adherence-monitoring platforms.
Strategic Opportunities
- Direct-to-patient dental channels:Online-fitted mandibular devices and teledentistry workflows bypass traditional sleep-study bundling, capturing margin pools previously allocated to diagnostic intermediaries.
- Radiofrequency ablation outpatient migration:Office-based soft palate stiffening procedures reduce facility fees and expand addressable volumes beyond hospital-based surgery.
- State dental board scope expansion:Regulatory clarity in New York and Texas on hygienist-assisted fitting protocols could accelerate oral appliance penetration through general dentistry practices.
Industry Challenges
- Polysomnography technologist shortages:Limited accredited training programs constrain sleep lab throughput and diagnostic appointment availability.
- Cross-state licensing fragmentation:Dental practitioners fitting custom oral appliances face credentialing reciprocity barriers that complicate multi-state provider network construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Anti-Snoring Devices and Snoring Surgery Market |
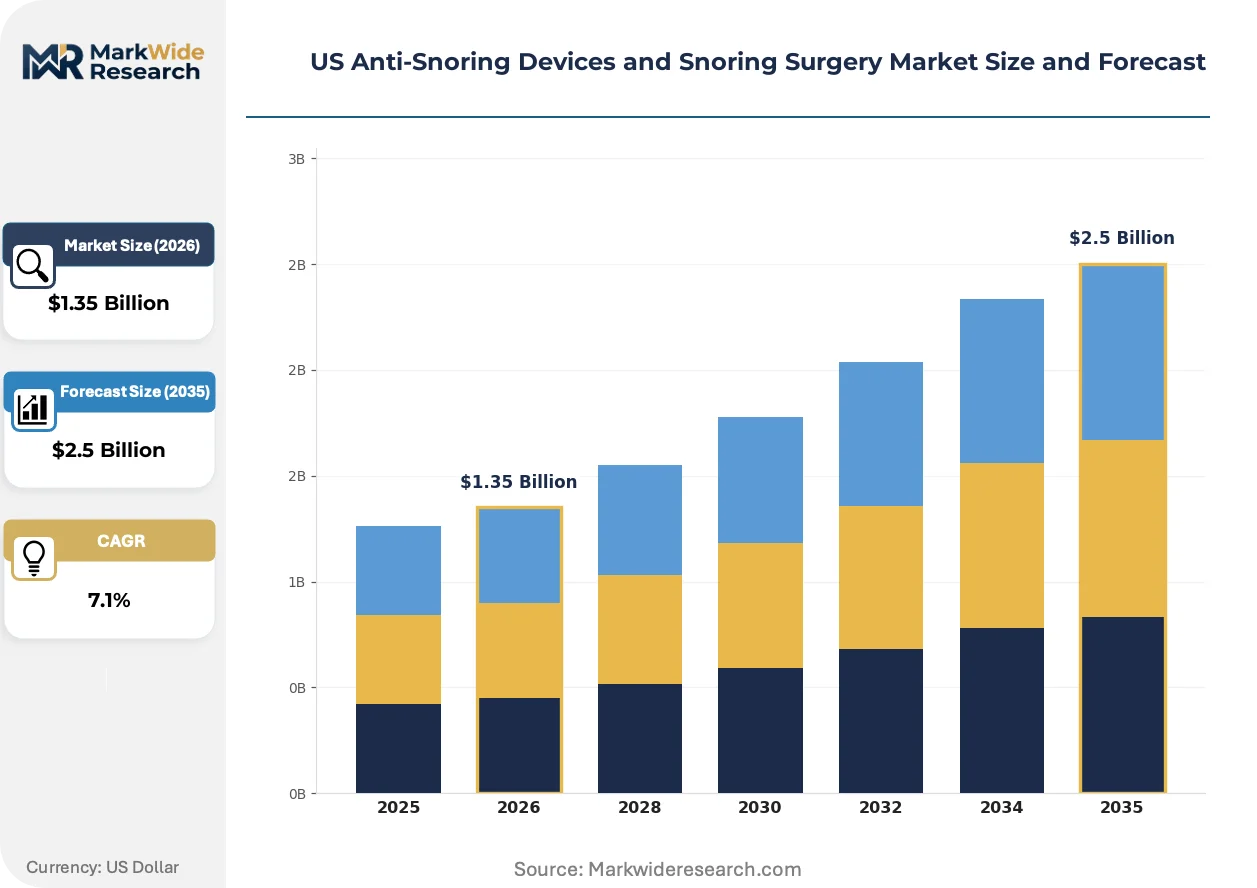
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mandibular Advancement Devices, Continuous Positive Airway Pressure, Nasal Devices, Custom Dental Appliances Technology: Laser Therapy, Radiofrequency Ablation, Surgical Procedures, Positional Therapy End User: Hospitals, Sleep Clinics, Home Care Settings, Dental Practices Application: Obstructive Sleep Apnea, Snoring Treatment, Dental Solutions, Surgical Interventions |
| Companies Covered | ResMed Inc., SomnoMed Ltd., Fisher & Paykel Healthcare Corp. Ltd., Koninklijke Philips NV, Airway Management, Inc., Tomed Dr. Toussaint GmbH, ProSomnus Sleep Technologies, Apnea Sciences Corporation, Vivos Therapeutics, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Anti-Snoring Devices and Snoring Surgery Market Strategic Shifts & Innovations
Digital health integration is unifying diagnostic, therapeutic, and adherence-monitoring functions into single-platform ecosystems. This convergence is compressing traditional channel boundaries between sleep medicine, dentistry, and direct-to-consumer distribution.
Smart mandibular advancement devices with embedded pressure sensors and Bluetooth connectivity are unifying real-time jaw position tracking with cloud-based therapy optimization. Sleep clinics and dental practices in California are adopting these systems to reduce in-person adjustment visits. The technology is unifying hardware sales with recurring software subscriptions, shifting revenue models toward adherence-dependent monetization.
FDA breakthrough device designation pathways for hypoglossal nerve stimulation systems are accelerating clinical evidence requirements and premarket review timelines. This regulatory pressure is forcing manufacturers to front-load pivotal trial investment. Implantable neurostimulation segments face compressed development cycles and elevated capital requirements.
Patients are bypassing traditional sleep-lab referrals through direct-purchase nasal dilators and boil-and-bite mandibular devices from e-commerce platforms. This channel disintermediation is fragmenting diagnostic oversight and shifting clinical accountability toward dental practices. Texas and Florida demonstrate the strongest direct-to-consumer velocity, correlating with limited Medicaid sleep-medicine coverage.
US Anti-Snoring Devices and Snoring Surgery Market Segmentation
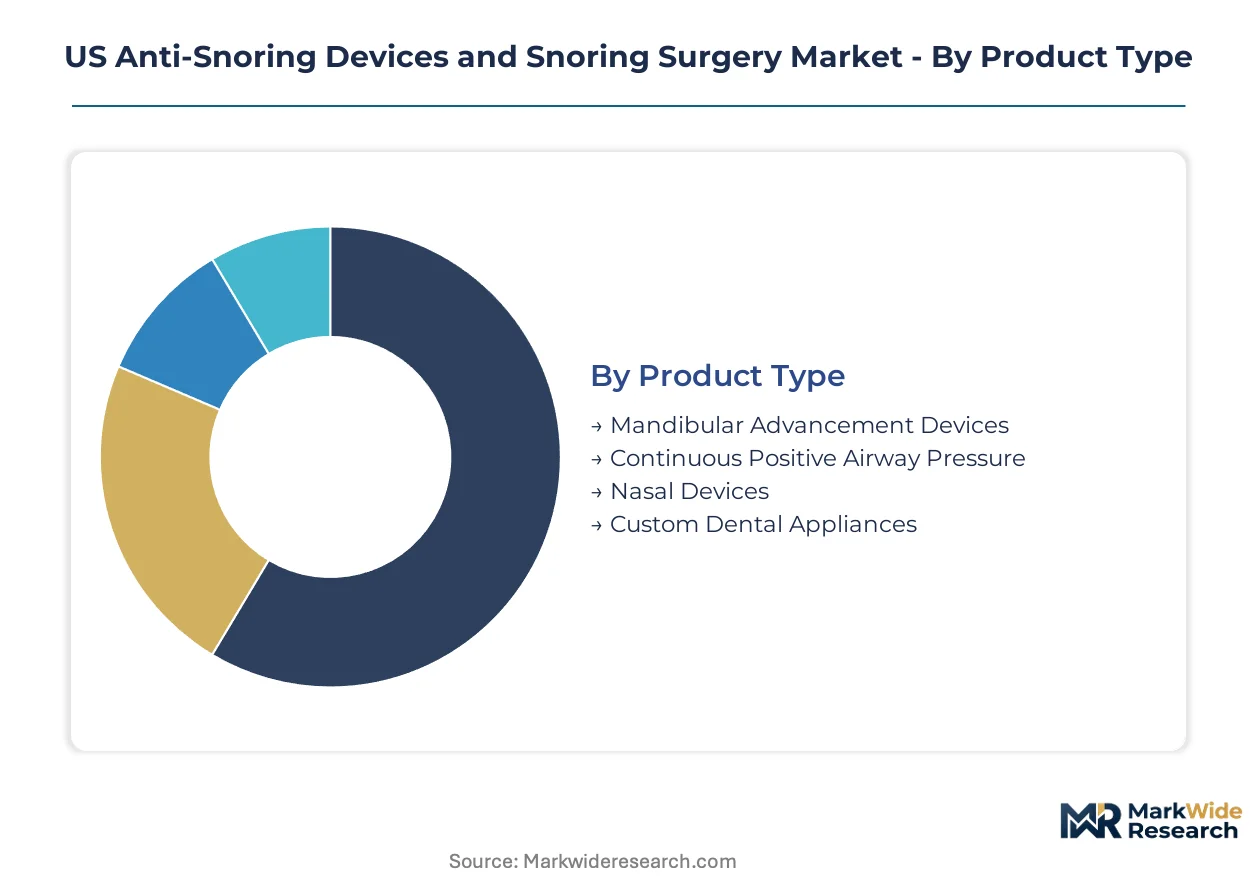
Segmentation in the US anti-snoring market reveals distinct channel economics and clinical workflows. Product type determines whether patients access therapy through dental practices, sleep medicine specialists, or direct-to-consumer platforms. Technology and end-user dimensions further stratify reimbursement pathways and capital intensity requirements.
Product Type:
Standalone devices dominate outpatient and home-based deployment, while embedded systems require sleep-lab infrastructure or surgical facilities for activation.
- Mandibular Advancement Devices:Medical-grade thermoplastic polymers permit millimeter-calibrated jaw repositioning. California dental practices and Texas direct-to-consumer channels concentrate demand, driven by FDA 510(k) clearance streamlining that compresses product development timelines.
- Continuous Positive Airway Pressure:Integrated digital health platforms unify diagnostic, therapeutic, and adherence-monitoring functions into single-platform ecosystems. Sleep clinics in Florida and hospital systems across the Northeast anchor procurement, constrained by HIPAA cloud architecture mandates that elevate development costs for connected platforms.
- Nasal Devices:Commoditized dilators and strips occupy mature, price-sensitive tiers where material comfort and fit precision provide limited differentiation.
- Custom Dental Appliances:Bespoke oral appliances fabricated through dental impressions command premium positioning through personalized fit and adjustment protocols.
Mandibular advancement devices lead volumes today; custom dental appliances are gaining share fastest through teledentistry workflows.
Technology:
Cost tier stratification separates capital-intensive surgical systems from disposable or reusable outpatient modalities.
- Laser Therapy:Office-based soft palate stiffening reduces facility fees compared to hospital-based surgery. Sleep clinics in metropolitan corridors concentrate adoption, though board-certified provider shortages constrain rural access.
- Radiofrequency Ablation:Outpatient migration of soft palate procedures expands addressable volumes beyond traditional surgical settings. Texas and Florida demonstrate strongest velocity, correlating with elevated obesity prevalence and limited Medicaid sleep-medicine coverage.
- Surgical Procedures:Uvulopalatopharyngoplasty and maxillomandibular advancement serve refractory cases with higher reimbursement thresholds but concentrated provider capacity in major metropolitan corridors.
- Positional Therapy:Wearable devices and vibratory feedback systems target positional obstructive sleep apnea with lower capital requirements and direct-to-patient accessibility.
Radiofrequency ablation leads volumes today; laser therapy is climbing the fastest as office-based adoption accelerates.
End User:
Customer type determines procurement authority, with institutional purchasers favoring bundled diagnostic-therapeutic packages and individual consumers driving direct-access segments.
- Hospitals:Integrated health systems anchor surgical procedure volumes and CPAP dispensing through sleep medicine departments. California and Texas hospital networks concentrate capacity, constrained by polysomnography technologist shortages that limit diagnostic throughput.
- Sleep Clinics:Expanding diagnostic and treatment capacity for obstructive sleep apnea patients across the United States. Medicare Local Coverage Determinations for home sleep testing broaden patient funnels for downstream interventions.
- Home Care Settings:Direct-purchase nasal dilators and boil-and-bite mandibular devices from e-commerce platforms fragment diagnostic oversight. Texas and Florida demonstrate strongest direct-to-consumer velocity.
- Dental Practices:Specialized partnerships control fitting and adjustment workflows for oral appliances. State dental board regulations across California, New York, and Texas govern scope-of-practice boundaries, creating fragmented channel access.
Sleep clinics lead volumes today; dental practices are expanding most quickly through hygienist-assisted fitting protocol clarity.
Application:
Maturity stages separate established obstructive sleep apnea treatment pathways from emerging snoring-focused indications with lighter regulatory burdens.
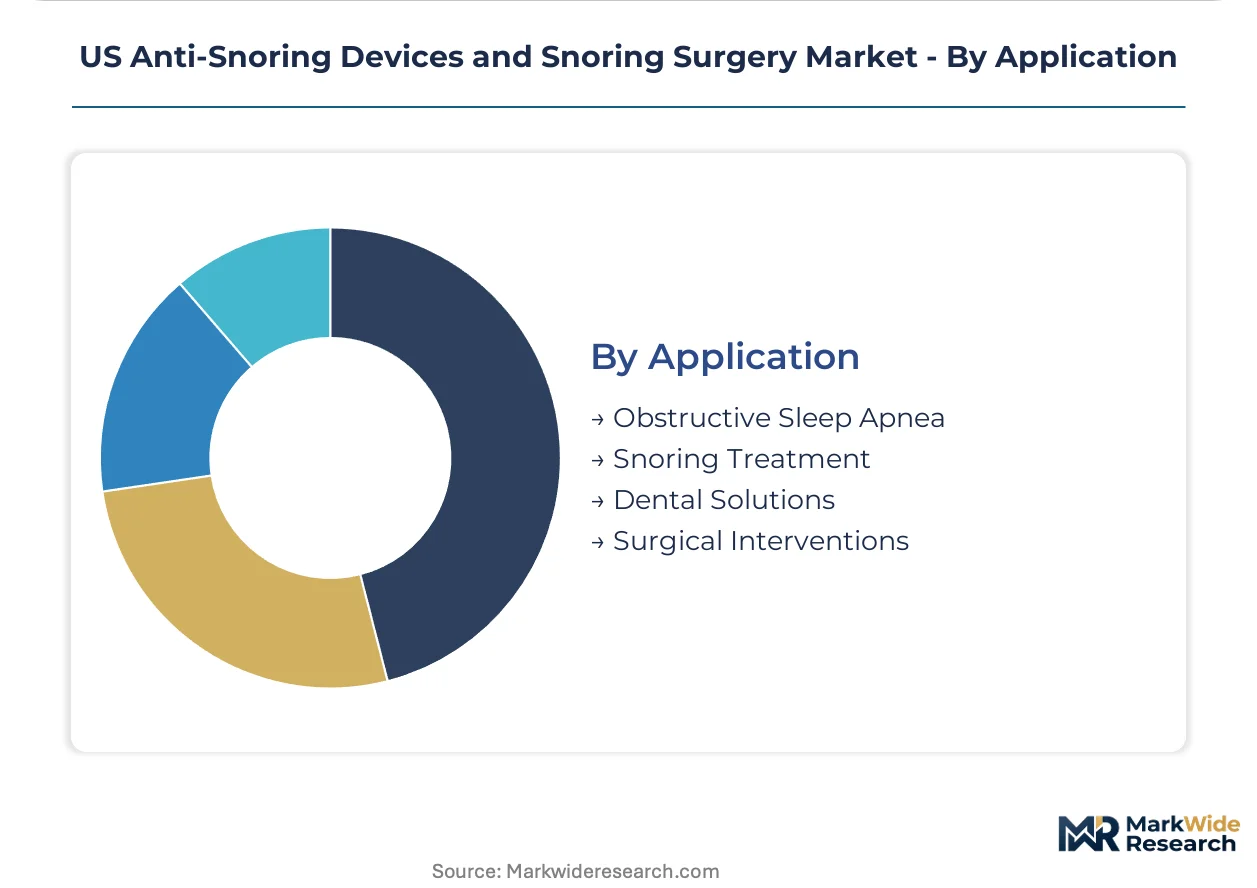
- Obstructive Sleep Apnea:Gold-standard diagnostic criteria and reimbursement codes anchor clinical workflows. CPAP retains primary position for moderate-to-severe cases, limiting oral appliance capture in severe-case segments.
- Snoring Treatment:Lighter regulatory pathways and direct-to-consumer accessibility expand addressable populations beyond diagnosed sleep apnea patients.
- Dental Solutions:Mandibular advancement and custom appliance therapy delivered through credentialed provider networks with state-specific scope regulations.
- Surgical Interventions:Refractory case management through board-certified otolaryngologists, with hypoglossal nerve stimulation systems accelerating through FDA breakthrough device designation pathways.
Obstructive sleep apnea leads volumes today; snoring treatment is gaining share fastest through direct-access channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sleep medicine infrastructure in the United States traces its commercial roots to Stanford University's sleep disorders clinic, established in 1970, which pioneered polysomnography standardization and spawned the diagnostic protocols now governing Medicare reimbursement across all fifty states.
California
Los Angeles and San Francisco Bay Area sleep clinics drive mandibular advancement device volumes through dense dental practice networks and elevated obesity prevalence in Central Valley agricultural communities. FDA 510(k) clearance streamlining accelerates product launches from Newport Beach medical device incubators. Stanford Medicine and UCLA Health anchor hypoglossal nerve stimulation surgical capacity, drawing patients from neighboring western states.
Texas
Houston and Dallas-Fort Worth metropolitan corridors concentrate board-certified otolaryngologists performing maxillomandibular advancement procedures, though rural counties face three-hour drive times to surgical facilities. State dental board scope-of-practice clarity on hygienist-assisted fitting protocols expands oral appliance penetration through general dentistry practices. Home sleep testing adoption rates exceed national averages, broadening downstream device funnels.
Florida
Miami and Tampa sleep medicine departments report the nation's highest direct-to-consumer nasal dilator and boil-and-bite mandibular device velocities, correlating with limited Medicaid sleep-medicine coverage and elevated retiree populations. Medicare Local Coverage Determinations for unattended polysomnography expand diagnostic access beyond traditional sleep lab infrastructure. Mayo Clinic Jacksonville anchors refractory case surgical referrals from throughout the Southeast.
New York
Manhattan and Long Island dental practices control premium custom appliance fitting workflows through credentialed provider networks, constrained by fragmented cross-state licensing reciprocity. State dental board regulations govern scope-of-practice boundaries for oral appliance therapy, creating channel access complexity for manufacturers. Columbia University Medical Center and NYU Langone anchor academic sleep medicine research with limited rural extension.
Illinois
Chicago metropolitan sleep clinics concentrate polysomnography technologist training programs, though statewide shortages persist in downstate counties. Northwestern Medicine and University of Chicago Medicine drive hypoglossal nerve stimulation adoption through FDA breakthrough device designation pathway participation. Rural patient access bottlenecks for surgical interventions exceed those of coastal states, amplifying demand for mail-fitted oral appliances.
US Anti-Snoring Devices and Snoring Surgery Market Key Industry Players
Premium-margin players sit above commodity-margin players across device customization and clinical support intensity, with bespoke mandibular advancement devices and integrated digital health platforms commanding reimbursement advantages over generic nasal dilators. The vendor base stratifies into three tiers: multinational respiratory conglomerates with sleep medicine portfolios, specialized dental-device manufacturers with credentialed provider networks, and direct-to-consumer brands bypassing clinical intermediaries. Dominant competitive moves include strategic partnerships with sleep clinic chains and dental service organizations, plus technology licensing for Bluetooth-enabled adherence monitoring.
Within the integrated-platform tier, ResMed Inc. exemplifies the recurring-revenue archetype through cloud-connected therapy ecosystems, while SomnoMed Ltd. occupies a specialized position anchored to dental practice partnerships. Among European-origin manufacturers, Fisher & Paykel Healthcare Corp. Ltd. and Koninklijke Philips NV represent scale-driven conglomerates with diversified respiratory portfolios spanning hospital and home care channels.
| Leading Market Players |
|---|
| ResMed Inc. |
| SomnoMed Ltd. |
| Fisher & Paykel Healthcare Corp. Ltd. |
| Koninklijke Philips NV |
| Airway Management, Inc. |
| Tomed Dr. Toussaint GmbH |
| ProSomnus Sleep Technologies |
| Apnea Sciences Corporation |
| Vivos Therapeutics, Inc. |
| Others |
Cost & Logistics Intelligence
Medicare Local Coverage Determination shifts toward home sleep testing are forcing manufacturers to unbundle diagnostic-therapeutic packages and absorb margin compression from disintermediated channel economics. This procurement preference reshapes supplier obligations toward direct-to-patient fulfillment infrastructure and teledentistry support systems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the US anti-snoring market by clinical support intensity and customization depth. FDA 510(k) clearance tier and dental practice partnership density drive price differentiation between prescription mandibular devices and direct-to-consumer boil-and-bite alternatives. Cost compression in the nasal dilator tier intensifies because material commoditization erodes brand premiums. Home care settings exhibit highest price sensitivity; hospital sleep medicine departments demonstrate lowest sensitivity due to bundled reimbursement protocols.
Supply Chain Analysis
FDA 510(k) clearance and ISO 13485 certification gating concentrate medical-grade thermoplastic polymer sourcing among US, Germany, and Switzerland-based specialty compounders. Mandibular advancement device production draws from copolyester resin, precision milling equipment, and dental impression logistics networks. Single-source vulnerability sits with medical-grade nylon variants used in millimeter-calibrated adjustment mechanisms. Distribution runs through credentialed dental service organizations and direct-to-consumer e-commerce platforms with divergent fulfillment specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US anti-snoring market reads as a late-cycle quality story as patient demand shifts toward Bluetooth-enabled adherence monitoring and cloud-based therapy optimization that commands premium positioning.
For Market Incumbents: Deepen vertical integration into medical-grade thermoplastic polymer compounding to defend margin position against resin price volatility. Fortify dental service organization partnerships to maintain channel control against direct-to-consumer disintermediation. Prioritize HIPAA-compliant cloud architecture investment as regulatory enforcement intensifies. For New Entrants and Emerging Players: Launch via teledentistry-enabled direct-to-patient channels to bypass incumbent-controlled sleep clinic networks. Target Texas and Florida rural counties where three-hour surgical facility drive times amplify demand for mail-fitted oral appliances. Pursue FDA 510(k) clearance streamlining for mandibular devices with embedded pressure sensors. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized dental-device manufacturers possessing credentialed provider networks and recurring software subscription revenue. Long-term viability centers on adherence-dependent monetization models rather than transactional hardware sales. Watch Medicare Local Coverage Determination revisions for oral appliance therapy as inflection indicator for patient funnel economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Streamlining | Accelerated premarket review compresses development timelines for mandibular advancement devices. |
| Dental Service Organization Partnership | Credentialed provider networks control fitting workflows and patient access channels. |
| Bluetooth-Enabled Adherence Platform | Cloud-connected therapy ecosystems shift revenue toward recurring software subscriptions. |
| Home Sleep Testing Integration | Unattended polysomnography expansion broadens diagnostic funnels for downstream interventions. |
| Teledentistry Workflow Deployment | Remote fitting protocols reduce in-person adjustment visits and capture rural patient volumes. |
Research Approach
Bottom-up dental practice and sleep clinic modeling reconciled against top-down thermoplastic polymer supply tracking forms the analytical core of this study. Primary interviews with otolaryngologists, dental sleep medicine specialists, GPO contracts managers, and biomedical engineers combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, and state dental board regulatory records. Triangulation between patient volume estimates and device shipment data ensures consistency across modeling approaches.
Historical trendline analysis of mandibular advancement device prescriptions, CPAP adherence rates, and surgical procedure volumes established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user channel, and application indication. CAGRs derived from regression analysis of Medicare Local Coverage Determination impacts and obesity prevalence trends. Forecast inputs incorporate home sleep testing adoption curves and state-level dental board scope-of-practice evolution.
Several conditions sit outside the modeled scope, including hypoglossal nerve stimulation reimbursement parity shifts and FDA breakthrough device designation pathway timeline acceleration. Forecasts reflect assumptions about HIPAA cloud architecture compliance costs and polysomnography technologist training program expansion. A model refresh is warranted upon material change in Medicare oral appliance therapy coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Massage Equipment Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Medication Management System Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Pelvic Muscle Probes Market