
 Kirschner Wires Market | 2026-2036
Kirschner Wires Market Size, Share, and Industry Trends Forecast 2026-2036
Kirschner Wires Market Outlook
Equipment leasing and pay-per-use instrument programs is fragmenting competitive tiers in the Kirschner wires space, allowing mid-scale providers to access advanced surgical sets without capital outlay. Stryker Corporation leverages its scale to bundle wire systems with power tools, locking in hospital contracts. Zimmer Biomet anchors its position through deep orthopedic portfolios that cross-sell fixation hardware. B. Braun Melsungen AG competes on sterile single-use configurations that reduce reprocessing liability for ambulatory centers.
Kirschner wires are smooth or threaded metallic pins, typically 0.6–3.0 mm in diameter, manufactured from stainless steel or titanium alloys through cold drawing and precision grinding, used to stabilize bone fragments during fracture reduction or guide drilling trajectories in orthopedic and trauma procedures. Stainless steel dominates volume due to cost efficiency and established supply chains, while titanium commands premium positioning in revision surgeries where biocompatibility and magnetic resonance imaging compatibility matter. Trauma surgery generates the fastest application growth as emergency department volumes expand and damage-control orthopedics standardizes temporary fixation protocols.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements govern market access, with notified bodies scrutinizing fatigue resistance and corrosion testing data more intensively than under prior directives. ISO 5832 standards for metallic implant materials establish baseline composition and mechanical property benchmarks that manufacturers must certify. Stakeholders should monitor how FDA's evolving substantial equivalence determinations and MDR's clinical evaluation requirements reshape compliance costs for new wire geometries and surface treatments.
Market Dynamics
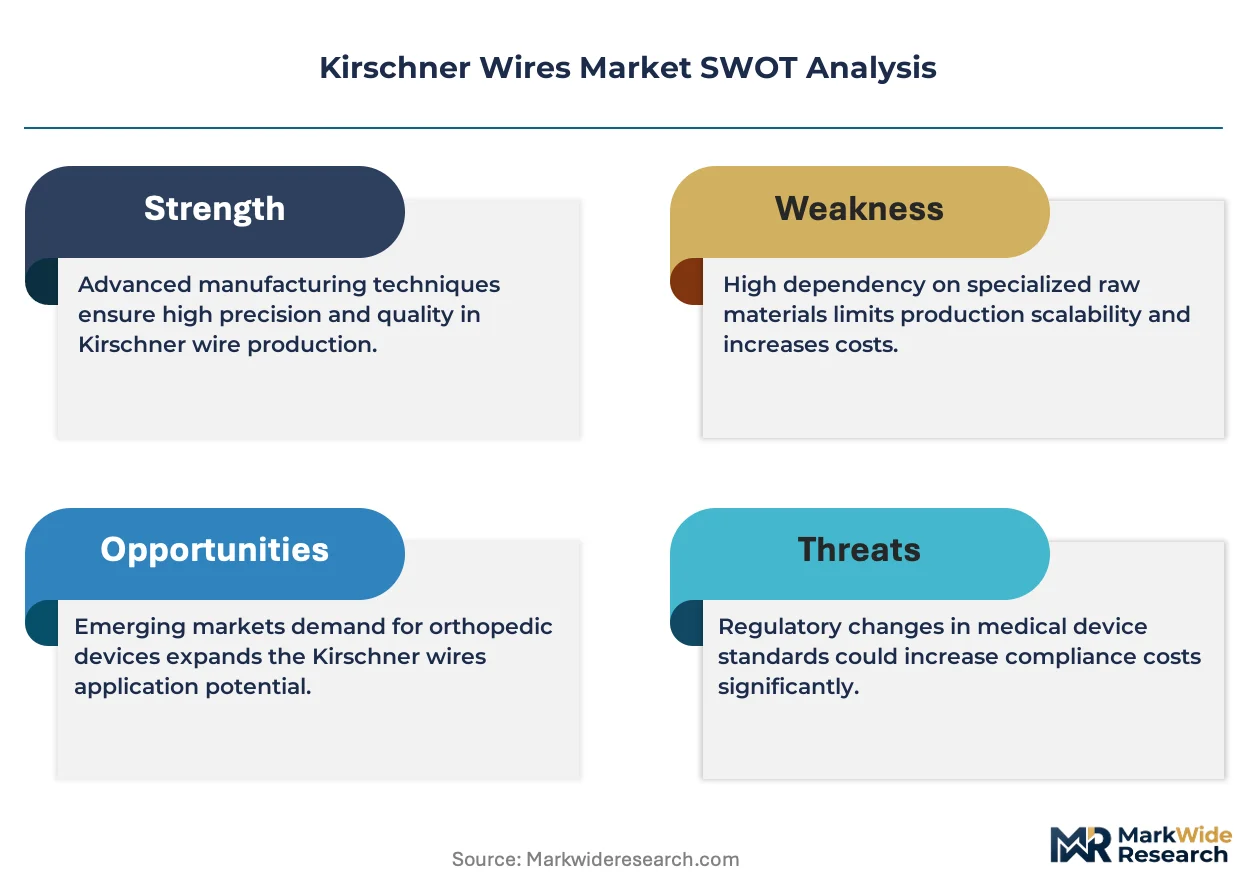
EU MDR technical documentation requirements are compressing product development timelines and forcing manufacturers to front-load clinical evaluation investments before market entry.
Growth Catalysts
- Emergency department volume expansion:Trauma centers in the United States are standardizing damage-control orthopedic protocols that rely on temporary Kirschner wire fixation for stabilizing polytrauma patients.
- FDA 510(k) pathway efficiency:Substantial equivalence determinations for stainless steel wire geometries allow faster clearance compared to novel implant categories, accelerating product refresh cycles.
- Titanium alloy biocompatibility:Revision surgery protocols increasingly specify MRI-compatible fixation hardware, pulling demand toward premium material specifications.
Market Restraints
- Raw material cost volatility:Nickel and chromium price swings in stainless steel supply chains compress margin buffers for standard wire product lines.
- Notified body capacity constraints:EU MDR transition bottlenecks delay conformity assessments for new wire surface treatments and extended fatigue testing protocols.
- External fixation substitute pressure:Ring fixators and modular external systems encroach on temporary stabilization applications traditionally served by percutaneous pinning.
Strategic Opportunities
- Ambulatory surgery center penetration:United States outpatient facilities seek sterile single-use wire configurations that eliminate reprocessing infrastructure investments.
- Surface modification convergence:Plasma electrolytic oxidation and antibiotic coating technologies are hybridizing to create infection-resistant wire surfaces for open fracture protocols.
- India trauma infrastructure buildout:Government hospital procurement programs under the Ayushman Bharat scheme create volume demand for cost-optimized stainless steel fixation sets.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity shortages, extending certification timelines for modified wire alloys.
- Legacy sterilization validation:Gamma irradiation dose mapping for novel packaging configurations requires extensive protocol revision under updated AAMI standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kirschner Wires Market |
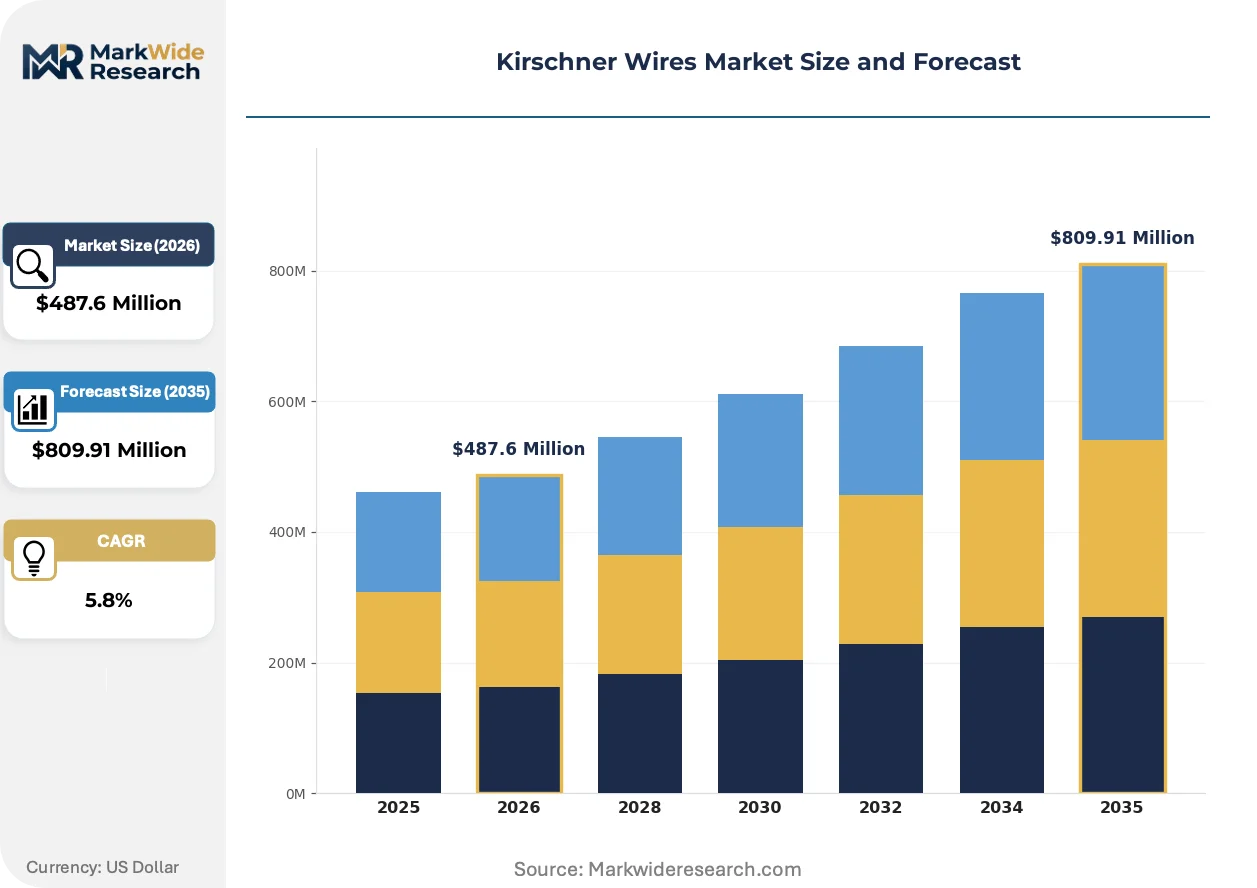
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Titanium, Nitinol, Other Alloys Application: Orthopedic Surgery, Neurosurgery, Trauma Surgery, Sports Medicine End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Others |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Arthrex Inc., DePuy Synthes, Orthofix Medical Inc., B. Braun Melsungen AG, Allegra Orthopaedics, Smith & Nephew, Globus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kirschner Wires Market Strategic Shifts
Material science advances and sterilization workflow redesigns are compressing the gap between commodity stainless steel pins and premium titanium systems. Regulatory convergence around fatigue testing protocols is forcing harmonization of quality systems across manufacturing footprints.
Shape-memory nickel-titanium alloys are hybridizing traditional Kirschner wire function with controlled retrieval capabilities. Pediatric orthopedic centers in Germany and Japan are piloting superelastic wire systems that enable less invasive extraction procedures. This convergence is compressing the addressable market for secondary removal surgeries while expanding premium positioning for temporary fixation hardware.
EU MDR Article 10 technical documentation requirements now mandate clinical evaluation reports for all wire diameter variants, not just novel materials. Manufacturers serving European trauma centers must maintain post-market surveillance systems that capture implant survival data. Small and mid-scale suppliers face disproportionate compliance cost burdens, accelerating consolidation of notified body relationships among scaled producers.
Hospital purchasing cooperatives in the United States are consolidating orthopedic hardware contracts into multi-year sole-source agreements. Independent ambulatory surgery centers respond by joining group purchasing organizations that aggregate volume across dozens of facilities. This channel concentration is most visible in Texas and Florida, where certificate-of-need deregulation has expanded the addressable site base for outpatient fracture care.
Kirschner Wires Market Segmentation
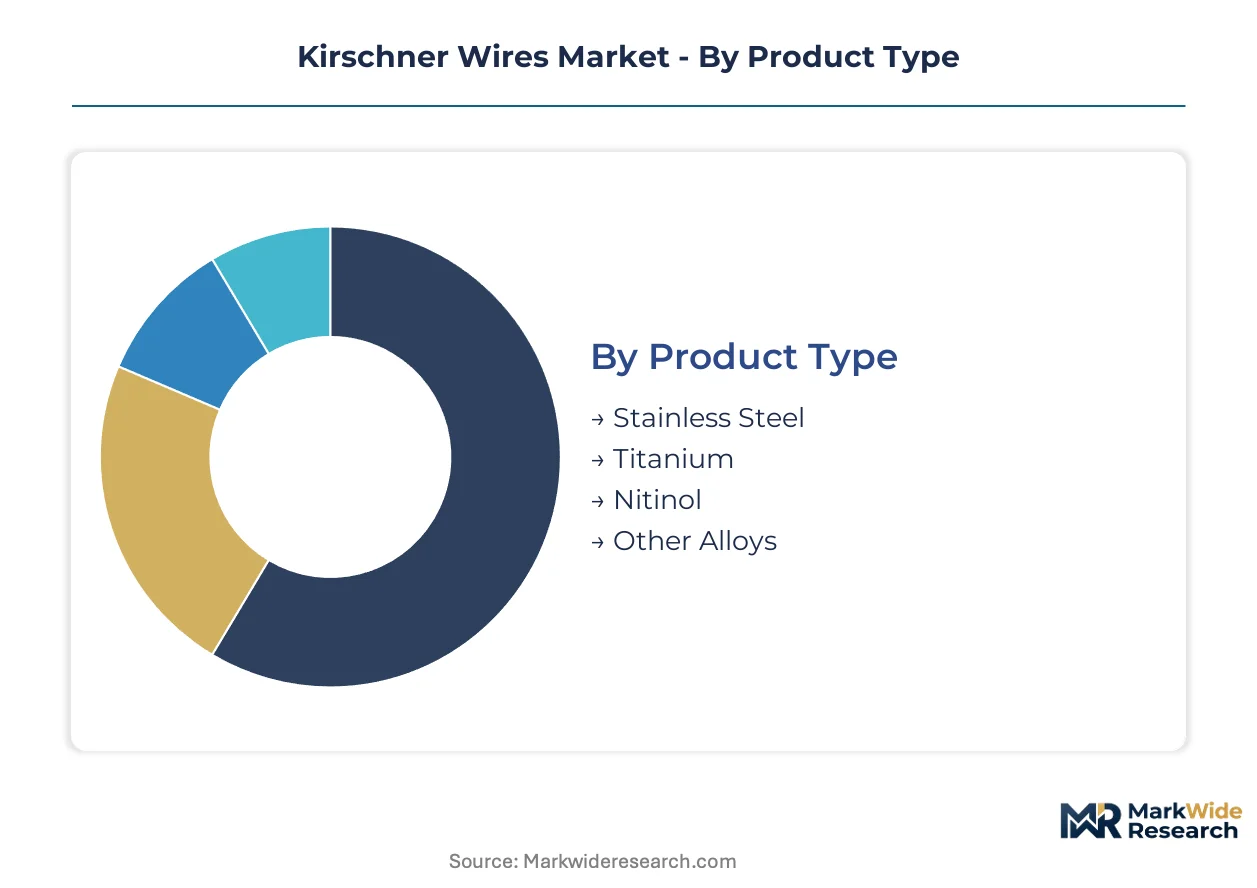
Segmentation in the Kirschner wires market reveals how material selection, surgical application, and care setting economics create distinct competitive arenas. Manufacturers configure product portfolios across these dimensions to capture volume in trauma centers while defending premium positions in revision surgery workflows.
Product Type:
Mature stainless steel configurations dominate hospital procurement budgets, while emerging alloy formulations target specialized extraction protocols and imaging compatibility requirements.
- Stainless Steel:Cold-drawn austenitic grades (316L, 316LVM) deliver tensile strength exceeding 500 MPa with established fatigue resistance profiles. United States trauma centers specify these wires for temporary fixation in polytrauma protocols where cost efficiency governs inventory decisions. Nickel and chromium supply volatility compresses margin buffers for commodity product lines.
- Titanium:Ti-6Al-4V ELI and commercially pure titanium variants offer magnetic resonance imaging compatibility and superior biocompatibility for revision surgeries. German and Japanese pediatric centers specify titanium for procedures requiring subsequent imaging surveillance. Premium positioning reflects raw material costs three to five times stainless steel equivalents.
- Nitinol:Nickel-titanium shape-memory alloys enable superelastic wire systems with controlled retrieval capabilities.
- Other Alloys:Cobalt-chromium and tantalum formulations serve niche indications requiring radiopacity or extreme corrosion resistance.
Stainless steel retains volume leadership across all geographies; titanium holds the steepest expansion curve as revision surgery protocols proliferate.
Application:
Volume concentrates in emergency stabilization procedures, while margin accumulates in specialized surgical disciplines requiring precision instrumentation sets.
- Trauma Surgery:Damage-control orthopedic protocols standardize percutaneous pinning for provisional fracture stabilization. United States emergency departments deploy Kirschner wires in open reduction workflows for distal radius and metacarpal injuries. Protocol standardization accelerates product refresh cycles.
- Orthopedic Surgery:Definitive fixation applications demand precise diameter tolerances and threaded configurations for fragment compression. Ambulatory surgery centers in Texas and Florida specify sterile single-use sets to eliminate reprocessing infrastructure. Bundled procurement contracts favor suppliers with comprehensive fixation portfolios.
- Neurosurgery:Cranial fixation and stereotactic guidance applications require submillimeter diameter precision.
- Sports Medicine:Arthroscopic-assisted pinning addresses athletic hand and wrist injuries in specialized clinic settings.
Trauma surgery commands absolute procedure volume; orthopedic surgery captures the highest per-procedure hardware value.
End User:
Capital intensity and sterilization infrastructure requirements stratify demand across inpatient and outpatient settings.
- Hospitals:Level I trauma centers maintain extensive wire inventories across diameter ranges for emergency operative suites. Reprocessing departments validate sterilization protocols under updated AAMI standards. FDA 510(k) clearance pathways enable rapid adoption of geometric variants.
- Ambulatory Surgical Centers:Certificate-of-need deregulation in Florida and Texas expands the addressable site base for outpatient fracture care. Single-use sterile configurations eliminate capital investment in autoclave infrastructure. Group purchasing organizations aggregate volume across dozens of facilities.
- Specialty Clinics:Hand surgery and sports medicine practices concentrate demand for precision diameter sets.
- Rehabilitation Centers:Post-operative monitoring and hardware removal scheduling create secondary demand touchpoints.
Hospitals retain volume leadership through emergency department capture; ambulatory surgical centers are expanding most quickly as outpatient migration accelerates.
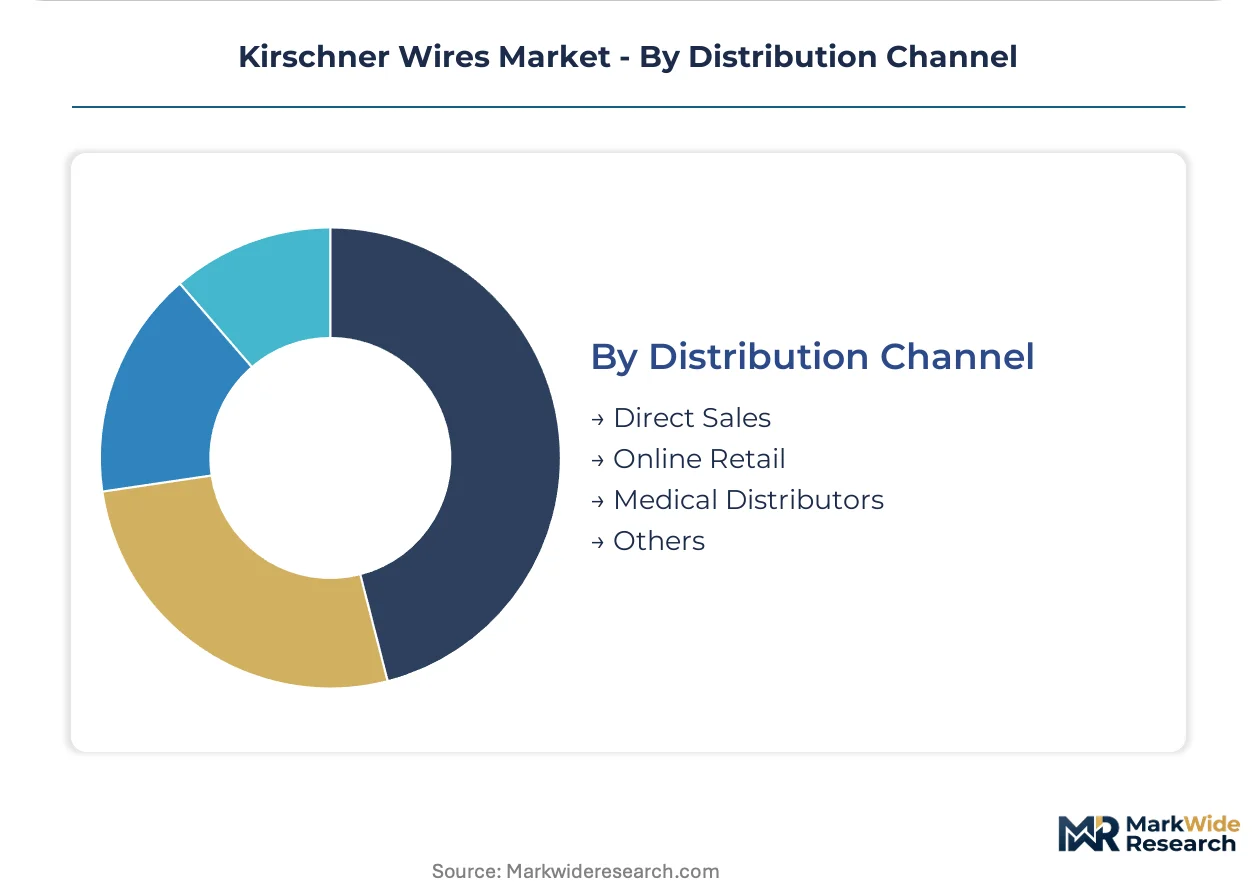
Distribution Channel:
Channel economics reflect contract consolidation trends and the shift toward inventory-light procurement models.
- Direct Sales:Orthopedic power tool bundling and multi-year sole-source agreements lock in hospital system commitments. Stryker Corporation and Zimmer Biomet field organizations maintain dedicated trauma hardware specialists. Contract renewal cycles concentrate in United States purchasing cooperatives.
- Medical Distributors:Independent ambulatory surgery centers rely on regional distributors for fragmented SKU fulfillment. B. Braun Melsungen AG leverages sterile single-use configurations through distributor networks serving certificate-of-need deregulated states. Inventory carrying costs shift to distributor balance sheets.
- Online Retail:Veterinary and research applications access standard wire geometries through specialized medical supply platforms.
- Others:Equipment leasing programs and pay-per-use instrument arrangements fragment competitive tiers.
Direct sales retains volume leadership through integrated system contracts; medical distributors are gaining share fastest in the ambulatory expansion corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in Kirschner wires track orthopedic device manufacturing clusters, with finished wire sets moving from European and North American fabrication centers toward trauma infrastructure buildouts in Asia-Pacific and Latin American markets.
United States
Certificate-of-need deregulation in Texas and Florida expands ambulatory surgery center capacity for outpatient fracture care. FDA 510(k) clearance pathways enable rapid geometric variant adoption by trauma hardware suppliers. The Dallas-Fort Worth metro anchors distributor networks serving certificate-of-need deregulated states with sterile single-use configurations.
Germany
Pediatric orthopedic centers in Bavaria pilot superelastic Nitinol wire systems for less invasive extraction procedures. EU MDR Article 10 technical documentation requirements mandate clinical evaluation reports for all wire diameter variants. The Stuttgart industrial corridor concentrates precision grinding capacity for submillimeter diameter neurosurgical wire specifications.
Japan
Aging demographics drive revision surgery volumes requiring MRI-compatible titanium fixation hardware. PMDA marketing authorization pathways align with ISO 5832 metallic implant material standards. The Osaka-Kobe manufacturing belt hosts cold-drawing facilities supplying austenitic stainless steel wire to domestic trauma centers.
India
Government hospital procurement programs under Ayushman Bharat create volume demand for cost-optimized stainless steel fixation sets. CDSCO medical device registration requirements govern import substitution strategies for trauma hardware. The Maharashtra-Gujarat industrial corridor scales domestic wire drawing capacity to serve government tender programs.
Brazil
Public health system trauma infrastructure investments expand emergency department operative capacity for damage-control orthopedic protocols. ANVISA medical device registration pathways require fatigue resistance testing documentation for imported wire sets. The São Paulo metropolitan concentration anchors distributor networks serving southeastern state hospital systems.
Kirschner Wires Market Competitive Environment
On the supply side, the industry is consolidating around multi-product orthopedic portfolios that bundle fixation hardware with power tools and instrument sets. Tiered competitive positioning separates scale-driven system suppliers from specialized wire fabricators and regional sterile-configuration providers. Dominant competitive moves include multi-year sole-source hospital contracts and equipment leasing programs that fragment capital barriers for mid-scale ambulatory entrants.
Among diversified orthopedic system suppliers, Stryker Corporation and Zimmer Biomet occupy positions anchoring integrated trauma hardware portfolios, while B. Braun Melsungen AG exemplifies the sterile single-use configuration archetype targeting ambulatory surgery center expansion corridors. These three entities represent distinct strategic postures: bundled system lock-in, comprehensive fixation portfolio cross-sell, and reprocessing liability elimination for outpatient facilities.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Arthrex Inc. |
| DePuy Synthes |
| Orthofix Medical Inc. |
| B. Braun Melsungen AG |
| Allegra Orthopaedics |
| Smith & Nephew |
| Globus Medical |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese cold-drawing facilities for austenitic stainless steel wire is compressing spot pricing for standard-diameter Kirschner wire configurations while simultaneously pressuring European and North American producers to shift toward titanium alloy premium tiers or exit commodity segments entirely. This utilization imbalance rewards suppliers with backward-integrated nickel sourcing and punishes merchant buyers exposed to London Metal Exchange volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in quarterly price adjustments tied to nickel and chromium indices. Price differentiation rests on ISO 5832 certification tier and MRI compatibility grade, with Ti-6Al-4V ELI variants commanding substantial premiums over 316LVM stainless steel. Cost compression in standard wire tiers is intensifying because Indian government tender programs under Ayushman Bharat are absorbing surplus Chinese capacity at distressed export pricing. Ambulatory surgery centers exhibit acute price sensitivity due to group purchasing organization aggregation, while Level I trauma centers prioritize supply security over unit cost.
Supply Chain Analysis
Upstream nickel and titanium sponge feedstock draws from Indonesian laterite mines, Chinese smelter complexes, and Japanese sponge producers in the Osaka-Kobe belt. Cold-drawing capacity concentrates in Germany's Stuttgart corridor, China's Jiangsu province, and India's Maharashtra-Gujarat industrial zone. Single-source vulnerability runs through Indonesian nickel processing dominance following export ban policy shifts. Distribution runs through orthopedic power tool bundling by Stryker and Zimmer Biomet field organizations, with regional medical distributors serving fragmented ambulatory surgery center demand in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against ring fixators and modular external fixation systems that are encroaching on temporary stabilization applications. Incumbents must navigate this threat while managing raw material cost volatility and regulatory compliance burdens.
For Market Incumbents: Insulate trauma hardware portfolios by deepening sterile single-use configuration capabilities for ambulatory surgery center expansion corridors in Texas and Florida. Lock in multi-year sole-source agreements with hospital purchasing cooperatives before EU MDR clinical evaluation requirements fully compress product refresh timelines. Prioritize backward integration into titanium sponge sourcing to defend margin position against nickel price swings. For New Entrants and Emerging Players: Establish a beachhead in India's Ayushman Bharat government tender programs by configuring cost-optimized 316L stainless steel wire sets for public hospital trauma infrastructure buildout. Target the Maharashtra-Gujarat procurement corridor where domestic cold-drawing capacity is scaling to serve import substitution strategies. Deploy distributor-centric go-to-market models that shift inventory carrying costs away from capital-constrained entrants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU MDR compliance infrastructure as clinical evaluation report mandates and post-market surveillance systems become table stakes for European market access. Acquisition targets should exhibit established notified body relationships and validated gamma irradiation sterilization protocols. Monitor CDSCO registration acceleration in India as an inflection signal for emerging market volume capture.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Clinical evaluation reports for all wire diameter variants secure notified body capacity ahead of competitor bottlenecks. |
| Sterile Single-Use Configuration Expansion | Eliminates ambulatory surgery center reprocessing liability while capturing Florida and Texas outpatient migration. |
| Titanium Alloy Portfolio Deepening | MRI-compatible hardware addresses Japanese and German revision surgery protocols with premium positioning. |
| Indian Domestic Manufacturing Scale-Up | Maharashtra-Gujarat cold-drawing capacity serves Ayushman Bharat tender programs with import substitution economics. |
| Plasma Electrolytic Oxidation R&D Partnership | Antibiotic coating hybridization targets open fracture infection resistance in damage-control orthopedic protocols. |
Study Parameters
Cross-validation between orthopedic device procurement databases and regulatory filing archives anchors the qualitative findings in observable contract and clearance patterns. Primary interviews with trauma surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers were synthesized with secondary validation from FDA 510(k) databases, EU MDR notified body documentation, CDSCO registration records, and customs trade flows for stainless steel and titanium wire. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation were reconciled across the analysis window.
Calibration against historical CAGR trajectories in orthopedic fixation hardware informed the projection framework across material type, surgical application, end-user setting, and distribution channel dimensions. Modeled inputs include emergency department volume expansion rates, ambulatory surgery center certificate-of-need deregulation patterns, and raw material index movements. Growth rates were derived from elasticity-adjusted demand curves and supply-side capacity utilization signals rather than extrapolated trend lines.
Stress conditions across nickel price volatility bands, notified body capacity constraints, and external fixation substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU MDR transition timelines and Indian government procurement acceleration. Cross-checking against hospital capital expenditure surveys and orthopedic power tool shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Mobility Aids Market
Medical Devices
Heart Defect Closure Devices Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Carotid Stents Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Smart Mask Market