
 Healthcare Data Annotation Tools Market | 2026-2036
Healthcare Data Annotation Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Data Annotation Tools Market Analytics
Cloud-based API distribution is reshaping how healthcare AI developers access annotation infrastructure. Scale AI leverages its federal contracting footprint to sustain high-assurance labeling pipelines for diagnostic imaging. Labelbox competes through workflow customization that anchors enterprise accounts across research institutions. Innodata specializes in clinical text normalization, occupying a defensible position in pharmaceutical regulatory submissions.
Healthcare data annotation tools are software platforms that apply structured labels to medical datasets—encompassing DICOM image coordinates, SNOMED CT coding for clinical text, temporal segmentation for video procedures, and phonemic tagging for audio diagnostics—to train supervised machine learning models for diagnostic and research applications. Image annotation leads product type adoption as radiology AI training consumes the majority of platform capacity, while text annotation grows fastest from NLP-driven extraction demands in electronic health records. Medical imaging commands the largest application margin pool due to reimbursement-linked diagnostic AI validation requirements, whereas clinical trials annotation exhibits the steepest growth trajectory from decentralized trial expansion.
FDA 21 CFR Part 11 imposes electronic record integrity standards that directly shape platform audit trail architectures, while HIPAA mandates de-identification protocols before any cloud-based annotation processing. ISO 13485 quality management requirements for medical device software increasingly extend to annotation tools bundled with diagnostic AI training pipelines. Stakeholders must monitor how EMA's evolving AI Act implementation timelines will synchronize with FDA software-as-medical-device guidance to determine dual-market platform certification strategies.
Market Dynamics
Cloud-native API architectures are compressing deployment timelines for healthcare AI training pipelines, forcing annotation platforms to embed compliance tooling directly into data ingestion workflows rather than bolt it on post-hoc.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic record integrity mandates from the US regulator are compelling platform vendors to build audit-native architectures that pharmaceutical sponsors now require for clinical data submissions.
- Decentralized trial expansion:Remote patient monitoring and virtual site operations are fragmenting data capture across home settings, multiplying annotation touchpoints for eCOA and wearable-derived endpoints.
- Radiology AI reimbursement:Diagnostic algorithm validation requirements tied to CMS coding decisions are sustaining platform capacity allocation toward DICOM labeling workflows.
Market Restraints
- HIPAA de-identification overhead:Safe harbor method implementation consumes 15-25% of project timelines before any labeling begins, compressing vendor margins on fixed-price contracts.
- Specialized annotator scarcity:Clinical domain expertise—radiology board certification, pathology fellowship training—concentrates supply in Boston, Basel, and Singapore, creating geographic chokepoints.
- ISO 13485 extension uncertainty:Medical device quality management standards are migrating downstream to annotation tools bundled with diagnostic AI, but certification timelines remain undefined by notified bodies.
Strategic Opportunities
- EMA AI Act synchronization:The European regulator's implementation timeline for high-risk AI system conformity assessment will create dual-certification demand from vendors serving transatlantic pharmaceutical clients.
- Clinical text normalization:SNOMED CT and ICD-10 coding automation for real-world evidence extraction represents underpenetrated whitespace beyond imaging-centric incumbent positioning.
- Edge deployment APIs:On-premise annotation instances for sensitive genomic datasets are opening channel innovation for vendors with air-gapped infrastructure capabilities.
Industry Challenges
- Inter-annotator variance control:Gold standard adjudication workflows for oncology lesion measurement require triple-pathologist review, inflating per-case costs beyond budgeted assumptions.
- Legacy EHR integration:HL7 FHIR connectivity gaps with decade-old hospital information systems are forcing custom middleware development that delays platform onboarding.
- Continuous learning deployment:Model drift detection and re-annotation triggering mechanisms remain immature, leaving performance degradation unflagged between validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Data Annotation Tools Market |
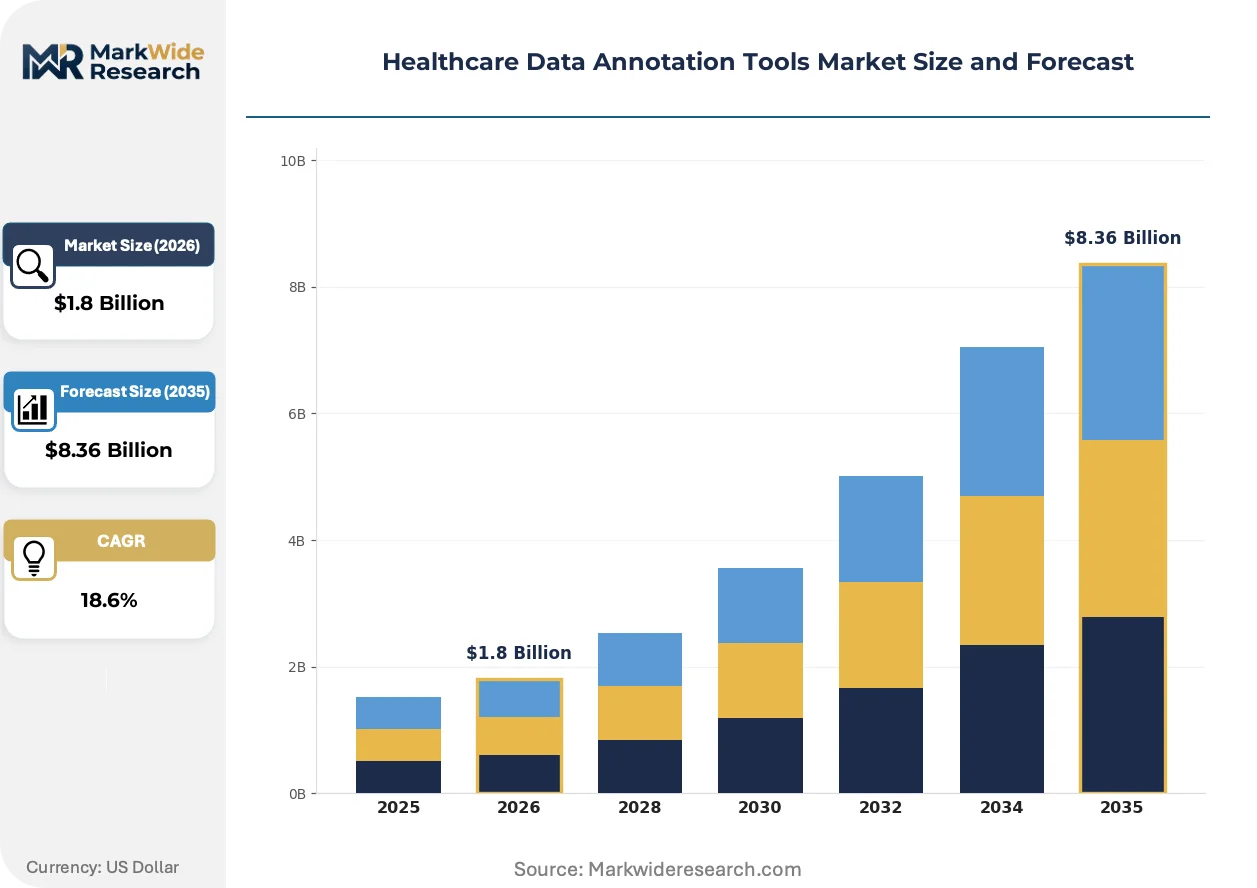
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Image Annotation, Video Annotation, Text Annotation, Audio Annotation Application: Clinical Trials, Medical Imaging, Patient Records, Research Studies End User: Hospitals, Research Institutions, Biotech Companies, Pharmaceutical Firms Technology: Machine Learning, Natural Language Processing, Computer Vision, Crowdsourcing |
| Companies Covered | Infosys BPM, iMerit Technology, Appen Limited, Scale AI, Labelbox, Shaip, Innodata, SuperAnnotate LLC, CloudFactory Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Data Annotation Tools Market Evolving Landscape
Active learning loops and federated annotation architectures are redistributing where labeling work happens and who performs it, collapsing the traditional centralized BPO model.
Multimodal foundation models are hybridizing text, image, and waveform inputs into unified embedding spaces. Radiology departments at academic medical centers are piloting these architectures for cross-modal retrieval, compressing the volume of manual bounding box annotation required for rare disease detection studies. The structural consequence is platform vendors racing to expose model-assisted pre-labeling APIs that accelerate rather than replace human reviewer throughput.
EMA's AI Act implementation guidance is mandating conformity assessment procedures for clinical decision support training data provenance. Pharmaceutical sponsors operating European trial networks must now document annotation workforce qualifications and inter-annotator agreement thresholds in technical files. Diagnostic imaging platform vendors are responding by embedding workforce analytics dashboards that generate audit-ready evidence packages for notified body review.
Hospital procurement committees are unbundling annotation services from end-to-end AI development contracts, creating direct vendor relationships that bypass systems integrator markups. Research institutions in Germany and the Netherlands are piloting this model for pathology whole-slide image projects, establishing volume-based pricing with specialist labeling firms. The shift is most visible in academic medical centers with established digital pathology programs and dedicated informatics budgeting authority.
Healthcare Data Annotation Tools Market Segmentation
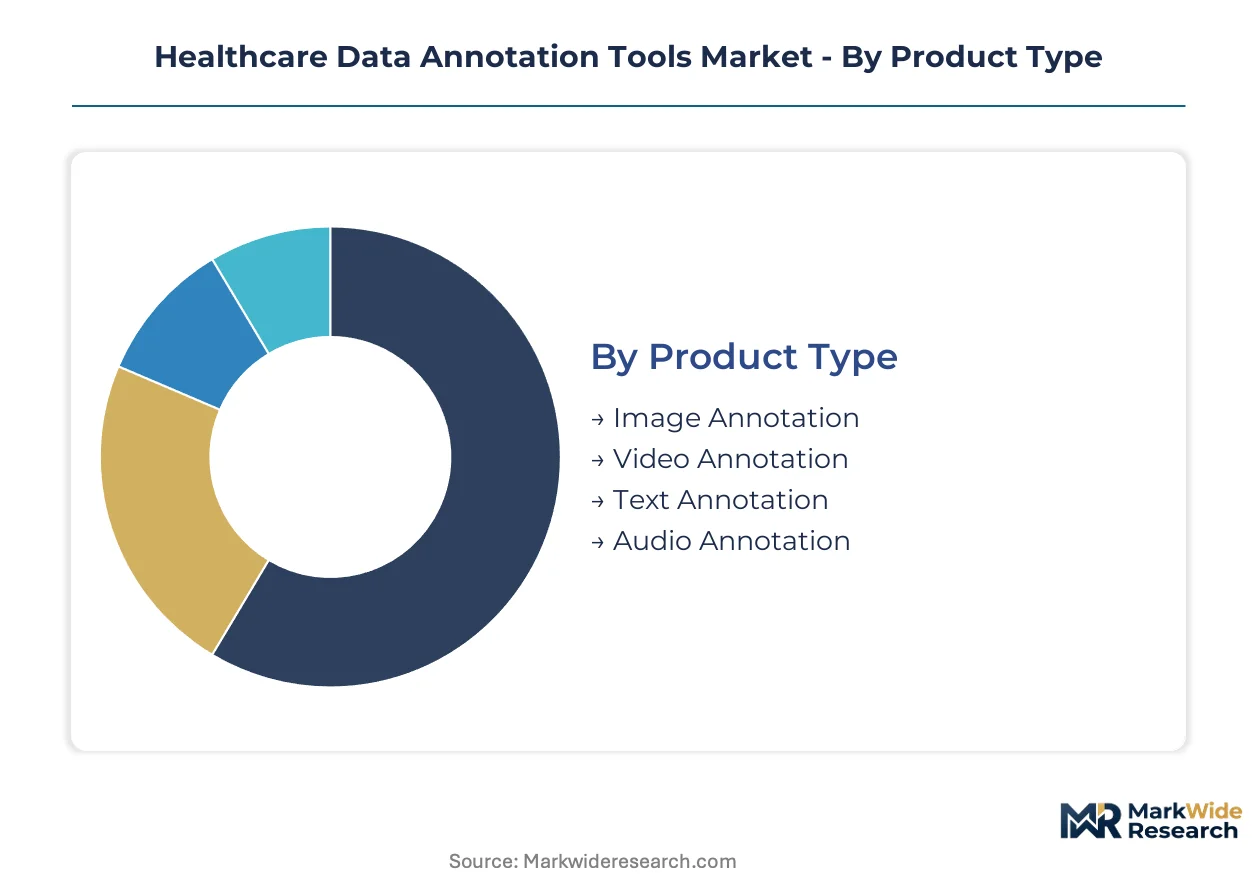
Healthcare data annotation tools fragment across four intersecting dimensions that determine pricing power and deployment complexity. Product type governs technical infrastructure requirements, while application context dictates regulatory stringency. End-user sophistication and technology modality further stratify vendor positioning across contract structures.
Product Type:
Use-case spectrum spans static medical imagery through continuous physiological waveforms, with each modality imposing distinct latency and precision requirements on platform architectures.
- Image Annotation:DICOM-compatible bounding box, segmentation mask, and landmark placement tools for radiology and pathology workflows. Demand concentrates in academic medical centers across Germany and the United States, where CMS reimbursement validation for diagnostic AI sustains high-throughput labeling contracts.
- Text Annotation:SNOMED CT and ICD-10 coding automation, entity extraction, and relation classification for clinical narratives. Pharmaceutical sponsors in Basel and Boston drive adoption for regulatory submission documentation, with HIPAA de-identification protocols consuming substantial preprocessing overhead.
- Video Annotation:Temporal segmentation and procedural phase labeling for surgical training datasets and endoscopy AI development.
- Audio Annotation:Phonemic tagging and respiratory pattern classification for diagnostic phonocardiography and sleep study analysis.
The dominant share belongs to Image Annotation, while Text Annotation is closing the gap fastest.
Application:
Cost tier segmentation separates reimbursable diagnostic validation from exploratory research budgets, with compliance overhead scaling proportionally.
- Medical Imaging:Radiology and pathology AI training pipelines requiring FDA 21 CFR Part 11 audit trails and inter-annotator agreement documentation. Reimbursement-linked validation protocols in the United States sustain premium pricing for this segment.
- Clinical Trials:eCOA endpoint labeling, adverse event extraction, and decentralized trial data harmonization. EMA-aligned networks in Germany and the Netherlands are expanding fastest as virtual site operations fragment data capture.
- Patient Records:Real-world evidence extraction from EHR archives for outcomes research and population health modeling.
- Research Studies:Exploratory annotation for rare disease biomarker discovery and genomic-phenotypic correlation studies.
Medical Imaging commands the largest margin pool, though Clinical Trials exhibits the steepest expansion trajectory from decentralized trial mandates.
End User:
Customer type determines procurement authority and contract duration, with pharmaceutical sponsors consolidating vendor relationships across therapeutic programs.
- Pharmaceutical Firms:Enterprise-scale annotation operations spanning imaging, text, and multimodal datasets for regulatory submissions. FDA and EMA dual-certification requirements are compressing vendor shortlists to platforms with validated quality management systems.
- Research Institutions:Academic medical centers with dedicated informatics budgeting authority piloting unbundled annotation procurement for pathology and radiology projects.
- Hospitals:Health system procurement committees integrating annotation tools into broader AI development partnerships.
- Biotech Companies:Venture-funded developers prioritizing speed-to-validation over compliance documentation depth.
Pharmaceutical Firms anchor volume commitment, while Research Institutions are gaining procurement autonomy fastest through dedicated informatics budget lines.
Technology:
Maturity segmentation distinguishes production-deployed modalities from emerging architectures still navigating validation protocols.
- Computer Vision:Convolutional and transformer-based architectures for medical image analysis, now standard in radiology AI pipelines with established FDA software-as-medical-device precedents.
- Natural Language Processing:Clinical text normalization and extraction systems, expanding fastest as real-world evidence requirements penetrate pharmaceutical regulatory strategy.
- Machine Learning:Active learning loops and model-assisted pre-labeling APIs that accelerate human reviewer throughput.
- Crowdsourcing:Distributed workforce models for low-sensitivity annotation tasks, constrained by HIPAA and GDPR data residency requirements.
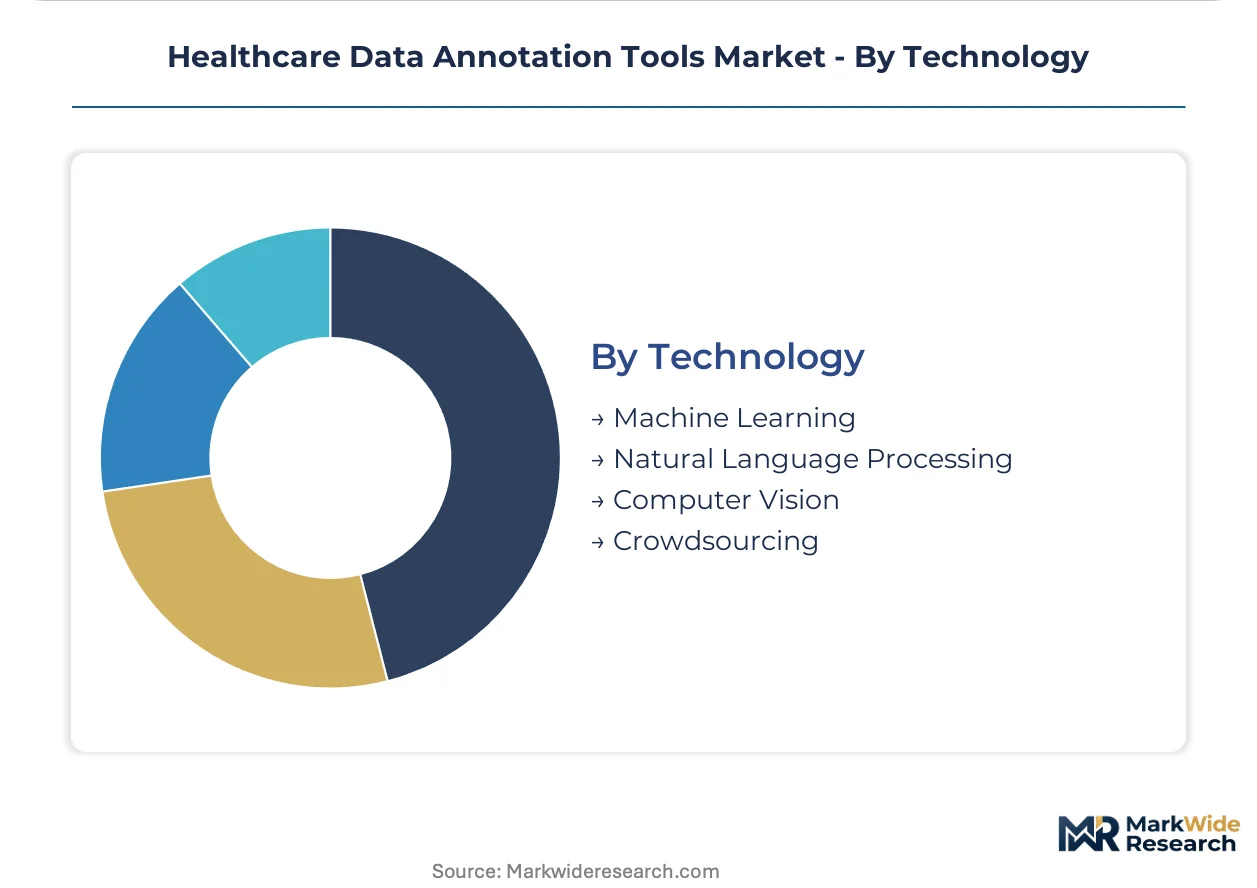
Computer Vision retains deployment dominance, though Natural Language Processing is gaining share fastest from regulatory documentation automation demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany while contract margins compress in India-based service delivery. Pharmaceutical sponsors in Basel and Boston command audit-native platform architectures that sustain 40-60% premiums over standard labeling contracts. Geographic chokepoints around clinical domain expertise—radiology board certification, pathology fellowship training—restrict supply elasticity in these premium markets.
United States
FDA 21 CFR Part 11 mandates and CMS reimbursement-linked diagnostic AI validation sustain premium platform pricing. HIPAA safe harbor de-identification consumes 15-25% of project timelines before labeling begins. The Greater Boston corridor anchors radiology AI training pipeline demand, with academic medical centers unbundling annotation procurement from systems integrator contracts.
Germany
EMA-aligned clinical trial networks require validated annotation workflows for regulatory submissions. The EU AI Act implementation timeline is mandating conformity assessment procedures for training data provenance documentation. The Rhine-Main cluster around Frankfurt and the Munich biotech corridor concentrate pharmaceutical sponsor procurement authority for dual-certification platform selection.
United Kingdom
NHS AI Lab validation frameworks and MHRA software-as-medical-device guidance shape procurement specifications for diagnostic imaging platforms. GDPR data residency requirements constrain cloud-native API deployment for genomic datasets. London's academic medical centers and the Cambridge life sciences cluster pilot unbundled annotation contracting for pathology whole-slide image projects.
India
CDSCO regulatory convergence with ICH-GCP standards is elevating compliance documentation requirements for contract research organizations. Cost arbitrage in clinical text normalization and low-sensitivity image labeling sustains offshore delivery center expansion. Hyderabad and Bengaluru concentrate HIPAA-trained workforce pools for pharmaceutical sponsor back-office annotation operations.
Switzerland
Swissmedic quality management requirements and proximity to Basel-headquartered pharmaceutical giants sustain high-assurance labeling contract premiums. ISO 13485 medical device software standards extend downstream to annotation tools bundled with diagnostic AI training pipelines. The Basel-Zurich corridor anchors specialized annotator supply for oncology lesion measurement and rare disease biomarker discovery studies.
Healthcare Data Annotation Tools Market Competitive Landscape
Federal contractors and workflow customization specialists split the market between high-assurance defense-adjacent pipelines and flexible enterprise research deployments. Consolidation pressure concentrates among pharmaceutical sponsors demanding dual FDA-EMA certification, compressing vendor shortlists to platforms with validated quality management systems. Three archetypes dominate: scale-driven API infrastructure providers, compliance-specialized clinical text normalizers, and modular workflow configurators. Competitive moves center on embedding audit-native architectures into data ingestion workflows and unbundling annotation services from end-to-end AI development contracts.
Within the federal contracting tier, Scale AI exemplifies high-assurance labeling pipeline positioning. Among workflow customization providers, Labelbox occupies the enterprise research institution segment. On the clinical text normalization vector, Innodata anchors pharmaceutical regulatory submission specialization. These three represent distinct strategic postures rather than direct substitutes, with procurement committees selecting across archetypes based on project-specific compliance depth and modality requirements.
| Leading Market Players |
|---|
| Infosys BPM |
| iMerit Technology |
| Appen Limited |
| Scale AI |
| Labelbox |
| Shaip |
| Innodata |
| SuperAnnotate LLC |
| CloudFactory Limited |
| Others |
Value Network & Pricing Analysis
Hyderabad and Bengaluru concentrate HIPAA-trained workforce pools that feed pharmaceutical sponsor back-office operations, with capacity scaling in these hubs directly compressing margins on standardized clinical text normalization contracts while sustaining premiums for FDA-validated audit-native architectures.
Pricing Analysis
The customization-premium spread separates configured-to-order audit-native platforms from standard labeling services. Subscription-tiered SaaS pricing dominates, with differentiation anchored in FDA 21 CFR Part 11 certification grade and geographic delivery cost. Cost compression in offshore text annotation intensifies as Indian delivery centers expand, while pharmaceutical sponsors in Basel and Boston show lowest price sensitivity for dual-certification platforms.
Supply Chain Analysis
Export-control regimes around AI training infrastructure constrain hardware flows to annotation platform operators, with licensing requirements affecting GPU cluster deployments. Supply concentrates in the United States, Germany, and India. Raw material dependencies span cloud compute credits, specialized DICOM storage arrays, and clinical domain expert labor pools. Single-source vulnerability in radiologist board-certified annotators creates chokepoint risk. Distribution runs through direct enterprise contracts and cloud-native API marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards scarce clinical domain expertise—radiology board certification, pathology fellowship training, and SNOMED CT coding proficiency—while penalizing undifferentiated labor arbitrage as automation encroaches on low-complexity tasks.
For Market Incumbents: Insulate high-assurance labeling pipelines by embedding workforce analytics dashboards that generate audit-ready evidence packages for notified body review. Deepen backward integration into clinical text normalization capabilities to offset margin erosion from imaging-centric competition. Certification investment in ISO 13485 quality management systems represents the priority defensive lever against emerging compliance-specialized entrants. For New Entrants and Emerging Players: Mid-market research institutions in the Netherlands and United Kingdom represent the most penetrable entry point for unbundled annotation procurement pilots. Clinical text normalization for real-world evidence extraction offers underpenetrated whitespace beyond imaging incumbent positioning. A direct channel strategy targeting academic medical centers with dedicated informatics budgeting authority bypasses systems integrator markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compliance-specialized clinical text normalizers over scale-driven API infrastructure providers. Long-term viability hinges on dual FDA-EMA certification capabilities as pharmaceutical sponsors consolidate vendor relationships. The signal to watch is EMA AI Act implementation guidance synchronizing with FDA software-as-medical-device timelines, which would accelerate conformity assessment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Audit-Native Architecture Development | FDA 21 CFR Part 11 compliance mandates reshape platform engineering priorities for pharmaceutical sponsors. |
| Clinical Text Normalization Expansion | SNOMED CT and ICD-10 automation penetrates real-world evidence extraction beyond imaging-centric positioning. |
| Dual-Certification Investment | EMA AI Act synchronization with FDA guidance creates transatlantic pharmaceutical procurement requirements. |
| Workforce Analytics Integration | Inter-annotator agreement dashboards generate notified body-ready evidence packages for diagnostic AI training. |
| Edge Deployment API Development | Air-gapped infrastructure capabilities open genomic dataset annotation channels for privacy-sensitive health systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical regulatory affairs leads, hospital procurement committee members, biomedical informatics directors, and contract research organization operations managers. Secondary validation drew from FDA 510(k) filings, EMA scientific advice letters, ClinicalTrials.gov protocol registries, and CMS Medicare reimbursement determinations. Bottom-up annotation platform deployment tallies were triangulated against top-down pharmaceutical R&D spending allocations.
Calibration against historical adoption curves in diagnostic AI and clinical trial digitization anchored the analytical framework. Segmentation dimensions spanned product type, application context, end-user sophistication, and technology modality across the projection horizon. CAGRs were derived from regression analysis of platform licensing growth and workforce scaling patterns. Industry-specific inputs included FDA software-as-medical-device approval trajectories and EMA AI Act implementation timelines.
Practitioners should monitor regulatory synchronization between FDA and EMA, HIPAA enforcement intensity, and radiologist annotator supply elasticity for early signals of forecast deviation. Material shifts in dual-certification requirements or cloud-native API security standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Medical Record Management System Market
Health Data Management
Clinical Data Management Systems (CDMS) Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Patient Data Management Systems Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
US Population Health Management Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Global Healthcare Data Storage Market