
 Medical Computer Carts Market | 2026-2036
Medical Computer Carts Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Computer Carts Market Outlook
Aftermarket service revenue is narrowing as original equipment manufacturers build captive maintenance networks. Ergotron, Inc. leverages its vertical integration into monitor arm production to control component costs across cart assemblies. Capsa Healthcare anchors its position through specialized distribution partnerships with group purchasing organizations serving acute care networks. Enovate Medical differentiates via R&D intensity in battery management systems for wireless cart deployments.
Medical computer carts are mobile or fixed workstation platforms engineered to transport computing hardware, displays, and peripheral devices within clinical environments, typically incorporating height-adjustable columns, antimicrobial surfaces, and casters rated for 300-pound dynamic loads to ensure stable operation during patient care. Their primary commercial purpose centers on enabling real-time electronic health record access, medication barcode verification, and telehealth consultations at the point of care. Mobile carts command the dominant share of product type revenue as hospitals prioritize flexibility in room turnover and emergency department workflows. Battery-powered technology segments are expanding fastest where facilities seek to eliminate cord hazards and support continuous clinical mobility across shift changes. Telemedicine application demand is accelerating as health systems deploy integrated video cart configurations for remote specialist consultations and rural care extension.
The FDA enforces 510(k) clearance pathways for powered medical carts with integrated computing, while IEC 60601-1 standards govern electrical safety and electromagnetic compatibility for devices deployed near patients. The EPA's antimicrobial coating regulations and OSHA ergonomic guidelines further constrain material selection and design configurations for US-manufactured units. Stakeholders must monitor evolving cybersecurity frameworks from the FDA and state-level telehealth reimbursement policies that will determine deployment scale for connected cart infrastructure.
Market Dynamics
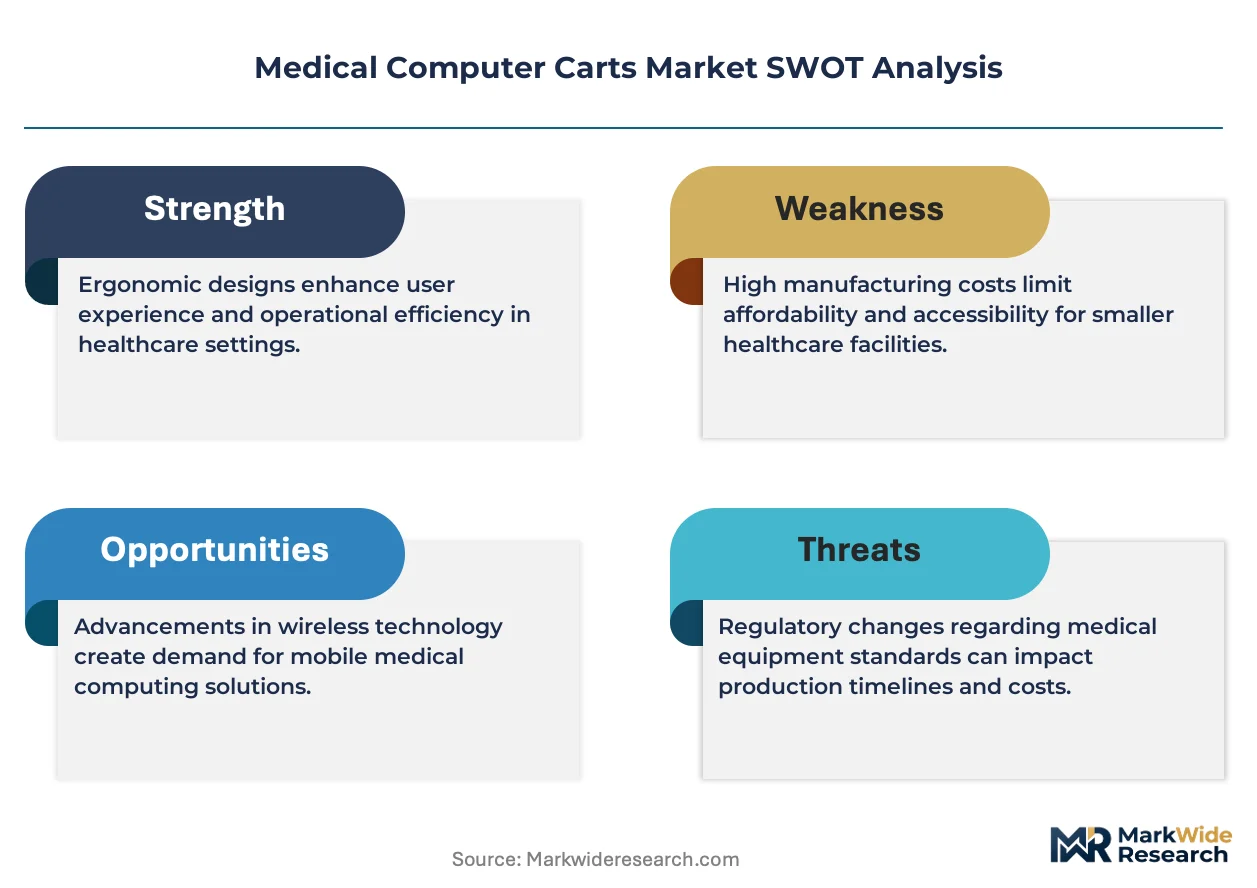
Hospital IT departments are consolidating vendor relationships around integrated powered workstation platforms that unify battery management, computing hardware, and antimicrobial surfaces into single-source procurement frameworks.
Growth Catalysts
- Point-of-care digitization mandates:Acute care facilities in the United States, Germany, and Japan are modernizing nursing station infrastructure to support real-time electronic health record access during patient rounds.
- IEC 60601 electrical safety standards:These certification requirements are filtering out non-compliant regional suppliers and elevating procurement specifications for powered mobile carts deployed near patients.
- Telehealth infrastructure expansion:Health systems are deploying integrated video cart configurations for remote specialist consultations, creating incremental demand for camera-mounted, height-adjustable mobile workstations.
Market Restraints
- Lithium-ion battery supply concentration:Cell production concentrates in East Asian manufacturing clusters, exposing cart assemblers to raw material volatility and logistics disruption risks.
- FDA 510(k) clearance timelines:Powered medical carts with integrated computing face extended premarket notification review periods that compress product launch windows and tie up R&D capital.
- Fixed workstation substitution:Wall-mounted arms and ceiling-mounted technology booms offer lower total cost of ownership for permanent room installations, limiting mobile cart penetration in new construction projects.
Strategic Opportunities
- Rural care extension networks:Underserved regions in the United States and Japan present deployment opportunities for telemedicine-configured carts connecting primary care clinics to urban specialists.
- Antimicrobial coating regulation tailwinds:EPA surface disinfectant requirements are driving replacement cycles for legacy carts lacking compliant finishes, opening upgrade revenue for certified suppliers.
- Battery-swapping logistics innovation:Third-party service providers are emerging to manage hot-swap battery fleets across multi-hospital networks, decoupling hardware sales from power infrastructure ownership.
Industry Challenges
- Cybersecurity integration complexity:Connected cart deployments must satisfy FDA cybersecurity framework requirements for networked medical devices, demanding specialized firmware development capabilities that strain traditional hardware manufacturers.
- Legacy fleet interoperability:Health systems with mixed-vendor installed bases face configuration management complexity when standardizing on new powered cart platforms with proprietary battery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Computer Carts Market |
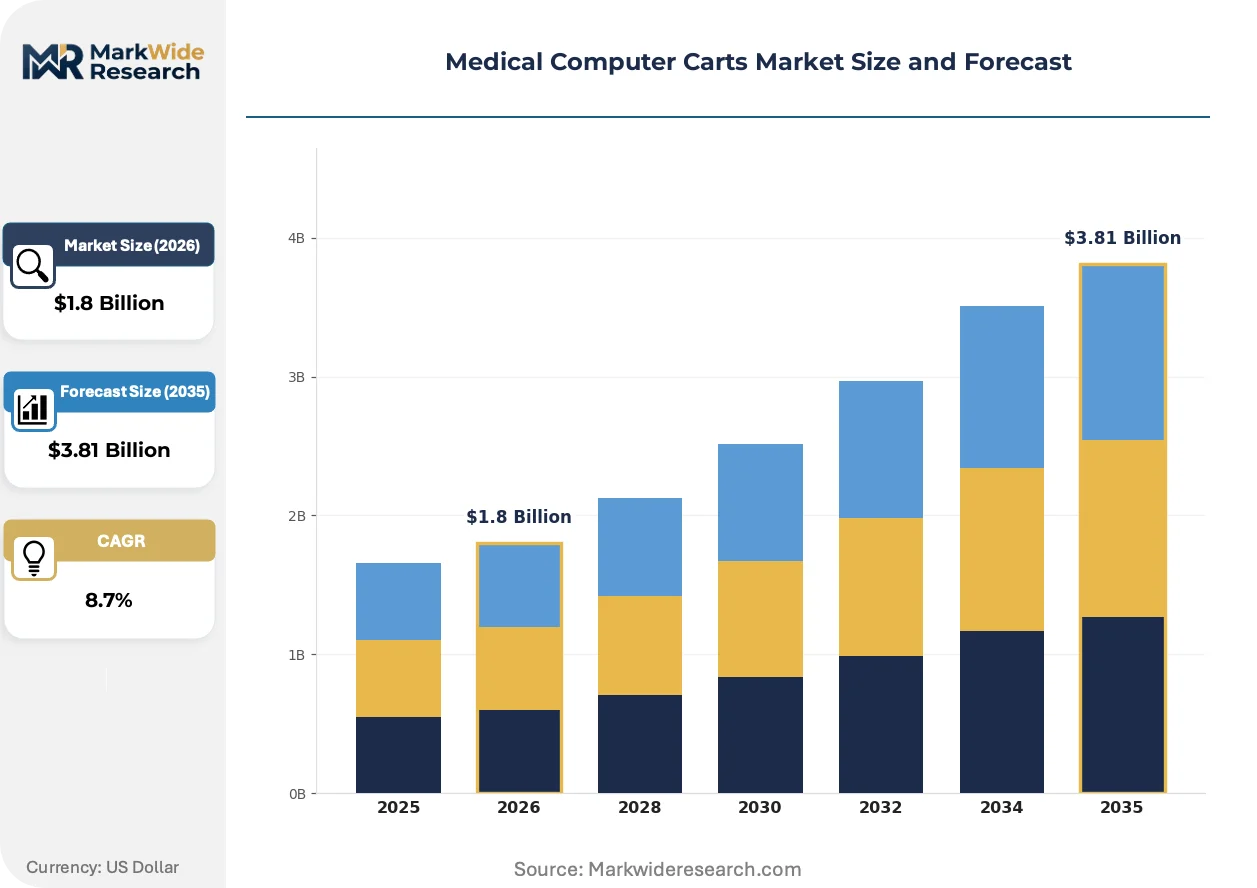
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Carts, Wall-Mounted Carts, Fixed Carts, Stationary Carts End User: Hospitals, Clinics, Long-Term Care Facilities, Home Healthcare Technology: Touchscreen, Wireless, Battery-Powered, Ruggedized Application: Patient Management, Medication Administration, Telemedicine, Data Entry |
| Companies Covered | Ergotron, Inc., AFC Industries, Capsa Healthcare, Enovate Medical, Advantech Co., Ltd., Harloff Manufacturing Co., JACO, Inc., Anthro Corporation, GCX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Computer Carts Market Strategic Shifts
Product architecture is converging around modular platform designs that separate compute, power, and display subsystems to accommodate faster technology refresh cycles without full cart replacement.
Hot-swappable battery architecture is hybridizing conventional mobile cart design with uninterrupted power supply principles. Emergency departments and intensive care units are adopting these configurations to eliminate cord hazards during rapid patient transport. This convergence is compressing replacement cycles for legacy plug-dependent carts while elevating vendor qualification criteria to include power electronics expertise.
REACH substance restrictions and RoHS hazardous material directives are constraining antimicrobial coating chemistries and electrical component solder specifications for carts manufactured or sold in European Union member states. Compliance investments are shifting toward material substitution and supply chain documentation systems. German acute care networks are responding by specifying pre-certified component platforms that accelerate their own procurement timelines.
Consolidated sourcing agreements are concentrating purchasing authority within health system corporate offices rather than individual facility departments. Group purchasing organizations are capturing larger contract volumes and unbundling aftermarket service from initial hardware transactions. This pattern is most pronounced in United States integrated delivery networks where standardization incentives override site-level brand preferences.
Medical Computer Carts Market Segmentation
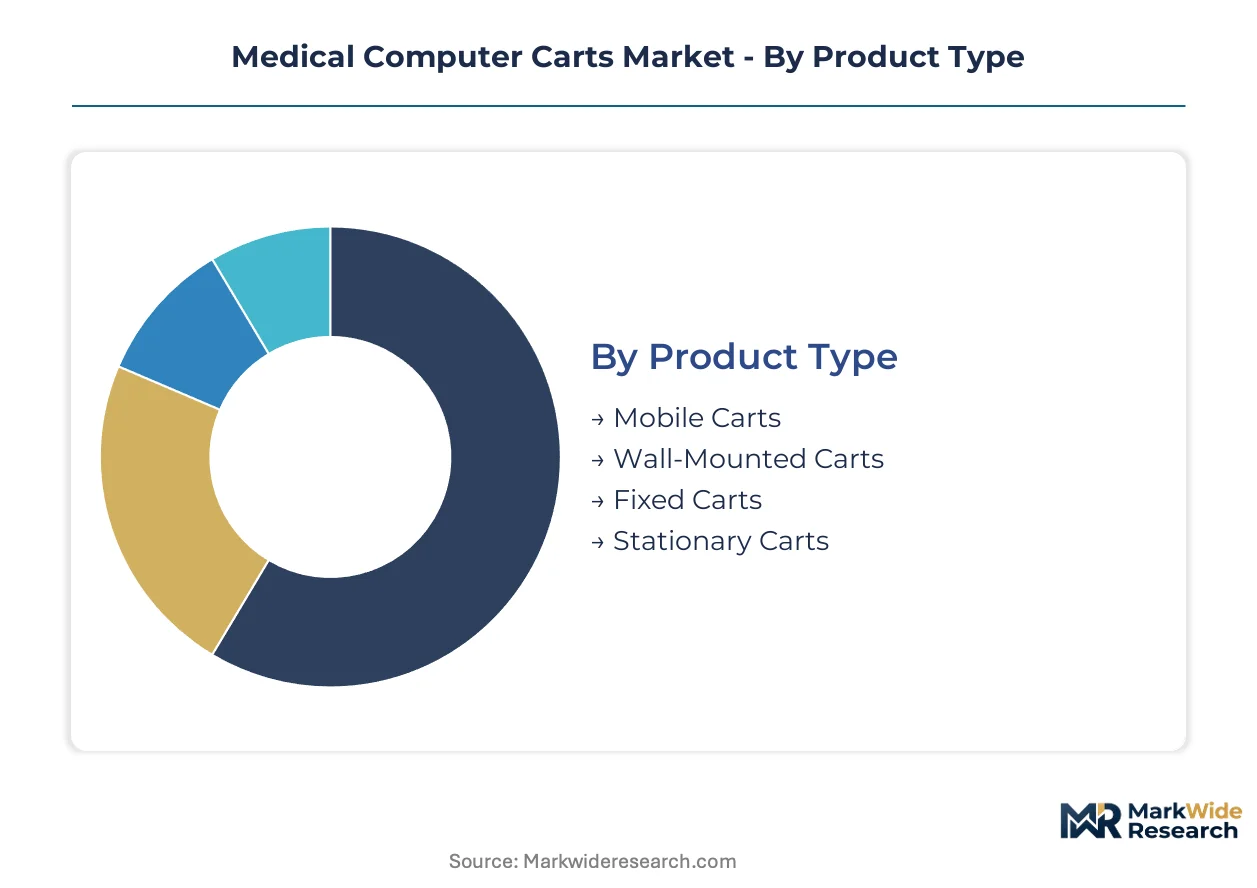
Segmentation in the medical computer carts market reveals distinct procurement patterns across product architecture, care setting, power technology, and clinical workflow integration. Each dimension carries different after-sales service intensity, with powered mobile platforms demanding captive maintenance networks while fixed installations minimize ongoing vendor dependency.
Product Type:
After-sales service intensity varies sharply across product mobility classes, with powered mobile carts requiring battery fleet management and preventive maintenance contracts that wall-mounted alternatives do not trigger.
- Mobile Carts:These platforms incorporate height-adjustable columns, antimicrobial surfaces, and casters rated for dynamic loads to transport computing hardware during patient rounds. Demand concentrates in United States acute care facilities modernizing emergency department workflows, where flexibility in room turnover outweighs higher total cost of ownership. Mobile Carts hold the largest share; momentum sits with Battery-Powered technology integration.
- Wall-Mounted Carts:Fixed-position arms attach to vertical surfaces to support displays and peripherals without floor footprint. German hospital construction projects specify these for permanent room installations where cord hazards must be eliminated without battery logistics.
- Fixed Carts:Stationary workstation platforms anchor to flooring or structural elements for high-stability computing access. Japan's aging facility infrastructure drives replacement demand where ceiling-mounted alternatives prove structurally impractical.
- Stationary Carts:Non-mobile units with limited or no casters serve dedicated departmental computing needs. Long-term care facilities in rural United States markets select these for medication administration stations with minimal relocation requirements.
Procurement specifications increasingly favor powered mobility; fixed alternatives dominate new construction budgets.
End User:
Customer type determines volume scale and standardization pressure, with hospital networks consolidating vendor relationships around integrated platforms while smaller settings prioritize acquisition cost.
- Hospitals:Acute care networks command the dominant procurement volume, consolidating purchasing authority through group purchasing organizations that unbundle aftermarket service from hardware transactions. United States integrated delivery networks drive standardization incentives that override site-level brand preferences.
- Clinics:Outpatient facilities select compact configurations for examination room computing with lower duty-cycle requirements. Telemedicine application demand accelerates in primary care clinics connecting to urban specialists.
- Long-Term Care Facilities:Skilled nursing and assisted living operators prioritize antimicrobial surface compliance and simplified cleaning protocols over advanced computing integration.
- Home Healthcare:Mobile cart deployments extend hospital-grade computing into residential settings for remote patient monitoring and telehealth consultations. Rural care extension networks in Japan present deployment opportunities for lightweight, battery-powered configurations.
Hospitals anchor procurement volume; home healthcare climbs fastest on telehealth infrastructure expansion.
Technology:
Power and interface technology selection determines replacement cycle timing and regulatory compliance burden, with battery architectures facing IEC 60601 certification requirements that touchscreen-only platforms avoid.
- Touchscreen:Integrated display interfaces eliminate peripheral keyboard and mouse dependencies for space-constrained clinical environments. Demand concentrates in medication administration applications requiring barcode verification at the point of care.
- Wireless:Network connectivity without Ethernet tethering supports continuous mobility across nursing units and emergency department zones. United States hospital IT departments prioritize these configurations for real-time electronic health record access during patient rounds.
- Battery-Powered:Hot-swappable lithium-ion architectures eliminate cord hazards and support uninterrupted operation across shift changes. IEC 60601 electrical safety standards filter non-compliant regional suppliers and elevate procurement specifications for powered mobile carts deployed near patients.
- Ruggedized:Reinforced enclosures withstand disinfection protocols, impact forces, and temperature variations in intensive care and operating room environments. German acute care networks specify pre-certified component platforms that accelerate procurement timelines.
Battery-Powered technology commands premium positioning; wireless connectivity gains share on network infrastructure modernization.
Application:
Clinical workflow integration determines display configuration, mounting flexibility, and peripheral integration requirements, with telemedicine deployments demanding camera-mounted, height-adjustable platforms that data entry stations do not require.
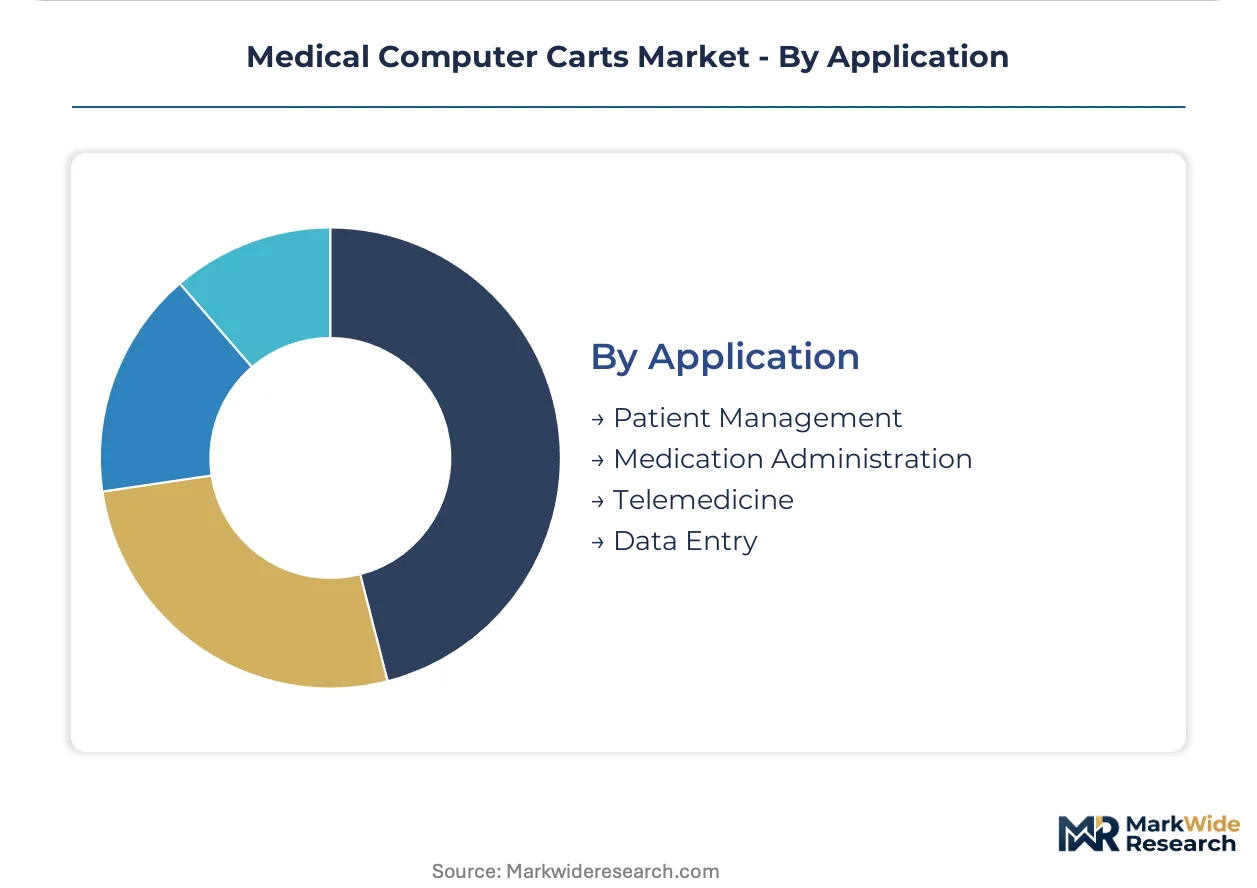
- Patient Management:Electronic health record access at the bedside drives height-adjustable configurations accommodating both seated documentation and standing rounds. United States facilities prioritize these for nursing station infrastructure modernization.
- Medication Administration:Barcode verification workflows require integrated scanners and secure storage compartments for pharmaceutical inventory. FDA 510(k) clearance pathways for powered medical carts with integrated computing extend premarket notification review periods for these configurations.
- Telemedicine:Video cart configurations connect rural primary care clinics to urban specialists for remote consultation. Health systems in Japan and the United States deploy integrated camera-mounted, height-adjustable mobile workstations for care extension networks.
- Data Entry:Administrative computing stations prioritize ergonomic keyboard positioning and display adjustability over clinical-grade mobility requirements. Fixed workstation substitution with wall-mounted arms limits mobile cart penetration in these applications.
Patient Management captures the greatest deployment volume; telemedicine expands most quickly on specialist access initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across procurement contexts. Acute care networks in mature markets absorb premium pricing for powered mobility, while budget-constrained facilities in emerging systems prioritize acquisition cost over battery-enabled configurations.
United States
Integrated delivery networks consolidate purchasing authority through group purchasing organizations, unbundling aftermarket service from hardware transactions. FDA 510(k) clearance pathways for powered medical carts with integrated computing compress product launch windows. Hospital IT departments in the Southeast and Midwest prioritize real-time electronic health record access during patient rounds.
Germany
Acute care networks specify pre-certified component platforms that accelerate procurement timelines. REACH substance restrictions and RoHS hazardous material directives constrain antimicrobial coating chemistries for carts manufactured or sold in European Union member states. Manufacturing clusters in Baden-Württemberg and Bavaria supply precision-engineered height-adjustable columns to cart assemblers.
Japan
Aging facility infrastructure drives replacement demand where ceiling-mounted alternatives prove structurally impractical. METI guidelines influence domestic procurement specifications for electrical safety near patients. Tokyo and Osaka metropolitan areas deploy telemedicine-configured carts connecting primary care clinics to urban specialists.
United Kingdom
NHS procurement frameworks standardize on antimicrobial surface compliance and simplified cleaning protocols. CE marking requirements under EU MDR filter non-compliant regional suppliers from cross-border supply chains. London and Southeast England health systems modernize nursing station infrastructure for medication barcode verification workflows.
India
Outpatient facilities select compact configurations for examination room computing with lower duty-cycle requirements. CDSCO medical device regulations establish premarket notification requirements for powered carts with integrated computing. Maharashtra and Karnataka states concentrate private hospital construction projects specifying mobile cart platforms for emergency department workflows.
Medical Computer Carts Market Competitive Environment
Capability concentration sits with specialists mastering battery management and IEC 60601 certification; scale advantage sits with diversified workstation platforms serving multi-hospital networks. The vendor base organizes into three tiers: integrated platform providers, component specialists with backward integration into monitor arms, and regional fabricators serving single-facility procurement. Dominant competitive moves include captive maintenance network construction and modular platform designs separating compute, power, and display subsystems.
Among North American specialists, Ergotron, Inc. and Capsa Healthcare occupy positions representing distinct strategic archetypes. Ergotron exemplifies upstream control over critical components through in-house production of monitor arm assemblies. Capsa Healthcare anchors the specialized distribution tier through partnerships with group purchasing organizations. Enovate Medical sits within the R&D-intensive segment focused on power electronics for wireless deployments. These three patterns—component control, channel anchoring, and technology specialization—define the competitive vectors reshaping vendor qualification criteria.
| Leading Market Players |
|---|
| Ergotron, Inc. |
| AFC Industries |
| Capsa Healthcare |
| Enovate Medical |
| Advantech Co., Ltd. |
| Harloff Manufacturing Co. |
| JACO, Inc. |
| Anthro Corporation |
| GCX Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in precision-machined height-adjustable column production across German and Japanese manufacturing clusters is elevating component pricing power while compressing margins for cart assemblers lacking captive supply. This utilization dynamic forces buyers into longer-term contracting to secure allocation, even as downstream hospital procurement offices consolidate volumes to extract concessions.
Pricing Analysis
Aftermarket service contracts and battery fleet management agreements generate lifetime value multiples exceeding initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates IEC 60601-certified powered platforms from basic touchscreen configurations and entry-level fixed installations. Cost compression in the standard tier is intensifying because group purchasing organizations are unbundling service from hardware and pitting vendors against consolidated volume targets. Long-term care facilities exhibit the highest price sensitivity, prioritizing acquisition cost over battery-enabled configurations, while United States integrated delivery networks absorb premium positioning for powered mobility with integrated cybersecurity frameworks.
Supply Chain Analysis
Lithium-ion cell production feeds from concentrated manufacturing bases in China, South Korea, and Japan, creating single-source vulnerability for cart assemblers without diversified supplier qualification. Aluminum extrusions for height-adjustable columns and antimicrobial-coated steel sheet for surfaces constitute additional critical inputs. Tariff exposure on Chinese-sourced battery cells and electronics assemblies is elevating landed cost volatility for North American and European cart manufacturers. Distribution runs through group purchasing organization contracts and direct hospital system procurement offices, with specialized medical device distributors serving smaller clinic and long-term care accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as point-of-care digitization mandates and telehealth infrastructure expansion create demand niches beyond the reach of consolidated platform providers. Modular subsystem specialization, rural care extension logistics, and cybersecurity-hardened firmware development each represent addressable white spaces.
For Market Incumbents: Build captive battery fleet management networks as the defensive moat. Integrate backward into power electronics assembly to control the highest-margin subsystem and reduce exposure to East Asian cell supply volatility. Invest in FDA cybersecurity framework pre-certification to accelerate 510(k) clearance timelines for connected cart deployments and lock out regional fabricators lacking firmware development capabilities. Fixed workstation substitution with wall-mounted arms threatens mobile cart penetration in new construction; counter by emphasizing hot-swap battery logistics as irreplaceable for emergency department workflows. For New Entrants and Emerging Players: Pursue third-party battery-swapping logistics services as an asset-light entry path, decoupling hardware sales from power infrastructure ownership across multi-hospital networks. Target rural primary care clinics in underserved United States and Japanese regions for telemedicine-configured cart deployments connecting to urban specialists. Leverage software-defined cart architectures with over-the-air firmware update capabilities to differentiate against legacy hardware vendors with stagnant product platforms. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists with proven IEC 60601 certification track records and existing group purchasing organization contract relationships, positioned for acquisition by integrated platform providers seeking geographic or technological fill-ins. Long-term viability hinges on cybersecurity integration capabilities and modular platform architectures accommodating faster technology refresh cycles. Monitor FDA premarket notification review period trends as an inflection indicator; extended timelines compress product launch windows and strain R&D capital for undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 60601-1 Certification Investment | Electrical safety compliance filters non-compliant regional suppliers from procurement specifications near patients. |
| Hospital System Partnership | Direct relationships with integrated delivery networks secure volume allocation ahead of GPO consolidation. |
| Software Companion Development | FDA cybersecurity framework compliance demands specialized firmware capabilities beyond traditional hardware manufacturing. |
| Backward Integration into Power Electronics | In-house battery management system production controls the highest-margin subsystem and reduces cell supply exposure. |
| Reimbursement Strategy | State-level telehealth policy alignment determines deployment scale for connected cart infrastructure in rural networks. |
Study Parameters
The analysis maps mobile cart platforms, fixed workstation alternatives, battery-powered configurations, and telemedicine-integrated systems, each validated through hospital IT directors, biomedical engineers, group purchasing organization contract managers, and antimicrobial coating suppliers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, IEC 60601 certification registries, hospital procurement transaction records, and GPO contract disclosure filings. Bottom-up cart shipment estimates by configuration type triangulated against top-down health system capital expenditure surveys.
Assumptions held fixed include regulatory compliance burden trajectories for FDA cybersecurity frameworks and IEC 60601 electrical safety standards, while battery cell cost curves and telehealth reimbursement policy evolution were varied across sensitivity scenarios. The forecast framework models product mobility class, power technology architecture, end-user facility type, and clinical workflow application as core segmentation dimensions. CAGRs were derived from installed base replacement cycle timing, new construction penetration rates, and technology substitution elasticities. Industry-specific inputs include lithium-ion battery supply lead times and hospital IT consolidation timelines.
Sensitivities concentrate around FDA premarket notification review period extensions, East Asian battery cell supply disruptions, and state-level telehealth reimbursement policy reversals. Cross-checking against hospital capital expenditure budget disclosures and GPO contract award announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Animal Operating Table Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Cell Washer Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Auditory Brainstem Response Analyzers Market
Medical Equipment
CO2 Medical Laser Systems Market