
 Orbital Shakers Market | 2026-2036
Orbital Shakers Market Size, Share, and Industry Trends Forecast 2026-2036
Orbital Shakers Market Analytics
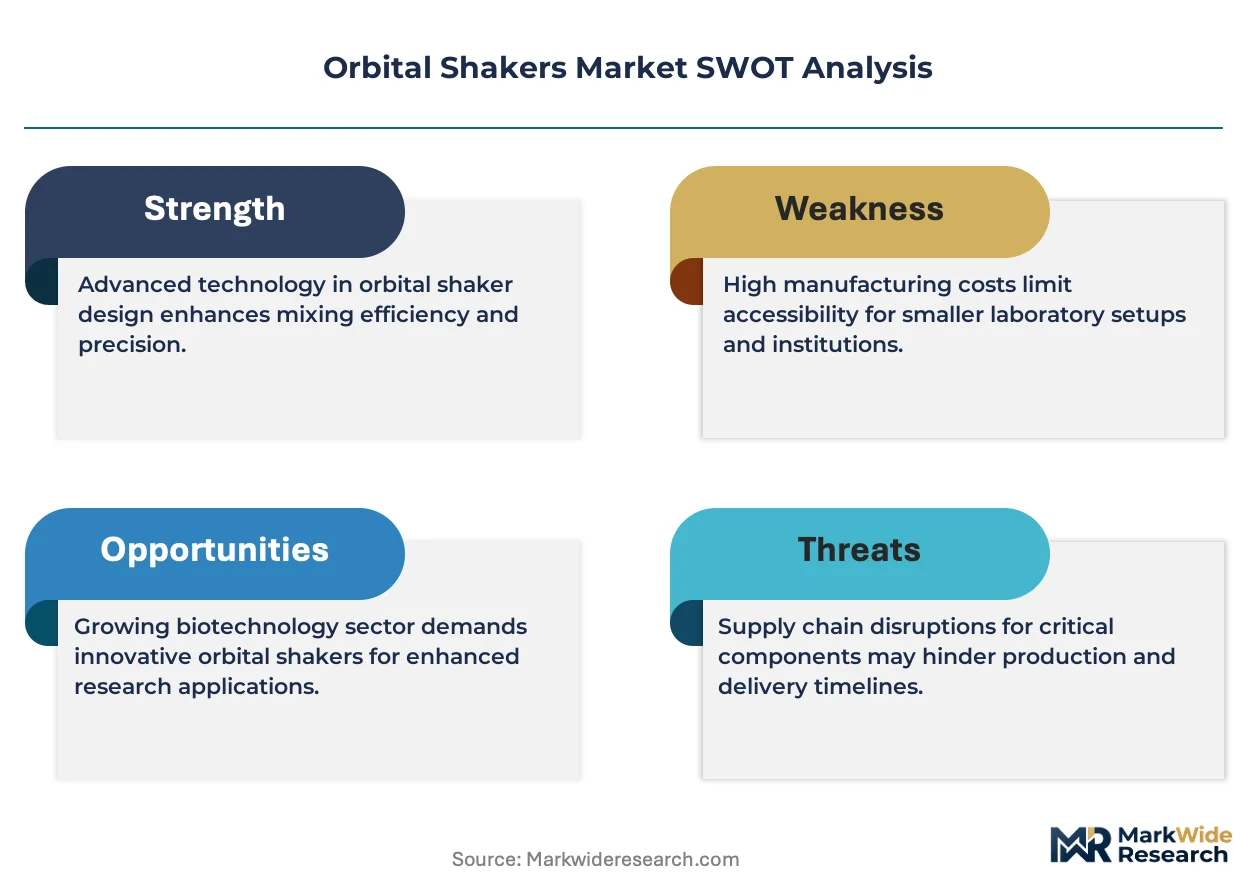
Buyer concentration among contract research organizations and biologics manufacturers is realigning procurement patterns across the supply base. Thermo Fisher Scientific leverages its integrated life sciences platform to dominate high-volume laboratory supply contracts. Eppendorf SE anchors its position through precision engineering capabilities in digital control systems. IKA Works competes on modular platform designs that reduce footprint constraints in crowded research facilities.
Orbital shakers are electromechanical devices that generate circular motion at controlled speeds, typically operating between 20 and 500 revolutions per minute with orbit diameters ranging from 3 mm to 50 mm, designed to suspend, mix, or aerate liquid samples in flasks, tubes, or microplates. Their primary purpose centers on maintaining homogeneous conditions for microbial culture, protein expression, and chemical synthesis where consistent oxygen transfer and temperature uniformity determine experimental reproducibility. Benchtop configurations occupy the largest installed base due to space constraints in academic and clinical laboratories, while automated technology segments capture expanding interest from pharmaceutical quality control departments seeking to reduce operator variability. Digital control systems now lead technology preferences over analog interfaces because programmable protocols enable traceable compliance documentation.
The FDA enforces current good manufacturing practice requirements that validate equipment qualification for pharmaceutical production environments, while EMA's Annex 15 guidelines extend similar expectations across European manufacturing sites. ISO 9001 quality management standards and ISO 13485 medical device frameworks further shape supplier certification requirements for equipment destined for regulated applications. Stakeholders must monitor how evolving GMP digitization mandates reshape validation documentation burdens and capital expenditure timelines.
Market Dynamics
Bioprocessing capacity expansion among contract research organizations is compressing equipment procurement cycles while tightening validation documentation requirements under evolving FDA and EMA digitization mandates.
Growth Catalysts
- Cell therapy manufacturing scale-up:Autologous and allogeneic cell therapy pipelines in the United States and Germany are demanding higher-throughput orbital shaker platforms for expansion culture workflows.
- EMA Annex 15 digitization:Electronic batch record requirements are accelerating replacement of analog-controlled equipment with programmable digital systems across European pharmaceutical manufacturing sites.
- Single-use bioreactor integration:Disposable culture vessel adoption is driving demand for orbital shakers with standardized docking interfaces and validated containment systems.
Market Restraints
- Stainless steel and rare earth magnet cost volatility:Electromechanical drive components face input price pressure from concentrated Chinese rare earth processing and European steel energy surcharges.
- Precision motor supplier concentration:Brushless DC motor and encoder manufacturing clusters in Japan and Germany create single-source vulnerability for high-precision speed control systems.
- Benchtop footprint constraints:Urban laboratory real estate limitations in Boston, San Francisco, and Cambridge restrict adoption of larger-capacity units regardless of performance advantages.
Strategic Opportunities
- India biologics manufacturing:CDSCO manufacturing license reforms and PLI scheme incentives are attracting bioprocessing investment in Hyderabad and Bangalore clusters.
- Gene therapy vector production:Adeno-associated virus suspension culture workflows require specialized high-speed orbital platforms with enhanced oxygen transfer capabilities.
- Cloud-connected equipment as a service:Subscription-based instrumentation models with remote monitoring and predictive maintenance are penetrating mid-sized CRO budgets.
Industry Challenges
- IQ/OQ/PQ documentation burden:FDA equipment qualification protocols demand 12-18 month validation timelines that delay revenue recognition for capital equipment vendors.
- Field service engineer scarcity:Electromechanical troubleshooting expertise and GMP documentation training gaps constrain aftermarket service expansion in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orbital Shakers Market |
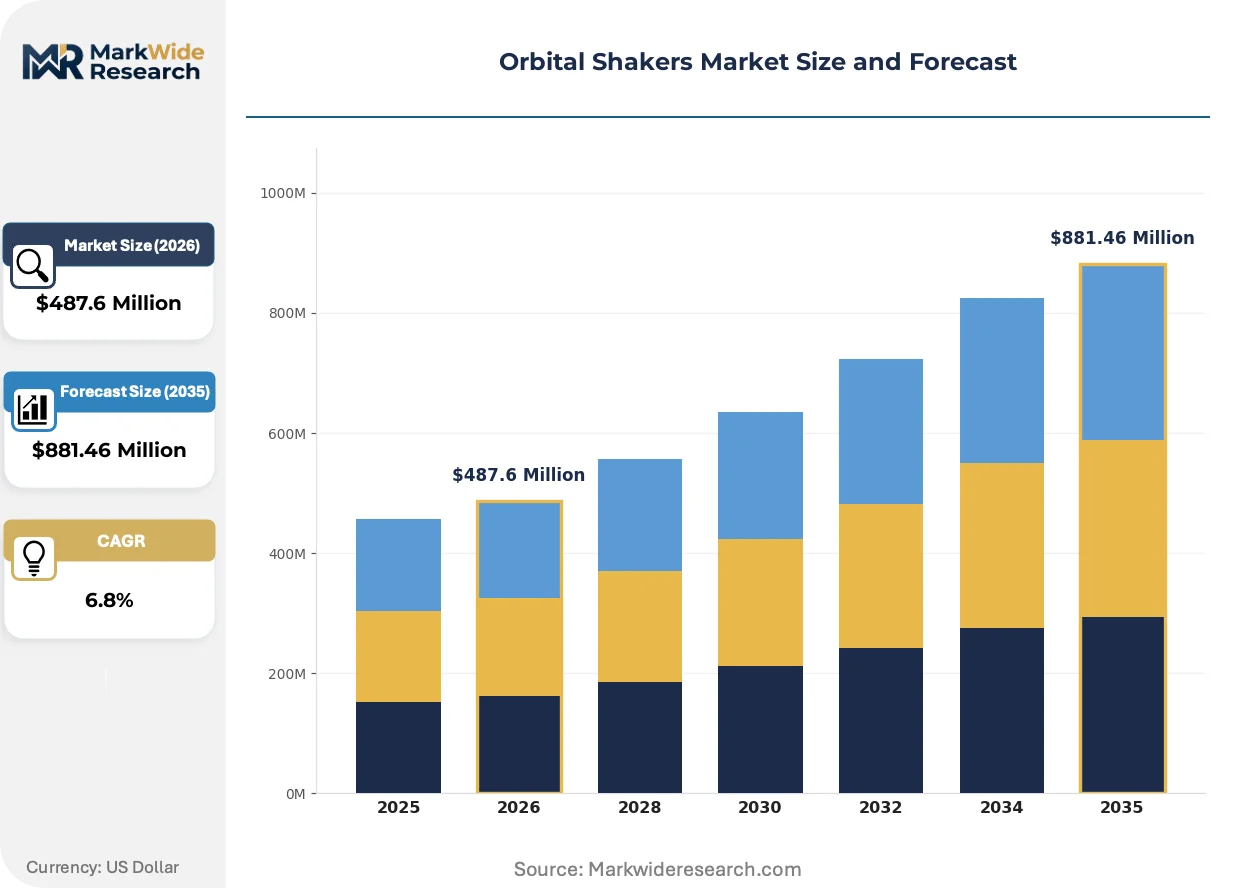
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Floor-Standing, Microplate, High-Speed End User: Laboratories, Pharmaceutical Companies, Research Institutions, Biotechnology Firms Application: Chemistry Research, Molecular Biology, Cell Culture, Quality Control Technology: Analog, Digital, Hybrid, Automated |
| Companies Covered | Thermo Fisher Scientific, Eppendorf SE, IKA Works, Heidolph Instruments, Benchmark Scientific, Corning, VWR International, Labnet International, Heathrow Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orbital Shakers Market Evolving Landscape
Digital control architectures and connectivity protocols are displacing analog interfaces across the installed base while regulatory digitization mandates compress equipment replacement cycles.
Stackable orbital shaker platforms with independent temperature and speed zones are modularizing laboratory space allocation. Pharmaceutical quality control departments in the United States are adopting these configurations to parallelize batch testing without expanding physical footprints. This modularity is enabling equipment-as-a-service business models that reduce capital commitment for mid-sized contract manufacturers.
EMA's Annex 15 revision and FDA's guidance on computerized systems in manufacturing equipment are mandating audit trail functionality and electronic signature capability. European biologics manufacturers face 2025 compliance deadlines for electronic batch record integration. Benchtop equipment suppliers are responding with embedded software validation packages that reduce customer qualification burden.
Consolidated procurement through integrated life sciences distributors is displacing direct manufacturer relationships for standard laboratory equipment. Academic institutions and small biotechs in Germany and the United Kingdom are channeling purchases through preferred vendor agreements with consolidated catalog suppliers. This concentration is compressing price realization for non-differentiated benchtop configurations while elevating service and compliance documentation as competitive differentiators.
Orbital Shakers Market Segmentation
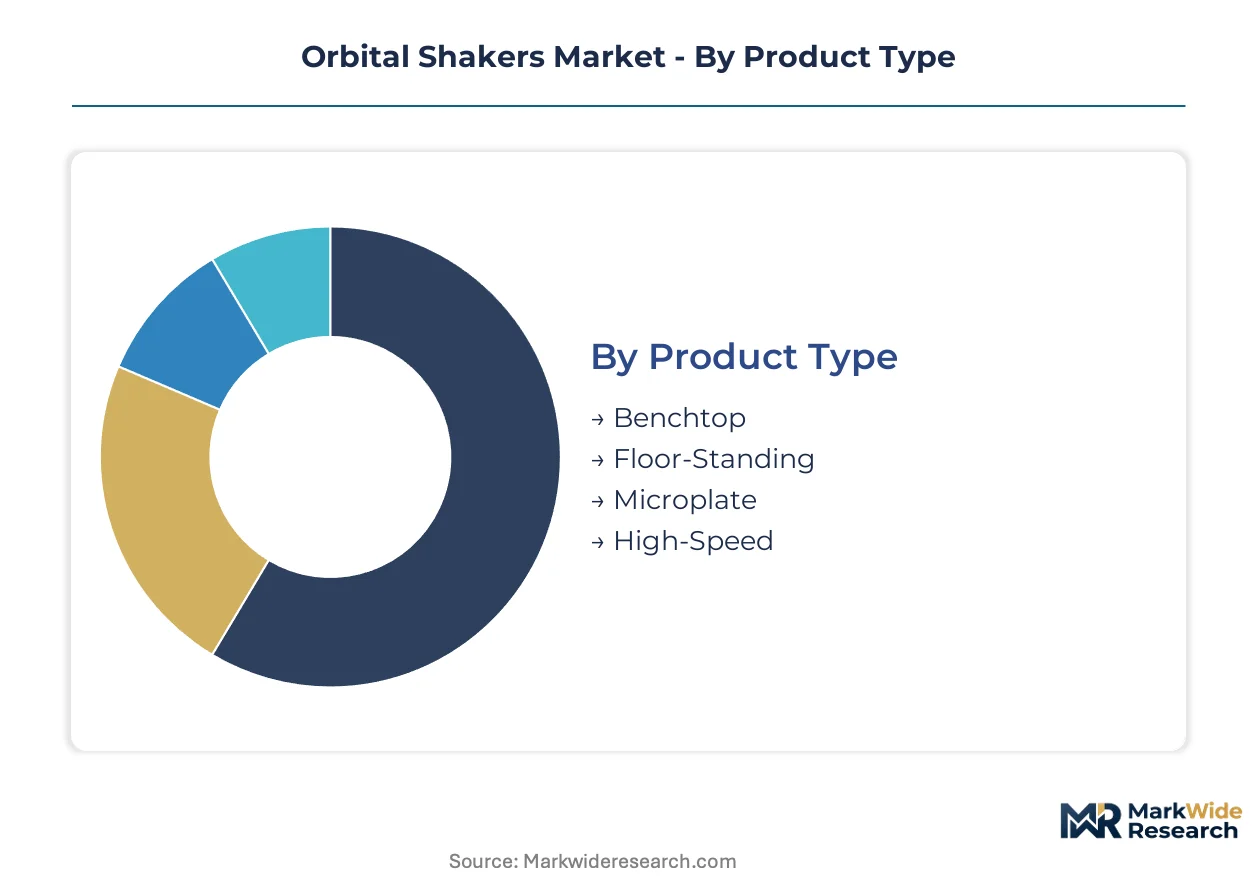
Orbital shaker procurement patterns diverge sharply between high-throughput pharmaceutical manufacturing and space-constrained academic settings. Equipment specifications, validation requirements, and connectivity protocols vary substantially across these deployment contexts.
Product Type:
Volume concentration sits with compact configurations, while premium pricing attaches to specialized high-performance platforms.
- Benchtop:These compact units operate within 20-500 RPM ranges with orbit diameters of 3-25 mm, designed for flask and tube agitation in confined laboratory spaces. Demand clusters in Boston and San Francisco biotech clusters where real estate costs constrain equipment footprint. Academic institutions and small CROs prioritize these units for routine microbial culture despite limited throughput capacity.
- Floor-Standing:Large-capacity platforms accommodate multiple vessel sizes simultaneously with enhanced temperature uniformity across expanded shaking surfaces. Pharmaceutical quality control departments in Germany and the United States deploy these for parallel batch testing workflows. EMA Annex 15 digitization mandates are accelerating replacement of legacy analog floor-standing units with programmable digital alternatives.
- Microplate:Specialized compact shakers optimized for 96-well and 384-well plate formats with precise orbit control for high-throughput screening applications.
- High-Speed:Accelerated platforms reaching 500+ RPM with enhanced oxygen transfer coefficients for suspension culture of shear-sensitive cell lines.
Today's leader: Benchtop. Tomorrow's challenger: High-Speed.
End User:
Procurement authority concentrates with organizations bearing GMP compliance burdens, while research institutions drive volume through fragmented purchasing.
- Laboratories:Academic and clinical testing facilities constitute the broadest installed base, prioritizing cost efficiency and space optimization over advanced connectivity features. University procurement departments in the United Kingdom and Germany channel purchases through consolidated catalog distributors, compressing price realization for standard configurations.
- Pharmaceutical Companies:Regulated manufacturers demand validated equipment with IQ/OQ/PQ documentation packages, electronic batch record integration, and audit trail functionality. FDA current good manufacturing practice requirements and EMA Annex 15 guidelines shape their specification criteria, extending procurement cycles to 12-18 months but commanding premium pricing.
- Research Institutions:Government and private research centers balance performance requirements with grant-funded budget constraints, often prioritizing multi-user platform flexibility.
- Biotechnology Firms:Venture-backed cell therapy and gene therapy developers require scalable platforms that transition from process development to cGMP manufacturing without revalidation.
Pharmaceutical Companies capture the steepest expansion trajectory as cell therapy manufacturing scales.
Application:
Cell culture workflows command premium platform specifications, while quality control applications drive standardization and replacement volume.
- Cell Culture:Mammalian and microbial suspension culture demands precise temperature uniformity, controlled oxygen transfer, and contamination prevention through sealed enclosure designs. Autologous and allogeneic cell therapy pipelines in the United States and Germany require orbital shakers with validated performance for expansion culture of sensitive therapeutic cell lines.
- Quality Control:Pharmaceutical release testing protocols require equipment with documented calibration traceability, electronic signature capability, and integration with laboratory information management systems. EMA's electronic batch record deadlines are compressing replacement cycles for analog-controlled units across European manufacturing sites.
- Chemistry Research:Synthetic and analytical chemistry applications emphasize chemical resistance, broad temperature ranges, and compatibility with aggressive solvents.
- Molecular Biology:Nucleic acid and protein workflows require minimal vibration transmission to protect sensitive reactions and hybridization processes.
Cell Culture leads current premium capture. Quality Control is gaining share fastest through regulatory-forced replacement.
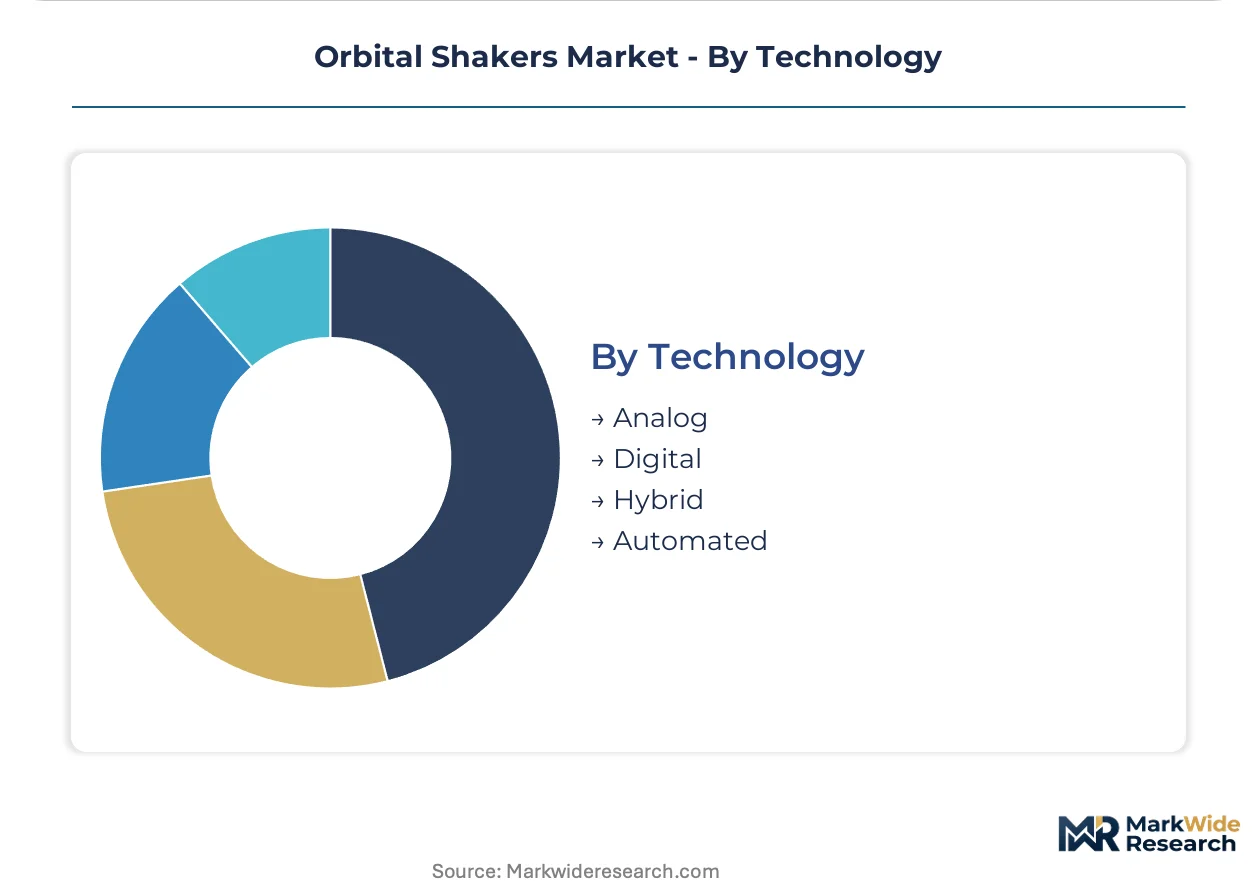
Technology:
Digital architectures displace analog interfaces across all price tiers, while automated platforms remain concentrated in high-throughput pharmaceutical environments.
- Digital:Microprocessor-controlled systems with programmable protocols, remote monitoring capability, and electronic documentation features now dominate new procurement. European biologics manufacturers face compliance deadlines for electronic batch record integration, accelerating adoption of digital platforms with embedded software validation packages.
- Automated:Robotic integration enables unattended operation with automated vessel handling, media exchange, and sampling for continuous culture applications. Gene therapy vector production facilities in the United States deploy these for adeno-associated virus suspension culture requiring precise environmental control over extended production campaigns.
- Analog:Mechanical speed control with minimal electronic components persists in budget-sensitive academic settings and developing market installations.
- Hybrid:Mixed architectures combine digital monitoring with simplified manual controls for facilities transitioning validation protocols.
Digital commands today's volume. Automated platforms are climbing the fastest as labor cost and reproducibility pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioprocessing engineers and GMP validation specialists concentrate in Germany and the United States, anchoring the highest-value procurement corridors for precision cell culture equipment.
United States
Autologous cell therapy manufacturers in Greater Boston and the San Francisco Bay Area drive demand for validated high-speed orbital platforms. FDA current good manufacturing practice requirements for electronic batch records compress replacement cycles for legacy analog equipment. Cambridge and South San Francisco biotech clusters prioritize stackable configurations that maximize throughput within constrained laboratory footprints.
Germany
Contract research organizations in Baden-Württemberg and Bavaria scale suspension culture capacity for viral vector production. EMA Annex 15 digitization mandates enforce audit trail functionality and electronic signature capability across pharmaceutical manufacturing sites. Heidelberg and Munich bioprocessing hubs accelerate procurement of programmable digital systems ahead of compliance deadlines.
India
CDSCO manufacturing license reforms and PLI scheme incentives attract biologics investment to Hyderabad and Bangalore. The national pharmaceutical regulator tightens documentation requirements for equipment qualification in export-oriented facilities. Genome Valley and Biocon Park clusters expand contract manufacturing capacity for monoclonal antibody production.
United Kingdom
Academic procurement departments channel purchases through consolidated catalog distributors, compressing price realization for standard benchtop configurations. Research councils prioritize multi-user platform flexibility in grant-funded laboratory renovations. Oxford and Cambridge life science clusters balance performance requirements with budget constraints from public funding cycles.
China
Domestic biopharmaceutical manufacturers expand viral vector production capacity for gene therapy pipelines under NMPA good manufacturing practice oversight. Dual carbon goals accelerate energy efficiency specifications for electromechanical laboratory equipment. Shanghai and Suzhou bioprocessing clusters invest in automated platforms with standardized docking interfaces for single-use bioreactor integration.
Orbital Shakers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base separates into three strategic archetypes: integrated life sciences platforms commanding high-volume supply contracts, precision engineering specialists anchoring digital control system segments, and modular design innovators addressing footprint-constrained facilities. Capacity expansion and compliance documentation differentiation dominate competitive moves as validation timelines extend procurement cycles.
Within the integrated platform tier, Thermo Fisher Scientific exemplifies the diversified conglomerate archetype with broad laboratory supply reach. Eppendorf SE occupies a position among precision-focused specialists emphasizing electromechanical engineering depth. IKA Works represents the modular innovation segment with configurable platform architectures. These three anchors illustrate how vendor strategies diverge between scale-driven consolidation and technical specialization in regulated bioprocessing environments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eppendorf SE |
| IKA Works |
| Heidolph Instruments |
| Benchmark Scientific |
| Corning |
| VWR International |
| Labnet International |
| Heathrow Scientific |
| Others |
Value Network & Pricing Analysis
EMA Annex 15 digitization mandates and FDA electronic batch record requirements gate qualified supply access for orbital shaker manufacturers, restricting premium-tier pricing to vendors with validated IQ/OQ/PQ documentation packages and embedded software validation capabilities. Pharmaceutical procurement teams in Germany and the United States pay substantial premiums for equipment meeting these compliance thresholds, while academic buyers face compressed price realization through consolidated catalog distribution channels.
Pricing Analysis
Bundled service contracts encompassing installation qualification, operational qualification, and ongoing calibration services command 35-50% price premiums over unbundled equipment-only transactions in regulated pharmaceutical environments. Pricing stratifies across GMP-validated, research-grade, and educational tiers, with FDA and EMA certification status serving as the primary differentiation driver. Cost compression in the research-grade tier intensifies as consolidated distributors like VWR International and Thermo Fisher Scientific aggregate volume and standardize specifications. Contract research organizations exhibit the highest price sensitivity due to grant-funded budget constraints, while cell therapy manufacturers demonstrate minimal elasticity given revalidation costs.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Singapore anchor hub-and-spoke fulfillment patterns for orbital shaker manufacturers serving bioprocessing clusters. Electromechanical production concentrates in Germany and Japan, with brushless DC motors and precision encoders sourced from concentrated supplier bases in Osaka and Stuttgart. Supply chain risk centers on single-source vulnerability for rare earth magnets processed through Chinese refining operations. Distribution runs through integrated life sciences platforms and specialized laboratory equipment distributors, with direct manufacturer relationships persisting only for large-scale GMP-validated deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orbital shakers function as a geographic-arbitrage play where CDSCO manufacturing license reforms and PLI scheme incentives in India offer 40-60% cost advantages against FDA-validated equipment procurement cycles in the United States, enabling capital-efficient capacity expansion for export-oriented biologics manufacturers.
For Market Incumbents: Acquire field service engineering capabilities with GMP documentation training to address scarcity constraints in secondary markets like India and China. Incumbent vendors face substitution risk from modular platform specialists like IKA Works; defensive consolidation requires backward integration into precision motor supply chains and capacity addition in Hyderabad and Bangalore to serve expanding CDSCO-regulated manufacturing clusters. For New Entrants and Emerging Players: Launch via cloud-connected equipment-as-a-service subscription models targeting mid-sized contract research organizations in the United Kingdom and Germany. White-space penetration concentrates in automated high-speed platforms for gene therapy vector production, where adeno-associated virus suspension culture workflows demand specialized oxygen transfer capabilities underserved by standard benchtop configurations. Go-to-market execution should prioritize direct relationships with cell therapy process development teams before cGMP manufacturing scale-up transitions. For Investors and Strategic Acquirers: Roll-up economics work for precision electromechanical specialists because EMA Annex 15 digitization mandates compress replacement cycles and extend validation documentation moats around established vendors. Five-to-ten-year viability hinges on software validation package differentiation and aftermarket service density. Acquisition targets should display embedded digital control architectures and installed bases in FDA-regulated pharmaceutical manufacturing sites. The critical inflection signal remains CDSCO export facility certification timelines accelerating bioprocessing investment in Indian manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Software Validation Package Development | Reduces customer IQ/OQ/PQ burden under FDA and EMA digitization mandates. |
| Field Service Engineer Training Programs | Addresses scarcity constraints for GMP documentation expertise in secondary markets. |
| Cloud-Connected Equipment-as-a-Service Launch | Penetrates mid-sized CRO budgets with predictive maintenance and remote monitoring. |
| Single-Use Bioreactor Docking Standardization | Enables seamless integration with disposable culture vessel adoption trends. |
| India Manufacturing Footprint Expansion | Captures PLI scheme incentives and CDSCO export facility growth in Hyderabad clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bioprocessing engineers, GMP validation specialists, laboratory procurement managers, and aftermarket service directors with secondary validation against FDA 483 observations, EMA inspection databases, ISO 13485 certification registries, and customs trade data for electromechanical laboratory equipment. Bottom-up triangulation across product type, end user, application, and technology segments anchored against top-down pharmaceutical capital expenditure disclosures.
Comparable-period anchoring linked projection assumptions to historical replacement cycle patterns and regulatory compliance deadline impacts across the analysis window. Segmentation modeling incorporated product configuration, end-user compliance burden, application workflow requirements, and technology architecture dimensions. CAGRs derived from equipment procurement cycle compression rates and bioprocessing capacity expansion trajectories, with gene therapy pipeline scale-up and cell therapy manufacturing investment serving as primary demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth magnet supply disruptions or accelerated EMA digitization deadline revisions. Outputs reflect documented assumptions regarding regulatory enforcement consistency and biologics manufacturing investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Electrophoresis Equipment and Supplies Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Global Hematology Analyzers and Reagents Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Microplate Handling Instruments Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Histopathology Laboratory Equipment Market