
 Reconstructive Surgery Market | 2026-2036
Reconstructive Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Reconstructive Surgery Market Outlook
South Korea is rewriting the competitive map for reconstructive surgery through concentrated investment in robotic surgical systems and biomaterial foundries. Johnson & Johnson sustains broad portfolio coverage across biologics and synthetic matrices for soft-tissue repair. Zimmer Biomet dominates orthopedic reconstruction through proprietary porous titanium constructs and patient-specific instrumentation. Integra LifeSciences specializes in regenerative biologics, leveraging its dermal regeneration platform across burn and breast reconstruction protocols.
Reconstructive surgery encompasses the surgical restoration of form and function following trauma, congenital defects, oncologic resection, or degenerative disease, employing autologous tissue transfer, allogeneic grafts, synthetic biomaterials, and biologic scaffolds engineered to integrate with host vasculature. The field serves both aesthetic and essential medical purposes, with particular intensity in post-mastectomy breast restoration and complex wound closure. Breast reconstruction commands the largest procedure-type revenue pool, though 3D bioprinting within the technology segment represents the fastest-expanding capability frontier as printed vascularized tissue constructs approach clinical translation. Hospitals retain the dominant end-user position for complex multi-stage cases, while ambulatory surgical centers capture escalating volume for streamlined tissue expansion and autologous flap procedures.
FDA premarket notification pathways and Good Manufacturing Practice standards for human cells and tissues govern product commercialization and clinical adoption timelines in the United States. The EU Medical Device Regulation and REACH chemical safety frameworks impose additional conformity requirements on synthetic biomaterial suppliers seeking European market access. Stakeholders must monitor regulatory convergence between FDA and EMA on 3D bioprinted product classification, as divergent frameworks could fragment clinical trial investment and delay cross-border technology deployment.
Market Dynamics
FDA clearance pathway compression for 3D bioprinted grafts is collapsing development timelines from decade-long cycles to multi-year sprints, forcing incumbent biomaterial suppliers to accelerate regenerative platform investments or cede position to biofabrication startups.
Growth Catalysts
- EU Medical Device Regulation harmonization:MDR conformity requirements for synthetic biomaterials are streamlining cross-border product registration, reducing redundant testing costs for European suppliers seeking multi-country access.
- Ambulatory surgical center volume concentration:United States outpatient facilities are capturing escalating breast reconstruction and orthopedic procedure flows, compressing hospital inpatient stays and expanding addressable sites for tissue expansion devices.
- Patient-specific instrumentation adoption:Preoperative 3D modeling and custom surgical guides are reducing operative time and revision rates in complex craniofacial and orthopedic reconstruction cases.
Market Restraints
- Human-derived biomaterial supply volatility:Allograft and xenograft sourcing depends on tissue bank network stability, with procurement disruptions concentrated in cadaveric skin and amniotic membrane segments.
- Bioprinted vascularization technical ceiling:Engineered tissue constructs remain limited to sub-millimeter thickness without functional capillary networks, constraining clinical translation beyond superficial dermal applications.
- REACH chemical safety compliance burden:Synthetic polymer suppliers face extended substance registration timelines and toxicity testing costs for novel biodegradable scaffolds entering European markets.
Strategic Opportunities
- Underpenetrated South Korean reconstructive demand:Concentrated investment in robotic surgical systems and biomaterial foundries is creating export-oriented manufacturing capacity for Asian and Middle Eastern markets.
- Regenerative biologics-microrobotics convergence:Magnetically actuated cell-laden hydrogels promise minimally invasive delivery of vascularized tissue precursors to deep wound beds.
- India CDSCO fast-track pathway utilization:Expedited approval mechanisms for orphan indication biomaterials offer first-mover positioning for complex congenital defect repair products.
Industry Challenges
- Microvascular anastomosis skill scarcity:Free flap reconstruction requires subspecialized surgical training programs that face enrollment bottlenecks and protracted credentialing timelines.
- Bioprinted product classification uncertainty:Divergent FDA-EMA frameworks for regulating living tissue constructs as devices versus biologics complicates clinical trial design and cross-border regulatory strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reconstructive Surgery Market |
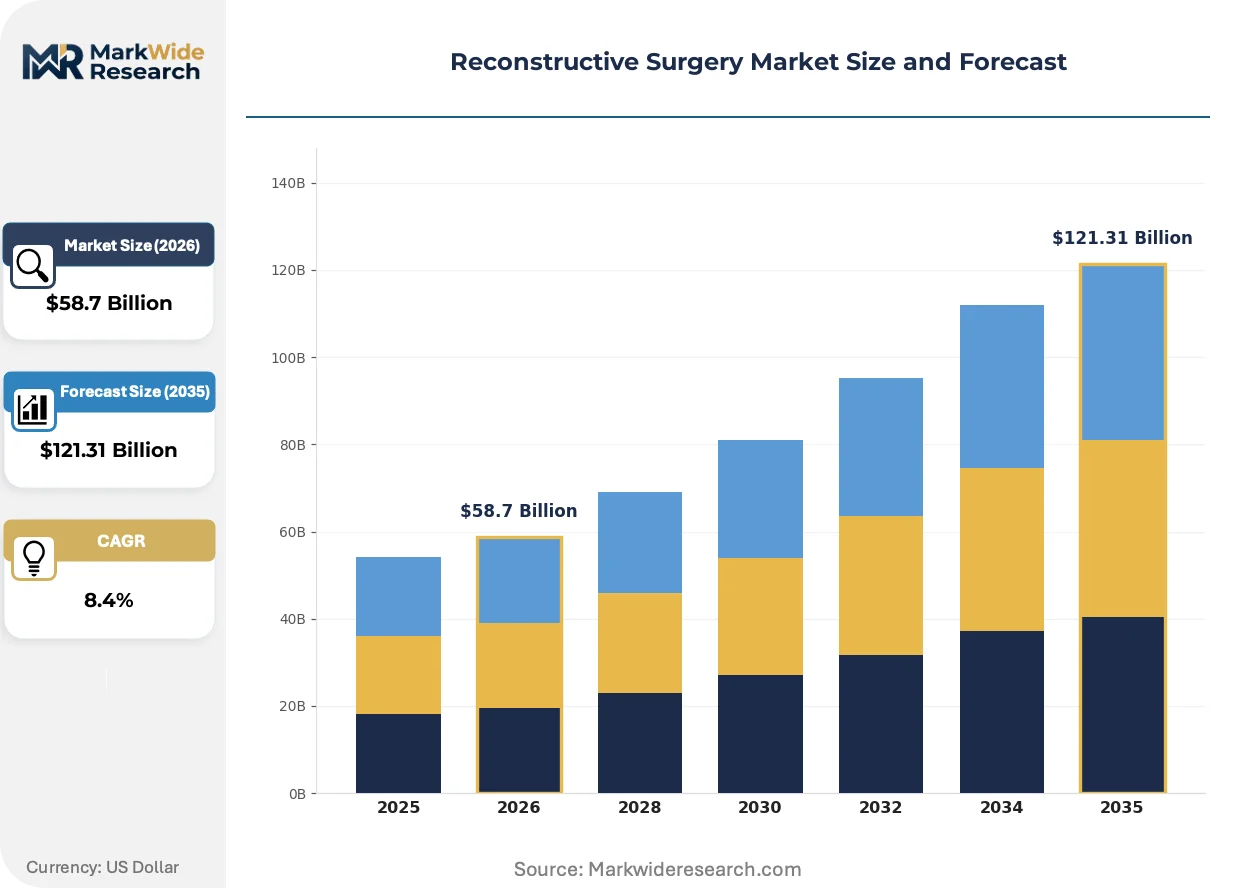
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Reconstruction, Skin Grafting, Tissue Expansion, Orthopedic Reconstruction End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Facilities Material Type: Biologics, Synthetic Biomaterials, Autologous Tissue, Allografts Technology: 3D Bioprinting, Robotics, Minimally Invasive Surgery, Surgical Navigation |
| Companies Covered | Medtronic, Johnson & Johnson, Zimmer Biomet, Integra LifeSciences, B. Braun Melsungen AG, AbbVie, Siemens, KLS Martin Group, Baxter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reconstructive Surgery Market Strategic Shifts
Bioprinting platforms and robotic surgical systems are converging to automate tissue fabrication and operative precision, while regulatory frameworks race to classify novel constructs. These forces are compressing the gap between laboratory innovation and bedside application.
Photocrosslinkable bioinks incorporating patient-derived cells are rendering obsolete the two-stage paradigm of synthetic scaffold implantation followed by delayed cellular infiltration. Academic medical centers in the United States and Germany are piloting same-day bioprinting workflows for burn and breast reconstruction. This compression of the treatment timeline is collapsing revenue recognition cycles for traditional matrix suppliers.
EMA and FDA are converging on Good Manufacturing Practice standards for human cells and tissues, though classification divergence persists for vascularized bioprinted constructs. The EU Medical Device Regulation now explicitly captures cell-laden scaffolds as Class III devices, triggering notified body involvement. Synthetic biomaterial suppliers with existing MDR technical documentation are leveraging regulatory familiarity to enter bioprinted product development partnerships.
Hospital procurement committees are unbundling reconstructive surgery device contracts from bundled payment agreements, creating direct purchasing relationships with biomaterial manufacturers. This disintermediation of group purchasing organization channels is most visible in United States academic medical centers with dedicated reconstructive service lines. Suppliers are responding with site-specific clinical specialist deployment and inventory consignment models.
Reconstructive Surgery Market Segmentation
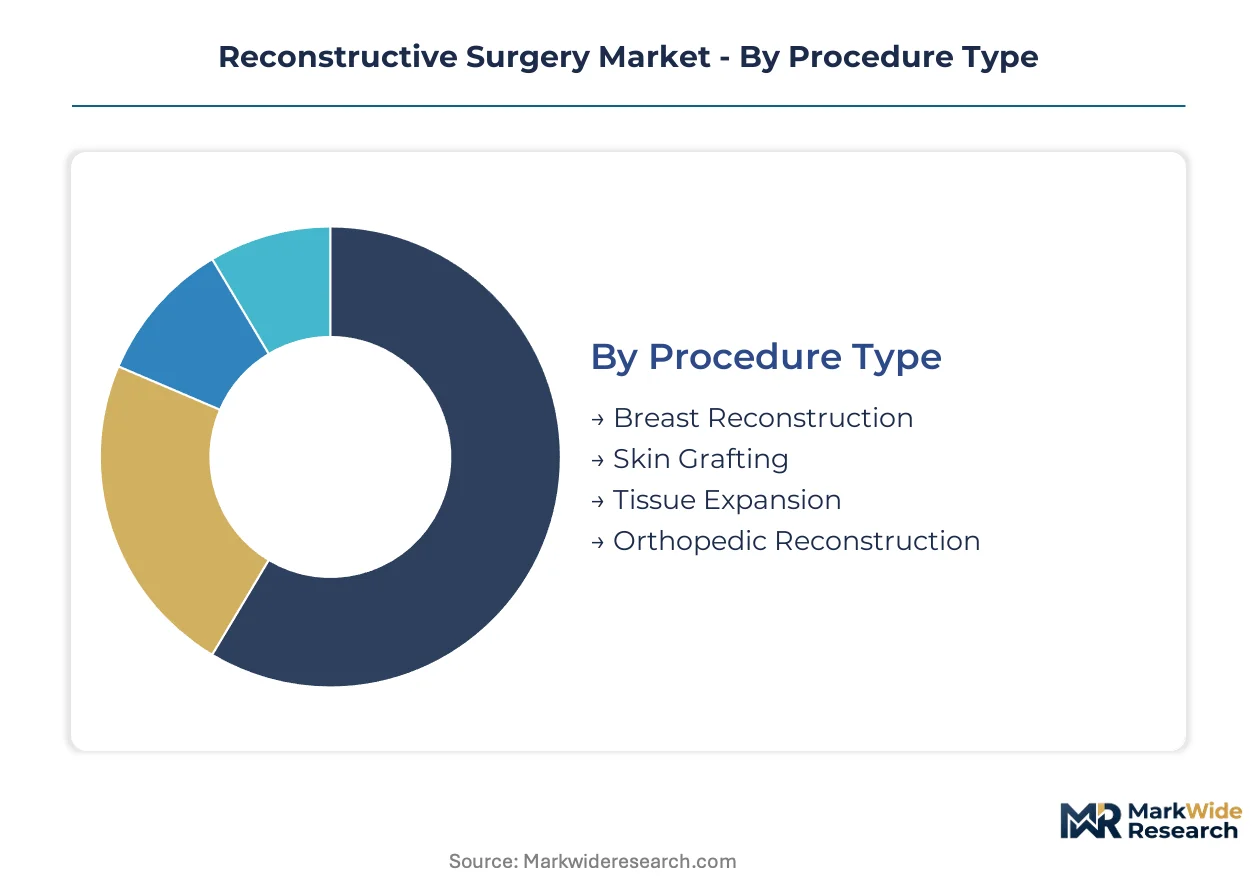
Reconstructive surgery segmentation reveals divergent capital intensity and reimbursement profiles across procedure types and material categories. Cycle times for technology adoption vary from immediate ASC uptake of minimally invasive tools to decade-long hospital validation of bioprinted constructs.
Procedure Type:
Breast reconstruction commands the longest procedure timelines with multi-stage tissue expansion protocols, while skin grafting turns over fastest in acute burn settings.
- Breast Reconstruction:Implant-based and autologous flap techniques dominate post-mastectomy restoration. United States ASC volume is escalating as prepectoral implant placement shortens operative time and recovery windows.
- Skin Grafting:Split-thickness and full-thickness autografts address acute thermal injury and chronic wound closure. Demand concentrates in United States burn centers where cadaveric allograft shortages accelerate synthetic dermal substitute adoption.
- Tissue Expansion:Gradual inflation of subcutaneous balloons precedes definitive reconstruction in burn scar revision and breast restoration. Hospital inpatient stays dominate due to serial expansion protocols requiring specialized nursing.
- Orthopedic Reconstruction:Bone grafting and joint restoration procedures leverage porous titanium constructs and patient-specific instrumentation. Zimmer Biomet's proprietary platforms anchor supply relationships with United States academic medical centers.
Breast reconstruction anchors the volume base while 3D bioprinting applications in skin grafting gain share at the steepest rate.
End User:
Capital deployment and staffing models separate high-acuity hospital systems from streamlined outpatient facilities pursuing case volume capture.
- Hospitals:Complex multi-stage reconstructions requiring microvascular teams and intensive care support. United States academic medical centers maintain dominant positions for free flap breast and craniofacial procedures.
- Ambulatory Surgical Centers:Streamlined tissue expansion and implant-based breast reconstruction drive volume migration. United States outpatient facilities are capturing escalating procedure flows as payer reimbursement shifts favor site-of-service arbitrage.
- Specialty Clinics:Focused burn and wound care centers with dedicated biologic dressing formularies. Procurement committees in these settings unbundle contracts from hospital group purchasing organizations.
- Rehabilitation Facilities:Post-operative recovery and functional restoration following major reconstructive interventions. Integration with acute care networks determines referral patterns and device consignment arrangements.
Hospitals retain the highest acuity tier while ambulatory surgical centers expand most quickly into historically inpatient-dominated procedures.
Material Type:
Supply chain resilience and regulatory pathway complexity create divergent margin structures across sourcing categories.
- Biologics:Acellular dermal matrices and growth factor formulations derived from human or animal tissue. Integra LifeSciences leverages regenerative platforms across United States burn and breast reconstruction protocols.
- Synthetic Biomaterials:Engineered polymers and ceramic scaffolds with defined degradation profiles. REACH chemical safety compliance burdens extend European market entry timelines for novel biodegradable constructs.
- Autologous Tissue:Patient-derived flaps and grafts eliminating rejection risk but requiring donor site morbidity trade-offs. Microvascular anastomosis skill scarcity constrains United States free flap program expansion.
- Allografts:Cadaveric skin and amniotic membrane products dependent on tissue bank network stability. Procurement disruptions in United States cadaveric skin segments accelerate synthetic substitute development.
Biologics anchor the revenue base while synthetic biomaterials climb the fastest as 3D printing enables patient-specific scaffold fabrication.
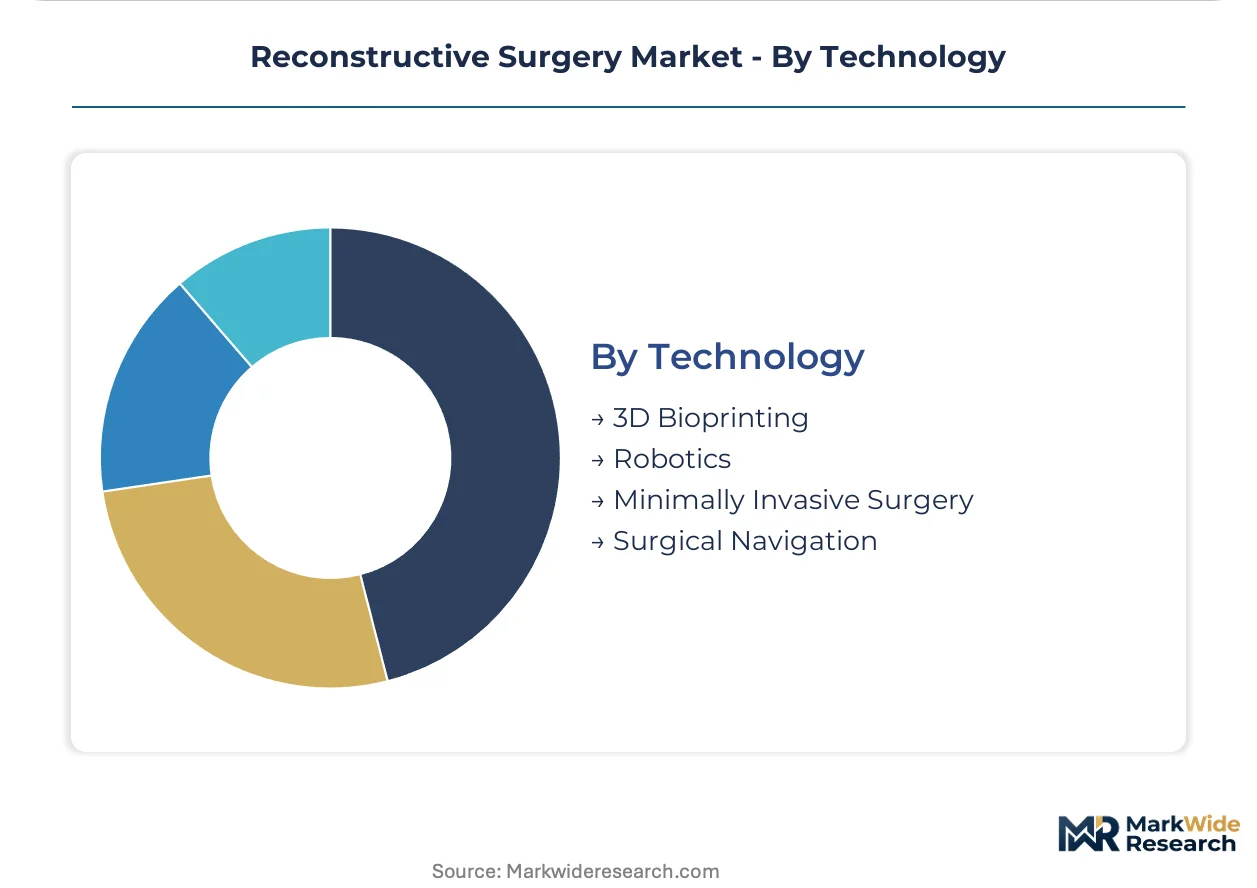
Technology:
Regulatory classification uncertainty and clinical validation timelines separate mature platforms from emerging capabilities approaching translation.
- 3D Bioprinting:Photocrosslinkable bioinks incorporating patient-derived cells for same-day tissue fabrication. FDA clearance pathway compression is collapsing development timelines from decade-long cycles to multi-year sprints.
- Robotics:Surgical systems enabling precision in microvascular anastomosis and bone preparation. South Korea's concentrated investment in robotic platforms is rewriting the competitive map for reconstructive surgery.
- Minimally Invasive Surgery:Endoscopic and percutaneous techniques reducing operative trauma and recovery duration. United States ASC adoption concentrates in tissue expansion and implant-based breast procedures.
- Surgical Navigation:Preoperative 3D modeling and intraoperative guidance for complex craniofacial and orthopedic reconstruction. Patient-specific instrumentation adoption is reducing operative time and revision rates in United States academic centers.
Robotics and surgical navigation anchor current procedural volume while 3D bioprinting represents the steepest expansion trajectory as vascularized constructs approach clinical translation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes reconstructive surgery capacity through ambulatory surgical centers at rates unmatched elsewhere, while South Korea and Germany channel demand through robotic surgical systems and academic medical centers respectively.
United States
FDA premarket notification pathways for 3D bioprinted grafts are compressing development timelines from decade-long cycles to multi-year sprints. The agency's Good Manufacturing Practice standards for human cells and tissues govern commercialization timelines. Greater Boston's academic medical centers pilot same-day bioprinting workflows for burn and breast reconstruction.
Germany
EMA convergence on Good Manufacturing Practice standards for human cells and tissues is streamlining cross-border product registration. The EU Medical Device Regulation explicitly captures cell-laden scaffolds as Class III devices. Academic centers in Baden-Württemberg leverage patient-specific instrumentation to reduce operative time in complex craniofacial cases.
South Korea
Concentrated investment in robotic surgical systems and biomaterial foundries is creating export-oriented manufacturing capacity. MFDS regulatory frameworks support fast-track pathways for orphan indication biomaterials. The Seoul Capital Area anchors production of magnetically actuated cell-laden hydrogels for minimally invasive tissue delivery.
India
CDSCO fast-track approval mechanisms for orphan indication biomaterials offer first-mover positioning for complex congenital defect repair products. The regulator's expedited pathways attract clinical trial investment. Maharashtra's specialty clinics unbundle contracts from hospital group purchasing organizations to secure direct biomaterial purchasing relationships.
United Kingdom
Post-MDR transition conformity requirements for synthetic biomaterials are reducing redundant testing costs for suppliers seeking multi-country European access. The Medicines and Healthcare products Regulatory Agency aligns with EMA standards. London's academic medical centers maintain dominant positions for free flap breast and craniofacial procedures requiring microvascular teams.
Reconstructive Surgery Market Competitive Environment
Capability concentration sits with specialized regenerative biologics developers; scale advantage sits with diversified orthopedic and surgical conglomerates. The market structures around three tiers: integrated health technology conglomerates with broad portfolio coverage, mid-cap specialists with proprietary biomaterial platforms, and emerging biofabrication startups approaching clinical translation. Consolidation pressure intensifies as FDA clearance pathway compression forces incumbents to accelerate regenerative platform investments or cede position. Dominant competitive moves include strategic partnerships between synthetic biomaterial suppliers and bioprinting ventures, plus site-specific clinical specialist deployment to bypass group purchasing organization channels.
Among diversified health technology conglomerates, Johnson & Johnson and Medtronic occupy positions spanning biologics and synthetic matrices. Zimmer Biomet anchors the orthopedic reconstruction tier with proprietary porous titanium constructs. Integra LifeSciences exemplifies the regenerative biologics specialist archetype, leveraging dermal regeneration platforms across burn and breast reconstruction protocols. These three represent distinct strategic postures: diversified portfolio coverage, orthopedic hardware dominance, and regenerative biologics depth.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Zimmer Biomet |
| Integra LifeSciences |
| B. Braun Melsungen AG |
| AbbVie |
| Siemens |
| KLS Martin Group |
| Baxter |
| Others |
Value Chain & Pricing Dynamics
Greater Boston's academic medical centers anchor North American bioprinted graft production, concentrating manufacturing capacity for patient-specific scaffolds and creating asymmetric pricing power for suppliers with FDA Master File documentation. This geographic concentration of advanced biomaterial foundries shapes downstream procurement negotiations, as hospital systems with dedicated reconstructive service lines leverage volume commitments to compress supplier margins.
Pricing Analysis
United States ASCs command price spreads of 15-25% below hospital inpatient rates for identical breast reconstruction procedures, driven by site-of-service reimbursement differentials and streamlined nursing protocols. Three-tier pricing structure across premium, standard, and economy levels stratifies by graft vascularization complexity and biologic sourcing pedigree, with cadaveric allografts carrying brand premiums over synthetic matrices. Cost compression in synthetic biomaterial tiers is intensifying because REACH compliance investments are being amortized across narrower European volumes. Price-sensitive independent ambulatory centers drive standard-tier demand, while academic medical centers with NIH funding access exhibit lowest sensitivity for premium bioprinted constructs.
Supply Chain Analysis
Export control regimes for dual-use bioprinting hardware limit flow of high-resolution tissue fabrication systems from Germany and the United States to certain jurisdictions, fragmenting equipment access across manufacturing zones. Supply concentrates in the United States, South Korea, and Germany for robotic surgical platforms, while cadaveric allograft sourcing draws from domestic tissue bank networks in each major market. Raw material dependencies include photocrosslinkable hydrogel precursors, clinical-grade titanium powder, and processed amniotic membrane. Single-source vulnerability characterizes the cadaveric skin segment, where procurement disruptions trigger rapid synthetic substitute adoption. Distribution runs through hospital procurement committees and GPO contracts, with direct manufacturer relationships gaining share in academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital systems with dedicated reconstructive service lines, as unbundling from GPO contracts accelerates and procurement committees gain direct purchasing authority over biomaterial selection.
For Market Incumbents: Build regulatory data moats through FDA Master File accumulation and EMA notified body relationships to delay biofabrication startup market entry. Accelerate backward integration into photocrosslinkable bioink precursor manufacturing to capture margin compression from specialty chemical suppliers. Defensive patent thickets around vascularization protocols represent critical leverage against emerging cell-laden hydrogel entrants. For New Entrants and Emerging Players: Pursue orphan indication positioning through CDSCO fast-track pathways in India and MFDS expedited mechanisms in South Korea, where regulatory friction for complex congenital defect products remains lowest. Underpenetrated demand for robotic-assisted microvascular anastomosis in Southeast Asian markets offers white-space expansion with lower competitive density. Go-to-market execution should anchor in site-specific clinical specialist deployment to bypass entrenched GPO channel relationships. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because FDA clearance pathway compression forces mid-cap biomaterial specialists into partnership or exit decisions within the analysis window. Acquisition targets should exhibit proprietary dermal regeneration platforms with established burn center relationships and MDR technical documentation. The signal to watch is EMA-FDA convergence on bioprinted product classification, which would trigger cross-border clinical trial investment and validate platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | 510(k) clearance for 3D bioprinted grafts collapses development timelines from decade-long cycles. |
| CE Marking Pathway | MDR Class III device classification for cell-laden scaffolds triggers notified body involvement in Europe. |
| Hospital System Partnership | Direct purchasing relationships with academic medical centers bypass GPO channel intermediaries. |
| Software Companion Development | Preoperative 3D modeling integration with patient-specific instrumentation reduces operative revision rates. |
| Reimbursement Strategy | Site-of-service arbitrage positioning captures ASC volume migration for streamlined tissue expansion. |
Study Parameters
Initial hypotheses were tested against primary input from reconstructive surgeons, hospital procurement managers, biomedical engineers, and GPO contracts specialists, and refined through secondary validation against FDA 510(k) filings, EMA MDR submissions, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up demand modeling triangulated with top-down market sizing across procedure volume estimates and material consumption rates.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning procedure type, material category, end-user facility tier, and technology platform maturity. CAGRs were derived from procedure volume trajectories and price evolution assumptions, incorporating inputs from tissue bank network capacity, robotic surgical system installation bases, and bioprinting platform clinical trial pipelines.
Sensitivities concentrate around FDA-EMA regulatory convergence timelines, bioprinted vascularization technical breakthroughs, and cadaveric allograft procurement stability. Material shifts in bioprinted product classification frameworks or REACH chemical safety enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Australia Cosmetic Surgery Market
Cosmetic Surgery
Spain Cosmetic Surgery Market