
 Rectal Catheters Market | 2026-2036
Rectal Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Rectal Catheters Market Analytics
Silicone is recalibrating rectal catheter economics as manufacturers phase out latex in favor of hypoallergenic alternatives with superior biocompatibility profiles. Medtronic leverages its diversified medtech infrastructure to sustain catheter supply chain reliability across acute and ambulatory channels. Coloplast anchors its position through specialized ostomy and continence portfolios that extend into rectal catheter adjacencies. Hollister Incorporated competes through focused wound and continence expertise that differentiates its clinical positioning.
Rectal catheters are flexible tubular devices, typically 12–24 French in diameter and 30–45 cm in length, designed for transanal decompression, medication delivery, or fecal diversion in patients with neurogenic bowel dysfunction or postoperative ileus. Disposable silicone intermittent catheters dominate hospital procurement due to infection control protocols and single-use economics, while home healthcare channels are driving fastest growth in continuous catheter configurations for chronic management. Fluid management applications command premium pricing relative to diagnostic procedures, reflecting the procedural complexity and reimbursement differentials in acute settings.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and market access costs for rectal catheter manufacturers. ISO 13485 quality management systems and biocompatibility testing under ISO 10993 govern material validation, with FDA enforcement of latex labeling requirements continuing to accelerate silicone conversions. Stakeholders must monitor evolving home healthcare reimbursement codes and decentralized care infrastructure investments that will determine volume allocation between institutional and community-based settings.
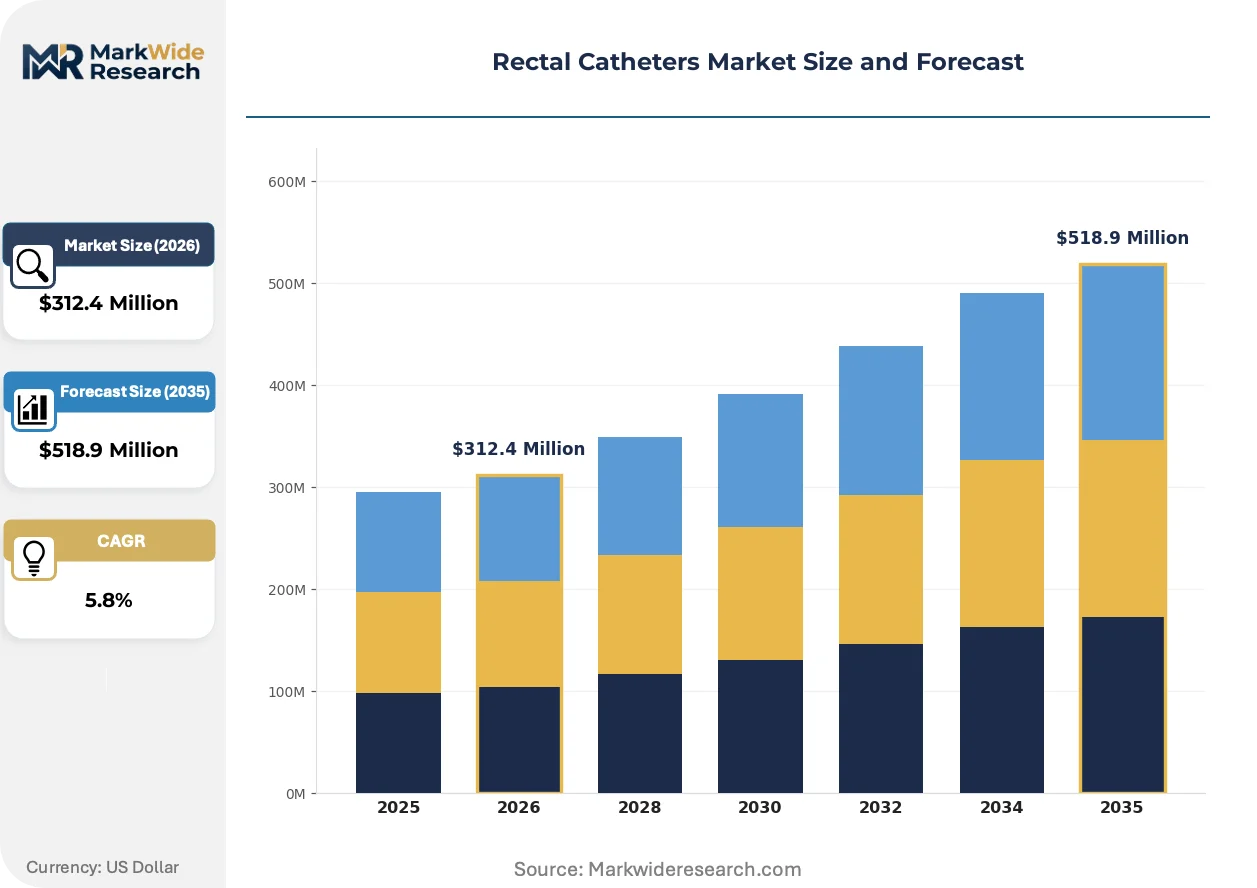
Market Dynamics
Silicone material conversions are restructuring rectal catheter supply economics as manufacturers absorb biocompatibility testing costs and revalidate production lines under tightened FDA and EU MDR pathways. This transition concentrates procurement power among converters with captive polymer compounding capabilities.
Growth Catalysts
- EU MDR conformity deadlines:European manufacturers accelerating silicone transitions ahead of 2027 recertification windows, creating replacement demand for legacy latex inventories.
- Home healthcare expansion:United States Medicare reimbursement clarity for chronic bowel management devices is shifting volume from acute to ambulatory channels.
- Aging demographics in Japan:METI-supported decentralized care infrastructure investments are embedding rectal catheters into community-based neurogenic bowel protocols.
Market Restraints
- Medical-grade silicone supply concentration:Three specialty chemical producers control 70% of biocompatible polymer feedstock, exposing converters to price volatility.
- ISO 10993-5 cytotoxicity testing bottlenecks:Contract laboratory capacity constraints are extending material validation timelines by 4-6 months.
- Reusable catheter substitution:Sterilizable silicone intermittent designs threaten disposable economics in cost-sensitive European hospital systems.
Strategic Opportunities
- Germany's Krankenhauszukunftsgesetz hospital reform:Outpatient procedure migration is opening ambulatory surgery center channels for procedure-specific catheter kits.
- Smart catheter convergence:Pressure-sensing lumens combined with wireless telemetry enable real-time intraluminal monitoring for ICU applications.
- Direct-to-patient subscription models:Chronic users in United States commercial insurance pools are bypassing durable medical equipment intermediaries.
Industry Challenges
- Polymer science talent scarcity:Medical device manufacturers compete with semiconductor and battery sectors for silicone formulation chemists.
- Legacy ERP integration friction:Track-and-trace requirements under FDA Unique Device Identification rules strain mid-tier converters with outdated inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rectal Catheters Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intermittent Catheters, Continuous Catheters, Inflatable Catheters, Disposable Catheters Material: Latex, PVC, Silicone, Polyolefin Application: Diagnostic Procedures, Surgical Applications, Fluid Management, Patient Care End User: Hospitals, Clinics, Nursing Homes, Home Healthcare |
| Companies Covered | Medtronic, Coloplast, Hollister Incorporated, Boston Scientific Corporation, B. Braun Melsungen AG, Teleflex Incorporated, ConvaTec, Cook Medical, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rectal Catheters Market Evolving Landscape
Rectal catheter development is pivoting from commodity tube production toward integrated procedure ecosystems. Material science, regulatory data infrastructure, and patient-administered care models are converging to redefine value capture points.
Silicone compounding with platinum-cured elastomers is modularizing catheter architecture into interchangeable proximal connector, shaft, and distal tip subassemblies. Acute care procurement teams in United States health systems are specifying these configurations to reduce SKU complexity and sterilization validation burdens. This standardization is compressing supplier qualification cycles and enabling dual-source strategies for critical components.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to rebuild clinical evidence portfolios for legacy latex devices facing reclassification. German notified bodies are imposing additional biocompatibility endpoints for prolonged mucosal contact claims. Smaller converters without dedicated regulatory affairs functions are exiting the European market, consolidating share among firms with established quality management systems.
Patients with spinal cord injuries are self-directing catheter selection through peer-supported digital channels rather than relying exclusively on clinician prescription. United States veterans affairs facilities and specialized neurogenic bowel clinics are responding with standardized assessment protocols that incorporate user-reported outcome measures. This behavioral shift is elevating comfort and discretion attributes alongside clinical efficacy in purchasing decisions.
Rectal Catheters Market Segmentation
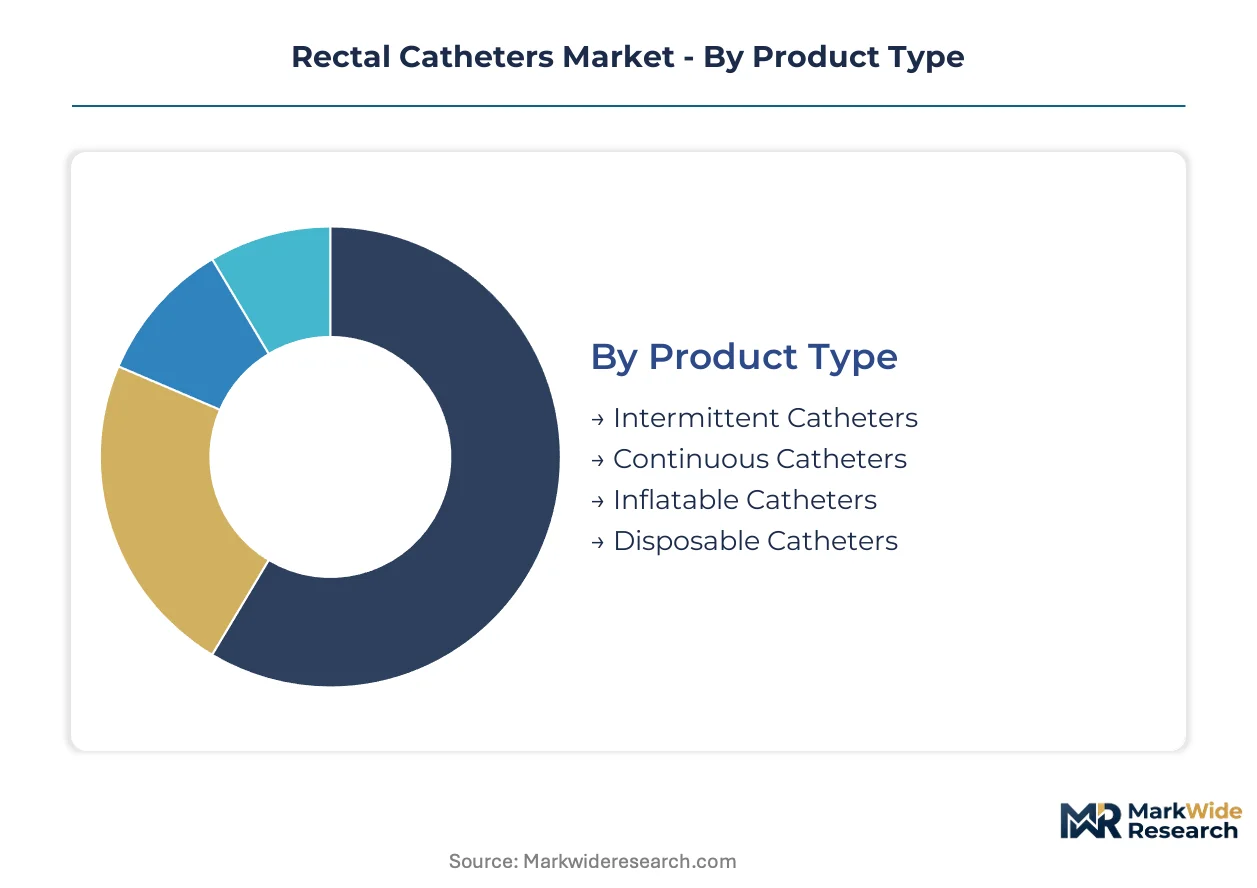
Rectal catheter purchasing decisions fragment across clinical workflow requirements, material safety profiles, and care setting economics. Manufacturers must align specifications with infection control protocols, reimbursement pathways, and patient self-administration capabilities to capture volume across institutional and ambulatory channels.
Product Type:
Catheter architecture determines usage frequency, sterilization burden, and reimbursement coding complexity across acute and chronic care pathways.
- Intermittent Catheters:Single-use designs with 12–24 French diameter range dominate hospital procurement for neurogenic bowel dysfunction protocols. United States acute care systems specify these for spinal cord injury units under Medicare Severity-Diagnosis Related Group reimbursement frameworks.
- Continuous Catheters:Indwelling configurations with drainage collection systems anchor home healthcare expansion for chronic fecal diversion. Medicare home health benefit clarity is accelerating ambulatory channel volume for patients with postoperative ileus or terminal colorectal conditions.
- Inflatable Catheters:Balloon-retention mechanisms secure positioning for extended medication delivery or decompression procedures.
- Disposable Catheters:Pre-sterilized single-use economics align with FDA infection control guidelines and EU MDR single-patient use requirements.
Intermittent catheters lead on scale; continuous catheters lead on momentum.
Material:
Polymer selection governs biocompatibility validation costs, allergen liability exposure, and manufacturing process economics under tightened regulatory pathways.
- Silicone:Platinum-cured elastomers with ISO 10993-5 cytotoxicity clearance are displacing legacy alternatives. FDA latex labeling enforcement and EU MDR prolonged mucosal contact claims are concentrating procurement among converters with captive compounding capabilities.
- Latex:Natural rubber formulations face accelerating phase-out due to Type I hypersensitivity liability and reclassification burdens under EU MDR Article 10 technical documentation requirements.
- PVC:Plasticized polyvinyl chloride retains cost-sensitive hospital share where DEHP plasticizer concerns remain secondary to procurement budget constraints.
- Polyolefin:Thermoplastic olefin alternatives offer solvent bonding advantages for complex multi-lumen catheter architectures.
Silicone commands premium positioning; latex retains residual volume in cost-constrained systems.
Application:
Procedure complexity and reimbursement differentials stratify pricing power across diagnostic, therapeutic, and chronic management use cases.
- Fluid Management:Decompression and drainage procedures in ICU settings command premium pricing relative to standard diagnostic applications. Acute care procurement teams specify procedure-specific kits bundling catheters with collection systems.
- Diagnostic Procedures:Contrast delivery and manometry applications require pressure-rated lumens with radiopaque markers. Outpatient migration under Germany's Krankenhauszukunftsgesetz reform is shifting volume to ambulatory surgery centers.
- Surgical Applications:Intraoperative fecal diversion and anastomotic protection drive sterile kit demand in operating room supply chains.
- Patient Care:Palliative and chronic bowel management protocols embed catheters into community-based care models with user-reported outcome assessment requirements.
Fluid management captures margin concentration; patient care demonstrates the steepest expansion trajectory.
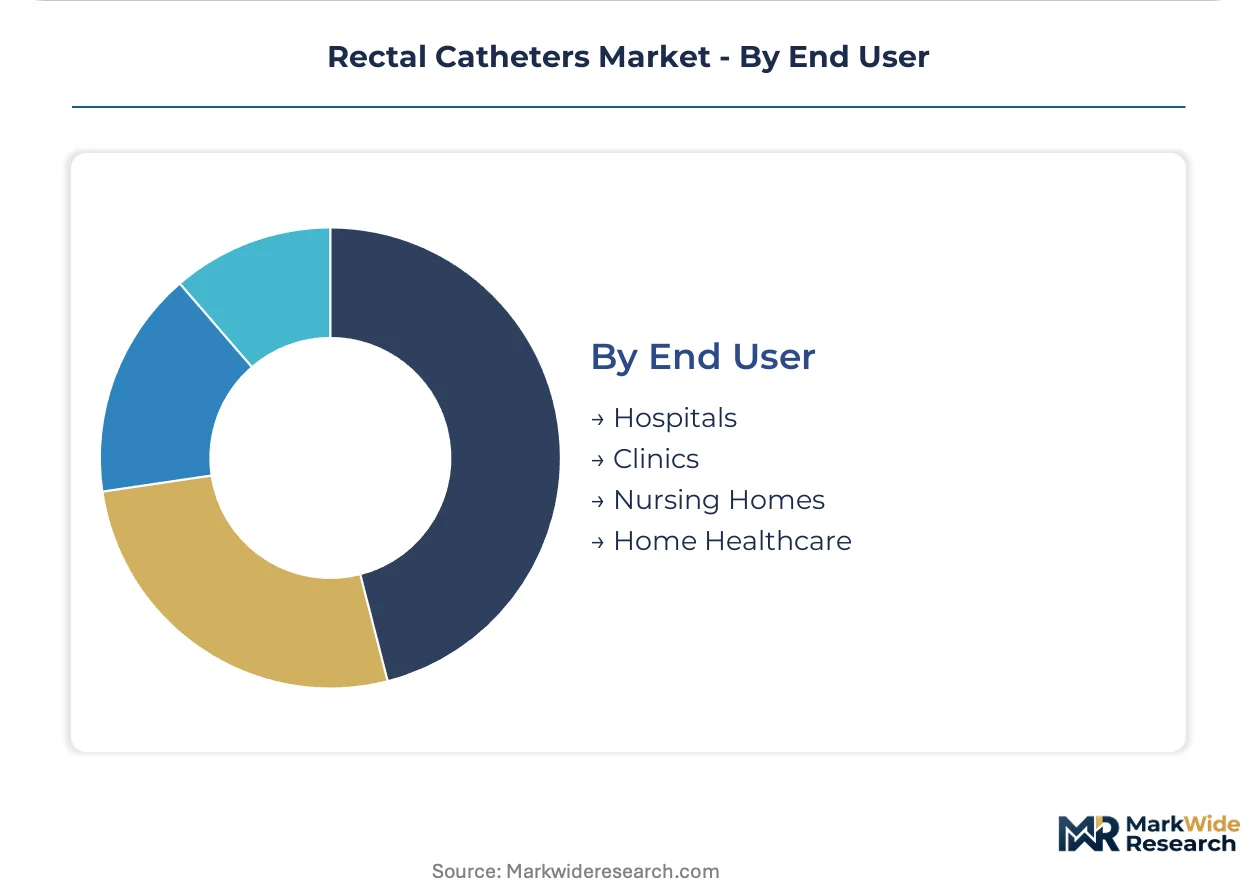
End User:
Channel economics and reimbursement infrastructure determine volume allocation between institutional procurement and direct-to-patient distribution models.
- Hospitals:Integrated delivery networks consolidate catheter purchasing through standardized formularies with infection control committee oversight. United States health systems specify silicone intermittent designs under value-based purchasing quality metrics.
- Home Healthcare:Medicare durable medical equipment reimbursement clarity and veterans affairs centralized procurement are embedding catheters into chronic disease management pathways. Direct-to-patient subscription models are bypassing traditional distributor intermediaries.
- Clinics:Specialty gastroenterology and urology practices drive procedure-specific kit demand with preference for pre-assembled configurations.
- Nursing Homes:Long-term care facility procurement prioritizes cost containment over material premiumization, retaining PVC and latex share despite clinical migration trends.
Hospitals anchor procurement volume; home healthcare channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors medical device manufacturing infrastructure that supports catheter supply chains serving North American acute care networks. Regional procurement patterns diverge based on reimbursement clarity, regulatory pathway maturity, and decentralized care infrastructure investments.
United States
Medicare durable medical equipment reimbursement codes for chronic bowel management devices are shifting procurement volume toward home healthcare channels. FDA 510(k) clearance pathways and Unique Device Identification rules govern market access timelines for silicone catheter conversions. The Minneapolis-St. Paul corridor concentrates catheter manufacturing infrastructure with integrated polymer compounding capabilities.
Germany
Krankenhauszukunftsgesetz hospital reform is migrating outpatient procedures to ambulatory surgery centers, opening procedure-specific kit demand. EU MDR Article 10 technical documentation requirements and notified body recertification deadlines are accelerating silicone transitions ahead of 2027 windows. The Rhine-Ruhr industrial cluster hosts specialized polymer converters with captive medical-grade silicone supply chains.
Japan
METI-supported decentralized care infrastructure investments are embedding rectal catheters into community-based neurogenic bowel protocols for aging populations. PMDA regulatory frameworks align with international ISO 13485 quality management standards for material validation. The Kanto region around Tokyo concentrates medical device distribution networks serving specialized rehabilitation facilities.
United Kingdom
NHS supply chain consolidation through standardized formularies is concentrating procurement among converters with established quality management systems. MHRA post-Brexit regulatory alignment with EU MDR requirements maintains biocompatibility testing standards for prolonged mucosal contact devices. The Midlands manufacturing corridor hosts polymer processing facilities serving continental European export markets.
Rectal Catheters Market Competitive Landscape
Silicone material transitions dominate the current landscape as manufacturers absorb biocompatibility testing costs and revalidate production lines under tightened regulatory pathways. The vendor base concentrates among diversified medtech conglomerates with captive polymer compounding capabilities and specialized continence care specialists with focused clinical positioning. Three strategic archetypes emerge: integrated hospital supply conglomerates, specialized ostomy and continence pure-plays, and diversified critical care device manufacturers. Competitive moves center on M&A for polymer science capabilities and strategic partnerships for EU MDR technical documentation support.
Among diversified medtech conglomerates, Medtronic, Coloplast, and Hollister Incorporated occupy distinct positioning archetypes. Medtronic exemplifies the scale-driven integrated supply model with diversified infrastructure spanning acute and ambulatory channels. Coloplast anchors the specialized continence and ostomy portfolio approach with clinical adjacency extension into rectal catheter applications. Hollister Incorporated represents focused wound and continence expertise that differentiates positioning through dedicated clinical specialization rather than scale breadth.
| Leading Market Players |
|---|
| Medtronic |
| Coloplast |
| Hollister Incorporated |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| ConvaTec |
| Cook Medical |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
EU MDR Article 10 prolonged mucosal contact claims gate qualified silicone supply and premium-tier pricing access for rectal catheter manufacturers seeking European market entry. FDA latex labeling enforcement and ISO 10993-5 cytotoxicity testing requirements simultaneously constrain converter qualification pools in the United States, concentrating procurement power among compounders with captive polymer capabilities.
Pricing Analysis
Medical-grade silicone feedstock cost pass-through dominates rectal catheter pricing dynamics as three specialty chemical producers control biocompatible polymer supply. Three-tier pricing structure across platinum-cured silicone premium, standard-grade silicone mid-market, and residual PVC economy segments reflects certification grade and volume scale differentiation. Pricing pressure stems from contract laboratory testing bottlenecks extending material validation timelines. Home healthcare channels exhibit highest price sensitivity due to Medicare reimbursement caps, while ICU fluid management applications maintain lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States health system procurement committees and German hospital networks drive multi-supplier qualification strategies among catheter converters. Manufacturing concentrates in the United States, Germany, and Japan where medical-grade silicone compounding infrastructure and FDA 510(k) clearance capabilities anchor production. Raw material dependencies rest on platinum-cured elastomers, radiopaque marker additives, and specialized connector moldings. Single-source vulnerability concentrates in medical-grade silicone feedstock where three producers dominate. Distribution runs through hospital GPO contracts, durable medical equipment intermediaries, and emerging direct-to-patient subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as home healthcare expansion shifts demand toward premium silicone specifications with superior biocompatibility profiles and user-reported comfort attributes.
For Market Incumbents: Extend regulatory affairs capabilities ahead of EU MDR recertification deadlines to capture share from exiting smaller converters lacking dedicated quality management systems. Defend against reusable catheter substitution threats in European hospital systems by embedding single-use economics into procedure kit bundling. Prioritize backward integration into captive silicone compounding to secure feedstock access against polymer science talent scarcity. For New Entrants and Emerging Players: Direct-to-patient digital channels offer the lowest friction entry path for chronic bowel management subscription models bypassing traditional durable medical equipment intermediaries. Target United States veterans affairs facilities and specialized neurogenic bowel clinics with standardized assessment protocols incorporating user-reported outcome measures. Leverage peer-supported digital communities for spinal cord injury patients to build brand recognition before clinical procurement engagement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier converters with established ISO 13485 quality management systems but lacking EU MDR technical documentation capabilities. Long-term viability over the next decade hinges on silicone material transition completion and home healthcare channel positioning. Watch Medicare durable medical equipment reimbursement code expansions as the primary inflection indicator for ambulatory volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Rebuild | Notified body recertification deadlines force legacy latex device reclassification investments ahead of compliance windows. |
| Silicone Compounding Backward Integration | Captive polymer production insulates converters from medical-grade silicone supply concentration and price volatility. |
| Direct-to-Patient Subscription Launch | Commercial insurance pool penetration bypasses durable medical equipment intermediaries for chronic user retention. |
| Smart Catheter Pressure-Sensing Development | Wireless telemetry integration enables real-time intraluminal monitoring for ICU premium pricing capture. |
| Hospital GPO Partnership Expansion | Integrated delivery network formulary inclusion secures standardized procurement under value-based purchasing metrics. |
Research Methodology
Bottom-up home healthcare and acute care channel modeling reconciled against top-down medical-grade silicone converter tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and home healthcare procurement directors combined with secondary validation from FDA 510(k) clearance databases, CMS Medicare reimbursement code filings, EU MDR notified body documentation, and hospital supply chain procurement records. Triangulation across bottom-up volume builds and top-down polymer feedstock demand estimates ensures analytical consistency.
Input-output matrices mapping catheter production volumes against medical-grade silicone consumption patterns, reimbursement code utilization rates, and channel-specific pricing differentials structure the forecast framework. Segmentation dimensions span product architecture, material composition, application complexity, and end-user channel across the projection horizon. CAGRs derive from procedure volume elasticity to aging demographic trends, reimbursement pathway expansion rates, and material substitution velocity. Forecast inputs incorporate ISO 10993 testing timeline bottlenecks and EU MDR recertification deadline clustering effects.
Medical-grade silicone supply disruption, reimbursement code revision delays, and reusable catheter technology advancement are the dominant revision risks to modeled outputs. Deviation in Medicare durable medical equipment benefit expansion timing would shift the home healthcare volume outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Nasal Cannula Market
Medical Devices
Global Medical Composite Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Band Ligators Market
Medical Devices
Deflectable Catheters Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Spinal Traction Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Uterine Fibroid Embolization Devices Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Elbow Fixators Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Global Otoscopes Market
Medical Devices
Contact Lenses Market