
 IV Therapy and Vein Access Devices Market | 2026-2036
IV Therapy and Vein Access Devices Market Size, Share, and Industry Trends Forecast 2026-2036
IV Therapy and Vein Access Devices Market Outlook
Polyurethane is decoupling from traditional PVC in mid-tier catheter construction, reducing thrombogenicity risks while preserving flexibility. Becton, Dickinson and Company leverages integrated manufacturing across catheter and infusion pump lines. Terumo Corporation anchors its position through precision extrusion capabilities in Japan. ICU Medical, Inc. specializes in closed-system transfer devices that limit clinician exposure to hazardous drugs.
IV therapy and vein access devices comprise sterile instruments for vascular cannulation and controlled fluid administration, typically manufactured via insert molding of medical-grade polymers with lumen diameters ranging from 14 to 27 gauge for peripheral applications. These devices deliver pharmaceuticals, parenteral nutrition, and blood products directly into the circulatory system. Peripheral catheters dominate hospital procurement volumes due to standardized insertion protocols and lower per-procedure cost, while smart infusion devices capture disproportionate margin pools through software-integrated dose-error reduction. Ultrasound guidance represents the fastest-expanding technology segment as vascular access teams adopt real-time visualization to reduce first-attempt failure rates in patients with difficult venous anatomy.
FDA enforces 510(k) clearance and quality system regulation for all vascular access devices sold in the United States, while the EU Medical Device Regulation mandates unique device identifiers and strengthened post-market surveillance across European Economic Area member states. ISO 10555 sets dimensional and performance benchmarks for intravascular catheters that manufacturers must meet for market access in multiple jurisdictions. Stakeholders must weigh capital deployment toward needle-free connector ecosystems against the operational drag of retraining nursing staff on new protocols.
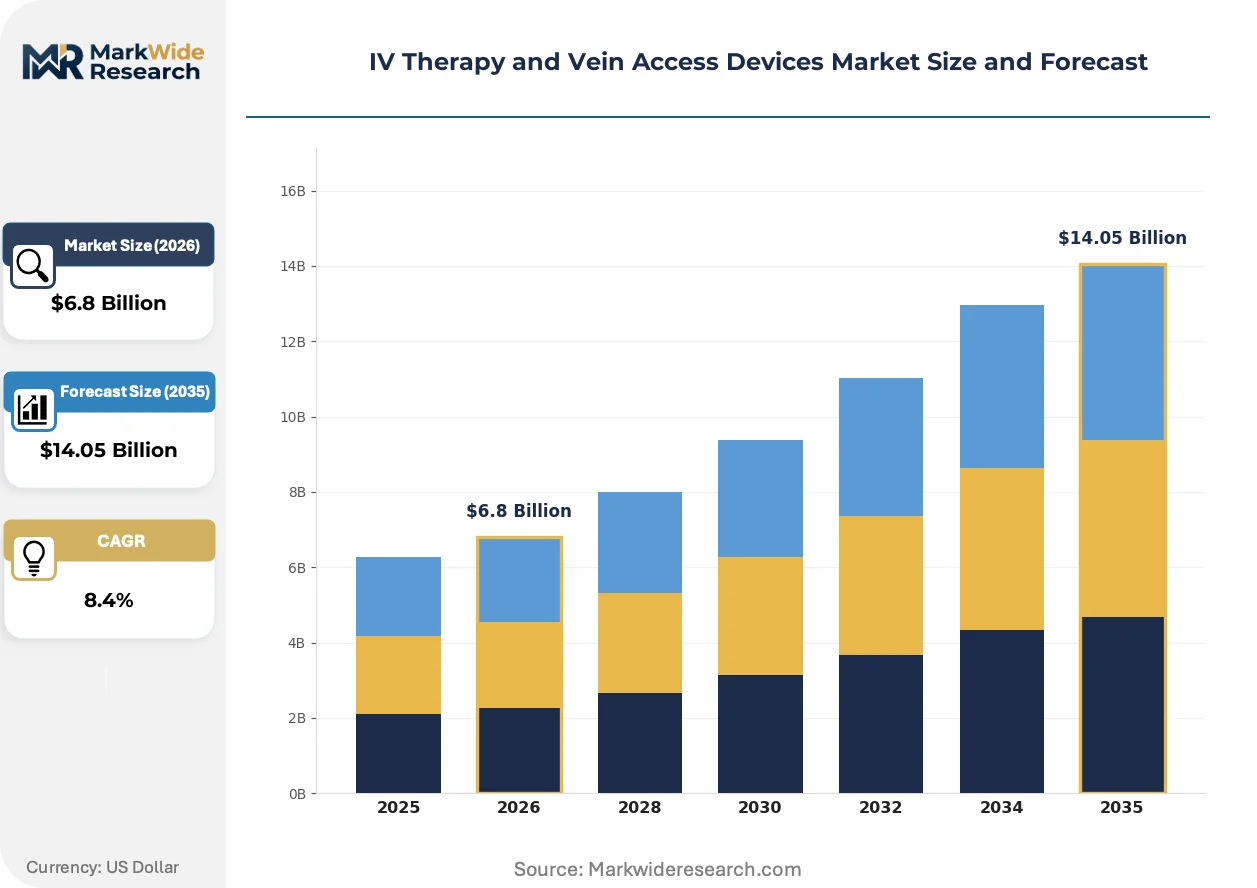
Market Dynamics
Hospital systems are consolidating vascular access procurement around closed-system transfer devices and ultrasound-guided insertion protocols, compressing vendor margins while elevating technical service requirements.
Growth Catalysts
- EU MDR traceability mandates:Device serialization requirements are accelerating replacement cycles for legacy catheter inventories across German and French hospital networks.
- Oncology infusion expansion:Peripheral catheter deployment in chemotherapy wards is rising as outpatient protocols extend treatment duration.
- Polyurethane material substitution:Thrombogenicity reduction in mid-tier constructions is expanding addressable patient populations with compromised vascular health.
Market Restraints
- Medical-grade polymer feedstock volatility:Polyurethane resin pricing swings are compressing gross margins for extrusion-dependent manufacturers.
- 510(k) clearance timelines:FDA review backlogs for novel connector designs are extending product launch windows by 8-14 months.
- Needle-free connector standardization gaps:Incompatible proprietary designs across Becton Dickinson, ICU Medical, and Terumo systems force hospitals into single-vendor lock-in.
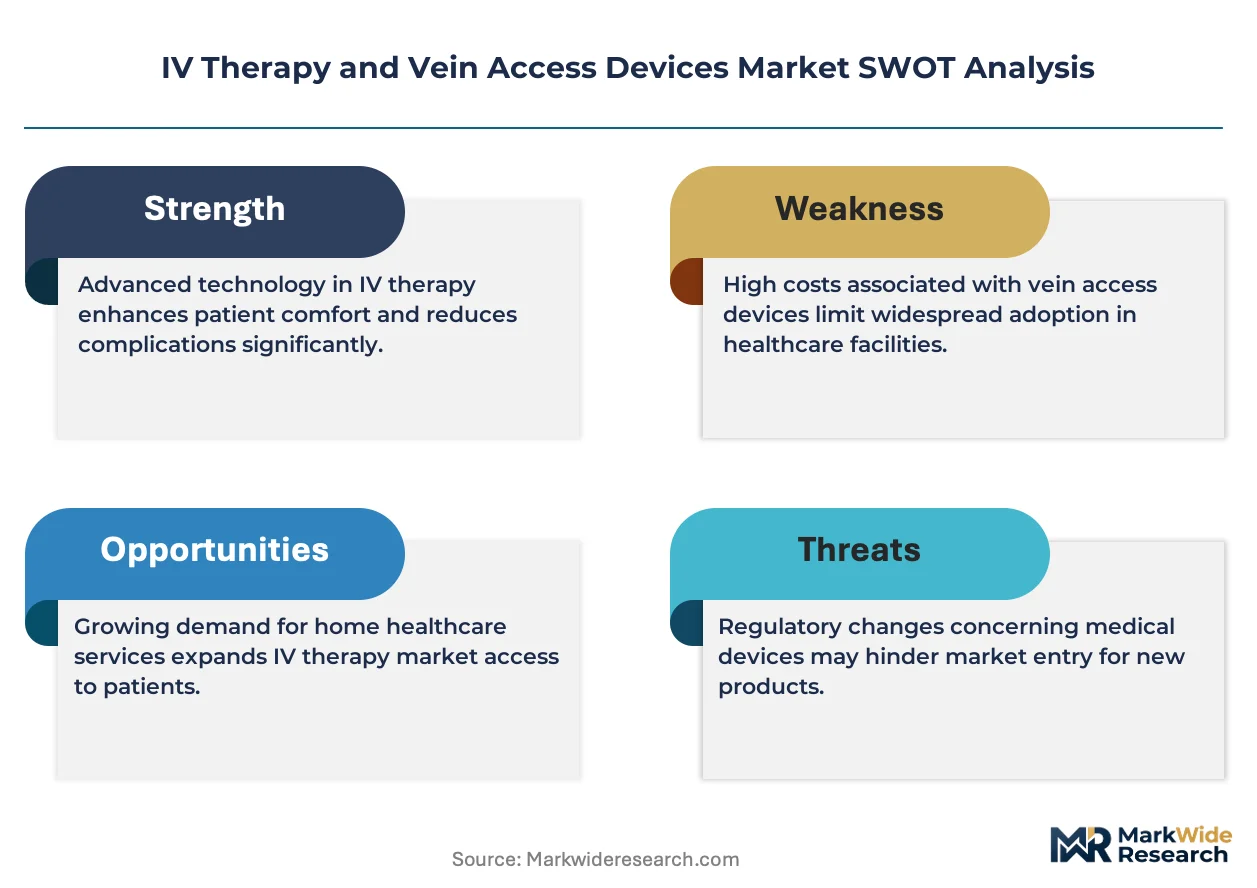
Strategic Opportunities
- Home infusion therapy expansion:Medicare reimbursement shifts for outpatient parenteral nutrition are creating demand for patient-portable infusion pumps in the United States.
- Smart pump-EMR convergence:Dose-error reduction software integrated with Epic and Cerner systems is commanding premium positioning in tertiary care centers.
- Japan's aging demographic tailwind:Chronic disease prevalence among patients over 75 is sustaining catheterization volumes in Tokyo and Osaka metropolitan hospital systems.
Industry Challenges
- Vascular access specialist shortages:PICC line certification programs are failing to match insertion volume growth in US academic medical centers.
- Legacy pump fleet integration:Software updates for decade-old infusion devices are creating cybersecurity vulnerabilities and FDA compliance exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IV Therapy and Vein Access Devices Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peripheral Catheters, Central Venous Catheters, Vascular Access Ports, Infusion Pumps End User: Hospitals, Clinics, Homecare Settings, Ambulatory Surgical Centers Technology: Needle Free Systems, Ultrasound Guidance, Smart Infusion Devices, Traditional Infusion Systems Application: Oncology, Pain Management, Antibiotic Therapy, Hydration Therapy |
| Companies Covered | Becton, Dickinson and Company, Teleflex Incorporated, ICU Medical, Inc., B. Braun SE, Medtronic, Terumo Corporation, AngioDynamics, Cook Medical, Fresenius Medical Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IV Therapy and Vein Access Devices Market Strategic Shifts
Real-time visualization technologies and closed-system drug handling are converging to reshape catheter placement protocols and clinician safety standards across tertiary care networks.
Ultrasound guidance systems are integrating with electromagnetic needle tracking to reduce first-attempt failure rates in patients with obesity or prior chemotherapy-induced venous damage. Vascular access teams at US academic medical centers are adopting these platforms at replacement cycle points. The technology is integrating peripheral catheter placement into standardized protocols previously reserved for central line specialists.
FDA's updated 510(k) sterility validation requirements for needle-free connectors are forcing manufacturers toward gamma-irradiated packaging and accelerated aging studies. The industrial consequence is elevated R&D spend for mid-tier catheter producers lacking in-house sterilization infrastructure. European manufacturers with CE marking under MDR Annex IX are responding faster than US counterparts due to prior experience with notified body technical documentation.
Hospital procurement committees are consolidating vendor relationships around single-source contracts bundling catheters, pumps, and informatics software. Group purchasing organizations are displacing individual hospital negotiations with multi-year enterprise agreements. This concentration is most visible in the United States, where Premier and Vizient networks cover over 4,000 member facilities.
IV Therapy and Vein Access Devices Market Segmentation
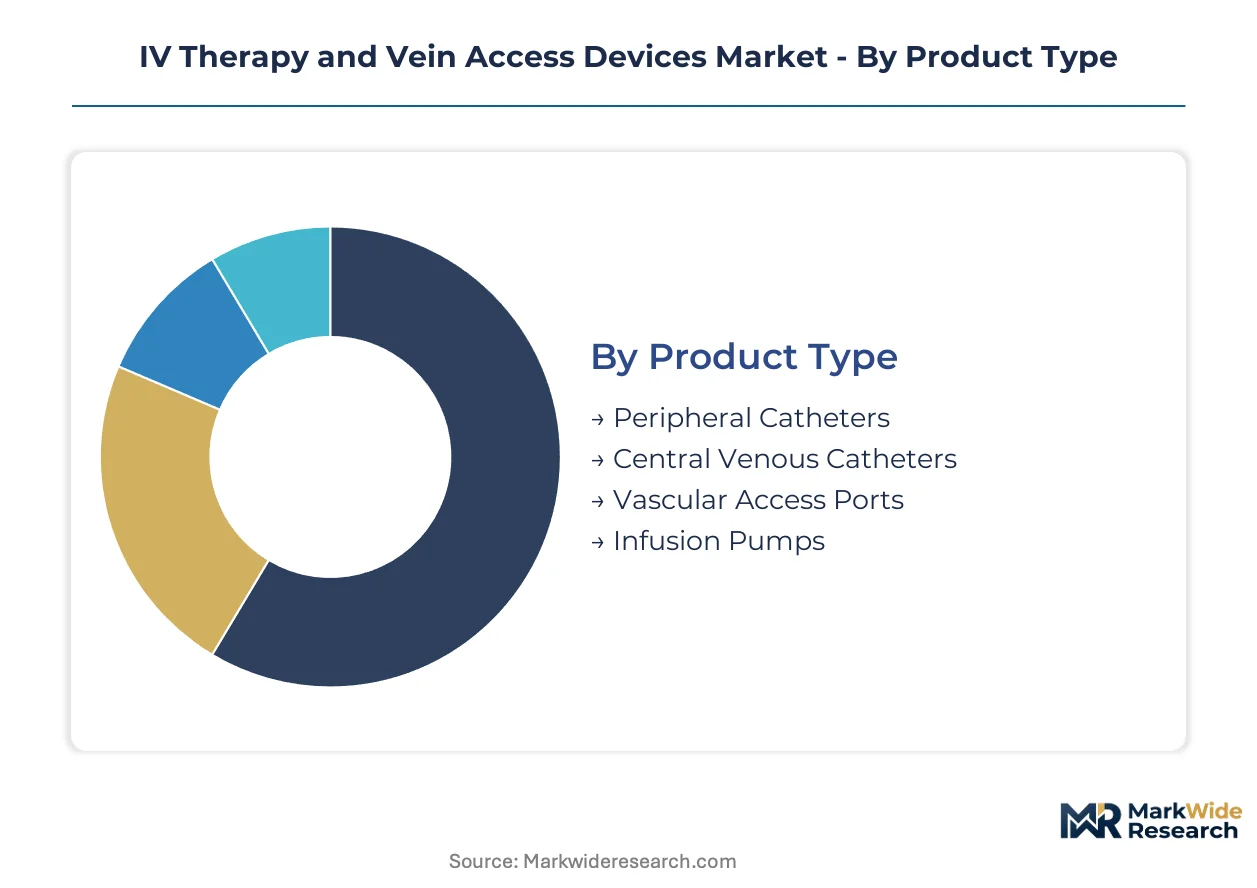
Catheter construction materials, insertion protocols, and care settings fragment procurement decisions across hospital systems. Each segmentation axis reveals distinct margin structures and compliance requirements that reshape vendor positioning.
Product Type:
Material composition and insertion depth define clinical utility and reimbursement pathways.
- Peripheral Catheters:Short-term vascular access devices constructed from polyurethane or PVC with 14-27 gauge lumens. Hospital oncology wards in the United States are expanding deployment volumes as outpatient chemotherapy protocols extend treatment duration, though thrombogenicity concerns limit use in compromised vasculature.
- Central Venous Catheters:Long-dwell devices terminating in the superior vena cava for high-osmolarity infusions. Tertiary care centers in Germany are consolidating procurement around antimicrobial-impregnated constructions to reduce bloodstream infection rates and associated EU MDR surveillance reporting.
- Vascular Access Ports:Fully implantable reservoir systems for intermittent long-term access.
- Infusion Pumps:Electromechanical or elastomeric devices for controlled flow delivery.
Mature deployment sits with Peripheral Catheters. Newer deployment is concentrated in Vascular Access Ports.
End User:
Facility infrastructure and reimbursement models determine device sophistication and service requirements.
- Hospitals:Acute care institutions with vascular access teams and sterile processing capabilities. United States academic medical centers are absorbing the fastest volume growth as PICC line specialization expands beyond interventional radiology into nursing-led placement protocols.
- Homecare Settings:Patient-residential environments requiring portable pump systems and simplified catheter maintenance. Medicare reimbursement shifts for outpatient parenteral nutrition are accelerating demand for patient-operated infusion devices across metropolitan regions.
- Clinics:Outpatient facilities with limited sterile processing infrastructure.
- Ambulatory Surgical Centers:Same-day procedure venues with rapid turnover requirements.
Volume concentrates in Hospitals. Margin expansion is climbing the fastest in Homecare Settings.
Technology:
Visualization and connectivity features reshape insertion protocols and error-reduction capabilities.
- Ultrasound Guidance:Real-time vascular imaging systems with linear array probes. Vascular access teams at US academic medical centers are adopting these platforms at replacement cycle points to reduce first-attempt failure rates in patients with obesity or prior chemotherapy-induced venous damage.
- Smart Infusion Devices:Software-integrated pumps with dose-error reduction and EMR connectivity. Tertiary care networks integrating Epic and Cerner systems are commanding premium positioning for these devices through closed-loop medication administration.
- Needle Free Systems:Mechanical connectors eliminating sharp exposure during line access.
- Traditional Infusion Systems:Gravity-dependent or basic mechanical flow control without electronic safeguards.
Standardized deployment sits with Traditional Infusion Systems. Technology migration is gaining share fastest in Smart Infusion Devices.
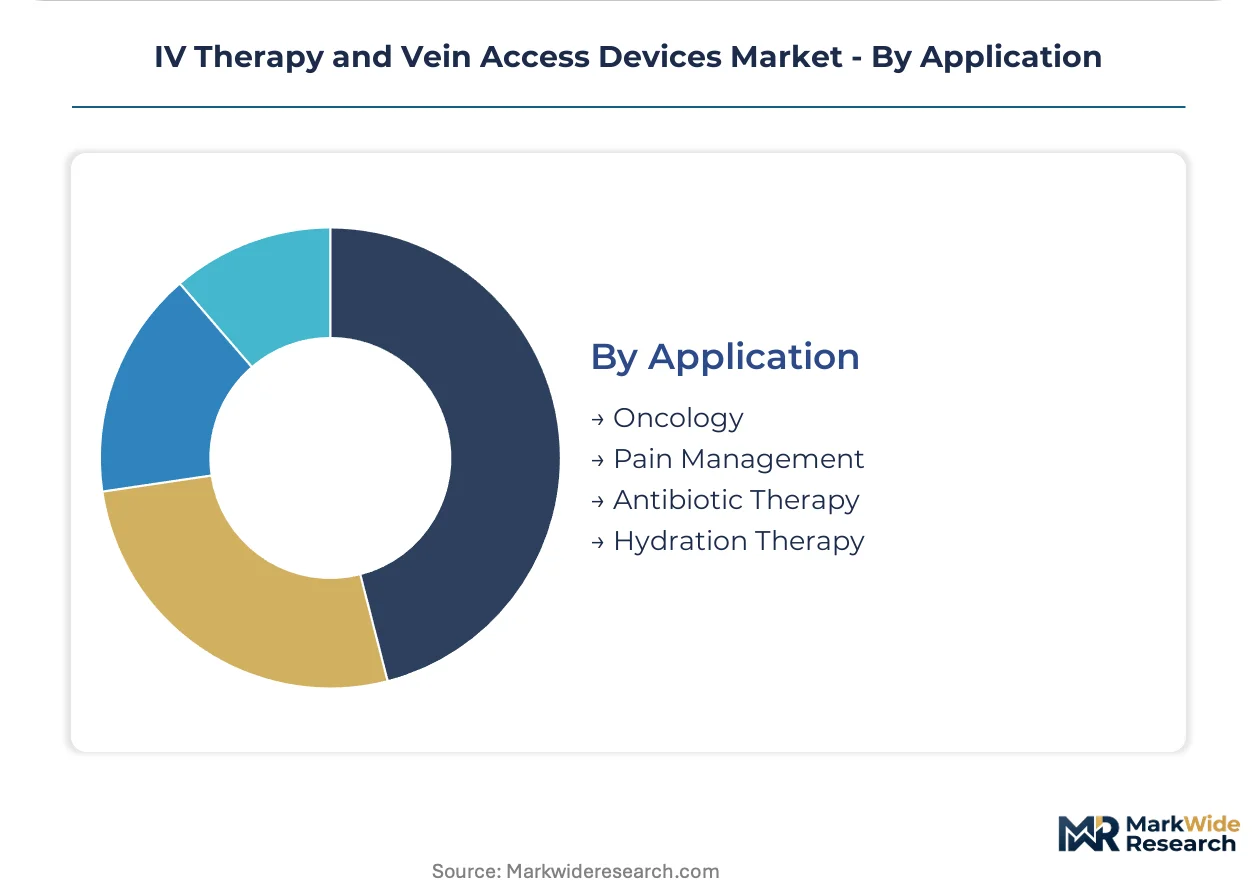
Application:
Therapeutic category dictates catheter dwell time, material compatibility, and handling precautions.
- Oncology:Chemotherapy administration requiring closed-system transfer to limit clinician exposure to hazardous drugs. ICU Medical's specialized connectors are capturing procurement share as US hospital networks consolidate around single-vendor safety protocols.
- Pain Management:Continuous or patient-controlled analgesic delivery via epidural or peripheral nerve catheters. Ambulatory surgical centers in Japan are expanding elastomeric pump deployment for post-discharge pain control in aging surgical populations.
- Antibiotic Therapy:Extended-duration antimicrobial infusion for resistant infections.
- Hydration Therapy:Fluid resuscitation and maintenance in acute or home settings.
Established volume sits with Hydration Therapy. Protocol expansion is expanding most quickly in Oncology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement volumes concentrate in the United States, Germany, and Japan, where aging patient populations and chronic disease management sustain catheterization demand. Regulatory divergence between FDA sterility mandates and EU MDR traceability rules is fragmenting vendor compliance strategies across these markets.
United States
Oncology infusion expansion and home parenteral nutrition reimbursement shifts drive peripheral catheter deployment. FDA enforces 510(k) clearance and quality system regulation for all vascular access devices. Academic medical centers in Boston and New York absorb the fastest PICC line volume growth as nursing-led placement protocols expand beyond interventional radiology.
Germany
EU MDR device traceability rules accelerate replacement cycles for legacy catheter inventories across hospital networks. B. Braun SE and Fresenius Medical Care anchor domestic manufacturing with integrated sterilization infrastructure. Tertiary care centers in Munich and Hamburg consolidate procurement around antimicrobial-impregnated central venous constructions to reduce bloodstream infection surveillance reporting.
Japan
Chronic disease prevalence among patients over 75 sustains catheterization volumes in metropolitan hospital systems. PMDA oversees medical device approvals under METI-coordinated standards harmonization. Tokyo and Osaka vascular access teams adopt ultrasound-guided insertion platforms at replacement cycle points to reduce first-attempt failure rates in aging surgical populations.
United Kingdom
NHS procurement consolidation around closed-system transfer devices compresses vendor margins while elevating technical service requirements. MHRA enforces UKCA marking and post-Brexit regulatory alignment with retained EU MDR provisions. London and Manchester hospital networks drive smart pump-EMR convergence through Epic and Cerner integration mandates.
India
Expanding private hospital infrastructure and medical tourism create demand for mid-tier polyurethane catheter constructions. CDSCO regulates medical device imports and domestic manufacturing under Drugs and Cosmetics Act provisions. Delhi-NCR and Maharashtra clusters attract contract manufacturing investment from multinational suppliers seeking cost-competitive extrusion capacity.
IV Therapy and Vein Access Devices Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated device-pump vendors commanding premium positioning in tertiary care while extrusion-focused suppliers serve cost-sensitive procurement tiers. Market structure tilts toward consolidation at the top through group purchasing organization bundling, with mid-tier producers facing margin compression from polymer feedstock volatility. Three archetypes dominate: diversified medical technology conglomerates with catheter-infusion pump integration, precision polymer extrusion specialists, and closed-system safety device innovators. Competitive dynamics center on M&A-driven portfolio expansion and strategic partnerships for EMR connectivity software.
Within the diversified conglomerate tier, Becton, Dickinson and Company and Medtronic occupy positions defined by integrated manufacturing breadth across catheter and infusion pump lines. Terumo Corporation represents the precision extrusion archetype, anchoring Japanese domestic supply with specialized polymer processing capabilities. ICU Medical, Inc. exemplifies the closed-system safety specialist model, limiting clinician exposure to hazardous drugs through proprietary connector designs. These three companies collectively illustrate how geographic origin and structural focus determine competitive positioning in vendor consolidation environments.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| ICU Medical, Inc. |
| B. Braun SE |
| Medtronic |
| Terumo Corporation |
| AngioDynamics |
| Cook Medical |
| Fresenius Medical Care |
| Others |
Value Chain & Pricing Dynamics
Polyurethane resin feedstock from German and Japanese petrochemical complexes flows through three-tier pricing structures across premium, standard, and economy catheter constructions, with antimicrobial-impregnated central venous devices commanding spreads over basic peripheral lines due to sterilization infrastructure requirements and FDA 510(k) compliance burdens.
Pricing Analysis
Peripheral catheter volumes dominate hospital procurement at compressed margins, while smart infusion devices with Epic and Cerner EMR integration capture premium positioning through software-embedded dose-error reduction. Price differentiation separates gamma-irradiated packaging tiers from ethylene oxide alternatives, with FDA sterility validation timelines adding certification-grade premiums. Pricing pressure stems from medical-grade polymer feedstock volatility squeezing extrusion-dependent manufacturers. Group purchasing organizations drive the sharpest price sensitivity, while tertiary care centers integrating ultrasound-guided platforms show lowest sensitivity to per-unit catheter costs.
Supply Chain Analysis
Medical-grade polyurethane supply rests on specialty polymer producers in Germany, Japan, and the United States, with precision extrusion capabilities concentrating manufacturing in these same markets. Raw material dependencies include TPU resin, radiopaque additives, and antimicrobial silver-ion compounds. Single-source vulnerability runs through Japanese precision extrusion equipment suppliers serving catheter lumen formation. Distribution runs through group purchasing organization networks covering over 4,000 member facilities in the United States, with direct hospital contracts prevailing in German and Japanese procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catheter-infusion pump integration represents the decisive vertical-integration race, with control over sterile polymer extrusion and gamma-irradiated packaging infrastructure determining margin capture across premium device tiers.
For Market Incumbents: Deploy closed-system transfer device bundling to lock hospital networks into single-vendor ecosystems, insulating against ICU Medical's hazardous drug safety specialization. Consolidate procurement relationships through multi-year enterprise agreements with Premier and Vizient GPOs. Counter Terumo's precision extrusion anchor in Japan by expanding in-house polymer processing capabilities in Germany and the United States. For New Entrants and Emerging Players: Launch via direct-to-hospital technical service partnerships in India's Delhi-NCR and Maharashtra clusters, bypassing established GPO concentration in developed markets. Target mid-tier polyurethane peripheral catheter segments where Becton Dickinson and B. Braun SE margin compression from feedstock volatility creates procurement openness. Exploit CDSCO regulatory pathways for cost-competitive extrusion capacity serving private hospital infrastructure expansion. For Investors and Strategic Acquirers: FDA 510(k) clearance backlogs extending product launch windows by 8-14 months is the leading indicator that sterilization infrastructure assets will command acquisition premiums. Five-to-ten year viability favors precision extrusion specialists with captive polymer supply and established notified body relationships under EU MDR Annex IX. Watch for Medicare reimbursement expansion signals in home parenteral nutrition as inflection triggers for patient-portable infusion pump demand.| Strategic Initiative | Industry Significance |
|---|---|
| Gamma-Irradiated Sterilization Infrastructure | FDA sterility mandates for needle-free connectors accelerate capital deployment toward in-house irradiation capacity. |
| EMR-Integrated Smart Pump Development | Epic and Cerner closed-loop medication administration commands premium positioning in tertiary care networks. |
| EU MDR Annex IX Technical Documentation | Prior notified body experience accelerates CE marking pathways against US 510(k) review backlogs. |
| Home Infusion Therapy Reimbursement Strategy | Medicare outpatient parenteral nutrition shifts create demand for patient-operated portable pump systems. |
| Ultrasound-Guided Insertion Platform Partnership | Vascular access team adoption at replacement cycles reduces first-attempt failure rates in difficult anatomy cases. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract records, complemented by interviews with vascular access team clinicians, biomedical engineers, GPO contracts managers, and sterile processing directors. Secondary validation drew from ISO 10555 dimensional standards, notified body guidance documents, and polymer feedstock trade data. Bottom-up catheter volume modeling and top-down infusion device value estimates were triangulated against manufacturer revenue disclosures.
Segment-level outputs across the projection horizon reflect material composition tiers, insertion protocol sophistication, and care setting reimbursement models. The analytical framework incorporated polyurethane substitution rates, ultrasound guidance adoption curves, and closed-system transfer device penetration by oncology ward type. CAGRs were derived from installed base replacement cycles, procedure volume growth in aging demographics, and regulatory-driven inventory refresh mandates.
The model assumes a particular technology adoption path for ultrasound-guided peripheral catheter placement; alternative pathways for electromagnetic needle tracking integration would alter the outlook for first-attempt failure rate improvements. Forecasts reflect assumptions around EU MDR traceability compliance timelines and FDA sterility validation evolution. A small set of triggers—Medicare home infusion reimbursement expansion, polymer feedstock price spike duration, and vascular access specialist certification program scaling—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Digital Phoropter Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Cervical Spine System Market