
 Patellar Implant Market | 2026-2036
Patellar Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Patellar Implant Market Analytics
The EU Medical Device Regulation is rebalancing the cost-of-entry calculus for patellar implant suppliers seeking CE marking access across European markets. Zimmer Biomet leverages its scale and regulatory infrastructure to navigate expanded clinical evaluation requirements. Stryker sustains competitive positioning through R&D intensity in patient-specific instrumentation. DePuy Synthes anchors its presence via deep backward integration into cobalt-chromium casting and polyethylene milling operations.
A patellar implant is a prosthetic component designed to replace the posterior articular surface of the patella during total or partial knee arthroplasty, typically manufactured from ultra-high molecular weight polyethylene or cobalt-chromium alloys with thickness profiles ranging from 8 to 12 millimeters to restore patellofemoral tracking and load distribution. Its primary commercial purpose is to reduce anterior knee pain and improve range of motion in patients with degenerative joint disease or post-traumatic arthritis. Cemented fixation dominates current surgical practice due to established long-term survivorship data and familiar operative technique, while robotic-assisted technology commands the fastest expansion trajectory as hospitals invest in precision alignment platforms. Polyethylene material formulations represent the deepest margin pool, driven by cross-linked and antioxidant-stabilized variants that command premium positioning against conventional gamma-sterilized stock.
FDA 510(k) clearance pathways, the EU MDR clinical evaluation framework, and ISO 5834 standards for implant-grade polyethylene collectively govern product development timelines and market access conditions for patellar implant manufacturers. These regulatory layers elevate barriers for new entrants while rewarding incumbents with established quality management systems and predicate device portfolios. Stakeholders must monitor evolving FDA guidance on orthopaedic implant biocompatibility testing and MDR notified body capacity constraints as decisive variables shaping competitive durability.
Market Dynamics
The EU Medical Device Regulation's clinical evidence requirements are redrawing competitive boundaries for patellar implant manufacturers, forcing portfolio rationalization and extended development timelines across European markets.
Growth Catalysts
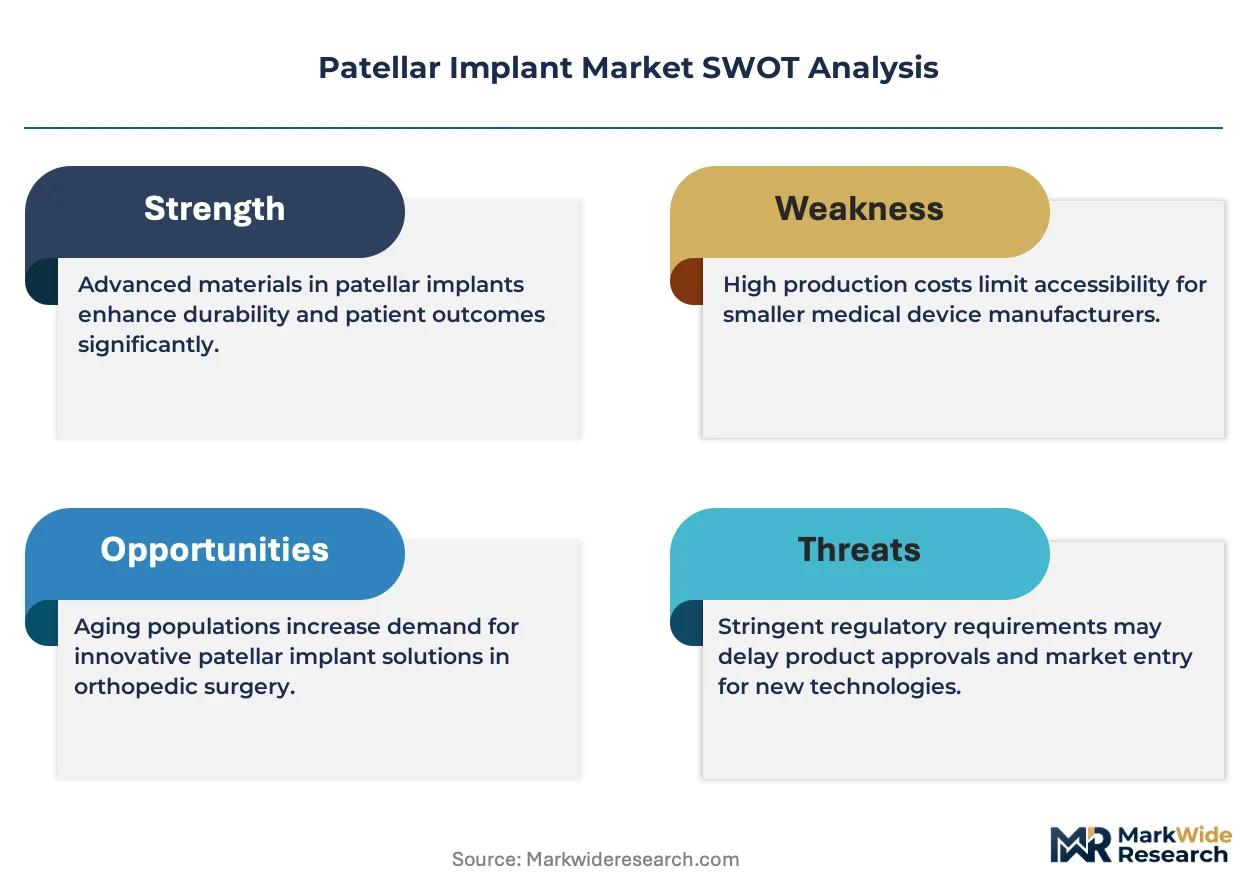
- EU MDR compliance frameworks:Extended transition timelines for legacy devices create temporary market access windows for manufacturers with robust technical documentation and quality management systems already in place.
- Ambulatory surgical centers:Rising procedure volumes at outpatient facilities in Germany and the United States are expanding the addressable patient base beyond traditional hospital settings.
- Antioxidant-stabilized polyethylene:Advanced material formulations with superior oxidative resistance are commanding premium positioning and expanding the high-margin product tier.
Market Restraints
- Cobalt-chromium supply concentration:Limited qualified foundry capacity for implant-grade alloys creates input bottlenecks and price volatility for manufacturers dependent on external suppliers.
- MDR notified body capacity constraints:Reduced certification throughput across European conformity assessment organizations extends time-to-market for new patellar implant designs.
- Cementless fixation alternatives:Porous titanium and trabecular metal technologies for total knee constructs threaten to displace traditional patellar resurfacing in select patient populations.
Strategic Opportunities
- German reimbursement density:Europe's highest orthopedic procedure volumes and favorable DRG classifications for knee arthroplasty create concentrated demand pull for premium implant systems.
- Robotic-assisted alignment platforms:Convergence of patient-specific instrumentation with computer-navigated surgery is opening new revenue streams through bundled hardware-implant contracts.
- Same-day discharge protocols:Regulatory and payer incentives for outpatient joint replacement in the United States are accelerating channel migration toward ambulatory surgery centers.
Industry Challenges
- Biocompatibility testing protocols:Evolving FDA guidance on orthopaedic implant cytotoxicity and sensitization assays requires repeated protocol updates and extended preclinical timelines.
- Polyethylene sterilization validation:Transition from gamma to gas plasma or e-beam methods demands capital-intensive equipment upgrades and process requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patellar Implant Market |
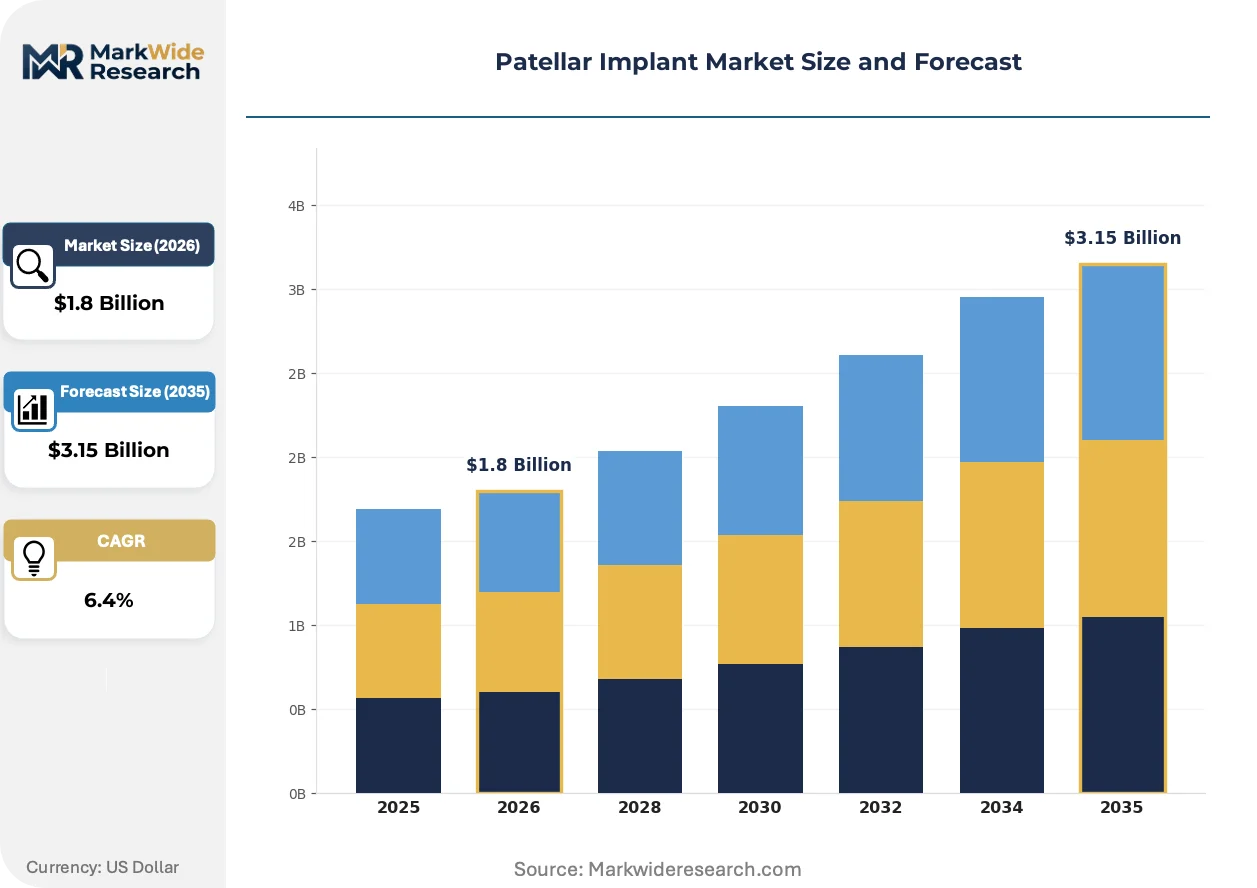
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cemented, Cementless, Hybrid, Patella Resurfacing Technology: Conventional, Computer-Assisted, Robotic-Assisted, Custom-Made End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Material: Polyethylene, Titanium, Cobalt-Chromium, Others |
| Companies Covered | Zimmer Biomet, Stryker, DePuy Synthes, Smith+Nephew, Medacta International, ConforMIS, MicroPort Scientific, Aesculap Implants Systems, Exactech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patellar Implant Market Evolving Landscape
Patellar implant development is pivoting toward precision-matched systems that integrate with broader knee reconstruction workflows, compressing the gap between generic components and patient-specific solutions.
Modular patellar implant systems with adjustable thickness and offset configurations are modularizing the traditional one-size-fits-all approach to patellar resurfacing. High-volume orthopedic service lines at academic medical centers in the United States are piloting these platforms to reduce operative inventory burden. This architecture is modularizing supplier relationships, enabling hospitals to consolidate vendor contracts while preserving surgical flexibility.
REACH restrictions on cobalt compounds are tightening material sourcing requirements for European implant manufacturers. The regulation's Annex XVII limitations on cobalt chloride and sulfate compounds are propagating through supply chain audit protocols. Cobalt-chromium casting operations in Germany and Switzerland are responding with enhanced lot traceability systems and alternative alloy qualification programs.
Hospital purchasing consortiums are consolidating orthopedic implant procurement through single-source agreements with penalty clauses for volume shortfalls. Independent ambulatory surgery centers in Florida and Texas are losing direct manufacturer access as distribution compresses toward integrated delivery networks. This concentration is most visible in Medicare Advantage–dominated markets where payers steer volume toward contracted facility networks.
Patellar Implant Market Segmentation
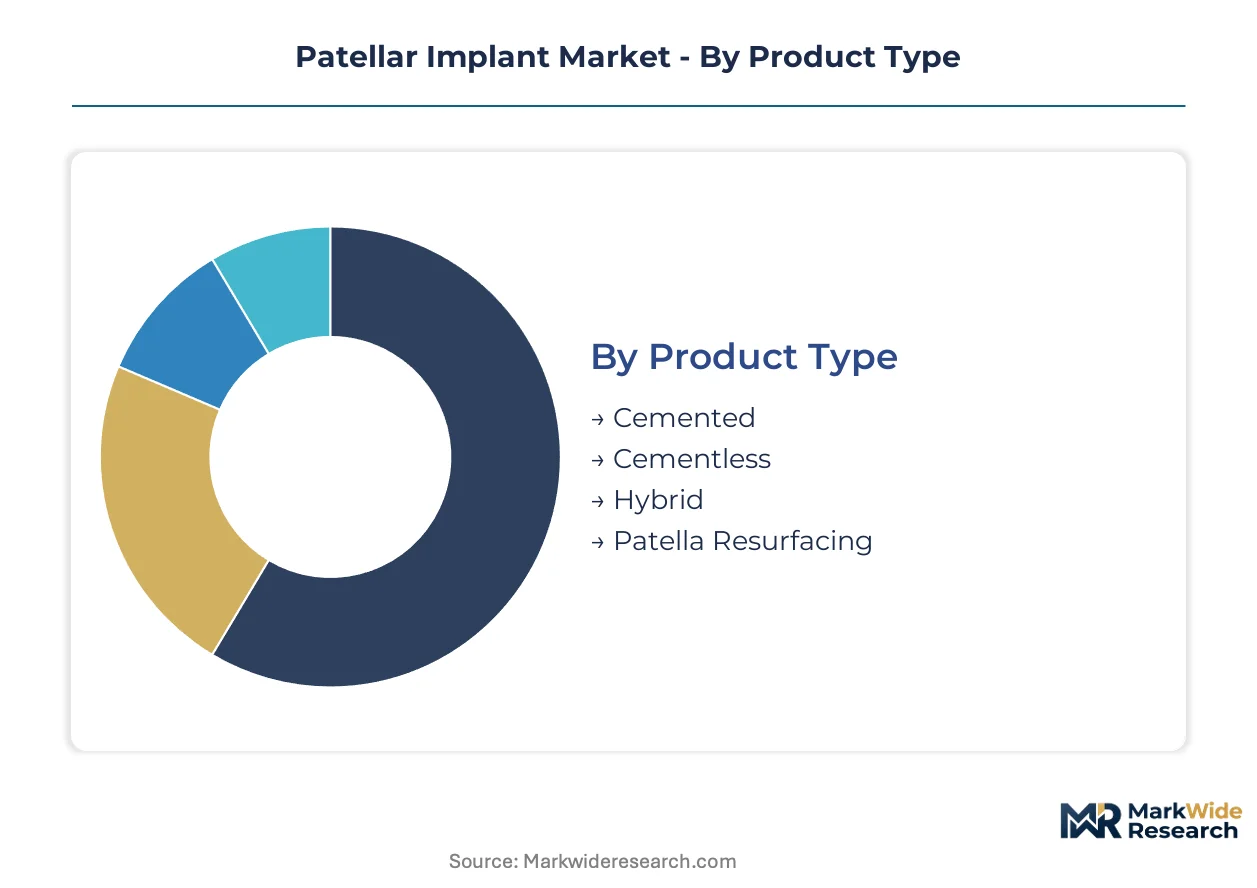
Patellar implant purchasing decisions split across fixation philosophy, surgical workflow integration, and material durability requirements. Each segmentation axis carries distinct margin profiles and regulatory pathways that reshape supplier competitive positioning.
Product Type:
Surgeon training and long-term survivorship data drive fixation method selection in hospital purchasing committees.
- Cemented:Polymethylmethacrylate bone cement anchors the implant to the patellar bed through mechanical interlock. Demand concentrates in academic medical centers across Germany and the United States where established protocols prioritize revision predictability over operative speed.
- Cementless:Porous-coated or trabecular metal surfaces enable biological osseointegration without cement. Growth tilts toward ambulatory surgical centers seeking reduced operative time and faster patient turnover within same-day discharge protocols.
- Hybrid:Combines cemented polyethylene articulation with cementless metal-backed baseplates for selective fixation zones.
- Patella Resurfacing:Thin polyethylene onlay designs preserve native patellar bone stock in partial knee arthroplasty.
Volume sits with cemented constructs; growth tilts toward cementless alternatives.
Technology:
Capital equipment investment cycles determine technology penetration rates across hospital systems.
- Conventional:Manual instrumentation and standard cutting jigs guide patellar resection and implant positioning. Demand remains anchored in community hospitals and international markets with limited robotic capital budgets.
- Robotic-Assisted:Computer-navigated resection with haptic feedback enables sub-millimeter precision in patellar thickness restoration. Adoption concentrates in integrated delivery networks in Texas and Florida where bundled payment contracts reward alignment accuracy.
- Computer-Assisted:Optical or electromagnetic tracking supplements manual technique without robotic hardware investment.
- Custom-Made:Patient-specific jigs manufactured from preoperative imaging data match individual patellar morphology.
Conventional systems dominate procedure counts; robotic-assisted platforms are climbing the fastest as health systems amortize capital across service lines.
End User:
Reimbursement differentials and regulatory licensing shape channel access for implant suppliers.
- Hospitals:Inpatient facilities with 24-hour recovery capabilities and full emergency backup. Procurement concentrates through integrated delivery networks with multi-year sole-source agreements.
- Ambulatory Surgical Centers:Outpatient facilities optimized for rapid turnover and reduced infection risk. Medicare Advantage penetration in the United States accelerates migration toward these settings.
- Orthopedic Clinics:Physician-owned facilities performing limited-scope joint replacement.
- Rehabilitation Centers:Post-acute settings managing implant recovery protocols without operative capability.
Hospitals retain the deepest volume; ambulatory surgical centers are gaining share fastest.
Material:
Wear characteristics and oxidative stability determine material selection in high-activity patient populations.
- Polyethylene:Ultra-high molecular weight formulations with cross-linked or antioxidant-stabilized variants provide articulating surfaces with reduced wear debris generation. Demand clusters in Germany where polyethylene milling operations enable just-in-time supply to major orthopedic manufacturers.
- Cobalt-Chromium:Cast or wrought alloys deliver structural backing for dome-shaped patellar components. REACH Annex XVII restrictions on cobalt compounds intensify supply chain audit requirements for European foundries.
- Titanium:Porous plasma-sprayed or trabecular metal structures promote bone ingrowth in cementless applications.
- Others:Ceramic and oxidized zirconium alternatives for metal-sensitive patients.
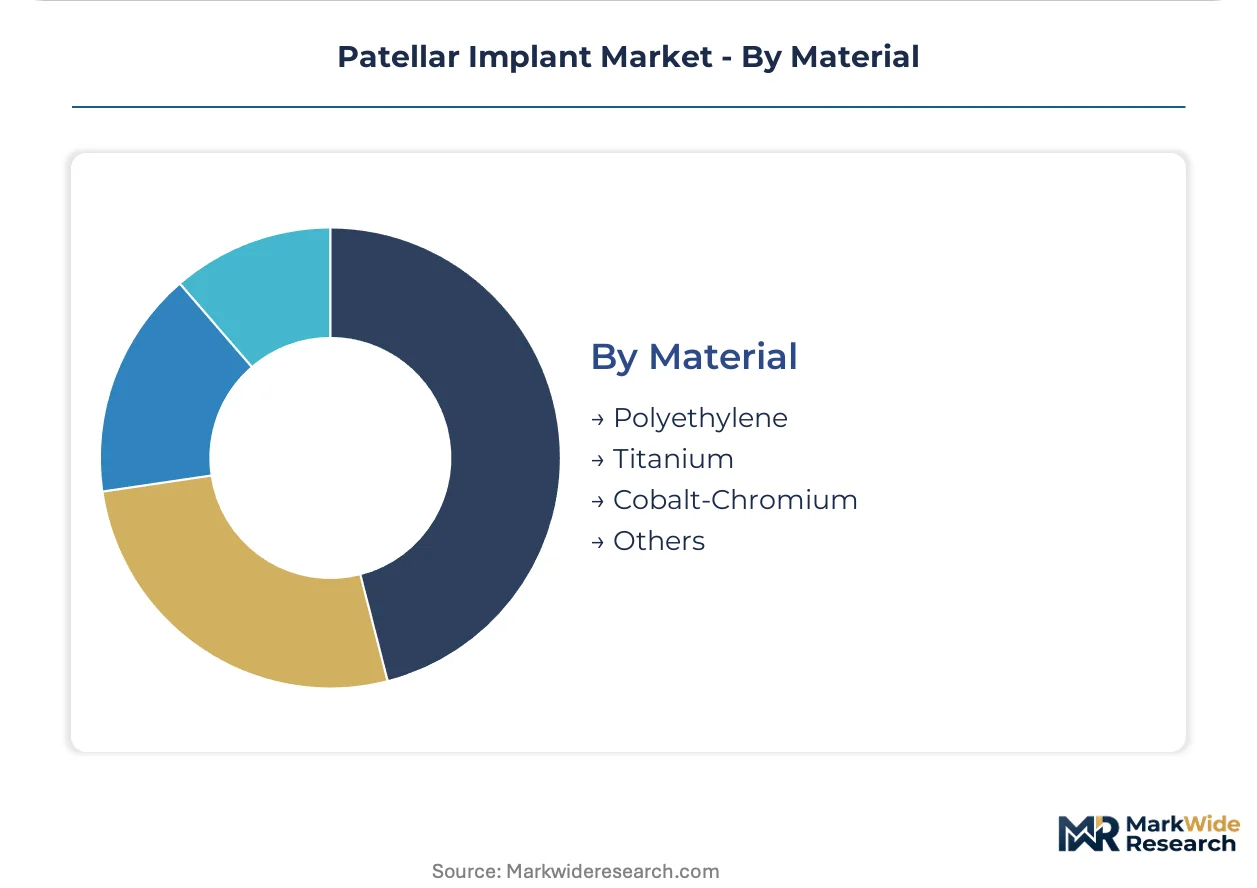
Polyethylene commands the broadest adoption; antioxidant-stabilized variants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Zhangjiakou concentrate orthopedic manufacturing infrastructure for Asia-Pacific distribution. Tax incentives for medical device R&D in Bavaria and Baden-Württemberg anchor European production networks. Special economic zones in Costa Rica and Tijuana accelerate North American supply chain regionalization.
United States
Medicare Advantage penetration in Florida and Texas accelerates ambulatory surgical center migration for outpatient knee arthroplasty. FDA 510(k) clearance pathways govern product development timelines for domestic manufacturers. The Dallas-Fort Worth metroplex hosts concentrated orthopedic distribution hubs serving the Southwest corridor.
Germany
DRG reimbursement density for knee arthroplasty procedures exceeds European benchmarks, concentrating demand pull for premium implant systems. EU MDR clinical evaluation requirements extend compliance timelines for manufacturers seeking CE marking renewal. The Tuttlingen industrial cluster maintains dense networks of precision instrument fabricators supplying major orthopedic OEMs.
China
NMPA regulatory harmonization with international standards accelerates market access for multinational implant manufacturers. Provincial medical procurement consortia in Jiangsu and Zhejiang consolidate purchasing power through volume-based tendering. The Suzhou Industrial Park hosts captive milling operations for polyethylene component supply to Asia-Pacific markets.
Switzerland
Swissmedic certification reciprocity with EU MDR frameworks preserves streamlined market access despite non-member status. Precision machining heritage in the Jura Arc sustains specialized contract manufacturers for implant-grade components. Geneva-based orthopedic research institutes pilot robotic-assisted surgical platforms with integrated patellar alignment modules.
Japan
PMDA reimbursement pricing reviews for knee arthroplasty devices compress margin structures for imported implant systems. METI industrial policy prioritizes domestic production of advanced biomaterials for orthopedic applications. The Kobe medical device cluster concentrates polymer processing capabilities for regional supply chain integration.
Patellar Implant Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure intensifies as regulatory compliance costs escalate under EU MDR frameworks and FDA biocompatibility testing protocols. Three strategic archetypes dominate: scale-driven integrated manufacturers with captive foundry and milling operations; mid-cap specialists leveraging patient-specific instrumentation partnerships; and regional challengers exploiting procurement localization mandates. Competitive moves concentrate on backward integration into polyethylene milling and cobalt-chromium casting, alongside bundled contracting for robotic-assisted surgical platforms.
Within the diversified conglomerate tier, Zimmer Biomet and Stryker occupy positions defined by regulatory infrastructure depth and capital equipment scale. DePuy Synthes anchors the integrated manufacturing archetype through upstream control over alloy supply chains. Among focused specialists, ConforMIS exemplifies patient-specific instrumentation positioning, while MicroPort Scientific represents regional challenger momentum in Asia-Pacific procurement environments.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| DePuy Synthes |
| Smith+Nephew |
| Medacta International |
| ConforMIS |
| MicroPort Scientific |
| Aesculap Implants Systems |
| Exactech |
| Others |
Value Network & Pricing Analysis
Antioxidant-stabilized polyethylene's performance divergence from gamma-sterilized stock manifests in both procurement premiums and captive milling investments across German and Swiss supply networks. This material-grade bifurcation concentrates pricing power with cross-linked formulation suppliers while forcing second-tier manufacturers toward spot-market cobalt-chromium sourcing.
Pricing Analysis
Short lead-time premiums of four to six weeks command fifteen to twenty percent markups over standard inventory cycles for implant-grade polyethylene. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 5834 compliance tier and sterilization method. Pricing pressure stems from REACH Annex XVII cobalt restrictions elevating European foundry audit costs. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize revision predictability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from major orthopedic OEMs mandate qualified suppliers in Germany, Switzerland, and the United States for implant-grade cobalt-chromium alloys. Raw material dependencies center on ethylene feedstock for polyethylene polymerization, cobalt ore from Central African mines, and precision machining equipment from Japanese suppliers. Single-source vulnerability concentrates in Tuttlingen instrument fabrication clusters. Distribution runs through integrated delivery networks with sole-source contracting and volume penalty clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR clinical evaluation framework has erected a cost-of-compliance moat that rewards incumbents with established quality management systems while filtering speculative entrants from European markets.
For Market Incumbents: Acquire captive polyethylene milling operations to secure margin pools in antioxidant-stabilized formulations. Cementless fixation platforms threaten displacement of traditional resurfacing in ambulatory settings; anchor hospital contracts through bundled robotic-assisted alignment packages. Expand Tuttlingen-area instrument fabrication capacity to capture patient-specific instrumentation workflows. For New Entrants and Emerging Players: Economy-tier polyethylene spot pricing gaps against premium cross-linked formulations open procurement entry points for cost-focused ambulatory surgical centers. German DRG reimbursement density creates concentrated demand pull for mid-tier hybrid fixation systems. Pursue NMPA harmonization pathways for Asia-Pacific volume scaling before attempting FDA 510(k) clearance. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing patient-specific instrumentation partnerships given convergence toward precision-matched patellar systems. Five-to-ten year viability favors suppliers with backward integration into cobalt-chromium casting. Monitor MDR notified body capacity constraints as inflection signal for European market access bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation investments preserve European market access for compliant manufacturers. |
| Backward Integration into Polyethylene Milling | Captive antioxidant-stabilized production secures premium-tier margin pools against commodity competitors. |
| Hospital System Partnership | Integrated delivery network sole-source contracts lock volume commitments through multi-year agreements. |
| Robotic-Assisted Platform Bundling | Alignment hardware-implant convergence opens new revenue streams in Texas and Florida Medicare Advantage markets. |
| Reimbursement Strategy | DRG classification optimization in Germany concentrates demand pull for premium patellar implant systems. |
Research Methodology
Multi-period observation of orthopedic procedure volumes, implant revision rates, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs leads at major OEMs. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body certification records, CMS Medicare claims data, and hospital procurement consortium contract filings. Bottom-up implant shipment estimates triangulated against top-down knee arthroplasty procedure forecasts.
Segment-weighting applied product type, technology adoption curve, end-user channel mix, and material formulation durability across the projection horizon. Modeled dimensions spanned fixation philosophy, surgical workflow integration, and oxidative stability requirements. CAGRs derived from surgical volume elasticity to demographic aging patterns and ambulatory migration rates. Forecast inputs incorporated REACH cobalt restriction implementation timelines and robotic-assisted platform capital expenditure cycles.
Inputs from FDA 510(k) databases and EU MDR certification records were available through the study window; gaps in real-time ambulatory surgical center inventory data introduce uncertainty bands around channel-shift assumptions. Deviation in MDR notified body capacity or NMPA harmonization pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Europe Breast Pumps Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Colposcopes Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Global Disability Devices Market
Medical Devices
Blood Warmers Market
Medical Devices
Elderly and Disabled Assistive Devices Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Breast Pump Flange Market