
 Computer-Aided Facility Management (CAFM) Market | 2026-2036
Computer-Aided Facility Management (CAFM) Market Size, Share, and Industry Trends Forecast 2026-2036
Computer-Aided Facility Management (CAFM) Market Analysis
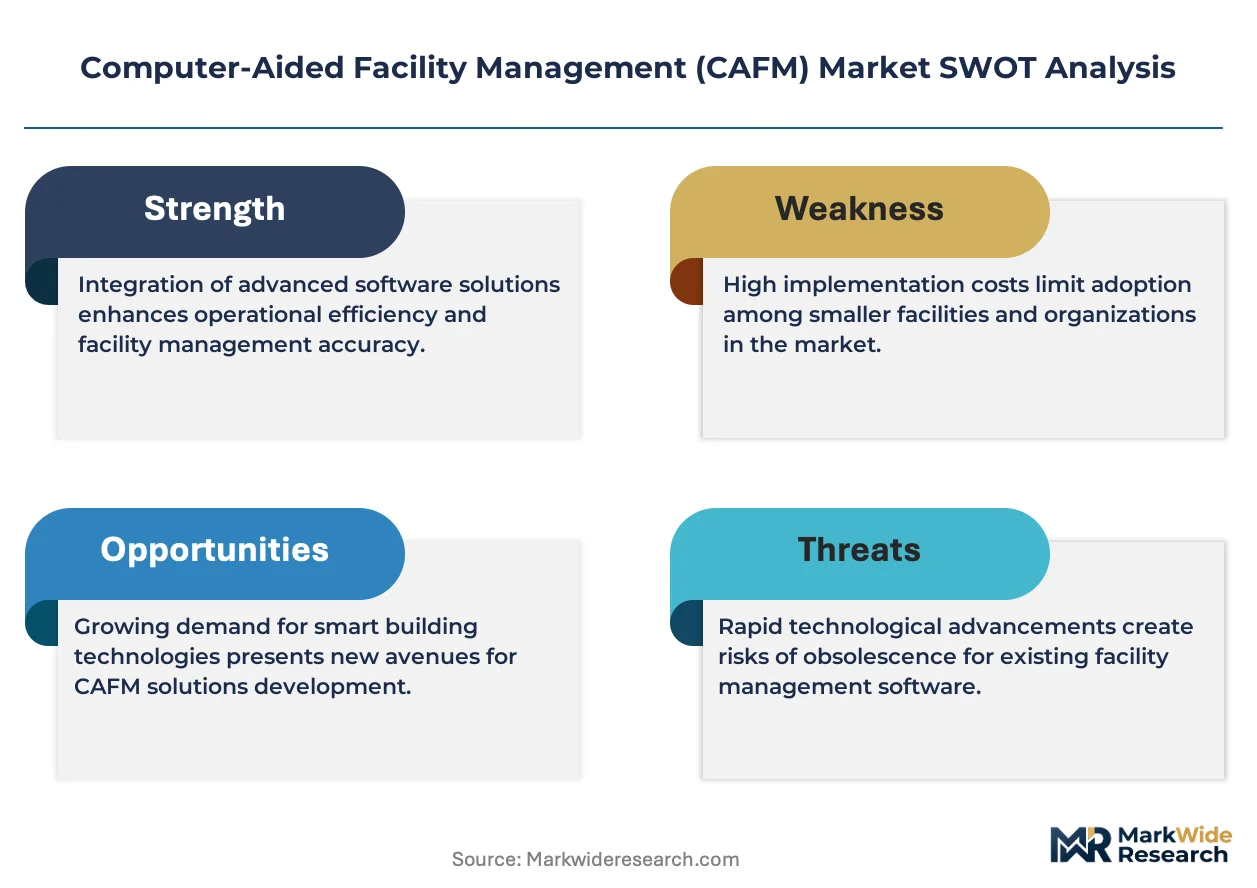
A shortage of credentialed facility engineers is redrawing competitive dynamics across the CAFM landscape. IBM TRIRIGA leverages its enterprise asset management heritage to anchor complex campus deployments for Fortune 500 clients. Planon sustains strong positioning in European commercial real estate through integrated workplace management modules. Fiix competes aggressively in the mid-market maintenance segment with mobile-first work order interfaces.
Computer-Aided Facility Management denotes software systems that digitize the planning, execution, and monitoring of built environment operations through CAD-integrated spatial databases, IoT telemetry ingestion, and predictive maintenance algorithms. These platforms synchronize building information models with real-time sensor feeds to optimize space utilization, reduce equipment downtime, and enforce regulatory compliance across distributed property portfolios. Cloud-based deployment now leads adoption as organizations shed capital-intensive on-premises infrastructure for elastic SaaS architectures with automatic compliance patching. Space Management and Asset Tracking features command premium pricing due to their direct impact on lease optimization and capital planning cycles, while Maintenance Management functions represent the largest volume segment across education and government end users.
Federal agencies in the United States face GSA mandates for building energy benchmarking, while the EPA ENERGY STAR program and OSHA workplace safety standards shape product certification requirements for CAFM vendors serving domestic facilities. The EU CSRD and Energy Performance of Buildings Directive impose parallel disclosure obligations across European portfolios, forcing platform providers to embed carbon accounting modules. Stakeholders must weigh interoperability investments against the risk of stranded data as regulatory jurisdictions proliferate divergent reporting standards.
Market Dynamics
Cloud-native CAFM architectures are compressing deployment timelines from eighteen-month on-premises implementations to six-week SaaS rollouts, forcing incumbent vendors to restructure professional services revenue models around subscription retention rather than perpetual license maintenance.
Growth Catalysts
- OSHA workplace safety mandates:Federal enforcement of incident reporting digitization drives CAFM adoption across manufacturing campuses and distribution centers in the United States.
- IoT sensor networks:Real-time telemetry from HVAC and electrical systems enables predictive maintenance workflows that reduce unplanned downtime in healthcare and education facilities.
- Energy benchmarking requirements:The EPA ENERGY STAR program compels commercial real estate owners to deploy automated utility tracking modules for portfolio-wide carbon disclosure.
Market Restraints
- Semiconductor supply volatility:IoT gateway and edge computing hardware procurement faces lead time extensions from foundry capacity constraints in East Asia.
- Data residency fragmentation:Divergent sovereign cloud requirements across Germany, France, and Switzerland force vendors to maintain redundant regional infrastructure.
- Legacy ERP entrenchment:Deep integration with SAP and Oracle systems creates switching costs that delay replacement cycles in Fortune 500 manufacturing.
Strategic Opportunities
- Small and medium commercial portfolios:Underpenetrated multi-tenant office buildings in secondary US metropolitan areas lack dedicated facility management staff.
- Digital twin convergence:Integration of building information models with real-time sensor feeds creates new value layers for capital planning and space optimization.
- EU CSRD alignment:Mandatory sustainability reporting for European corporates generates demand for embedded carbon accounting and Scope 3 emission tracking modules.
Industry Challenges
- Facility engineering credential scarcity:Shortages of certified energy managers and building automation specialists constrain implementation velocity for complex campus deployments.
- Interoperability certification delays:Vendor-specific data formats impede seamless migration between platforms, extending proof-of-concept timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer-Aided Facility Management (CAFM) Market |
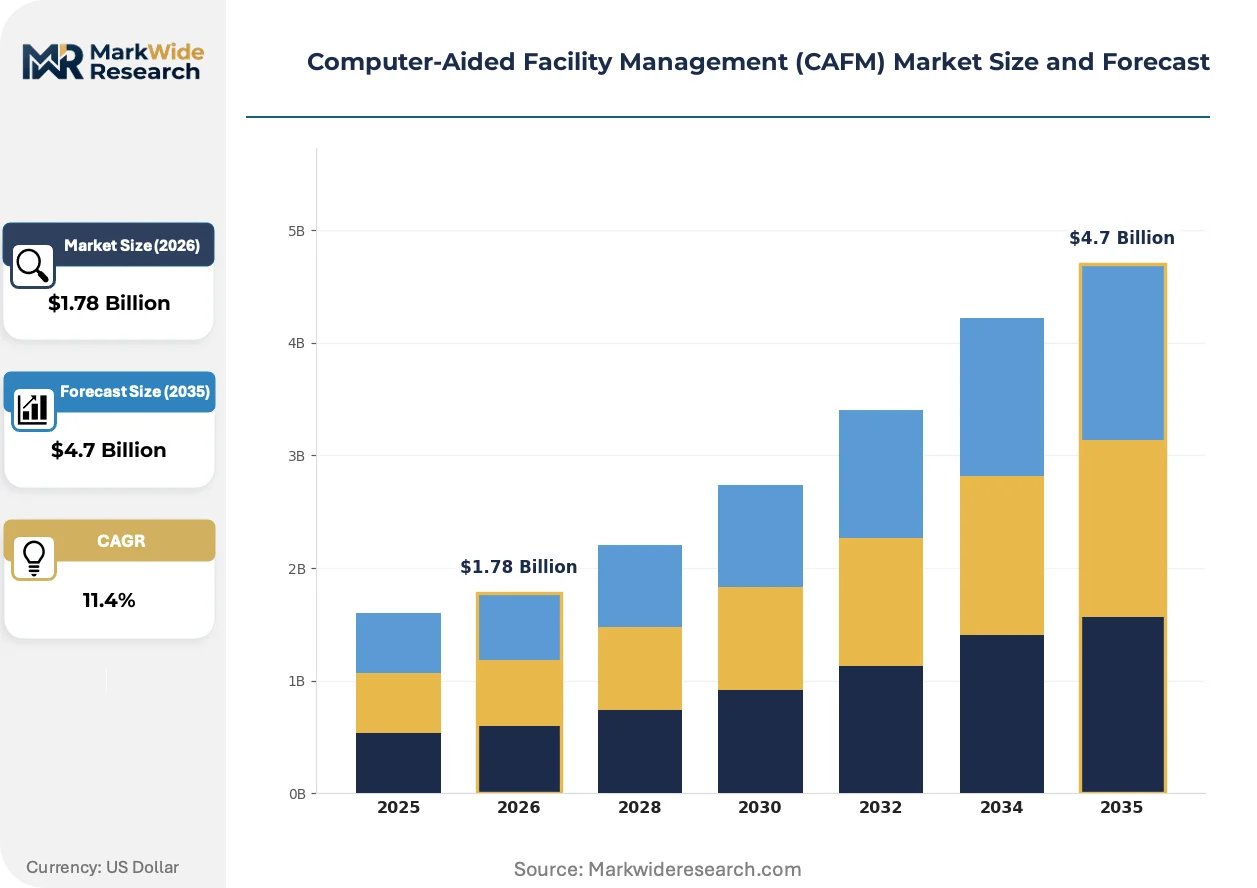
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-based, Hybrid, Integrated End User: Real Estate, Education, Healthcare, Government Feature: Space Management, Maintenance Management, Asset Tracking, Reporting Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | UpKeep, Limble CMMS, IBM TRIRIGA, Fiix, Corrigo, Planon, AkitaBox, FM:Systems, Factory AI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer-Aided Facility Management (CAFM) Market Emerging Trajectories
Artificial intelligence inference at the network edge is redefining how building systems process telemetry, shifting analytical workloads from centralized cloud servers to localized compute nodes that enable sub-second response times for critical equipment alerts.
Edge AI inference engines are supplanting rule-based fault detection in commercial HVAC and electrical distribution systems. Large hospital networks and university campuses are deploying these architectures at scale to reduce latency in emergency equipment shutdowns. The shift compresses maintenance response windows from hours to seconds while reducing data transmission costs.
The EU Energy Performance of Buildings Directive mandates automated building logbooks and smart readiness indicators for all new construction and major renovations. This regulatory pressure forces CAFM vendors to pre-certify platforms against national energy agency protocols. German and Dutch commercial developers now require smart readiness certification as a standard procurement criterion.
Subscription-based platform access is displacing perpetual license purchases across municipal government and education sectors. State procurement offices in California, Texas, and New York have shifted RFP structures toward multi-year SaaS commitments with built-in compliance patching. This reconfiguration compresses vendor sales cycles while extending customer lifetime value measurement horizons.
Computer-Aided Facility Management (CAFM) Market Segmentation
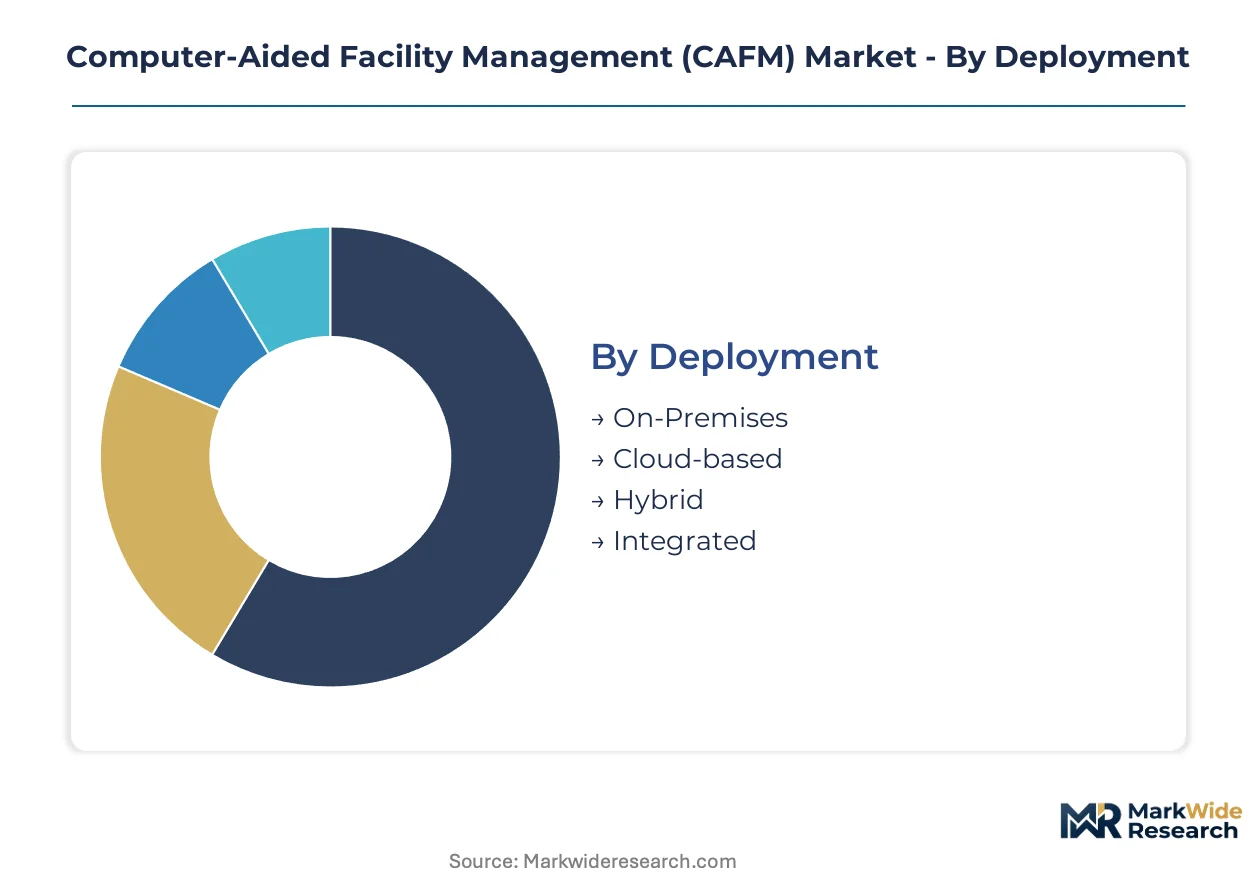
CAFM procurement patterns diverge sharply across deployment architectures and functional modules. Buyers weigh capital intensity against compliance velocity when selecting configuration tiers. Feature prioritization reflects whether organizations optimize for space revenue or asset longevity.
Deployment:
Cloud-native substitutes threaten on-premises incumbents most aggressively where elastic scaling outweighs data sovereignty requirements.
- Cloud-based:Multi-tenant SaaS architectures eliminate server maintenance overhead while embedding automatic security patching. US federal agencies and university systems concentrate demand here, driven by GSA procurement standards that mandate continuous compliance updates without capital refresh cycles.
- On-Premises:Perpetual license models retain foothold in defense contractors and financial institutions with air-gapped security requirements. These deployments require dedicated infrastructure teams and eighteen-month implementation timelines that compress competitive positioning against cloud alternatives.
- Hybrid:Split workloads between local edge processing and cloud analytics accommodate facilities with mixed sensitivity classifications.
- Integrated:Pre-built connectors to ERP and building automation systems reduce customization labor for Fortune 500 campus portfolios.
On-Premises anchors the volume base while Cloud-based gains share at the steepest rate.
End User:
Cost tier stratification separates enterprise-grade deployments from mid-market configurations across facility types.
- Healthcare:Equipment lifecycle tracking and Joint Commission compliance documentation command premium module pricing. Hospital networks in the United States deploy predictive maintenance algorithms for MRI and HVAC systems to minimize patient care disruption.
- Government:Federal building portfolios face EPA ENERGY STAR benchmarking mandates and OSHA incident reporting digitization requirements. State procurement offices in California and Texas structure multi-year SaaS RFPs with built-in compliance patching.
- Real Estate:Commercial developers prioritize lease optimization and tenant experience scoring over deep asset telemetry.
- Education:K-12 districts and community colleges favor standardized work order modules with limited customization scope.
Government contracts anchor the revenue base while Healthcare expands most quickly on compliance complexity.
Feature:
Application maturity varies widely across functional modules, with newer capabilities commanding implementation premiums.
- Space Management:CAD-integrated spatial databases enable real-time occupancy heat mapping and lease scenario modeling. Corporate real estate teams in commercial office towers deploy these tools to right-size footprints amid hybrid work transitions.
- Asset Tracking:RFID and IoT sensor fusion creates digital twin representations of equipment location and condition state. Healthcare facilities prioritize these capabilities for mobile medical device fleet management and regulatory audit trails.
- Maintenance Management:Work order routing and vendor dispatch automation serve as the entry-level capability across education and municipal government sectors.
- Reporting:Pre-configured dashboards for carbon disclosure and safety compliance reduce analyst labor for EU CSRD-aligned portfolios.
Maintenance Management anchors the installed base while Asset Tracking climbs the fastest on IoT hardware cost declines.
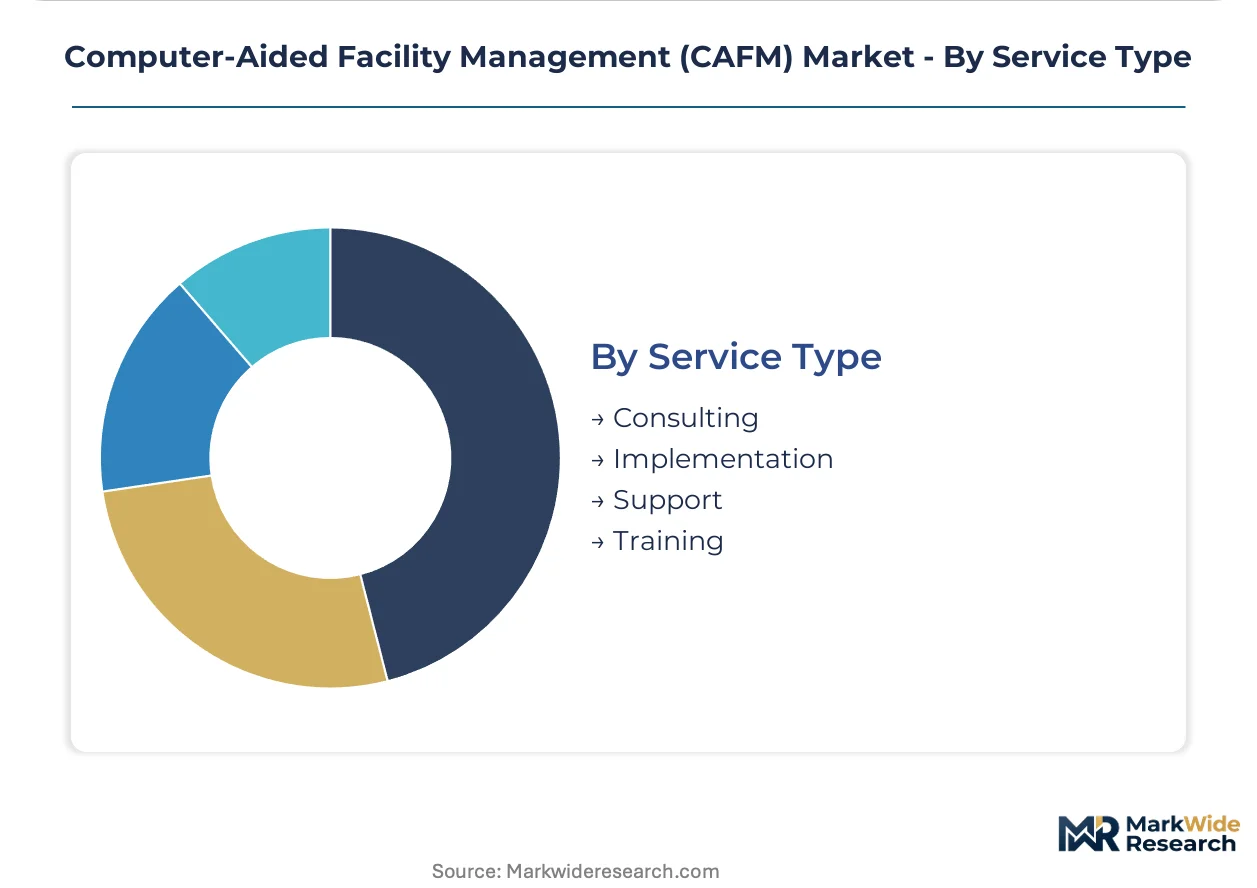
Service Type:
Customer type segmentation separates self-sufficient IT organizations from those requiring full-service enablement.
- Implementation:Data migration from legacy CMMS and ERP systems demands specialized engineering labor that extends project timelines. System integrators concentrate staffing in metropolitan corridors with dense healthcare and university cluster presence.
- Consulting:Change management and workflow redesign services accelerate user adoption for organizations with limited facility engineering benches. These engagements concentrate among mid-market commercial real estate owners lacking dedicated operations technology staff.
- Support:Tiered response commitments differentiate vendor positioning for mission-critical healthcare deployments.
- Training:Certification programs for energy managers and building automation specialists address credential scarcity constraining deployment velocity.
Implementation services anchor the revenue mix while Consulting shows the steepest expansion trajectory on skills gap remediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal agencies deploy cloud-native CAFM architectures for GSA-mandated energy benchmarking, while European healthcare networks prioritize carbon accounting modules for CSRD alignment. German commercial developers and Japanese hospital systems exhibit divergent feature preferences shaped by distinct regulatory timelines.
United States
Federal building portfolios and university systems drive cloud migration under GSA procurement standards and EPA ENERGY STAR mandates. OSHA workplace safety digitization requirements accelerate adoption across manufacturing campuses. Healthcare networks in the Boston-Cambridge corridor deploy predictive maintenance for MRI equipment lifecycle management.
Germany
Commercial real estate developers mandate smart readiness certification under the Energy Performance of Buildings Directive. The country's national energy agency protocols force platform pre-certification for new construction projects. Industrial clusters in North Rhine-Westphalia integrate CAFM with building automation systems for chemical facility compliance.
Japan
Hospital networks and semiconductor fabrication facilities prioritize edge AI inference for sub-second equipment alerts. METI building efficiency standards shape procurement criteria for commercial portfolios. Tokyo-Osaka corridor deployments concentrate on digital twin convergence for capital planning optimization.
United Kingdom
Corporate real estate teams in London deploy space management modules for hybrid work footprint right-sizing. The country's national building safety regulator post-Grenfell mandates digitized incident reporting for high-rise portfolios. Manchester-Leeds industrial zones adopt asset tracking for manufacturing equipment fleet visibility.
France
Healthcare facility managers integrate CAFM with Joint Commission-equivalent compliance documentation for medical device tracking. ANSM digital health infrastructure requirements influence platform selection in hospital procurement. Lyon-Grenoble technology clusters pilot IoT sensor networks for research campus energy optimization.
Computer-Aided Facility Management (CAFM) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the CAFM market structure. Enterprise-grade vendors anchor complex campus deployments through ERP-integrated architectures, while mid-market specialists compete on mobile-first interfaces and rapid SaaS onboarding. Two strategic archetypes dominate: platform consolidators pursuing cross-module bundling and vertical specialists defending segment-specific workflow depth. M&A activity concentrates on IoT sensor network capabilities and carbon accounting module tuck-ins.
Within the enterprise platform tier, IBM TRIRIGA and Planon occupy positions reflecting distinct geographic heritage and deployment complexity. IBM TRIRIGA exemplifies the integrated systems archetype for Fortune 500 campus portfolios, while Planon anchors European commercial real estate positioning through workplace management specialization. Fiix represents the mobile-native mid-market vector competing on work order interface simplicity.
| Leading Market Players |
|---|
| UpKeep |
| Limble CMMS |
| IBM TRIRIGA |
| Fiix |
| Corrigo |
| Planon |
| AkitaBox |
| FM:Systems |
| Factory AI |
| Others |
Supply Flow & Price Mechanics
Multi-year SaaS subscription contracts lock in both supply access and price visibility for CAFM vendors serving federal agencies and university systems, insulating platform providers from spot-market volatility in cloud infrastructure while compressing buyer negotiation leverage.
Pricing Analysis
Subscription-based capacity reservations dominate enterprise procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by compliance module depth and integration complexity. Price differentiation rests on EPA ENERGY STAR certification tier and GSA procurement standing. Cost compression in the mid-market segment is intensifying because mobile-native entrants undercut legacy perpetual-license maintenance fees. Municipal governments exhibit highest price sensitivity; healthcare networks demonstrate lowest sensitivity due to Joint Commission compliance requirements.
Supply Chain Analysis
Just-in-time provisioning of cloud compute resources prevails among SaaS-native vendors, though strategic stockpiling of IoT gateway hardware buffers against semiconductor foundry constraints in Taiwan and South Korea. Edge AI inference chip supply draws from NVIDIA, Qualcomm, and MediaTek fabrication networks concentrated in East Asia. Single-source vulnerability in sensor microcontroller supply creates exposure for vendors dependent on specific ARM licensee production. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CAFM market sits in a cyclical recovery phase as deferred facility modernization budgets reopen following post-pandemic capital allocation freezes.
For Market Incumbents: Compound defensive positioning through backward integration into IoT sensor hardware supply and carbon accounting module certification investment. Cloud-native substitutes threaten perpetual-license maintenance revenue. Vertical integration into edge AI inference engines anchors premium-tier pricing power. For New Entrants and Emerging Players: Mid-market commercial real estate owners lacking dedicated facility engineering staff represent the most penetrable white-space target. Secondary US metropolitan multi-tenant office buildings remain underpenetrated. Channel partnerships with regional system integrators accelerate proof-of-concept timelines. For Investors and Strategic Acquirers: IoT sensor network specialists with healthcare compliance documentation capabilities present the most attractive acquisition target archetype. Long-term viability over a five-to-ten-year window hinges on CSRD-aligned carbon accounting module penetration. Watch EU Energy Performance of Buildings Directive enforcement intensity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built ERP connectors reduce Fortune 500 implementation timelines from months to weeks. |
| Acquisition of Specialist Firm | IoT sensor network tuck-ins embed real-time telemetry for predictive maintenance workflows. |
| Geographic Expansion | German smart readiness certification unlocks Energy Performance of Buildings Directive-mandated procurement. |
| Product Launch | Edge AI inference modules enable sub-second HVAC emergency shutdowns for hospital networks. |
| Strategic Partnership | Hyperscaler marketplace listings accelerate municipal government SaaS procurement velocity. |
Methodological Framework
The analysis maps cloud-native deployment, on-premises legacy, hybrid architectures, and integrated ERP connectors, each validated through facility engineering directors, IT procurement officers, cloud platform engineers, and system integration specialists. Primary interview findings triangulate against GSA procurement databases, EPA ENERGY STAR certification records, SEC 10-K infrastructure disclosures, and EU CSRD reporting filings. Bottom-up deployment volume estimates reconcile with top-down software spend benchmarks across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, functional module, and service type, alongside geographic regulatory cluster. CAGRs derive from elasticity-adjusted adoption curves and compliance mandate enforcement schedules. Forecast inputs incorporate IoT hardware cost decline trajectories and federal energy benchmarking mandate expansion timelines.
Material uncertainties — semiconductor supply volatility, divergent sovereign cloud requirements, legacy ERP entrenchment — sit outside the modeled envelope. Forecasts reflect assumptions regarding GSA procurement standard continuity and EPA enforcement intensity. Revision becomes warranted when EU CSRD alignment deadlines accelerate or OSHA digitization mandates expand beyond manufacturing scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
North America Building Automation System Market