
 Dredge Automation Market | 2026-2036
Dredge Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Dredge Automation Market Insights
Modular sensor-and-control packages are recalibrating how fleet operators configure automation upgrades, letting buyers mix GPS positioning, hydraulic monitoring, and remote operation modules rather than purchasing monolithic systems. DSC Dredge anchors its market presence through specialized cutter suction automation for mining and construction channels. James Fisher Prolec differentiates via precision dredge positioning technology that leverages integrated sensor fusion. Alewijnse competes in the electrical and control systems layer, sustaining its role across European harbor deepening projects.
Dredge automation encompasses the integration of sensor networks, programmable logic controllers, and telematics to govern dredge pump operation, spud positioning, and swing movement without continuous manual intervention, typically achieving positional accuracy within sub-meter tolerances through differential GPS and motion reference units. The primary industrial purpose is to optimize sediment removal rates while minimizing fuel consumption, environmental spillover, and crew exposure in hazardous marine environments. Cutter suction dredger automation currently leads product type adoption due to its prevalence in capital dredging and land reclamation, while remote operation deployment models represent the fastest-growing configuration as harbor authorities seek to reduce onboard staffing for repetitive maintenance cycles. Environmental end-user applications are expanding fastest in regulatory intensity, though port operators still occupy the largest value pool through recurring channel maintenance contracts.
The International Maritime Organization's dredged material management guidelines, the EPA's ocean dumping criteria in the United States, and the EU Marine Strategy Framework Directive collectively shape equipment specifications by mandating sediment plume monitoring, precision excavation boundaries, and real-time turbidity reporting. These frameworks compel operators to specify automation systems with integrated environmental sensor suites and data logging capabilities as a condition of permit approval. Stakeholders must weigh the capital cost of full fleet automation against phased retrofit strategies as regulatory enforcement tightens across major shipping corridors.
Market Dynamics
Port authorities in Indonesia, Singapore, and Vietnam are consolidating dredging contracts under automated fleet mandates, compressing procurement timelines and forcing equipment suppliers to bundle sensor suites with maintenance service agreements rather than selling discrete hardware.
Growth Catalysts
- IMO Sediment Management Protocols:The International Maritime Organization's tightened ballast water and dredged material guidelines are compelling harbor operators to install real-time turbidity monitoring and precision excavation systems as permit conditions.
- Cutter Suction Automation:Capital dredging and land reclamation projects across Southeast Asia are specifying automated swing control and spud positioning to achieve sub-meter accuracy in dense urban waterways.
- Deep-Sea Port Expansion:Indonesia's Patimban port and Jakarta Bay reclamation are generating continuous demand for unmanned dredging capacity capable of operating in repetitive maintenance cycles.
Market Restraints
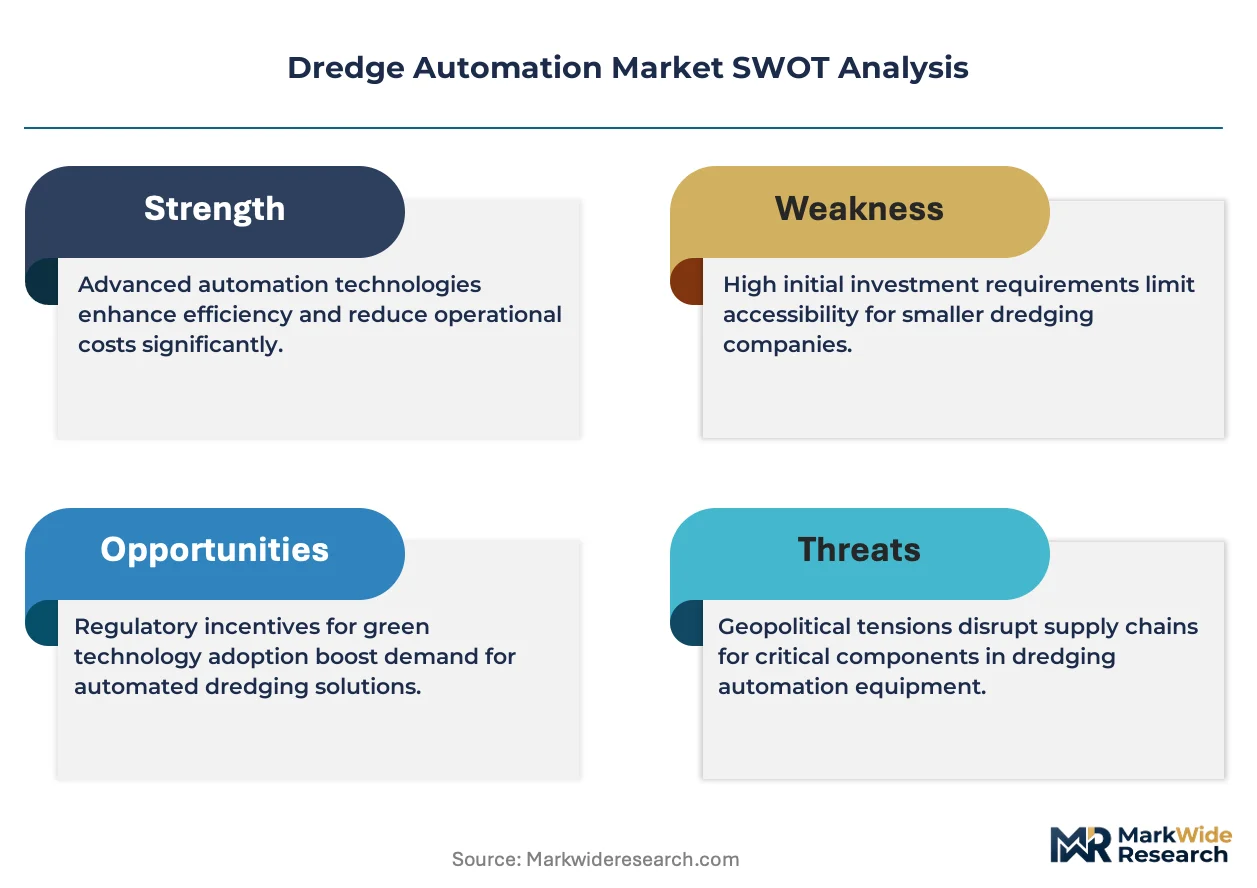
- Specialized Component Supply Concentration:Differential GPS modules and motion reference units for marine environments concentrate among a limited set of European and North American sensor manufacturers, creating procurement bottlenecks.
- Capital Intensity of Full Fleet Conversion:Complete automation retrofits for existing trailing suction hopper dredgers require simultaneous replacement of hydraulic control systems, spud carriage mechanisms, and pump monitoring arrays.
- Skill Scarcity in Marine Mechatronics:Technicians capable of integrating PLC programming with offshore hydraulic systems remain concentrated in established European dredging hubs, limiting deployment velocity in emerging markets.
Strategic Opportunities
- Modular Retrofit Packages:Fleet operators in Indonesia and the Philippines are adopting mix-and-match sensor configurations—GPS positioning, hydraulic monitoring, remote operation modules—rather than monolithic system purchases, opening margin pools for component specialists.
- Environmental Compliance as Service:Real-time sediment plume monitoring and automated reporting systems can be unbundled as subscription offerings, converting capital equipment sales into recurring revenue streams.
- Remote Operation Centers:Harbor authorities in Singapore and Rotterdam are consolidating dredge control into shore-based facilities, eliminating onboard staffing for routine channel maintenance and expanding addressable market for telematics providers.
Industry Challenges
- Integration Complexity with Legacy Hydraulic Systems:Older cutter suction dredgers operate on proprietary analog control architectures that resist direct interface with modern digital sensor networks, requiring expensive middleware development.
- Certification Timeline for Marine Automation:Classification societies and flag state regulators lack harmonized standards for autonomous dredging operations, forcing equipment suppliers to pursue multiple parallel approval processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dredge Automation Market |
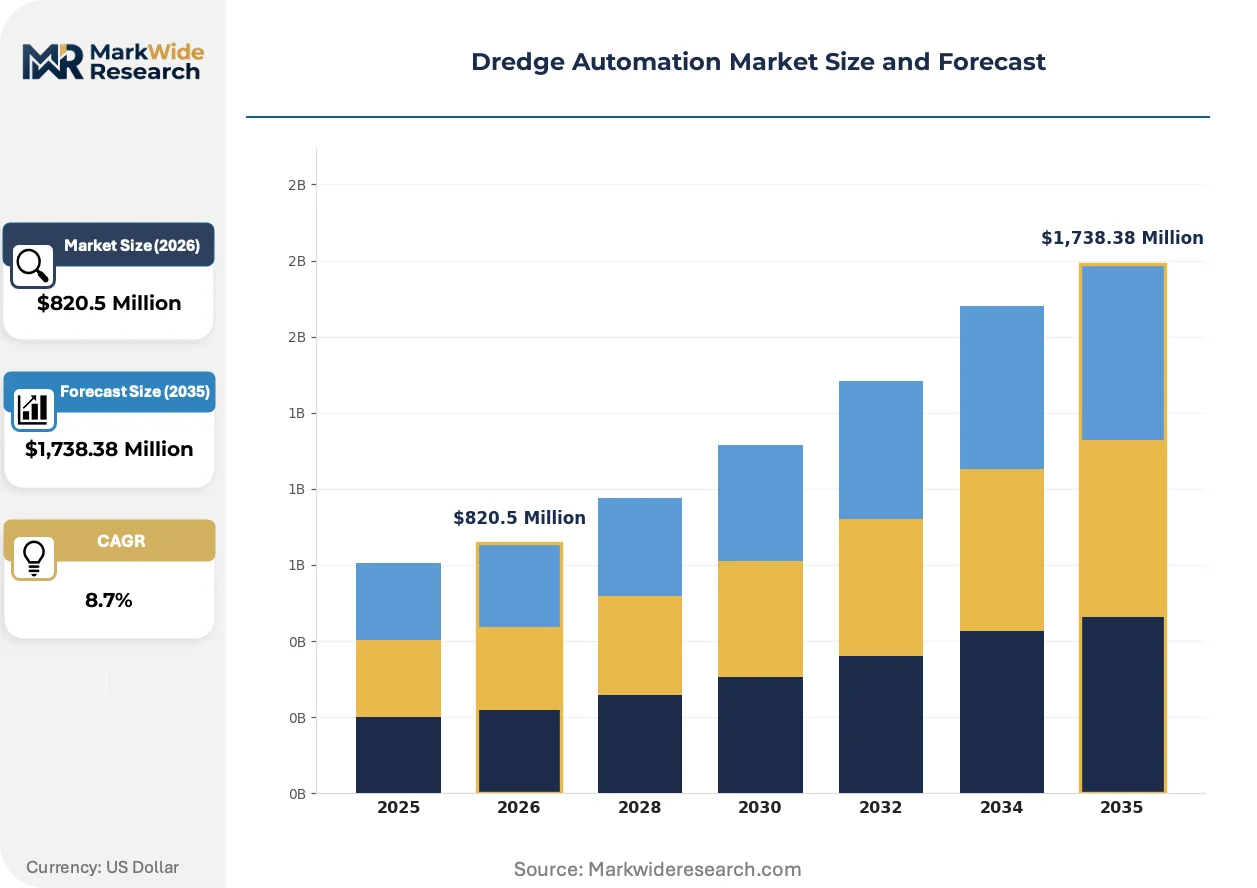
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,738.38 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plow, Cutter Suction Dredger, Backhoe Dredger, Grab Dredger End User: Ports, Construction, Mining, Environmental Technology: Hydraulic, Electric, Automated Control, GPS Deployment Model: Onshore, Offshore, Fleet Management, Remote Operation |
| Companies Covered | TDK Dredging, Imotec, Alewijnse, James Fisher Prolec, DSC Dredge, Aquatics ESI, Marotechniek, Mud Cat Dredges, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dredge Automation Market Trends and Innovations
Edge computing architectures and satellite telemetry are collapsing the latency between vessel sensor arrays and shore-based decision systems, enabling real-time optimization of dredge pump performance and sediment discharge logistics.
Distributed sensor networks is decentralizing control authority from centralized bridge consoles to localized pump monitoring nodes and spud position controllers. Indonesian port operators are deploying these architectures fastest, driven by reclamation project density. The shift is compressing vendor margins on high-value control hardware while expanding software and data service contracts.
REACH substance restrictions and the EU Marine Strategy Framework Directive are mandating closed-loop sediment handling and real-time contaminant detection in European harbor deepening projects. Equipment specifications now require integrated chemical sensor suites and automated sampling protocols. Dutch and Belgian contractors are responding by pre-certifying automation packages for simultaneous compliance across multiple North Sea jurisdictions.
Buyers are unbundling maintenance contracts from initial equipment procurement, separating preventive service agreements from hardware capital expenditure. Port authorities in Singapore and Rotterdam are driving this shift, negotiating multi-year automation performance guarantees independent of vessel purchase financing. The model concentrates risk with equipment suppliers while transferring operational data ownership to harbor operators.
Dredge Automation Market Segmentation
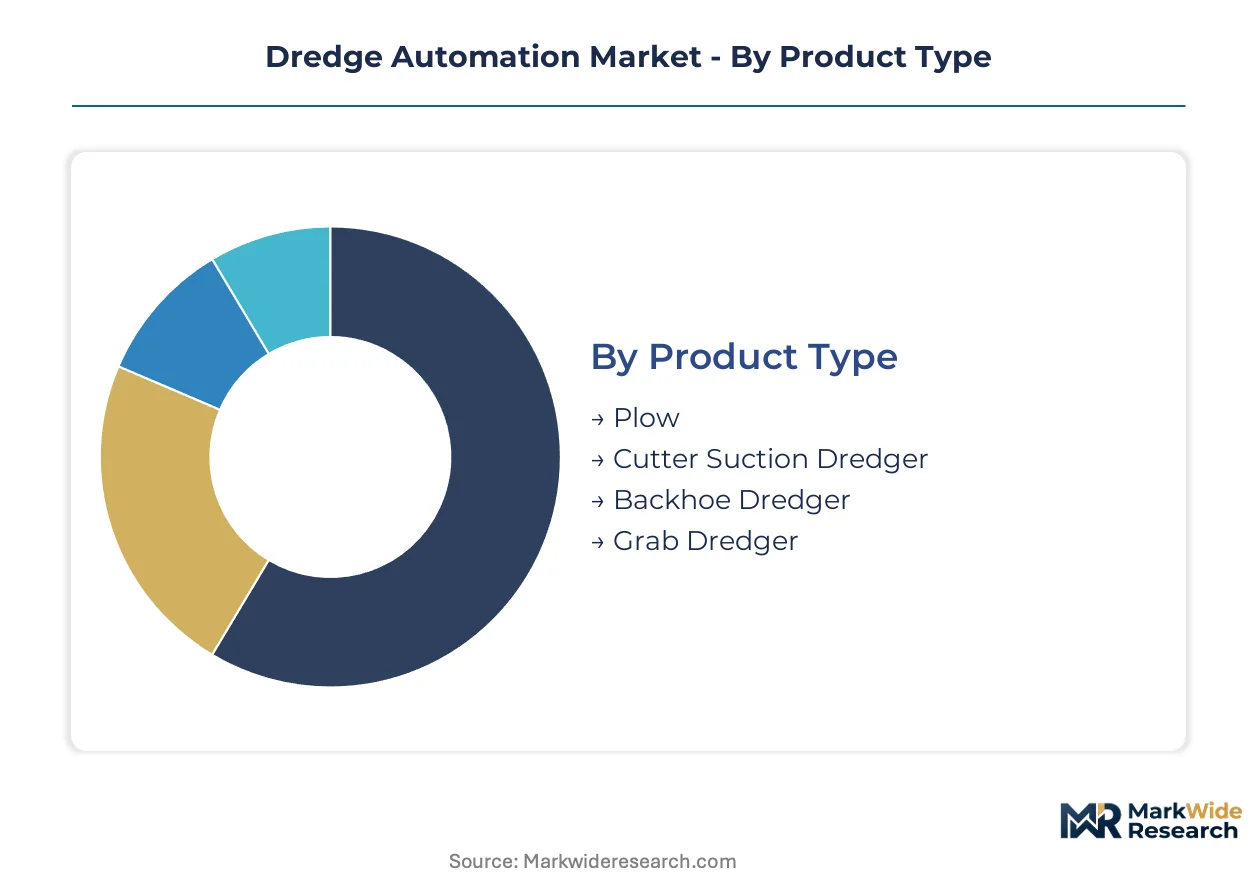
Dredge automation vendors configure their product portfolios across four distinct axes, each commanding different margin profiles and technical service requirements. Equipment suppliers must align sensor integration depth with the operational intensity of specific dredger types and deployment environments.
Product Type:
Component sourcing for automation systems clusters around specialized European sensor manufacturers, concentrating procurement leverage among firms with established marine certification pathways.
- Cutter Suction Dredger:Automation integrates swing angle controllers, spud positioning systems, and pump load sensors to maintain continuous production in capital dredging. Port authorities in Indonesia specify these systems for Jakarta Bay reclamation, where sub-meter accuracy prevents encroachment on protected marine zones. IMO sediment management protocols mandate real-time turbidity feedback loops as permit conditions.
- Grab Dredger:Crane-mounted automation governs grab depth, closing force, and discharge sequencing through programmable logic controllers networked to shore-based monitoring. Singapore's harbor deepening contracts are consolidating procurement under automated fleet mandates, compressing supplier margins on discrete hardware while expanding software service agreements.
- Backhoe Dredger:Excavator-based systems leverage GPS-guided bucket positioning for precision trenching in confined waterways.
- Plow:Seabed leveling automation employs towed arrays with acoustic positioning for pipeline burial and cable route preparation.
Today's leader: Cutter Suction Dredger. Tomorrow's challenger: Grab Dredger.
End User:
Customer procurement patterns diverge sharply between recurring maintenance contracts and one-off capital projects, reshaping how vendors structure performance guarantees and data ownership terms.
- Ports:Channel maintenance automation emphasizes repetitive cycle optimization, with differential GPS and motion reference units achieving positional tolerances under one meter. Indonesian port authorities at Patimban and existing Tanjung Priok facilities are unbundling maintenance contracts from equipment procurement, transferring operational data ownership to harbor operators while concentrating automation risk with suppliers.
- Environmental:Sediment remediation systems integrate chemical sensor suites and automated sampling protocols for contaminant detection. REACH substance restrictions and the EU Marine Strategy Framework Directive are mandating closed-loop handling in North Sea harbor deepening, with Dutch contractors pre-certifying packages for multi-jurisdiction compliance.
- Construction:Land reclamation automation prioritizes production volume over precision, specifying robust pump monitoring for continuous discharge operations.
- Mining:Aggregate extraction systems emphasize durability in abrasive slurry environments, with hydraulic monitoring arrays rated for extended duty cycles.
Ports anchor current revenue. Environmental applications are climbing the fastest.
Technology:
Capital allocation across technology layers reflects divergent paths to margin capture, with hardware commoditization pushing suppliers toward software and data service contracts.
- Automated Control:Programmable logic controllers and distributed sensor networks decentralize authority from bridge consoles to localized pump monitoring nodes. Indonesian operators are deploying these architectures fastest, driven by reclamation project density and compressed procurement timelines under fleet automation mandates.
- GPS:Differential positioning systems achieve sub-meter accuracy through satellite correction signals and motion reference unit fusion. Supply concentrates among limited European and North American manufacturers, creating procurement bottlenecks for fleet-scale deployments.
- Hydraulic:Pressure and flow monitoring arrays govern pump performance and spud carriage mechanics in legacy cutter suction installations.
- Electric:Drive system automation replaces conventional hydraulic powertrains, reducing fuel consumption and enabling finer speed control in environmentally sensitive zones.
Automated Control commands the premium tier. GPS faces supply-side constraints.
Deployment Model:
Operational risk transfer from vessel operators to shore-based control facilities is restructuring staffing models and expanding addressable markets for telematics specialists.
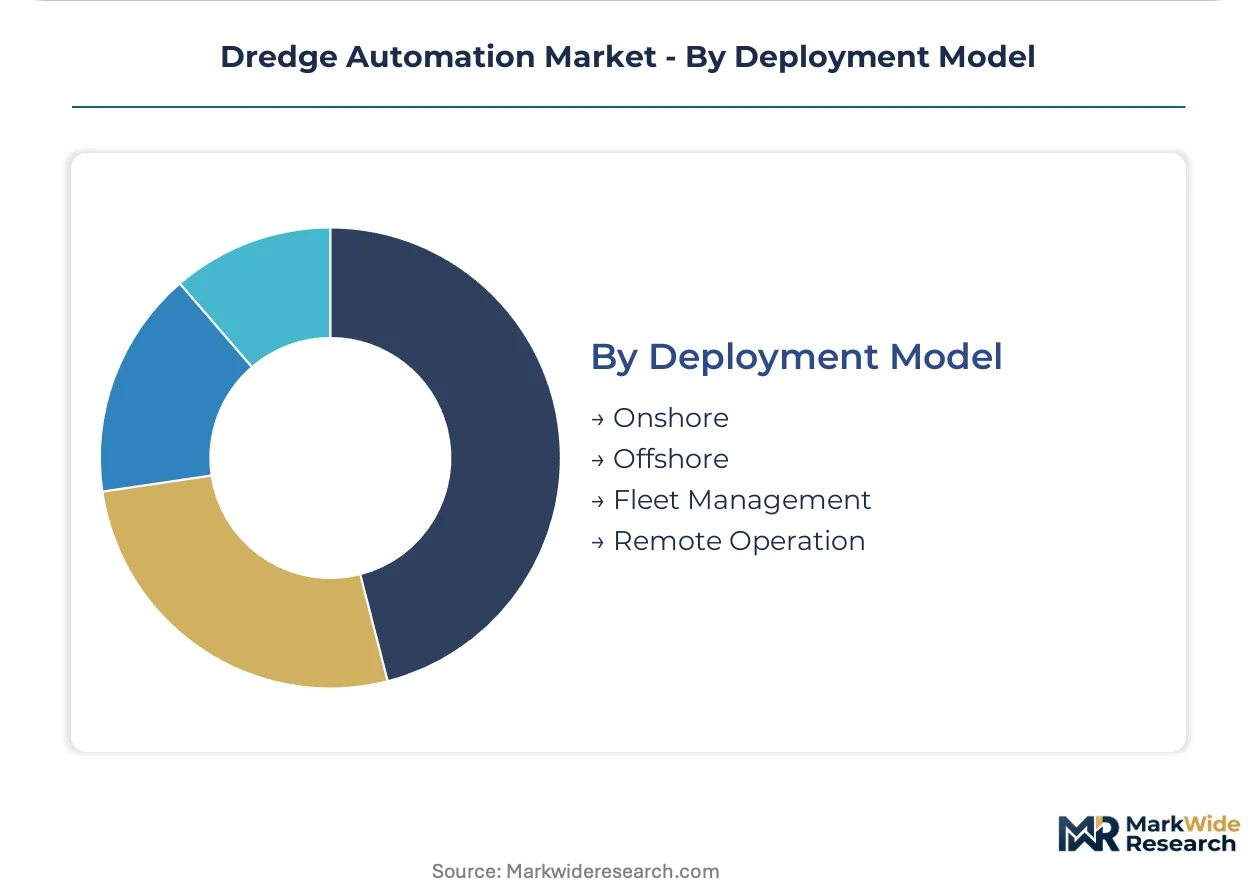
- Remote Operation:Shore-based control centers eliminate onboard staffing for repetitive maintenance cycles, with satellite telemetry collapsing latency between sensor arrays and decision systems. Singapore and Rotterdam harbor authorities are consolidating dredge control into dedicated facilities, generating continuous demand for real-time pump optimization and sediment discharge logistics.
- Fleet Management:Multi-vessel coordination platforms synchronize maintenance scheduling and equipment positioning across dispersed operating areas.
- Offshore:Deep-water automation withstands harsh marine environments, with hardened sensor housings and redundant communication links.
- Onshore:Near-shore and inland waterway systems prioritize cost efficiency over environmental hardening, specifying standard industrial automation components.
Remote Operation is expanding most quickly. Fleet Management offers the steadiest contract visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated dredging systems emerged from Dutch hydraulic engineering traditions in the Rhine-Meuse-Scheldt delta, where precision sediment management became essential for maintaining Europe's densest waterway network. This technical heritage now diffuses across Southeast Asian port expansion programs and North American environmental remediation projects.
Indonesia
Jakarta Bay reclamation and the Patimban deep-sea port project drive continuous demand for unmanned dredging capacity. The country's national port authority mandates automated fleet specifications for all new channel maintenance contracts. Surabaya and Tanjung Priok facilities are unbundling maintenance agreements from equipment procurement, transferring operational data ownership to harbor operators.
Singapore
The Maritime and Port Authority's fleet automation directives compress procurement timelines for sensor-integrated dredging systems. Shore-based control centers eliminate onboard staffing for repetitive maintenance cycles across the Strait of Singapore. Tuas Port expansion is consolidating dredge control into dedicated remote operation facilities, generating demand for real-time pump optimization.
Netherlands
REACH substance restrictions and the EU Marine Strategy Framework Directive mandate closed-loop sediment handling in North Sea harbor deepening. Dutch contractors pre-certify automation packages for simultaneous compliance across multiple European jurisdictions. Rotterdam harbor authorities negotiate multi-year automation performance guarantees independent of vessel purchase financing.
United States
EPA ocean dumping criteria shape equipment specifications by mandating sediment plume monitoring and precision excavation boundaries. Gulf Coast port authorities specify automation systems with integrated environmental sensor suites as conditions of permit approval. Houston and New Orleans channel maintenance programs are retrofitting legacy cutter suction dredgers with modular sensor-and-control packages.
Vietnam
Cai Mep-Thi Vai deep-water port expansion and Lach Huyen terminal development require automated swing control for sub-meter accuracy. The country's transport ministry is consolidating dredging contracts under fleet automation mandates. Hai Phong port operators are adopting mix-and-match sensor configurations rather than monolithic system purchases.
Dredge Automation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sensor integration depth and marine certification pathways. The vendor base organizes around three strategic archetypes: European electrical control specialists, precision positioning technology developers, and cutter suction automation engineers. Consolidation pressure is accelerating as port authorities bundle sensor suites with maintenance service agreements. Dominant competitive moves include geographic expansion into Southeast Asian procurement clusters and technology licensing partnerships for modular retrofit architectures.
Within the electrical and control systems tier, Alewijnse anchors European harbor deepening projects through sustained presence across North Sea jurisdictions. DSC Dredge occupies a position exemplifying specialized cutter suction automation for mining and construction channel applications. James Fisher Prolec represents precision dredge positioning technology that leverages integrated sensor fusion architectures. These three entities illustrate how component specialists capture margin pools as fleet operators adopt mix-and-match configurations over monolithic system purchases.
| Leading Market Players |
|---|
| TDK Dredging |
| Imotec |
| Alewijnse |
| James Fisher Prolec |
| DSC Dredge |
| Aquatics ESI |
| Marotechniek |
| Mud Cat Dredges |
| Xylem |
| Others |
Pricing and Supply Chain Analysis
Marine mechatronics technicians concentrated in Dutch and Belgian dredging hubs command wage premiums that compress margins on standard automation packages while widening spreads between premium certified systems and economy retrofit tiers. Labor-cost differentials between European engineering centers and Southeast Asian deployment sites force equipment suppliers to unbundle software service contracts from hardware capital expenditure, transferring pricing risk to buyers seeking modular configurations.
Pricing Analysis
Project-based contracting with multi-year performance guarantees dominates procurement for port authority fleet mandates, with pricing stratifying across IMO-certified precision systems, regional-standard automation packages, and economy-grade sensor retrofit kits. Price differentiation rests on certification depth and real-time environmental reporting capability, with Dutch and Belgian contractors capturing premiums for pre-certified multi-jurisdiction compliance. Cost compression in economy tiers is intensifying because Indonesian and Philippine operators are mixing discrete GPS, hydraulic, and remote operation modules rather than purchasing integrated platforms. Environmental end-users exhibit lowest price sensitivity due to regulatory non-compliance penalties, while construction sector buyers prioritize capital efficiency over precision specifications.
Supply Chain Analysis
Single-source vulnerability sits with differential GPS module and motion reference unit suppliers concentrated in Germany, the Netherlands, and the United States, creating procurement bottlenecks for fleet-scale deployments across Southeast Asia. Component sourcing draws from specialized European sensor manufacturers for marine-certified positioning systems, North American suppliers for satellite telemetry hardware, and East Asian fabricators for standard industrial control enclosures. Supply chain risk centers on tariff exposure for precision electronics crossing from European engineering hubs to Indonesian port construction sites. Distribution runs through OEM equipment bundling for newbuild dredgers and authorized service networks for aftermarket retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dredge automation market represents a late-cycle quality story as port authorities shift procurement criteria from capital cost minimization toward total-cost-of-ownership optimization through automated fleet performance guarantees. Premium specifications for real-time turbidity monitoring and sub-meter positioning accuracy are displacing price-first purchasing across Indonesian and Singaporean harbor deepening contracts.
For Market Incumbents: Anticipate margin compression from modular retrofit specialists by accelerating certification investments for simultaneous compliance across IMO, EPA, and EU Marine Strategy Framework Directive jurisdictions. Defensive consolidation should prioritize backward integration into sensor fusion software and captive supply of motion reference units to reduce exposure to European component supply bottlenecks. Shore-based remote operation center contracts in Singapore and Rotterdam offer channel control leverage against emerging telematics entrants.
For New Entrants and Emerging Players: Small-to-mid sized environmental remediation contractors in Vietnam and the Philippines represent an underserved buyer archetype with limited access to integrated automation platforms from established European vendors. White-space targets include subscription-based sediment plume monitoring services unbundled from capital equipment sales, and mix-and-match GPS-hydraulic-remote operation modules for legacy cutter suction dredger retrofit. Go-to-market execution should anchor on regional service partnerships with Indonesian port maintenance operators seeking alternatives to OEM-locked maintenance agreements.
For Investors and Strategic Acquirers: Port authority automation procurement offices are the most active acquirer in this space, consolidating dredging contracts under fleet mandates that favor suppliers with integrated environmental compliance capabilities. Long-term viability over a five-to-ten year horizon rests on regulatory enforcement intensity rather than commodity shipping volume cycles. Acquisition targets should screen for marine certification pathway depth and established presence across multiple North Sea and Southeast Asian jurisdictions. The signal to watch is harmonization progress between classification societies on autonomous dredging operation standards, which would collapse parallel approval cost burdens and accelerate vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification for Multi-Jurisdiction Compliance | Dutch contractors capture pricing premiums by front-loading IMO, EPA, and EU Marine Strategy Framework Directive approval costs. |
| Modular Sensor-Package Development | Component specialists displace monolithic system vendors as Indonesian operators mix GPS, hydraulic, and remote operation modules. |
| Remote Operation Center Infrastructure | Singapore and Rotterdam harbor authorities eliminate onboard staffing through shore-based dredge control consolidation. |
| Environmental Compliance-as-Service Unbundling | Subscription revenue models convert capital equipment sales into recurring turbidity monitoring and automated reporting streams. |
| Backward Integration into Sensor Manufacturing | Equipment suppliers reduce European GPS module supply vulnerability through captive production of motion reference units. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dredge fleet managers, port authority procurement officers, marine automation engineers, and environmental compliance consultants with secondary validation from IMO sediment management protocol filings, EPA ocean dumping permit databases, EU Marine Strategy Framework Directive implementation reports, and customs trade data on dredging equipment imports. Bottom-up vessel automation installation tracking and top-down port infrastructure investment assessments were triangulated against manufacturer order backlogs.
Historical reference periods anchored the projection horizon to capital dredging contract award cycles and regulatory enforcement phase-in timelines across the analysis window. The analytical framework modeled segmentation dimensions including dredger type, end-user sector, technology layer, and deployment model, with CAGRs derived from regression against port throughput growth and channel maintenance contract value trends. Industry-specific forecast inputs incorporated satellite telemetry latency reduction curves and classification society autonomous operation standard development progress.
Underlying measurement precision varies by segment; cutter suction dredger automation carries tighter precision than grab dredger or plow system estimates due to more concentrated vendor reporting. Forecasts reflect documented assumptions regarding IMO protocol enforcement intensity and Indonesian port expansion commitment continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
Crane Motors Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Global Construction Machinery Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market