
 Zero Energy Buildings Market | 2026-2036
Zero Energy Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Zero Energy Buildings Market Outlook
LEED certification is collapsing as the sole gateway for premium zero energy projects, with BREEAM, Passive House, and regional net-zero standards fragmenting qualification pathways. Siemens AG leverages its building automation portfolio to anchor European commercial retrofits. Schneider Electric competes through integrated microgrid and energy management platforms. Kingspan Group Plc specializes in high-performance envelope systems that reduce thermal bridging in prefabricated assemblies.
Zero energy buildings achieve net annual energy consumption of approximately zero through on-site renewable generation matched to demand, typically requiring envelope U-values below 0.15 W/m²K and airtightness below 0.6 air changes per hour at 50 Pascals. Their primary purpose is eliminating operational carbon emissions from heating, cooling, ventilation, and plug loads across the building lifecycle. Residential applications lead volume deployment where modular construction methods compress delivery timelines, while commercial segments concentrate margin pools through integrated smart grid and energy storage configurations. Solar PV dominates technology adoption due to declining module costs, though wind energy and storage pairings are gaining traction in larger institutional footprints.
The US Department of Energy's Zero Energy Ready Home program and the EU Energy Performance of Buildings Directive tighten efficiency thresholds that reshape product specifications and market access conditions. California's Title 24 and Germany's Building Energy Act impose enforceable operational carbon limits that filter supplier participation. Stakeholders must monitor how efficiency standard fragmentation across jurisdictions affects certification costs and cross-border equipment compatibility.
Market Dynamics
Building-integrated photovoltaics is miniaturizing rapidly, collapsing the physical and cost barriers that once separated renewable generation from architectural envelope design. This technology convergence is compressing payback periods and forcing envelope manufacturers to requalify as energy asset suppliers.
Growth Catalysts
- California Title 24 mandates:Near-zero operational carbon requirements for new residential permits are pulling high-performance HVAC and smart control systems into standard specifications.
- Phase-change materials:Thermal storage integration in lightweight assemblies is reducing peak cooling loads in commercial retrofits across Germany and the United Kingdom.
- Municipal net-zero ordinances:Cities in Denmark, France, and the Netherlands are extending carbon performance requirements to existing building renovations.
Market Restraints
- High-performance glazing supply concentration:Triple-pane vacuum-insulated production capacity clusters in Central Europe, creating import bottlenecks for North American projects.
- Skilled installer scarcity:Airtightness detailing and thermal-bridge-free construction demand specialized labor pools that training infrastructure has not scaled.
- Utility interconnection delays:Grid-tie approval timelines for on-site generation stretch 8-14 months in jurisdictions with understaffed permitting offices.
Strategic Opportunities
- Industrial facility retrofits:Warehouse and logistics properties in Poland and the Czech Republic present untapped envelope upgrade potential ahead of EU Energy Performance of Buildings Directive deadlines.
- Heat pump-BIPV pairing:Integrated system packages that merge electrified heating with rooftop generation are opening multi-family residential segments previously blocked by split incentives.
- Performance-based insurance:New underwriting products that guarantee actual energy outcomes against design predictions are reducing developer risk perception.
Industry Challenges
- Commissioning complexity:The gap between modeled and measured energy performance requires specialized building science expertise that project teams rarely retain post-handover.
- Certification fragmentation:Competing net-zero verification frameworks create administrative overhead and delay financing approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero Energy Buildings Market |
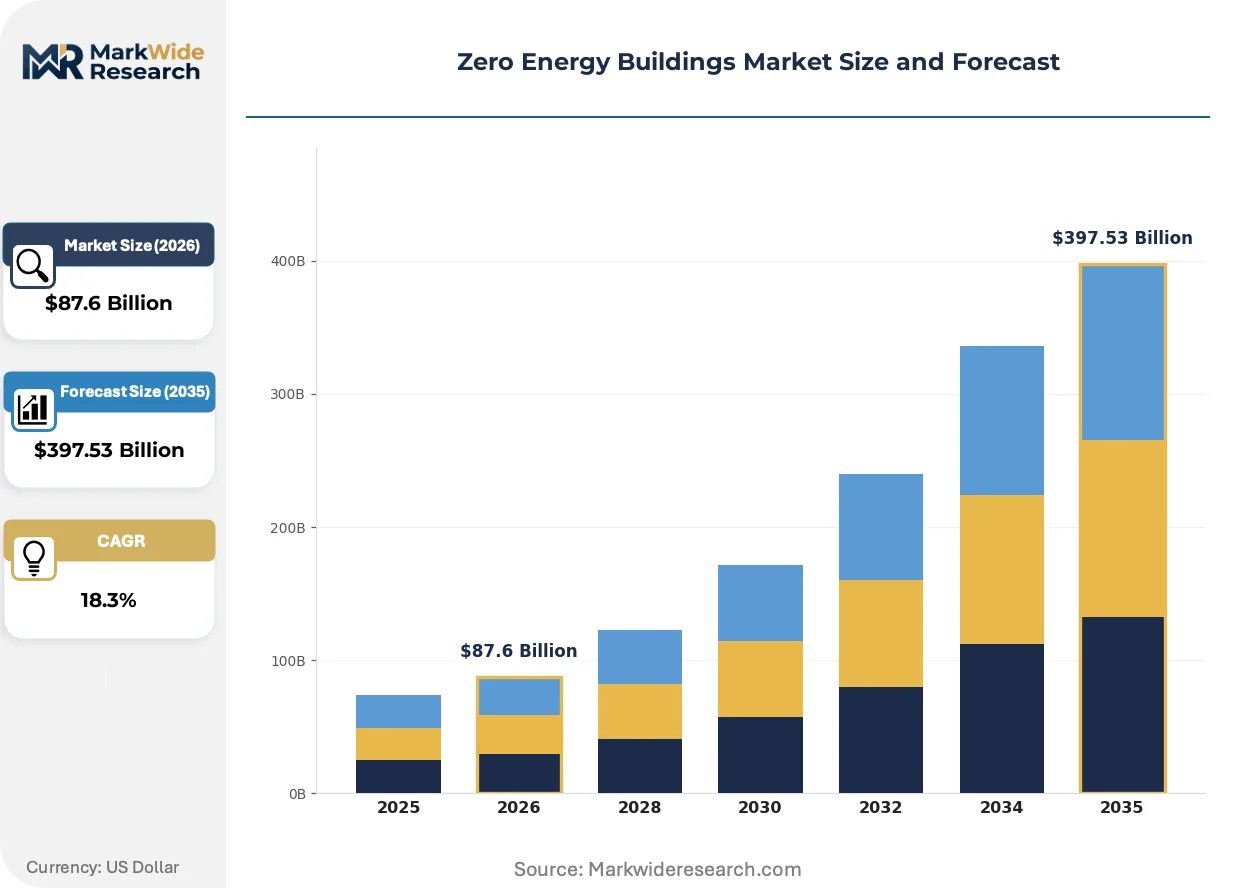
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $397.53 Billion |
| CAGR (2026 – 2036) | 18.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Residential, Commercial, Institutional, Industrial Technology: Solar PV, Wind Energy, Energy Storage, Smart Grid Construction Method: Modular, Prefabricated, Traditional, Renovation Efficiency Standard: LEED, BREEAM, Energy Star, Passive House |
| Companies Covered | Schneider Electric, Siemens AG, Johnson Controls, Daikin Industries Ltd., Honeywell International Inc., General Electric Company, Kingspan Group Plc, SunPower Corporation, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero Energy Buildings Market Strategic Shifts
Envelope technology is converging with active energy systems, dissolving the traditional boundary between passive conservation and on-site generation. This fusion is redrawing competitive boundaries and supplier value capture.
Building-integrated photovoltaics is miniaturizing from rooftop arrays to facade-embedded thin-film and transparent organic PV layers. Commercial developers in Germany and California are specifying these systems for curtainwall retrofits where roof area is constrained. The technology is miniaturizing energy generation into architectural surfaces previously treated as pure cost centers.
The EU Energy Performance of Buildings Directive is tightening operational carbon thresholds for existing stock, not just new construction. Member states must transpose these requirements into national law by specified deadlines, triggering renovation waves in France, Italy, and Spain. Residential landlords in Germany are responding by bundling envelope upgrades with heat pump installations to meet combined efficiency mandates.
Institutional buyers are unbundling design-build contracts into separate performance-guarantee and construction-risk components. Pension funds and real estate investment trusts in the United Kingdom and the Netherlands are demanding fixed energy-cost outcomes rather than efficiency specifications. This shift is elevating energy service companies and specialist contractors over traditional general contractors in project control.
Zero Energy Buildings Market Segmentation
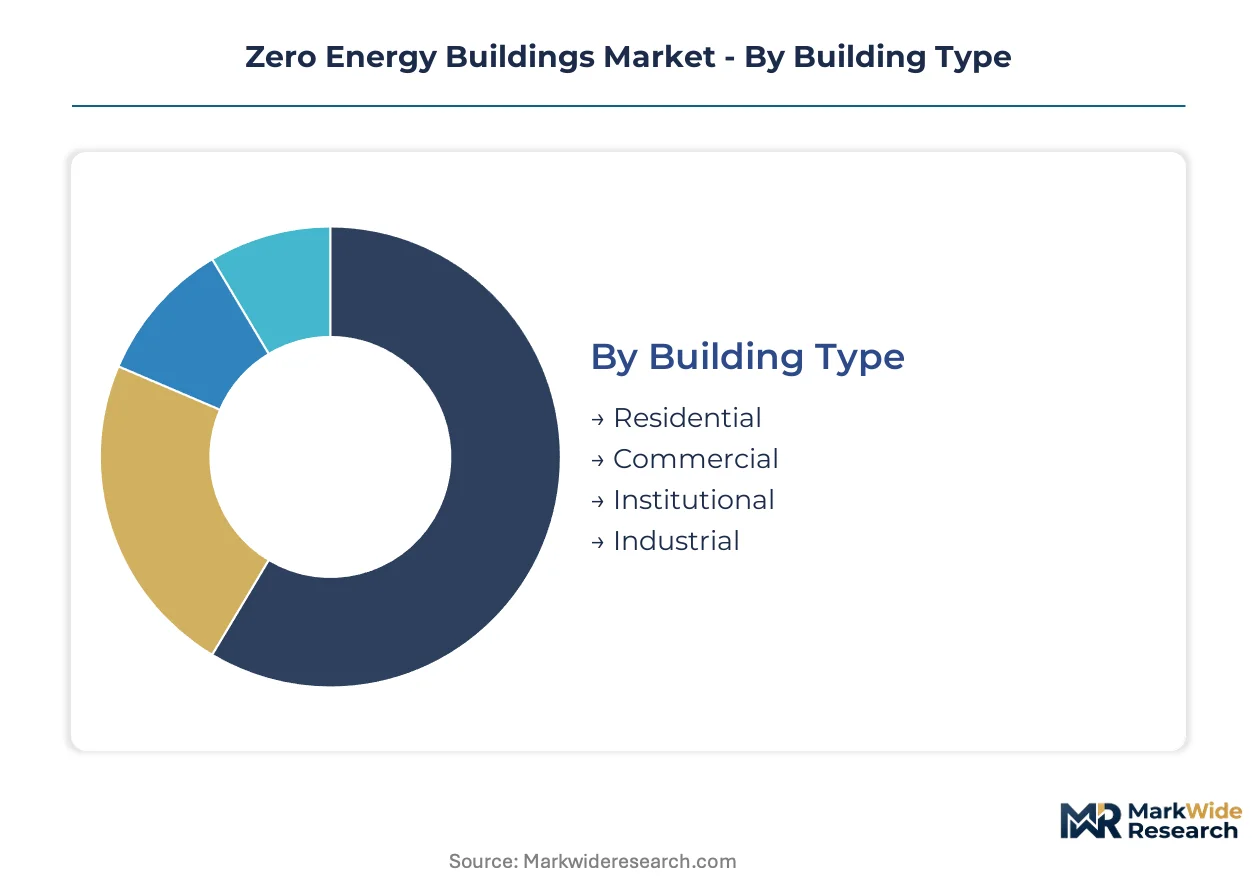
Zero energy buildings fragment across four distinct classification systems that reshape procurement patterns and supplier access. Building type determines financing structures and regulatory pathways. Technology selection and construction method dictate which contractors qualify for project awards.
Building Type:
Residential construction concentrates in domestic markets where local building codes enforce efficiency minimums, while commercial and industrial segments attract cross-border equipment suppliers seeking scale.
- Residential:Single-family and multi-family units dominate unit volumes, with modular construction compressing delivery timelines in California and Germany. California's Title 24 mandates pull high-performance HVAC and envelope systems into standard specifications for new permits.
- Commercial:Office and retail properties concentrate margin pools through integrated smart grid and energy storage configurations. Pension funds in the United Kingdom and the Netherlands are demanding fixed energy-cost outcomes rather than efficiency specifications alone.
- Institutional:Schools and hospitals in Denmark and the Netherlands face municipal net-zero ordinances extending carbon requirements to existing building renovations.
- Industrial:Warehouse and logistics properties in Poland and the Czech Republic present envelope upgrade potential ahead of EU Energy Performance of Buildings Directive deadlines.
Residential holds the largest share; momentum sits with Commercial as institutional buyers unbundle design-build contracts into performance-guarantee components.
Technology:
Cost tiers separate mature photovoltaic deployment from emerging storage pairings that command premium pricing in commercial applications.
- Solar PV:Building-integrated photovoltaics miniaturizes from rooftop arrays to facade-embedded thin-film layers, collapsing physical barriers between generation and envelope design. Germany and California developers specify these systems for curtainwall retrofits where roof area is constrained.
- Energy Storage:Battery integration enables load-shifting and grid-independence verification, with heat pump-BIPV pairings opening multi-family residential segments previously blocked by split incentives.
- Wind Energy:Small-scale turbines gain traction in larger institutional footprints where roof-mounted solar proves insufficient.
- Smart Grid:Utility interconnection delays stretching 8-14 months in understaffed jurisdictions constrain deployment velocity despite technology readiness.
Solar PV captures the dominant deployment share; storage integration is climbing the fastest as performance-based insurance products reduce developer risk perception.
Construction Method:
Volume concentration favors factory-controlled modular and prefabricated approaches that guarantee airtightness outcomes, while traditional methods retain share in renovation-heavy markets.
- Modular:Factory production compresses delivery timelines and enables thermal-bridge-free assembly through precision manufacturing. Residential applications lead volume deployment where speed-to-occupancy drives developer returns.
- Prefabricated:Kingspan Group Plc and envelope specialists supply high-performance panelized systems that reduce on-site skilled labor dependency.
- Traditional:Stick-built methods persist in markets with limited modular supply chain infrastructure or where existing trade relationships dominate procurement.
- Renovation:Deep energy retrofits of existing stock accelerate across France, Italy, and Spain as EU Energy Performance of Buildings Directive requirements transpose into national law.
Modular commands the steepest expansion trajectory; prefabricated maintains stable share in commercial segments where envelope performance guarantees are contractually required.
Efficiency Standard:
Certification fragmentation creates administrative overhead that filters supplier participation, with regional standards displacing legacy frameworks in procurement specifications.
- Passive House:Airtightness thresholds below 0.6 air changes per hour at 50 Pascals and envelope U-values below 0.15 W/m²K define the technical frontier. Germany's Building Energy Act imposes enforceable operational carbon limits that align with this standard's specifications.
- BREEAM:United Kingdom and Netherlands institutional investors favor this framework for asset benchmarking, fragmenting qualification pathways previously dominated by LEED.
- LEED:North American commercial developers retain this standard for market recognition, though its dominance collapses as sole gateway for premium zero energy projects.
- Energy Star:United States residential builders leverage this EPA program for consumer-facing efficiency claims in mass-market housing.
Passive House holds the highest technical specification share; BREEAM is gaining share fastest among institutional capital sources seeking comparable asset benchmarking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pension funds and municipal governments in Germany, California, and the United Kingdom concentrate procurement authority for premium zero energy assets, filtering supplier access through enforceable operational carbon limits and performance-guarantee contract structures.
United States
California's Title 24 mandates pull high-performance HVAC and smart control systems into standard specifications for new residential permits. The EPA's Energy Star program provides consumer-facing efficiency benchmarks for mass-market housing developers. Los Angeles and San Diego clusters drive BIPV curtainwall retrofits where roof area constraints limit traditional solar deployment.
Germany
The Building Energy Act imposes enforceable operational carbon limits that align with Passive House airtightness thresholds below 0.6 air changes per hour. Municipal net-zero ordinances in Berlin and Hamburg extend carbon performance requirements to existing building renovations. Bavarian industrial zones concentrate heat pump-BIPV pairing deployments for multi-family residential segments.
United Kingdom
BREEAM certification fragments qualification pathways previously dominated by LEED, with institutional investors demanding fixed energy-cost outcomes. The country's national building regulator enforces efficiency minimums that reshape product specifications. London and Southeast England concentrate pension fund capital deployment into performance-guarantee contract structures.
France
The EU Energy Performance of Buildings Directive transposition triggers renovation waves across Île-de-France and Auvergne-Rhône-Alpes. National efficiency mandates filter supplier participation through administrative overhead and certification costs. Lyon and Marseille present deep energy retrofit potential in existing commercial stock ahead of directive deadlines.
Netherlands
Municipal net-zero ordinances in Amsterdam and Rotterdam extend carbon requirements to existing building renovations. Institutional capital from Dutch pension funds demands fixed energy-cost outcomes rather than efficiency specifications alone. Randstad corridor concentrates integrated smart grid and energy storage configurations for commercial properties.
Zero Energy Buildings Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with building automation and energy management portfolios, creating a tiered structure where envelope specialists and solar manufacturers occupy adjacent but distinct competitive positions. Strategic archetypes include integrated building systems providers, high-performance envelope fabricators, and renewable generation equipment suppliers. Dominant competitive moves center on technology convergence partnerships and backward integration into energy storage and microgrid control systems.
Among diversified industrial conglomerates, Schneider Electric, Siemens AG, and Kingspan Group Plc represent three distinct archetype anchors. Schneider Electric exemplifies the integrated microgrid and energy management platform position. Siemens AG occupies a position within building automation portfolios anchoring European commercial retrofits. Kingspan Group Plc sits within the high-performance envelope specialist tier, with its Plc structure indicating UK-listed status and prefabricated assembly focus.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| Johnson Controls |
| Daikin Industries Ltd. |
| Honeywell International Inc. |
| General Electric Company |
| Kingspan Group Plc |
| SunPower Corporation |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Fourteen-month utility interconnection queues in California and Germany compress developer cash conversion cycles and force premium pricing for expedited grid-tie approvals, concentrating margin capture among integrated energy service companies with pre-approved microgrid configurations.
Pricing Analysis
Cost-plus contracts indexed to steel and polysilicon spot markets dominate commercial envelope procurement, with German and Czech fabricators passing through raw material volatility via quarterly adjustment clauses. Price differentiation rests on Passive House certification tier and factory-controlled modular delivery versus site-built stick construction. Pricing pressure stems from skilled installer scarcity that elongates project timelines and inflates labor contingency reserves. Mass-market residential developers in California exhibit highest price sensitivity, while Dutch pension funds deploying performance-guarantee structures demonstrate lowest sensitivity.
Supply Chain Analysis
Triple-pane vacuum-insulated glass production chokepoints in Austria and Germany constrain North American project timelines and inflate glazing package costs. Supply draws from Chinese polysilicon ingots, South Korean BIPV laminators, and Central European framing systems. Single-source vulnerability concentrates in high-performance glazing substrates where alternative qualification pathways require 18-24 month thermal cycling validation. Distribution runs through regional envelope specialists who bundle panelized systems with installation labor pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero energy buildings are shifting toward platform economics where interoperability between envelope, generation, and control systems determines supplier viability, with California's Title 24 and Germany's Building Energy Act mandating open-protocol energy management as a condition of permit approval.
For Market Incumbents: Consolidate control over heat pump-BIPV pairing supply chains through backward integration into inverter and thermal storage manufacturing, defending against modular construction entrants who bypass traditional specification channels. Anchor position in California and Germany through captive installation labor pools certified to Passive House airtightness protocols.
For New Entrants and Emerging Players: Lead with performance-based insurance products that guarantee actual energy outcomes against design predictions, targeting Polish and Czech industrial retrofits where EU Energy Performance of Buildings Directive deadlines compress procurement timelines and legacy suppliers lack underwriting capabilities. Pursue direct contracting with warehouse REITs ahead of 2030 compliance cliffs.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional efficiency standard fragmentation creates acquisition opportunities for compliance-technology platforms that consolidate certification workflows across LEED, BREEAM, and Passive House frameworks. Target envelope fabricators with pre-qualified curtainwall systems for constrained-roof commercial retrofits in Los Angeles and London. Monitor municipal net-zero ordinance adoption velocity as the signal for renovation-wave timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump-BIPV System Integration | Combined electrified heating and rooftop generation packages unlock multi-family residential segments previously blocked by split incentive structures. |
| Performance-Based Insurance Launch | Underwriting products guaranteeing actual energy outcomes against design predictions reduce developer risk perception and accelerate financing approvals. |
| Prefabricated Envelope Capacity Expansion | Factory-controlled panelized systems guarantee airtightness outcomes and reduce on-site skilled labor dependency in Germany and California. |
| Smart Grid Interoperability Certification | Open-protocol energy management platforms satisfy California Title 24 and Germany Building Energy Act permit requirements. |
| Industrial Retrofit Partnership Program | Direct contracting with Polish and Czech warehouse operators captures envelope upgrade demand ahead of EU directive deadlines. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, construction permit databases, and equipment shipment records, combining interviews with building automation engineers, envelope procurement leads at German and Dutch developers, utility interconnection officers, and Passive House certifiers with validation against California Title 24 compliance data, EU Energy Performance of Buildings Directive transposition timelines, and BIPV trade flow statistics. Bottom-up project pipeline analysis triangulates against top-down equipment capacity and efficiency standard adoption curves.
Segmentation dimensions modeled span building type, technology configuration, construction method, and efficiency standard certification across the projection horizon, with CAGRs derived from regression against historical permit issuance and equipment deployment trajectories. Forecast inputs incorporate municipal net-zero ordinance adoption schedules and skilled installer training pipeline capacity.
Forecasts assume regulatory continuity in California Title 24, Germany Building Energy Act, and EU Energy Performance of Buildings Directive enforcement regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as utility interconnection staffing levels and phase-change material cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
United States Smart Windows Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Global Door Closers Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
United States Building Automation Controls Market