
 North America Building Automation System Market | 2026-2036
North America Building Automation System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Building Automation System Market Insights
Systems integrator relationships are rewriting how building automation reaches end users across North America. Johnson Controls International PLC leverages its direct channel strength to lock in long-term service contracts with institutional buyers. Siemens AG competes through deep vertical expertise in healthcare and data center environments. Schneider Electric SE anchors its position with EcoStruxure platforms that bridge on-premise and cloud architectures.
Building automation systems integrate sensors, controllers, and software to regulate HVAC, lighting, security, and energy flows within commercial and industrial structures, typically operating through BACnet or Modbus protocols with response latencies under 100 milliseconds for critical climate adjustments. HVAC Control commands the largest installed base due to code-mandated efficiency minimums, while Cloud-Based Solutions represent the fastest expansion vector as remote diagnostics displace truck rolls. IoT-Enabled Devices concentrate margin pools at the edge, where embedded analytics reduce central server loads.
EPA ENERGY STAR certification, ASHRAE Standard 90.1, and Canadian NECB amendments collectively raise baseline performance thresholds that obsolete legacy pneumatic controls. The US Department of Energy enforces federal efficiency mandates that filter down to state adoption timelines. Stakeholders must weigh capital allocation between wireless retrofit architectures and full rip-and-replace strategies as utility rebate programs shift toward measured outcome verification.
Market Dynamics
The convergence of utility decarbonization mandates with wireless retrofit architectures is restructuring capital deployment patterns across North American commercial real estate. Building operators now face binary choices between measured outcome verification paths and traditional equipment replacement cycles.
Growth Catalysts
- ASHRAE Standard 90.1 stringency:Federal efficiency minimums cascade through state adoption timelines, forcing pneumatic control obsolescence in Class B office stock across the United States.
- Data center thermal loads:Hyperscale facilities in Northern Virginia and Dallas-Fort Worth are driving demand for precision cooling integration with building-wide energy management platforms.
- Canadian NECB amendments:Provincial adoption of the National Energy Code for Buildings tightens envelope and mechanical performance thresholds in Ontario and British Columbia commercial construction.
Market Restraints
- Semiconductor input volatility:BACnet chip and sensor microcontroller supply concentration in East Asian foundries creates lead time unpredictability for controller manufacturers.
- Legacy protocol fragmentation:Persistent Modbus and proprietary fieldbus installations in existing buildings complicate unified platform deployment and extend commissioning cycles.
- Skilled technician scarcity:Unionized controls programming expertise concentrates in major metropolitan labor pools, constraining rollout velocity in secondary markets.
Strategic Opportunities
- Electrification mandates:California's Title 24 building standards and New York City's Local Law 97 create compliance-driven replacement cycles for fossil fuel heating systems.
- Edge analytics convergence:Embedded machine learning on IoT sensors is hybridizing with cloud platforms to enable predictive maintenance without continuous connectivity.
- Utility outcome verification:Rebate program structures in Ontario and Massachusetts are shifting toward measured savings, favoring vendors with performance-guaranteed service models.
Industry Challenges
- Controls programming talent gap:BACnet/IP and wireless commissioning expertise lags behind hardware deployment capacity, extending project timelines in the Mountain West.
- Multi-vendor integration complexity:Open protocol adoption varies across HVAC, lighting, and security subsystems, forcing costly middleware development for unified dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Building Automation System Market |
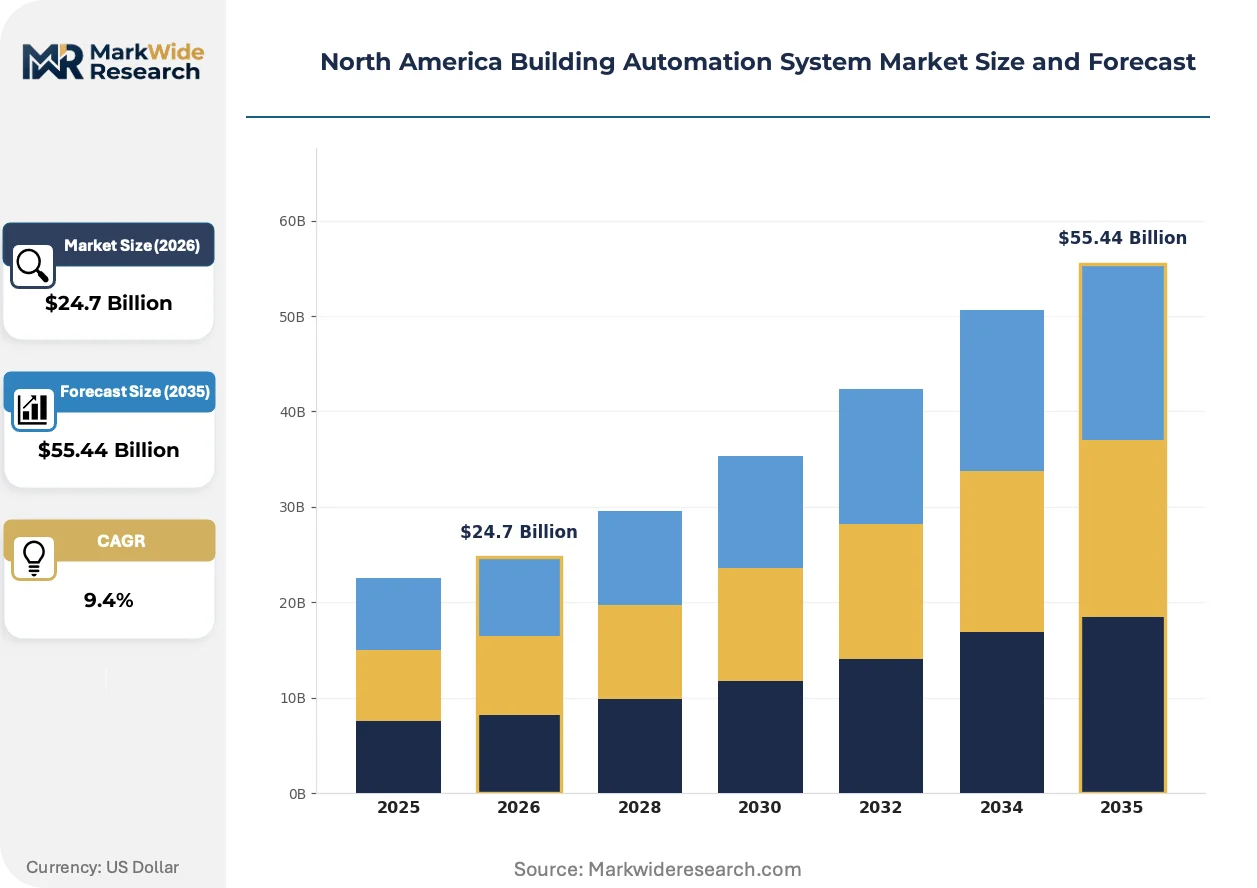
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $55.44 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control, HVAC Control, Security Systems, Access Control End User: Commercial Buildings, Residential Buildings, Industrial Facilities, Educational Institutions Technology: Wired Systems, Wireless Systems, Cloud-Based Solutions, IoT-Enabled Devices Application: Energy Management, Environmental Monitoring, Security Management, Remote Control |
| Companies Covered | Honeywell International Inc., Johnson Controls International PLC, Siemens AG, Schneider Electric SE, ABB Ltd, Trane Technologies plc, Carrier Global Corporation, Delta Controls Inc., Lutron Electronics Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Building Automation System Market Trends and Innovations
Digital twin architectures and edge-native analytics are compressing the traditional design-build-operate lifecycle for commercial building systems. Vendors are repositioning around continuous optimization services rather than discrete equipment sales.
Wireless mesh networking for sensor deployment is hybridizing with traditional wired BACnet backbone infrastructure. Healthcare facility operators in Texas and Florida are adopting hybrid architectures fastest, driven by infection control requirements that demand rapid sensor reconfiguration. The structural consequence is collapsing the three-month commissioning window to under four weeks for retrofit projects.
EPA's ENERGY STAR certification requirements for commercial buildings are tightening data granularity standards for HVAC performance verification. Portfolio owners must now submit monthly utility interval data rather than annual aggregates, forcing automation upgrades for submetering accuracy. Large office REITs in Chicago and Atlanta are responding by consolidating vendor relationships around platforms with native EPA reporting modules.
Facility management procurement is fragmenting from single-source mechanical contracts to unbundled software subscriptions and hardware-as-a-service arrangements. Institutional buyers in the education sector are separating controls platform licensing from installation labor, creating openings for specialized systems integrators. This pattern is most pronounced in California community college districts and Ontario school boards with centralized capital planning authority.
North America Building Automation System Market Segmentation
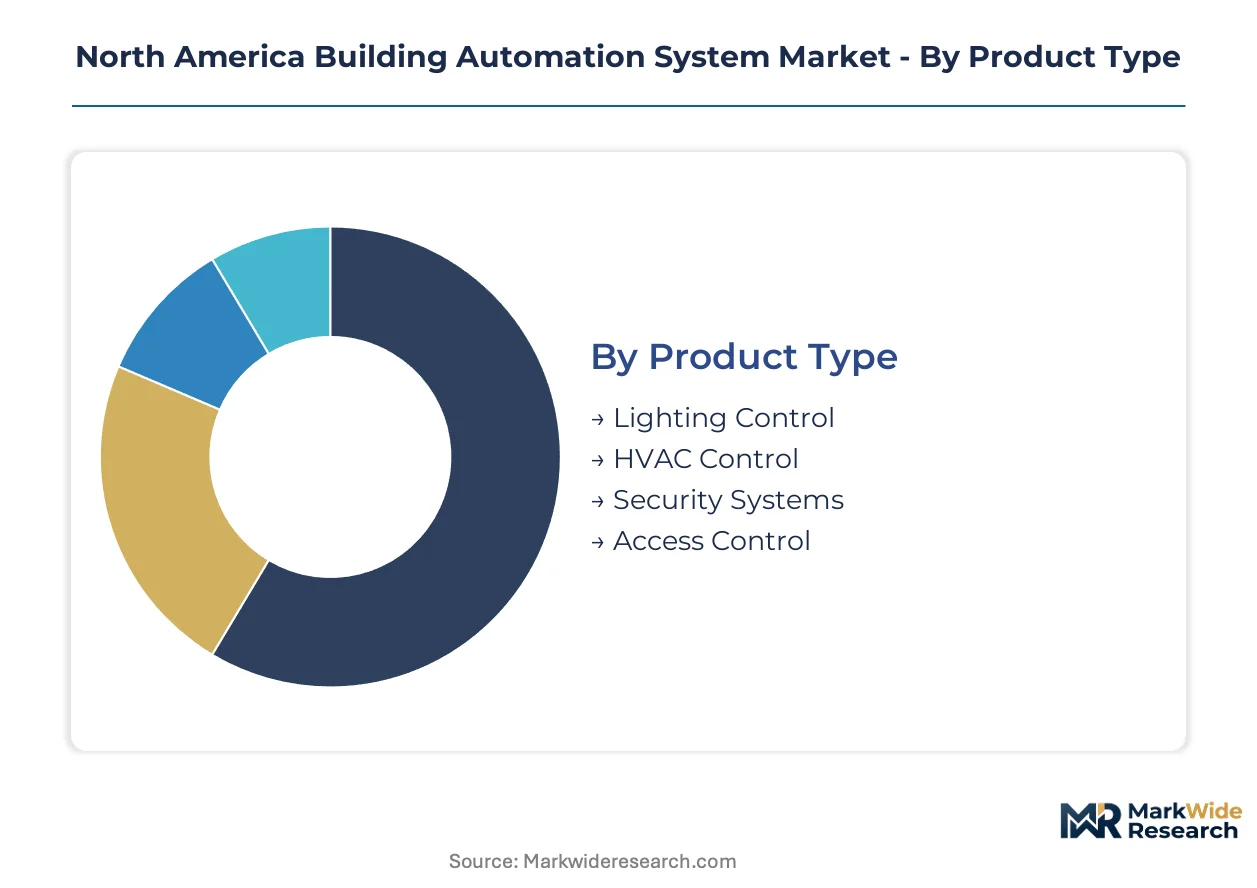
Building automation vendors structure their service organizations around segment-specific commissioning complexity and lifecycle support intensity. Product architecture, end-use regulatory exposure, and technology maturity each create distinct margin profiles that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with HVAC controls demanding continuous calibration support while lighting systems trend toward self-configuring installations.
- HVAC Control:Pneumatic-to-digital retrofit cycles dominate replacement demand in Class B office stock across the United States. California Title 24 enforcement and ASHRAE 90.1 state adoptions are accelerating controller upgrades in legacy buildings.
- Lighting Control:Daylight harvesting and occupancy-based dimming systems reduce baseline electrical loads through sensor networks. Ontario school boards and Texas healthcare facilities are deploying wireless retrofit architectures fastest.
- Security Systems:Video analytics integration with access logs creates unified threat detection platforms.
- Access Control:Mobile credentialing and biometric readers are displacing card-based systems in high-security environments.
By volume, HVAC Control leads. By growth pace, Lighting Control is gaining share fastest.
End User:
Cost tier stratification separates capital-rich institutional buyers from price-sensitive residential developers, with commercial buildings absorbing premium platform pricing for compliance visibility.
- Commercial Buildings:Office REITs in Chicago and Atlanta are consolidating vendor relationships around platforms with native EPA ENERGY STAR reporting modules. Portfolio-scale data granularity requirements are forcing automation upgrades for submetering accuracy.
- Educational Institutions:California community college districts and Ontario school boards with centralized capital planning authority are unbundling controls platform licensing from installation labor. This procurement fragmentation creates openings for specialized systems integrators.
- Industrial Facilities:Process control integration with building systems demands hardened environmental enclosures.
- Residential Buildings:Multifamily developers prioritize cost-minimized thermostat and lighting packages over integrated platforms.
Commercial Buildings command the largest installed base. Educational Institutions show the steepest expansion trajectory for professional services attach rates.
Technology:
Application flexibility determines deployment architecture, with cloud platforms enabling remote diagnostics that displace truck rolls while edge-native devices reduce connectivity dependency.
- Cloud-Based Solutions:Continuous optimization services replace discrete equipment sales through subscription pricing models. Large office REITs are responding to EPA data granularity requirements by consolidating around platforms with integrated reporting.
- IoT-Enabled Devices:Embedded machine learning on sensors enables predictive maintenance without continuous connectivity. Healthcare facility operators in Texas and Florida are adopting hybrid wireless-wired architectures fastest.
- Wireless Systems:Mesh networking for sensor deployment collapses three-month commissioning windows to under four weeks.
- Wired Systems:BACnet backbone infrastructure remains mandatory for critical climate adjustments requiring sub-100 millisecond response latencies.
Wired Systems retain the largest installed footprint. Cloud-Based Solutions are climbing the fastest as remote diagnostics displace on-site service visits.
Application:
Customer type specialization separates compliance-driven buyers from operational efficiency seekers, with energy management absorbing the majority of capital deployment.
- Energy Management:Utility rebate programs in Ontario and Massachusetts are shifting toward measured outcome verification. Vendors with performance-guaranteed service models capture preferential procurement positioning.
- Environmental Monitoring:Infection control requirements in Texas and Florida healthcare facilities demand rapid sensor reconfiguration capabilities.
- Security Management:Unified dashboards force costly middleware development across multi-vendor installations.
- Remote Control:Mobile operator interfaces reduce facility management headcount requirements.
Energy Management leads by deployment volume. Environmental Monitoring is expanding most quickly in healthcare verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American electrical grid interconnection infrastructure underwrites continental BAS deployment scale, with major transmission corridors enabling data center clustering and urban electrification mandates that drive control system demand.
United States
Class B office stock in Chicago and Atlanta drives pneumatic-to-digital retrofit demand as EPA ENERGY STAR data granularity requirements tighten. ASHRAE Standard 90.1 federal minimums cascade through state adoption timelines, forcing controller upgrades. Northern Virginia's hyperscale data center corridor commands precision cooling integration with building-wide energy platforms.
Canada
Ontario school boards with centralized capital planning authority unbundle controls platform licensing from installation labor, creating procurement fragmentation. National Energy Code for Buildings amendments tighten envelope and mechanical performance thresholds in commercial construction. Toronto's healthcare facility cluster adopts hybrid wireless-wired architectures fastest among Canadian metros.
Mexico
Manufacturing facility expansion near the US border generates demand for industrial BAS integration with process control systems. Mexican federal energy efficiency standards for commercial buildings remain less stringent than US or Canadian equivalents. Monterrey's industrial corridor concentrates foreign direct investment requiring environmental monitoring and security management platforms.
North America Building Automation System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, controllers, and actuators. The North American BAS market structures around three strategic tiers: diversified industrial conglomerates with building technology divisions, pure-play automation specialists, and regional systems integrators. Competitive dynamics center on long-term service contract capture and vertical expertise depth in healthcare and data center verticals. M&A activity targets wireless retrofit capabilities and cloud platform assets; strategic partnerships bridge protocol fragmentation gaps.
Within the diversified industrial tier, Honeywell International Inc., Johnson Controls International PLC, and Siemens AG exemplify platform-scale positioning. Honeywell's US incorporation anchors its federal contracting access. Johnson Controls' PLC structure reflects its transatlantic operational footprint. Siemens AG represents European-headquartered competition with deep vertical specialization. These three occupy positions defined by direct channel strength versus systems integrator networks rather than product differentiation alone.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International PLC |
| Siemens AG |
| Schneider Electric SE |
| ABB Ltd |
| Trane Technologies plc |
| Carrier Global Corporation |
| Delta Controls Inc. |
| Lutron Electronics Co., Inc. |
| Others |
Pricing and Supply Chain Analysis
East Asian foundry concentration for BACnet chip and sensor microcontroller production concentrates margin capture upstream, forcing North American controller manufacturers to absorb lead time unpredictability through inventory carrying costs or premium expediting fees. This supply asymmetry pushes downstream pricing power toward systems integrators with captive installation labor pools and long-term service contract visibility.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade platform licensing for institutional REITs from per-project transactional pricing for regional mechanical contractors. Certification grade differentiation—ASHRAE compliance tiers versus legacy pneumatic equivalents—creates pricing stratification across premium, standard, and economy levels. Cost compression in wireless retrofit architectures is intensifying because utility rebate programs now demand measured outcome verification rather than equipment installation proof. Regional mechanical contractors exhibit highest price sensitivity, while institutional buyers with centralized capital planning authority accept premium positioning for native EPA reporting modules.
Supply Chain Analysis
Extended payment terms from tier-one HVAC OEMs to sensor suppliers have compressed working capital cycles across the component tier, forcing specialized controller manufacturers toward supply-chain finance facilities. Manufacturing concentrates in Taiwan for semiconductors, China for sensor assemblies, and Mexico for electromechanical actuators. Raw material dependencies include silicon wafers, rare-earth magnets, and copper wiring. Single-source vulnerability for BACnet protocol chips creates structural risk. Distribution runs through authorized systems integrator networks rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American BAS market rewards scarce capabilities in BACnet/IP commissioning and wireless protocol integration, with talent shortages constraining rollout velocity more than hardware availability. Firms that lock in controls programming expertise gain disproportionate pricing leverage in secondary markets.
For Market Incumbents: Pre-empt wireless retrofit specialists from capturing utility outcome verification contracts by embedding performance-guaranteed service models into existing mechanical service relationships. Consolidate backward integration into sensor manufacturing to reduce East Asian foundry exposure. Channel control through direct systems integrator networks remains the priority defensive lever against cloud-native platform entrants. For New Entrants and Emerging Players: Pursue unbundled software subscription positioning in California community college districts and Ontario school boards, where centralized procurement authority favors separating platform licensing from installation labor. The most penetrable white space sits in secondary Mountain West metropolitan markets where unionized controls programming expertise concentrates insufficiently. A specialized systems integrator go-to-market angle—contracting directly with facility managers rather than mechanical prime contractors—bypasses incumbent channel lock-in. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional controls specialists that accumulated through 2015-2019 rollup activity and now face succession-driven divestiture pressure. Long-term viability over a 5-10 year window hinges on cloud platform architecture migration and edge analytics capability integration. The signal to watch as inflection indicator is utility rebate program structure shifts from equipment-based to measured-savings verification, which favors vendors with performance data infrastructure already deployed.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Retrofit Capability Acquisition | Compresses commissioning windows from three months to four weeks for healthcare facility operators. |
| Cloud Platform Integration Partnership | Enables remote diagnostics that displace truck rolls for EPA ENERGY STAR data granularity compliance. |
| Edge Analytics Talent Acquisition | Secures embedded machine learning expertise for predictive maintenance without continuous connectivity. |
| Systems Integrator Network Expansion | Extends reach into secondary markets where skilled technician scarcity constrains incumbent rollout velocity. |
| Utility Outcome Verification Certification | Qualifies vendors for measured-savings rebate programs in Ontario and Massachusetts procurement cycles. |
Research Methodology
The analysis maps HVAC control, lighting control, security systems, and access control segments, each validated through facility management directors, controls programming contractors, mechanical contractor procurement leads, and utility demand-side management officers. Primary interview findings triangulate against ASHRAE standard documentation, EPA ENERGY STAR program filings, Canadian NECB amendment records, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up project pipeline assessment and top-down construction spending allocation models converge on volume estimates.
Assumption sets held utility decarbonization mandate timelines and semiconductor supply normalization pathways fixed while varying wireless protocol adoption rates and skilled technician availability across metropolitan labor pools. Segmentation dimensions modeled include product type, end user category, technology deployment architecture, and application function across the projection horizon. CAGRs derive from installed base replacement cycles intersecting with regulatory compliance deadlines. Forecast inputs incorporate state-level ASHRAE 90.1 adoption timelines and Title 24 electrification enforcement intensity.
Sensitivities concentrate around East Asian foundry output disruption, unionized controls programming wage inflation, and utility rebate program structure shifts. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
Escalator Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
United States Building Automation Controls Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Global Door Closers Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Global Modularization Market