
 Insulating Glass Window Market | 2026-2036
Insulating Glass Window Market Size, Share, and Industry Trends Forecast 2026-2036
Insulating Glass Window Market Analysis
Low-emissivity (Low-E) coatings is repositioning cost-performance tradeoffs across residential and commercial specifications. Guardian Glass leverages captive float-glass capacity to anchor North American supply chains. AGC Inc. competes through R&D intensity in thin-film deposition technologies. Saint-Gobain dominates European renovation channels with specialized spacer systems.
An insulating glass window comprises two or more glass panes separated by a dehydrated airspace or inert gas fill, bonded with primary polyisobutylene and secondary structural silicone sealants to achieve thermal transmittance values below 1.0 W/m²K. Its primary purpose is to reduce conductive and convective heat transfer in building envelopes, cutting HVAC loads. Double glazed units occupy the volume core across temperate climates where cost sensitivity limits triple-glazed penetration. Vacuum insulated glass captures premium retrofit margins in historic preservation and high-performance commercial facades. Low-E coatings concentrate value pools as energy codes harden across jurisdictions.
EPA Energy Star certification and the EU Green Deal's building performance standards shape product specifications and market access thresholds on both sides of the Atlantic. The F-Gas Regulation constrains spacer-fill gas choices in Europe, pushing manufacturers toward krypton recovery systems and warm-edge spacer redesigns. China's GB standards for building energy efficiency, enforced by MEE provincial inspections, mandate insulating glass in new public construction across northern heating zones. Stakeholders must weigh stranded-asset risk in conventional double-glazed capacity against the capital requirements of vacuum-insulated and electrochromic integration pathways.
Market Dynamics
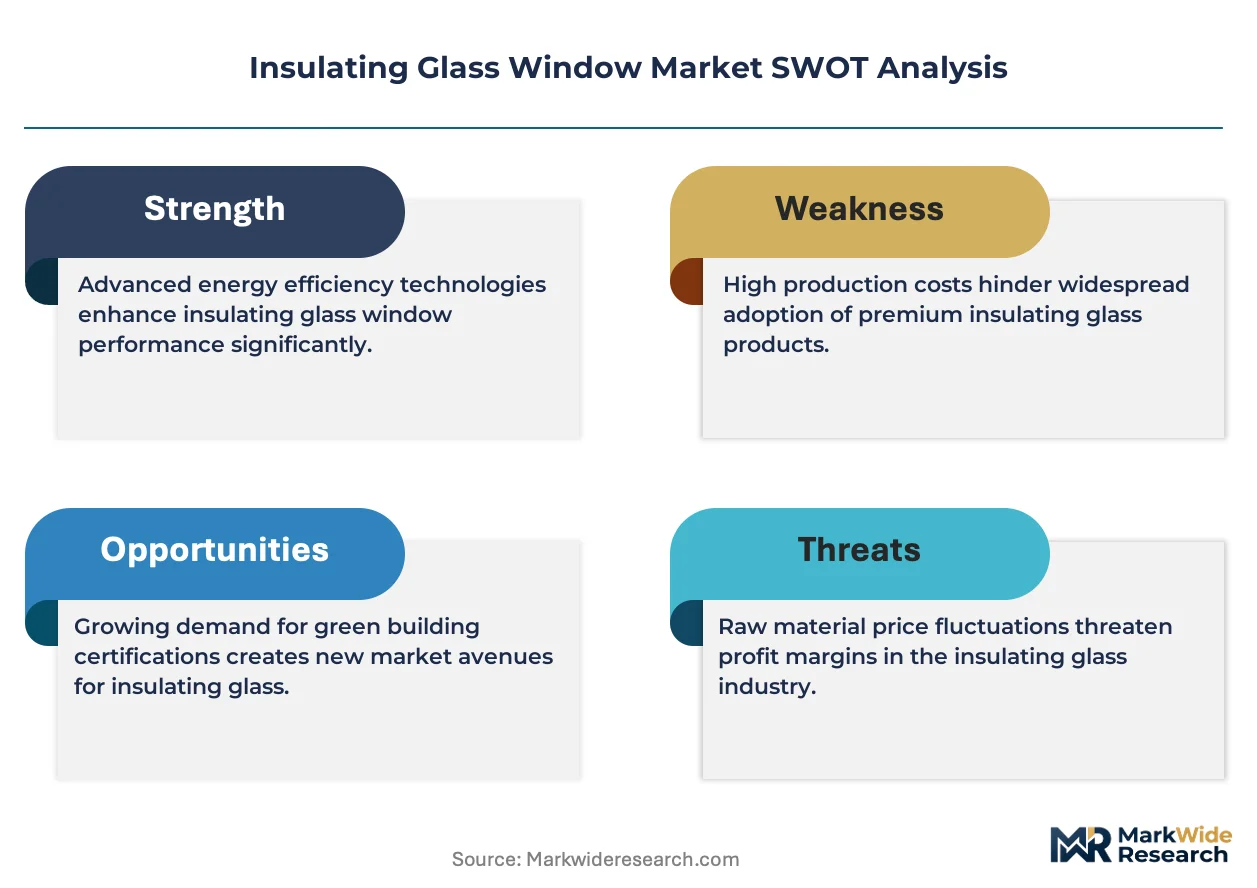
Low-E coatings are compressing thermal performance thresholds faster than conventional glazing can adapt, forcing manufacturers to retool float-glass lines and spacer systems simultaneously.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based spacer fills is accelerating warm-edge spacer adoption and krypton recovery system deployment across German and French fabrication plants.
- Commercial envelope retrofits:North American building owners facing EPA Energy Star certification deadlines are specifying triple-glazed units with suspended-film technology to hit U-factors below 0.20.
- China's MEE enforcement:Provincial inspections of GB 50189 compliance in northern heating zones are mandating insulating glass in all new public construction above 10,000 square meters.
Market Restraints
- Argon supply concentration:Industrial gas production clusters in Germany and the United States create vulnerability when geopolitical events disrupt cylinder logistics to window fabricators.
- Silicone sealant cost volatility:Petrochemical feedstock fluctuations for structural silicone secondary seals compress margin predictability for mid-sized insulating glass unit assemblers.
- Vacuum insulation scaling limits:Micropillar array manufacturing yields remain below 70 percent, constraining vacuum insulated glass output for historic preservation projects.
Strategic Opportunities
- Electrochromic integration:Convergence of dynamic glazing control with vacuum insulated cores opens premium facades in Singapore and Dubai where solar heat gain coefficients must modulate diurnally.
- India's Smart Cities Mission:Green building mandates in Ahmedabad, Pune, and Kochi create first-mover advantage for suppliers establishing local spacer fabrication.
- Performance contracting channels:Energy Service Companies in the United States are bundling window replacement with HVAC upgrades, shifting specification authority from architects to financiers.
Industry Challenges
- Warm-edge spacer engineering talent:Polymer thermal modeling and desiccant integration expertise concentrates among German and Austrian technical specialists, creating recruitment bottlenecks for new market entrants.
- Dual certification timelines:Simultaneous EPA Energy Star and Passive House Institute validation requires 14-18 month test cycles, delaying product launches for integrated glazing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulating Glass Window Market |
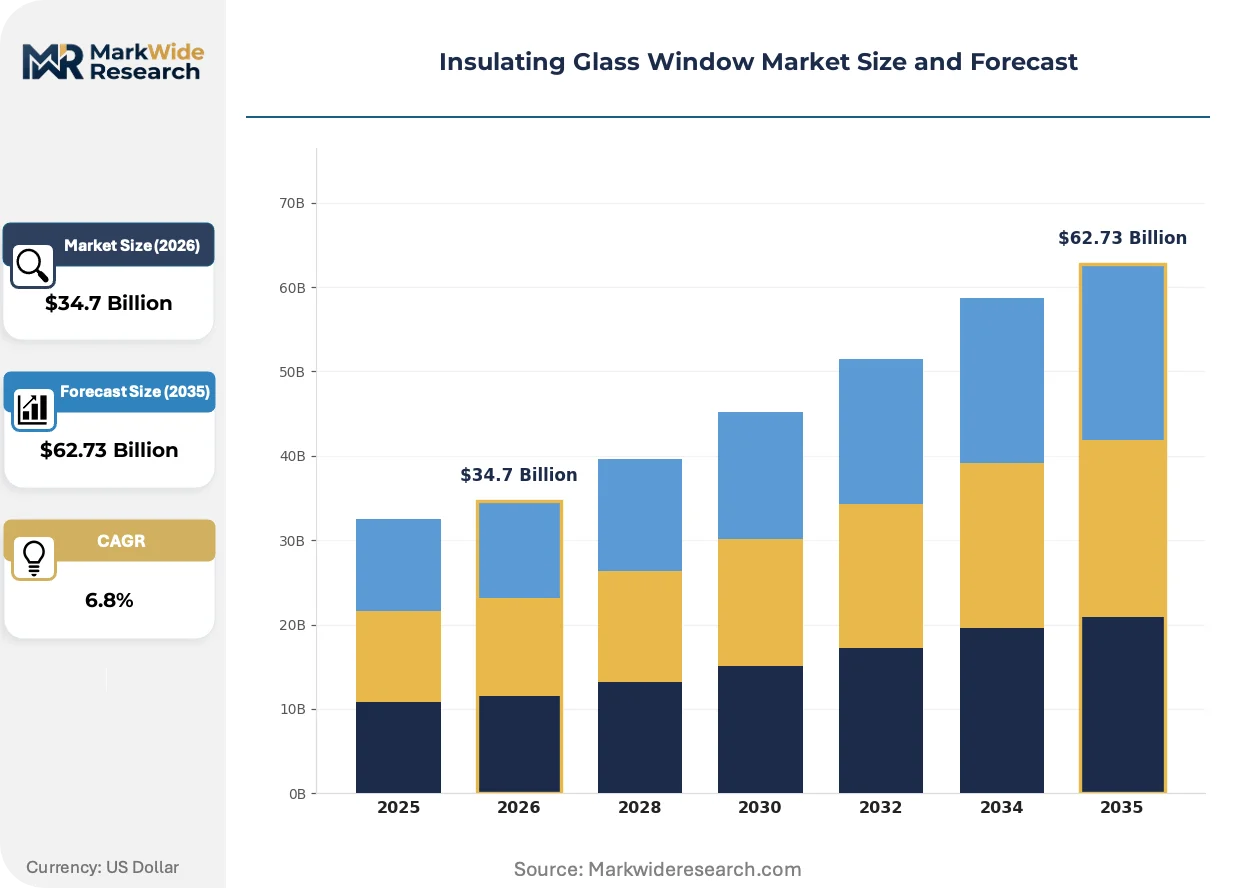
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Glazed, Triple Glazed, Low-E, Vacuum Insulated End User: Residential, Commercial, Industrial, Government Application: New Construction, Renovation, Retrofit, Energy-Efficient Installation Type: Frame-mounted, Spacer-filled, Air-filled, Gas-filled |
| Companies Covered | Saint-Gobain, AGC Inc., Guardian Glass, Nippon Sheet Glass Co., Ltd., Cardinal Glass Industries, Central Glass Co., Ltd., PPG Industries, NSG Group, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulating Glass Window Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine performance benchmarks across the value chain. Fabrication methods and buyer specifications are shifting in parallel.
Vacuum insulated glass is overtaking conventional triple-glazed units in heritage building retrofits where sightline preservation conflicts with thermal targets. Preservation architects in London and Boston specify 8.3 millimeter overall thickness units achieving 0.4 W/m²K. The technology compresses structural load requirements while enabling single-pane aesthetic replication.
The EU Green Deal's building performance standards are hardening enforcement timelines for member state renovation waves. National transposition of the Energy Performance of Buildings Directive is triggering deep retrofit obligations for commercial stock above 1,000 square meters. German landlords are pre-emptively replacing double-glazed facades to avoid 2027 compliance penalties.
Building owners are unbundling window procurement from general contracting, establishing direct relationships with insulating glass unit fabricators for performance guarantees. This disintermediation concentrates volume with certified suppliers capable of 25-year seal warranties. The pattern is most visible in United States healthcare construction where infection control and thermal comfort must coexist.
Insulating Glass Window Market Segmentation
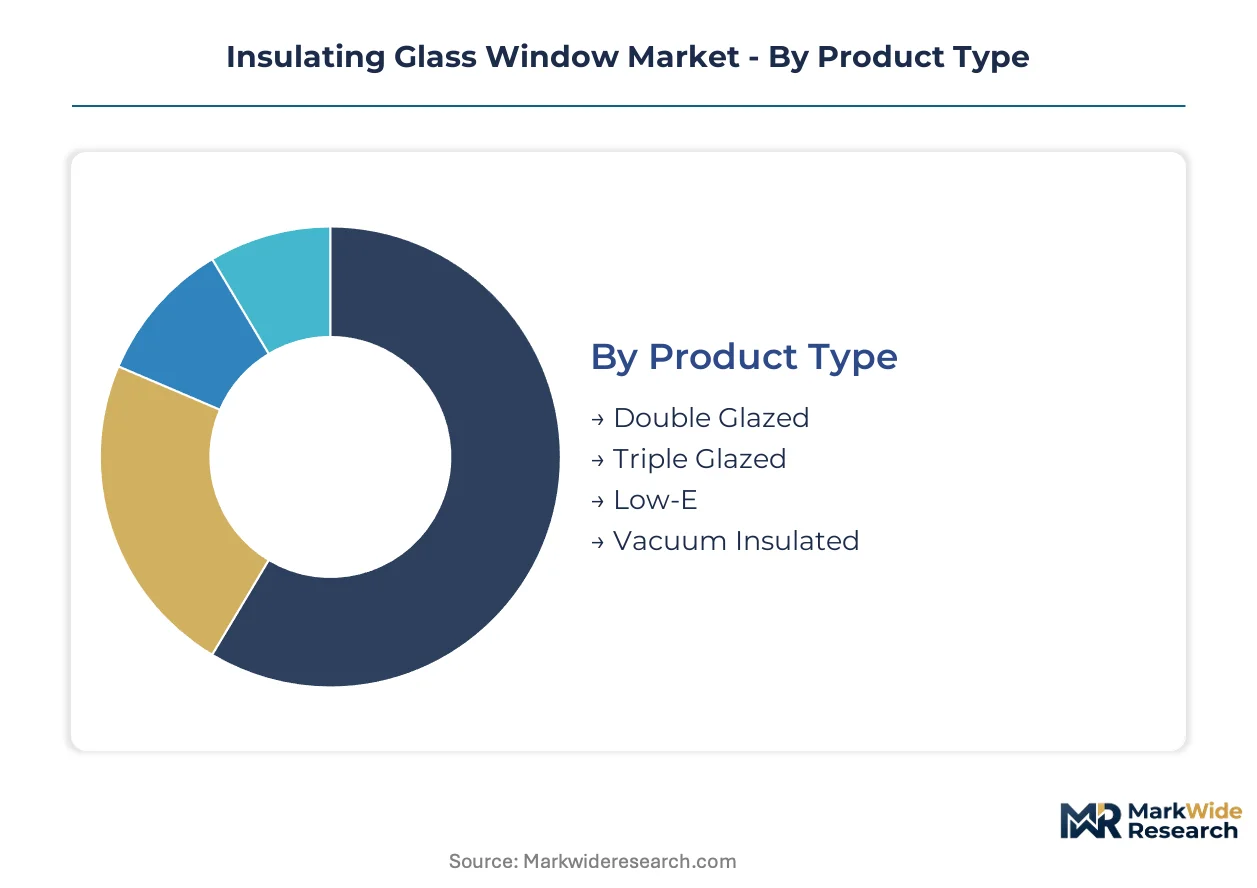
Insulating glass windows fragment across product architecture, end-use requirements, and installation methodology. Specification authority varies sharply between new construction and renovation channels, forcing suppliers to maintain parallel technical roadmaps.
Product Type:
Replacement cycles for conventional glazing are compressing as energy codes harden, accelerating upgrades toward higher-performance configurations.
- Double Glazed:Two glass panes separated by a dehydrated airspace or argon fill, bonded with polyisobutylene primary seals and silicone secondary seals. Volume concentrates in temperate climate residential construction across the United States and Germany where cost sensitivity limits penetration of triple-glazed alternatives.
- Low-E:Glass with microscopically thin metallic oxide coatings that reduce thermal emissivity while preserving visible light transmission. Commercial envelope retrofits in Boston and London specify these units to meet tightening U-factor thresholds without full facade replacement.
- Triple Glazed:Three panes with dual gas-filled cavities achieving thermal transmittance below 0.8 W/m²K. Scandinavian and northern Chinese markets mandate these for passive house compliance.
- Vacuum Insulated:Micropillar-separated panes with evacuated cavities achieving 0.4 W/m²K in sub-10mm profiles. Historic preservation projects in London and Boston drive niche adoption where sightline constraints prohibit conventional thickness.
Volume placements concentrate in Double Glazed; the faster expansion belongs to Vacuum Insulated.
End User:
Procurement authority diverges across customer types, with institutional buyers demanding certified performance guarantees that residential channels rarely require.
- Commercial:Office towers, retail facades, and hospitality envelopes specifying 25-year seal warranties and dynamic glazing integration. North American building owners facing EPA Energy Star deadlines are unbundling window procurement from general contracting.
- Residential:Single-family and multi-family housing where cost-per-square-foot dominates specification. German landlords pre-emptively replacing double-glazed units to avoid EU Green Deal compliance penalties.
- Industrial:Manufacturing facilities and logistics centers requiring impact resistance and thermal stability for process control. Chinese GB 50189 enforcement in northern heating zones mandates insulating glass for new public construction above 10,000 square meters.
- Government:Schools, hospitals, and administrative buildings with extended asset-life requirements and public procurement transparency rules. United States healthcare construction combines infection control with thermal comfort specifications.
Commercial channels dominate absolute volume; residential retrofits are climbing the fastest as energy audits proliferate.
Application:
Project timing determines specification flexibility, with renovation timelines permitting custom engineering that new construction schedules foreclose.
- New Construction:Greenfield developments where insulating glass integrates into curtain wall systems during design phase. Singapore and Dubai premium facades specify electrochromic-vacuum hybrid cores for diurnal solar heat gain modulation.
- Renovation:Partial facade upgrades preserving structural frames while replacing glazing units. German and French fabrication plants are deploying krypton recovery systems to serve this channel under F-Gas Regulation constraints.
- Retrofit:Deep energy retrofits replacing entire window assemblies including frames and spacers. India's Smart Cities Mission in Ahmedabad, Pune, and Kochi is creating first-mover opportunities for local spacer fabrication.
- Energy-Efficient:Performance-contracting bundles where Energy Service Companies combine window replacement with HVAC upgrades, shifting specification authority from architects to financiers.
New Construction commands the largest share; Energy-Efficient applications are expanding most quickly as performance contracting models mature.
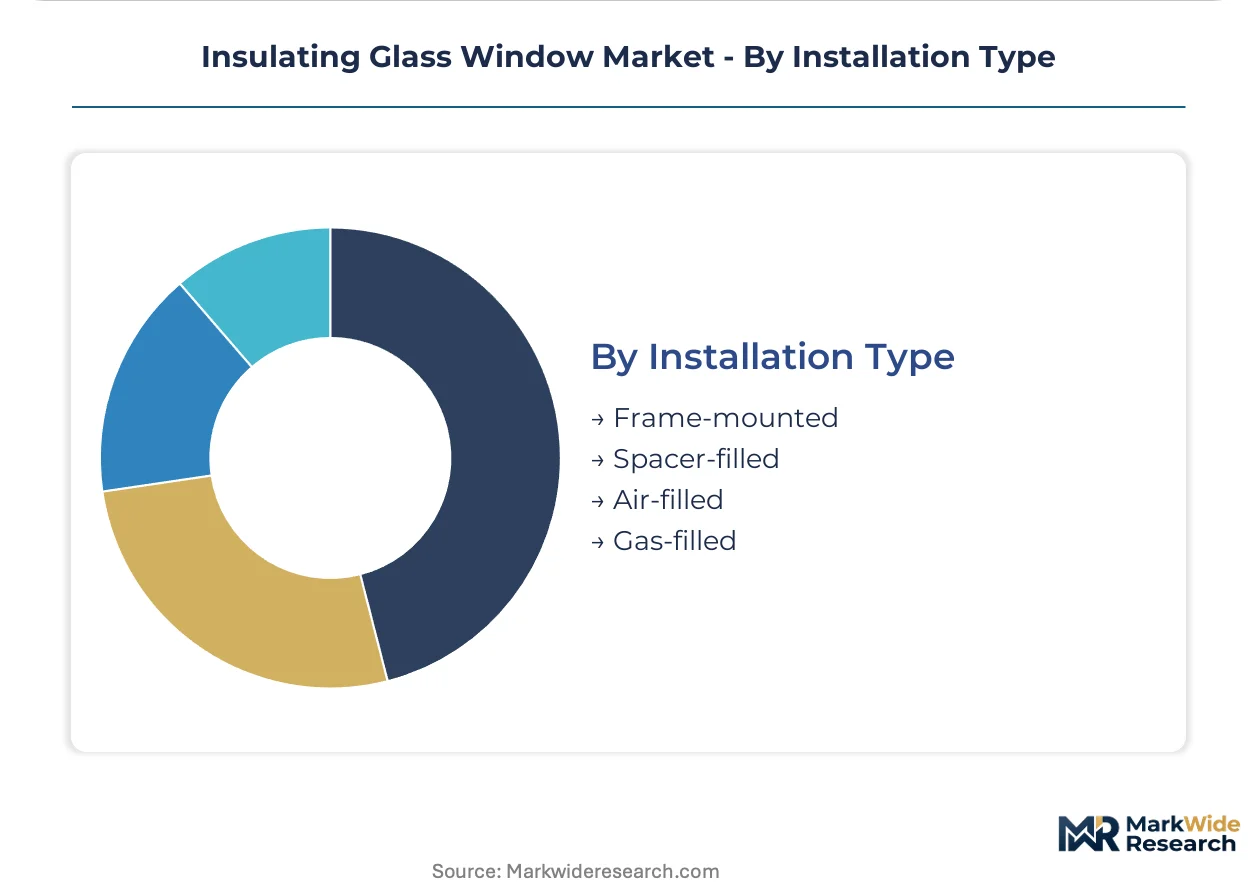
Installation Type:
Spacer and fill-gas choices are restructuring as regulatory constraints on fluorinated gases intensify technical specialization requirements.
- Gas-filled:Argon or krypton injection between panes, with krypton recovery systems becoming critical under EU F-Gas Regulation phasedown schedules. Industrial gas production clusters in Germany and the United States create supply vulnerability during logistics disruptions.
- Spacer-filled:Warm-edge spacer systems incorporating desiccant-integrated polymer profiles. Polymer thermal modeling expertise concentrates among German and Austrian technical specialists, creating recruitment bottlenecks.
- Frame-mounted:Conventional aluminum or uPVC frame integration with primary and secondary sealant bonding. Mid-sized assemblers face margin compression from silicone sealant petrochemical feedstock volatility.
- Air-filled:Dehydrated air cavities in cost-optimized units for price-sensitive markets. These configurations are losing share to gas-filled alternatives as energy codes tighten.
Gas-filled installations lead in volume; Spacer-filled systems are gaining share fastest as warm-edge technology diffuses beyond European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial construction in Germany, China, and the United States concentrates insulating glass window demand as building codes tighten thermal performance thresholds. Retrofit activity in these markets is accelerating replacement cycles for conventional glazing systems.
United States
Healthcare construction and commercial envelope retrofits drive specification volume. EPA Energy Star certification deadlines push building owners toward triple-glazed units with suspended-film technology. Fabrication clusters in Greater Boston and the Pacific Northwest serve renovation channels demanding 25-year seal warranties.
Germany
Deep retrofit obligations under national transposition of the Energy Performance of Buildings Directive trigger pre-emptive facade replacements. The EU F-Gas Regulation accelerates warm-edge spacer adoption and krypton recovery system deployment. Industrial gas production concentration in Bavaria and North Rhine-Westphalia creates supply vulnerability during logistics disruptions.
China
MEE provincial inspections enforce GB 50189 compliance in northern heating zones, mandating insulating glass in new public construction above 10,000 square meters. Yangtze River Delta fabrication plants scale double-glazed output for temperate climate residential markets. Pearl River Delta clusters supply electrochromic-vacuum hybrid cores for premium facades.
India
Green building mandates in Ahmedabad, Pune, and Kochi under the Smart Cities Mission create first-mover opportunities for local spacer fabrication. BIS standards for building energy efficiency are tightening procurement specifications for institutional construction. Maharashtra and Gujarat industrial corridors attract fabrication capacity to serve retrofit demand.
United Kingdom
Preservation architects in London specify vacuum insulated glass for heritage building retrofits where sightline constraints prohibit conventional thickness. National transposition of EU Green Deal building performance standards triggers deep retrofit obligations for commercial stock above 1,000 square meters. Southeast England fabrication clusters specialize in sub-10mm profile units achieving 0.4 W/m²K thermal transmittance.
Insulating Glass Window Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers retool float-glass lines and spacer systems simultaneously to meet hardening energy codes. The vendor base concentrates among integrated glass producers, specialized spacer fabricators, and regional insulating glass unit assemblers serving renovation channels. Three archetypes define competitive positioning: captive float-glass operators with downstream fabrication control, thin-film coating specialists licensing deposition technologies, and warm-edge spacer designers with polymer thermal modeling expertise. M&A activity and strategic partnerships concentrate volume among certified suppliers capable of dual EPA Energy Star and Passive House Institute validation.
Among integrated glass producers, Saint-Gobain, AGC Inc., and Guardian Glass occupy positions spanning multiple regional markets. Saint-Gobain represents the European renovation channel specialist archetype with spacer system integration capabilities. AGC Inc. exemplifies the thin-film deposition technology path for commercial envelope specifications. Guardian Glass anchors North American supply chains through captive float-glass capacity and downstream fabrication control.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Guardian Glass |
| Nippon Sheet Glass Co., Ltd. |
| Cardinal Glass Industries |
| Central Glass Co., Ltd. |
| PPG Industries |
| NSG Group |
| Sika AG |
| Others |
Supply Flow & Price Mechanics
Low-E certification tiers bifurcate insulating glass window procurement into EPA Energy Star-validated premium channels and commodity double-glazed alternatives, with this divergence manifesting in both unit economics and supply chain configurations. German fabricators commanding dual Passive House Institute certification capture margin premiums through captive krypton recovery systems, while mid-sized assemblers in the United States face margin compression from silicone sealant feedstock volatility.
Pricing Analysis
Volume-margin splits separate high-performance vacuum insulated glass from commodity double-glazed units across temperate climate markets. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and spacer technology complexity. Cost compression in standard double-glazed tiers is intensifying because argon supply concentration in Germany and the United States creates logistics vulnerability during cylinder distribution disruptions. Residential retrofits in northern Chinese heating zones exhibit highest price sensitivity, while United States healthcare construction tolerates premium positioning for 25-year seal warranty bundles.
Supply Chain Analysis
EPA Energy Star and Passive House Institute certification gating concentrates qualified supply among fabricators maintaining in-house thin-film deposition and warm-edge spacer engineering capabilities. Float-glass production clusters in China, Germany, and the United States anchor upstream supply, with downstream fabrication drawing from specialized spacer manufacturers in Austria and polymer desiccant suppliers in Japan. Single-source vulnerability concentrates in industrial gas production for krypton and argon fills, with distribution running through regional insulating glass unit assemblers serving renovation channels directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insulating glass window manufacturing is becoming a vertical-integration race as players pursue captive float-glass capacity to secure coating line feedstock and control thermal performance consistency. Control over upstream glass melting and downstream spacer fabrication determines qualification for dual-certification procurement channels.
For Market Incumbents: Cement market position through backward integration into warm-edge spacer polymer compounding and krypton recovery system deployment. Vacuum insulated glass manufacturing yields below 70 percent represent a margin threat from specialized entrants with micropillar array process expertise. Capacity addition in Yangtze River Delta clusters secures proximity to Chinese MEE enforcement zones for GB 50189 compliance mandates. For New Entrants and Emerging Players: Electrochromic-vacuum hybrid core technology offers a technology-first wedge into Singapore and Dubai premium facade specifications requiring diurnal solar heat gain modulation. India's Smart Cities Mission green building mandates in Ahmedabad, Pune, and Kochi represent the most penetrable geography for local spacer fabrication establishment. Direct contracting with Energy Service Companies in the United States bypasses architect specification gatekeeping. For Investors and Strategic Acquirers: Re-rating potential sits with warm-edge spacer designers with polymer thermal modeling expertise given EU F-Gas Regulation phasedown accelerating adoption timelines. Five-to-ten year viability framing favors fabricators with dual EPA Energy Star and Passive House Institute validation capabilities and established 25-year seal warranty track records. Acquisition target archetype: mid-cap insulating glass unit assemblers in Greater Boston or Pacific Northwest clusters with renovation channel relationships. The signal to watch is provincial MEE inspection intensity in Chinese northern heating zones triggering public construction specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float-Glass Melting | Captive coating line feedstock secures thermal performance consistency for EPA Energy Star validation. |
| Warm-Edge Spacer Polymer Compounding | In-house desiccant integration addresses recruitment bottlenecks among German and Austrian technical specialists. |
| Krypton Recovery System Deployment | F-Gas Regulation compliance enables continued service of European deep retrofit channels. |
| Electrochromic-Vacuum Hybrid Development | Diurnal modulation capability opens Singapore and Dubai premium facade specifications. |
| Energy Service Company Partnership | Direct contracting shifts specification authority from architects to financiers in United States healthcare construction. |
Methodological Framework
Document review covered SEC 10-K filings from integrated glass producers, EU F-Gas Regulation implementation assessments, and Chinese GB 50189 provincial inspection reports, complemented by interviews with plant managers at Yangtze River Delta fabrication facilities, procurement leads at United States healthcare construction developers, and warm-edge spacer technical directors in Bavaria. Secondary validation drew from customs trade data on industrial gas cylinder movements, EPA Energy Star certification databases, and Passive House Institute component listings. Bottom-up insulating glass unit production estimates triangulated against top-down building envelope retrofit spending projections.
Historical shipment trajectories cross-referenced against panel input from fabrication plant technical directors and commercial specification architects informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-use procurement authority, installation methodology, and regional regulatory enforcement intensity. CAGRs derived from growth rate reconciliation between supply-side capacity expansion announcements and demand-side building code amendment schedules. Industry-specific forecast inputs incorporated MEE provincial inspection intensity indices and EU Green Deal national transposition timelines.
Several conditions sit outside the modeled scope, including geopolitical disruption of industrial gas logistics, breakthrough advances in micropillar array manufacturing yields, and unanticipated amendments to F-Gas Regulation phasedown schedules. Forecasts reflect documented assumptions regarding certification timeline durations and spacer technology diffusion rates. A model refresh is warranted upon material change in Chinese MEE enforcement intensity or EPA Energy Star specification threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Door System Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Mexican Insulated Panels Market
Building & Construction Materials
Japan Prefab Wood Building Market