
 LAMEA Building Automation System Market | 2026-2036
LAMEA Building Automation System Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Building Automation System Market Insights
UAE-based system integrators is rebalancing project pipelines toward cloud-managed platforms as Gulf construction activity intensifies. Honeywell International Inc. leverages its regional distribution network to anchor premium HVAC control installations across Saudi megaprojects. Schneider Electric SE differentiates through integrated energy management software that competes with legacy wired architectures. Johnson Controls International plc sustains its position in commercial building retrofits through localized service partnerships.
A building automation system comprises networked controllers, sensors, actuators, and software platforms that regulate mechanical, electrical, and environmental functions within structures, typically operating through BACnet or Modbus communication protocols with response latencies under 100 milliseconds. These systems reduce operational energy expenditure by enabling centralized monitoring of lighting, climate, and access functions across multi-zone facilities. HVAC Control commands the largest installed base due to cooling-dominated climates across the Middle East and Africa, though Cloud-Based deployments are expanding fastest as telecommunications infrastructure improves. Security Systems generate concentrated margins in high-end commercial applications across Gulf financial districts, while Wired technology retains dominance in industrial facilities where electromagnetic interference demands shielded cabling.
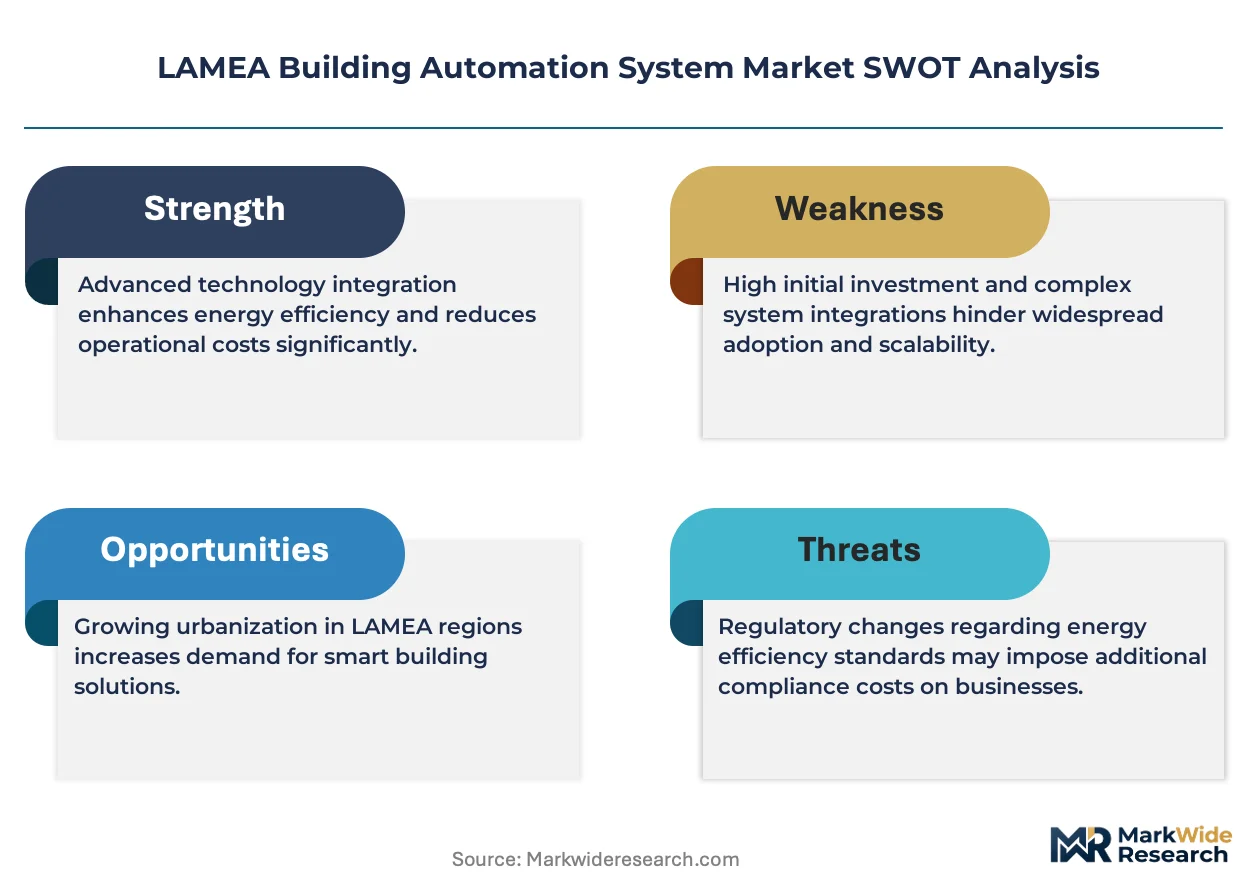
Saudi Arabia's Saudi Building Code and the UAE's Estidama Pearl Rating System mandate energy-efficient building operations, compelling owners to upgrade legacy infrastructure with automated monitoring platforms. South Africa's National Energy Regulator enforces consumption disclosure rules that push commercial landlords toward real-time energy management systems. Brazil's INMETRO certification requirements for electrical building systems create compliance barriers for imported automation hardware. Stakeholders must evaluate whether wireless retrofit architectures or full controller replacements better align with evolving national efficiency mandates and local technical workforce availability.
Market Dynamics
Cloud-native control architectures are compressing deployment timelines across LAMEA commercial construction, forcing incumbent integrators to retrain field technicians on API-driven commissioning protocols or lose retrofit contracts to software-first competitors.
Growth Catalysts
- Estidama Pearl Rating System:UAE commercial developments above 25,000 square meters must achieve minimum Pearl ratings, mandating automated energy monitoring systems that drive controller procurement volumes.
- Data center construction:Hyperscale facility operators across Saudi Arabia and South Africa require precision cooling automation, creating concentrated demand for BACnet-IP compatible HVAC controllers.
- Edge analytics modules:On-premise inference engines processing occupancy and thermal data locally reduce cloud latency below 50 milliseconds, enabling real-time damper adjustments in high-rise towers.
Market Restraints
- Copper and semiconductor input volatility:Shielded twisted-pair cabling and sensor microcontrollers face price swings that compress system integrator margins on fixed-bid government contracts.
- Legacy proprietary protocols:Tridium Niagara and Siemens proprietary networks in 1990s-era Dubai commercial stock resist standard BACnet/IP migration without full controller replacement.
- Skilled technician scarcity:Certified commissioning agents familiar with both mechanical HVAC and IT network administration command premium wages that inflate project labor costs.
Strategic Opportunities
- Nigeria commercial real estate:Lagos and Abuja office construction lacks automated controls penetration below 15 percent, creating first-mover advantage for cloud-managed platform providers.
- Grid-interactive building codes:Saudi Arabia's evolving demand-response mandates position battery-integrated BAS controllers as revenue-generating assets through peak-shaving incentives.
- Digital twin convergence:Unity 3D and Autodesk platforms merging with operational BAS data enable predictive maintenance contracts that extend vendor recurring revenue streams.
Industry Challenges
- Multi-protocol integration complexity:Facilities mixing Modbus RTU, BACnet MS/TP, and emerging MQTT require middleware development that delays project handover and strains warranty obligations.
- Cybersecurity certification timelines:IEC 62443 compliance documentation for controller firmware extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Building Automation System Market |
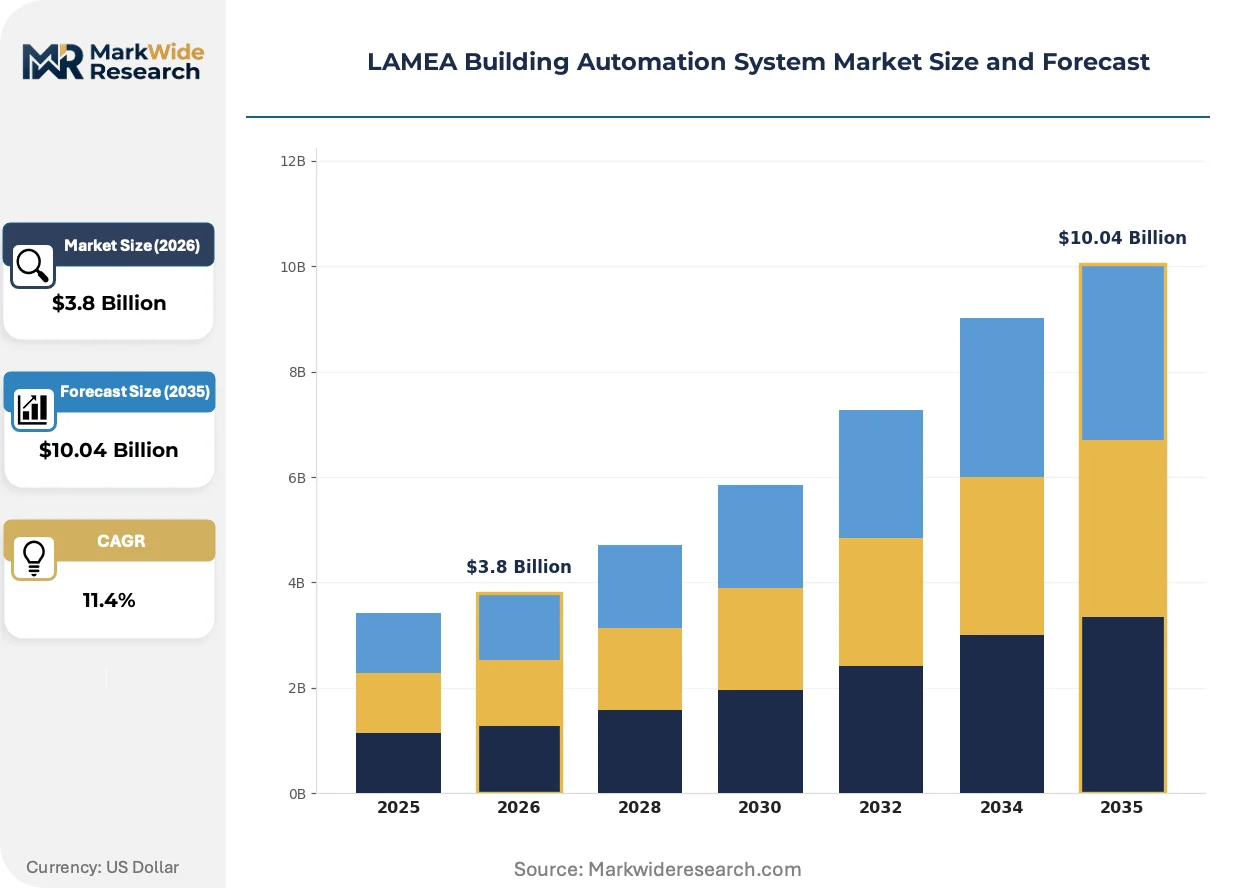
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control, HVAC Control, Security Systems, Energy Management Technology: Wired, Wireless, Cloud-Based, Hybrid Application: Commercial Buildings, Residential Buildings, Industrial Facilities, Educational Institutions End User: Facility Managers, Building Owners, Contractors, System Integrators |
| Companies Covered | Honeywell International Inc., Siemens AG, Johnson Controls International plc, Schneider Electric SE, ABB Ltd, Carrier Global Corporation, Robert Bosch GmbH, Legrand SA, Mitsubishi Electric Corporation, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Building Automation System Market Trends and Innovations
Artificial intelligence inference at the controller level is displacing rule-based setpoint logic across Middle Eastern smart building deployments, compressing energy consumption while raising hardware cost thresholds.
Edge-native machine learning controllers process occupancy patterns and weather forecast data locally to anticipate thermal loads before they materialize. Large-format retail and hospitality operators in the UAE and Saudi Arabia are piloting these systems in 50,000-plus square meter properties. This capability is expanding into district cooling substations where predictive valve positioning reduces pumping energy by double-digit percentages.
Saudi Arabia's Saudi Building Code enforcement is tightening minimum automation requirements for new commercial construction above 10,000 square meters. The regulation mandates centralized monitoring of HVAC, lighting, and water systems with automated fault detection. High-rise residential towers in Riyadh and Jeddah now represent the fastest-compliance segment, with developers pre-specifying integrated platforms to avoid construction permit delays.
Building operators are unbundling long-term service contracts from initial hardware procurement, favoring subscription-based remote monitoring over traditional warranty extensions. This restructuring concentrates purchasing authority with facility management firms rather than construction contractors. Brazilian commercial landlords in São Paulo and Rio de Janeiro exhibit the most aggressive shift, driven by INMETRO certification requirements that favor ongoing vendor accountability over one-time equipment validation.
LAMEA Building Automation System Market Segmentation
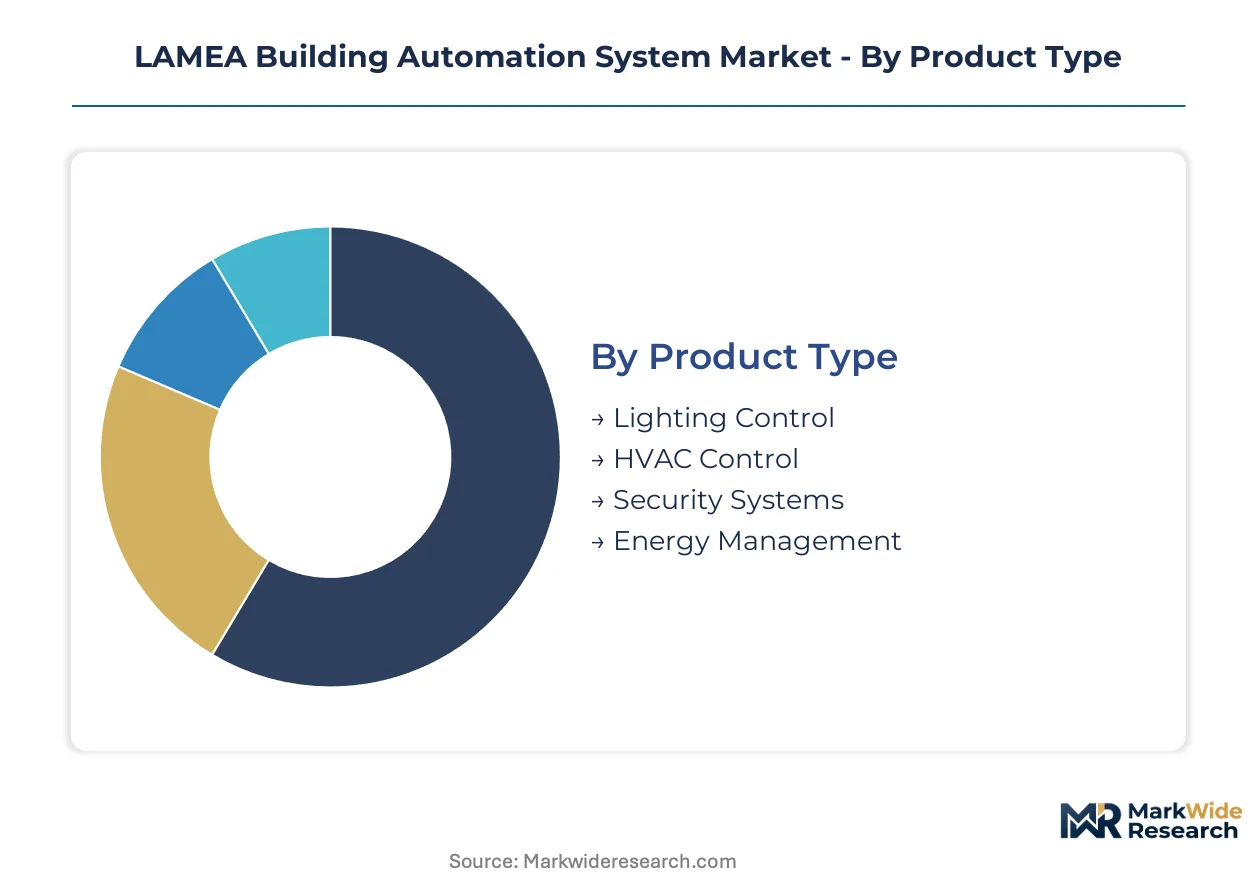
Building automation system deployment across Latin America, the Middle East, and Africa fragments across product architectures, connectivity modes, and stakeholder procurement patterns. Each segmentation axis reveals distinct margin profiles and installation complexity barriers that shape vendor competitive positioning.
Product Type:
Controller hardware specifications determine integration depth with legacy mechanical infrastructure across Gulf commercial towers and Brazilian industrial parks.
- HVAC Control:Cooling-dominated climates across Saudi Arabia and the UAE drive specification of variable air volume controllers and chilled water valve actuators with sub-100-millisecond response latencies. Demand concentrates in Riyadh and Jeddah high-rise residential where Saudi Building Code mandates automated fault detection for developments exceeding 10,000 square meters.
- Security Systems:Biometric access controllers and IP video management platforms generate concentrated margins in Dubai International Financial Centre and Abu Dhabi Global Market developments. Financial district landlords specify IEC 62443-compliant firmware to satisfy cybersecurity audit requirements from Gulf central banks.
- Lighting Control:Daylight harvesting dimmers and occupancy sensors reduce artificial lighting loads in Estidama Pearl-rated UAE commercial stock above 25,000 square meters.
- Energy Management:Sub-metering aggregation platforms enable real-time consumption disclosure compliance with South Africa's National Energy Regulator mandates.
HVAC Control leads on scale; Security Systems leads on momentum.
Technology:
Connectivity architecture selection hinges on electromagnetic environment severity and existing infrastructure replacement economics.
- Cloud-Based:API-driven commissioning protocols compress deployment timelines for Nigerian commercial real estate in Lagos and Abuja where first-mover platform providers face minimal legacy protocol competition. Brazilian landlords in São Paulo favor subscription-based remote monitoring over traditional warranty extensions to satisfy INMETRO certification accountability requirements.
- Wired:Shielded twisted-pair BACnet MS/TP cabling dominates industrial facilities across South African mining corridors and Saudi petrochemical zones where electromagnetic interference demands physical signal isolation. Copper input volatility compresses system integrator margins on fixed-bid government contracts.
- Wireless:Zigbee and LoRaWAN sensors enable rapid retrofit of 1990s-era Dubai commercial stock without full controller replacement.
- Hybrid:Edge analytics modules processing occupancy data locally reduce cloud latency below 50 milliseconds in UAE hospitality properties exceeding 50,000 square meters.
Wired technology retains the largest installed base; Cloud-Based deployments are climbing the fastest.
Application:
Building typology dictates controller density per square meter and software licensing complexity.
- Commercial Buildings:Multi-tenant office towers across Dubai Marina and São Paulo Faria Lima require centralized monitoring platforms with tenant-level sub-metering and automated demand-response capability for grid-interactive code compliance.
- Industrial Facilities:Precision cooling automation for hyperscale data centers in Saudi Arabia and South Africa demands BACnet-IP compatible HVAC controllers with redundant communication paths.
- Residential Buildings:High-rise towers in Riyadh and Jeddah represent the fastest-compliance segment under tightened Saudi Building Code automation requirements.
- Educational Institutions:University campuses across Brazil and South Africa prioritize occupancy-based ventilation control to reduce operational expenditure amid constrained public budgets.
Commercial Buildings anchor procurement volume; Industrial Facilities show the steepest expansion trajectory.
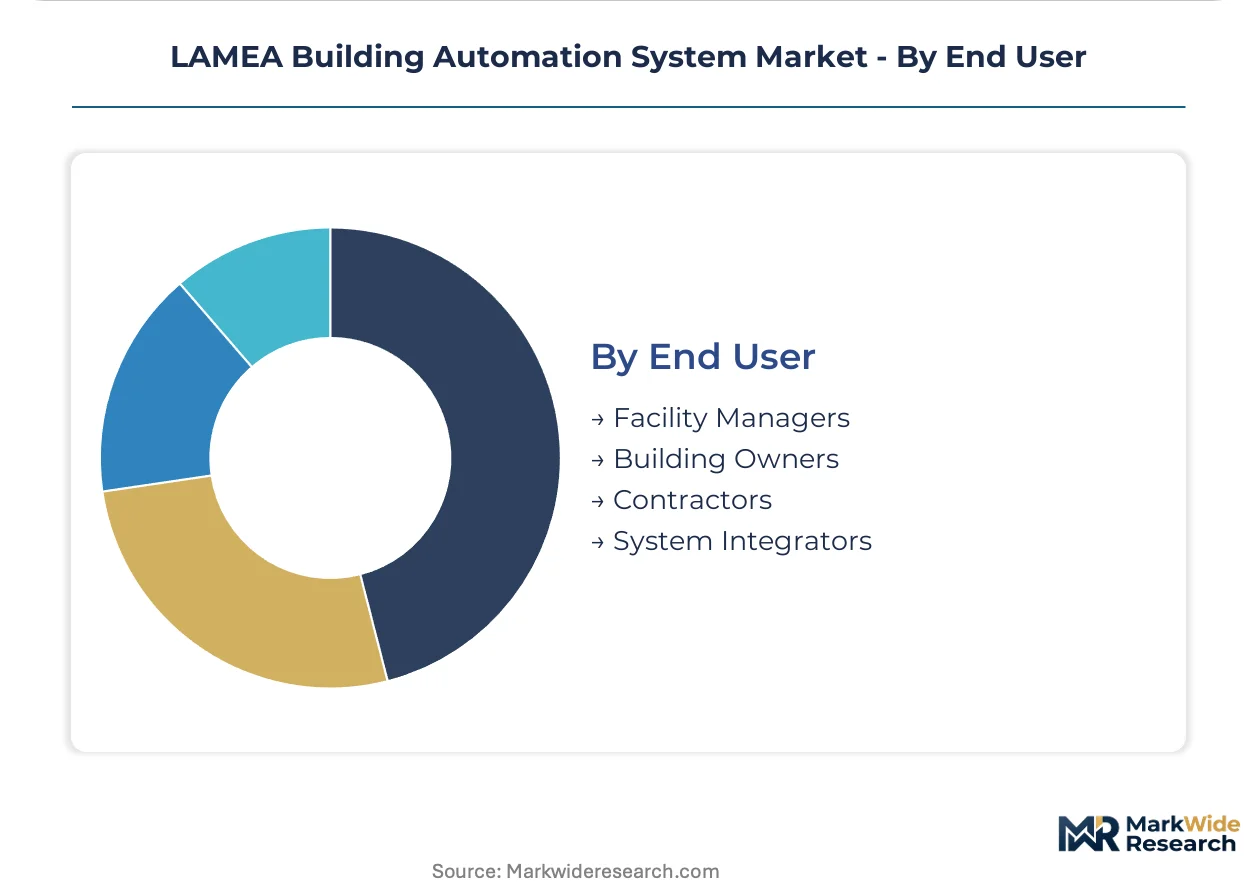
End User:
Procurement authority is restructuring as facility management firms displace construction contractors in long-term service contracting decisions.
- Facility Managers:Brazilian commercial landlords exhibit the most aggressive shift toward subscription-based vendor accountability, driven by INMETRO certification requirements that favor ongoing performance validation over one-time equipment procurement.
- System Integrators:UAE-based integrators are rebalancing project pipelines toward cloud-managed platforms as Gulf construction activity intensifies and API-driven commissioning protocols displace traditional field technician skill sets.
- Building Owners:Saudi megaproject developers pre-specify integrated platforms to avoid construction permit delays under tightening automation mandates.
- Contractors:Fixed-bid government contracts in South Africa and Nigeria expose this segment to copper and semiconductor input price volatility.
Facility Managers are gaining purchasing authority fastest; System Integrators face the steepest capability retraining requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting building automation procurement toward jurisdictions with enforceable energy codes and accessible technical labor pools. Gulf construction booms and Latin American retrofit cycles create divergent compliance cost structures that reshape vendor deployment strategies.
United Arab Emirates
Dubai International Financial Centre and Abu Dhabi Global Market developments drive specification of IEC 62443-compliant security controllers. The Estidama Pearl Rating System mandates automated energy monitoring for commercial stock above 25,000 square meters. System integrators in Dubai are rebalancing pipelines toward cloud-managed platforms as API-driven commissioning displaces traditional field protocols.
Saudi Arabia
Riyadh and Jeddah high-rise residential towers represent the fastest-compliance segment under tightened Saudi Building Code automation requirements. The regulation mandates centralized monitoring of HVAC, lighting, and water systems with automated fault detection for developments exceeding 10,000 square meters. NEOM and Red Sea Project megaprojects are pre-specifying integrated platforms to avoid construction permit delays.
Brazil
São Paulo and Rio de Janeiro commercial landlords exhibit aggressive shifts toward subscription-based remote monitoring over traditional warranty extensions. INMETRO certification requirements for electrical building systems favor ongoing vendor accountability rather than one-time equipment validation. Faria Lima district office towers require tenant-level sub-metering platforms with automated demand-response capability.
South Africa
Hyperscale data center operators in Johannesburg and Cape Town require precision cooling automation with redundant communication paths. The National Energy Regulator enforces consumption disclosure rules that push commercial landlords toward real-time energy management systems. Mining corridors in the Northern Cape retain shielded twisted-pair BACnet MS/TP dominance where electromagnetic interference demands physical signal isolation.
Nigeria
Lagos and Abuja office construction lacks automated controls penetration below 15 percent, creating first-mover advantage for cloud-managed platform providers. The absence of legacy proprietary protocol competition enables rapid API-driven deployment timelines. Local system integrators face minimal retraining requirements compared to Gulf markets saturated with 1990s-era wired architectures.
LAMEA Building Automation System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native retrofit opportunities in underpenetrated African markets. The vendor base stratifies across three maturity tiers: legacy industrial conglomerates with regional distribution networks, building technology specialists with integrated energy software portfolios, and software-first challengers compressing deployment timelines through API-driven commissioning. Dominant competitive moves include strategic partnerships with Gulf megaproject developers and portfolio diversification into edge analytics modules that reduce cloud latency below 50 milliseconds.
Among diversified industrial conglomerates, Honeywell International Inc., Siemens AG, and Schneider Electric SE exemplify distinct archetype positioning. Honeywell anchors premium HVAC control installations through established regional distribution networks across Saudi megaprojects. Siemens represents legacy proprietary protocol incumbents facing migration pressure toward standard BACnet/IP architectures. Schneider Electric occupies the integrated energy management software tier, competing with legacy wired architectures through unified platform offerings. These three entities collectively illustrate how vendor origin—American, German, French—correlates with divergent technology licensing and partnership strategies across LAMEA commercial construction cycles.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Johnson Controls International plc |
| Schneider Electric SE |
| ABB Ltd |
| Carrier Global Corporation |
| Robert Bosch GmbH |
| Legrand SA |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange copper price volatility cascades through LAMEA building automation supply chains, compressing system integrator margins on fixed-bid Saudi megaprojects while pushing Brazilian landlords toward subscription-based procurement that transfers hardware cost risk to vendors.
Pricing Analysis
Distributor margins on BACnet controllers range from 15 to 22 percent across Gulf markets, with project-based pricing dominating Saudi commercial construction while subscription SaaS tiers gain traction in Brazilian retrofit markets. Price differentiation hinges on IEC 62443 cybersecurity certification grade and localized service bundling, with certified controllers commanding 30 to 40 percent premiums over uncertified alternatives. Pricing pressure intensifies in Nigerian greenfield deployments where cloud-native competitors compress commissioning timelines by half. Facility management firms exhibit lowest price sensitivity, prioritizing uptime guarantees over per-unit hardware costs.
Supply Chain Analysis
Freight cost spikes on Asia-Gulf routes have elevated landed costs for sensor microcontrollers by double-digit percentages since 2022, forcing inventory pre-positioning in Dubai free zones. Manufacturing concentrates in China, Germany, and the United States for precision controllers, while copper cabling draws from Chilean and Zambian smelters. Single-source vulnerability in semiconductor foundry capacity represents the dominant supply chain risk. Distribution runs through authorized system integrator networks across Saudi Arabia and the UAE, with direct OEM relationships penetrating large-scale data center operators in South Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LAMEA building automation functions as a regulatory compounder where Saudi Building Code enforcement milestones and UAE Estidama Pearl mandates mechanically expand addressable demand regardless of cyclical construction sentiment.
For Market Incumbents: Anticipate margin compression from software-first challengers by deepening API-driven commissioning capabilities and securing exclusive partnerships with NEOM and Red Sea Project developers. Backward integration into edge analytics module production reduces cloud latency vulnerabilities while capturing recurring revenue streams that hardware-only competitors cannot match. For New Entrants and Emerging Players: Begin with cloud-managed platform deployment in Nigerian commercial real estate where legacy protocol competition remains absent and first-mover positioning enables rapid API-driven market share accumulation. Target Lagos and Abuja office construction with subscription pricing models that align with local capital constraints and favor ongoing vendor accountability over upfront procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with software-first challengers possessing IEC 62443 certification progress and established Gulf system integrator partnerships. Long-term viability across the projection horizon favors vendors with recurring revenue concentration above 40 percent and demonstrated ability to compress deployment timelines through API-driven protocols. Watch for Saudi demand-response mandate finalization as inflection indicator for battery-integrated BAS controller demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | API-driven commissioning compresses deployment timelines by 40 percent in Nigerian greenfield markets. |
| IEC 62443 Certification Investment | Cybersecurity-compliant firmware unlocks Dubai International Financial Centre and Abu Dhabi Global Market specifications. |
| Edge Analytics Module Development | On-premise inference engines reduce cloud latency below 50 milliseconds in UAE hospitality properties. |
| Subscription Service Restructuring | Ongoing vendor accountability aligns with Brazil INMETRO certification requirements and extends recurring revenue. |
| System Integrator Capability Retraining | API protocol proficiency defends incumbent positioning against software-first competitors in Gulf construction. |
Research Methodology
Bottom-up commercial building and industrial facility modeling reconciled against top-down controller shipment tracking forms the analytical core of this study. Primary interviews with system integrators, facility management executives, and OEM procurement directors combined with secondary validation from Saudi Building Code regulatory filings, UAE Estidama Pearl certification databases, and South African National Energy Regulator consumption disclosure records. Field perspectives from certified commissioning agents and cloud platform engineering teams anchored demand-side assumptions.
Historical trendline analysis across product type, connectivity architecture, and application segments informed projection framework construction. Segmentation dimensions modeled include HVAC control versus security systems versus energy management, cloud-based versus wired versus wireless deployment, and commercial buildings versus industrial facilities versus residential towers. CAGR derivation incorporated technology substitution curves for cloud-native platforms and regulatory compliance deadlines across Saudi Arabia, the UAE, and Brazil. Input variables span copper price indices, semiconductor lead times, and telecommunications infrastructure deployment schedules.
Several conditions sit outside the modeled scope, including geopolitical disruptions to Asia-Gulf shipping lanes and abrupt shifts in national energy code enforcement timelines. Forecasts reflect assumptions about continued Gulf construction activity intensity and Brazilian commercial landlord procurement authority migration. Stakeholders should weight assumptions against their own operating context and regional regulatory implementation cadence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Global Door Closers Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Commercial Building Automation Systems Market