
 Canada Construction Equipment Market | 2026-2036
Canada Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Construction Equipment Market Insights
Aftermarket service revenue is rewriting profitability benchmarks across the Canada Construction Equipment Market. Caterpillar leverages its dealer network density to capture recurring parts and service contracts in remote mining territories. Komatsu sustains competitive pressure through telematics-integrated fleet management programs that reduce customer downtime. John Deere anchors its position in agricultural-adjacent construction segments with specialized compact equipment lines.
Construction equipment encompasses mobile machinery engineered for earthmoving, material handling, and structural lifting operations, typically powered by diesel engines rated between 75 and 750 horsepower and governed by exhaust emission certification tiers. Excavators dominate product type revenue due to versatility across trenching, demolition, and material loading applications, while the off-road deployment model commands premium pricing through reinforced undercarriages and sealed hydraulic systems designed for unimproved terrain. The rental service type is expanding fastest as project owners shift capital expenditure toward operational flexibility, though direct sales still concentrate margin pools in heavy-duty mining configurations.
Environment and Climate Change Canada enforces Tier 4 Final emission standards that mandate selective catalytic reduction and diesel particulate filter integration, forcing manufacturers to redesign powertrain architectures or risk market exclusion. Transport Canada's Motor Vehicle Safety Regulations govern on-road equipment variants, while provincial occupational health agencies mandate rollover protective structures and operator certification programs that influence equipment specification requirements. Stakeholders must monitor federal infrastructure commitment continuity and provincial mining lease approvals, as these funding pipelines determine fleet absorption capacity more than equipment innovation cycles.
Market Dynamics
Federal infrastructure stimulus programs and Environment and Climate Change Canada's Tier 4 Final emission standards are forcing simultaneous fleet replacement and compliance redesign across Canadian construction equipment procurement channels.
Growth Catalysts
- Alberta oil sands remediation:Federal remediation mandates and provincial lease rehabilitation requirements are accelerating excavator and loader procurement for environmental restoration projects across northern Alberta.
- Ontario transit expansion:The province's subway and light rail corridor investments are creating sustained demand for tunnel boring equipment and specialized material handling machinery in the Greater Toronto Area.
- Tier 4 Final compliance:Environment and Climate Change Canada's emission standards are compressing replacement cycles as operators retire pre-compliant diesel fleets to avoid operational restrictions.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings for high-grade steel and precision hydraulic systems are compressing manufacturer margins and triggering price escalation clauses in equipment contracts.
- Dealer network concentration:Remote mining territories in northern Canada depend on a thin distributor layer, creating service access bottlenecks and extended downtime risks for operators.
- Electrification technical ceiling:Battery energy density limitations and cold-weather performance degradation are blocking full electrification of heavy-duty mining configurations.
Strategic Opportunities
- Telematics-integrated fleet management:Convergence of IoT sensors and predictive maintenance software is enabling subscription-based uptime guarantees that shift revenue from equipment sales to recurring service contracts.
- Saskatchewan agricultural-adjacent construction:Grain handling infrastructure and rural road maintenance programs represent underpenetrated demand for compact equipment lines outside traditional urban construction corridors.
- British Columbia hydroelectric expansion:Provincial Crown corporation procurement for dam maintenance and run-of-river projects is creating specialized demand for amphibious excavators and precision grading equipment.
Industry Challenges
- Certified technician scarcity:Tier 4 Final after-treatment systems and telematics diagnostics require specialized training that Canadian technical colleges are not yet producing at replacement rates.
- Legacy fleet integration friction:Operators running mixed-generation equipment face parts standardization failures and software incompatibility between pre-Tier 4 and current-generation control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Construction Equipment Market |
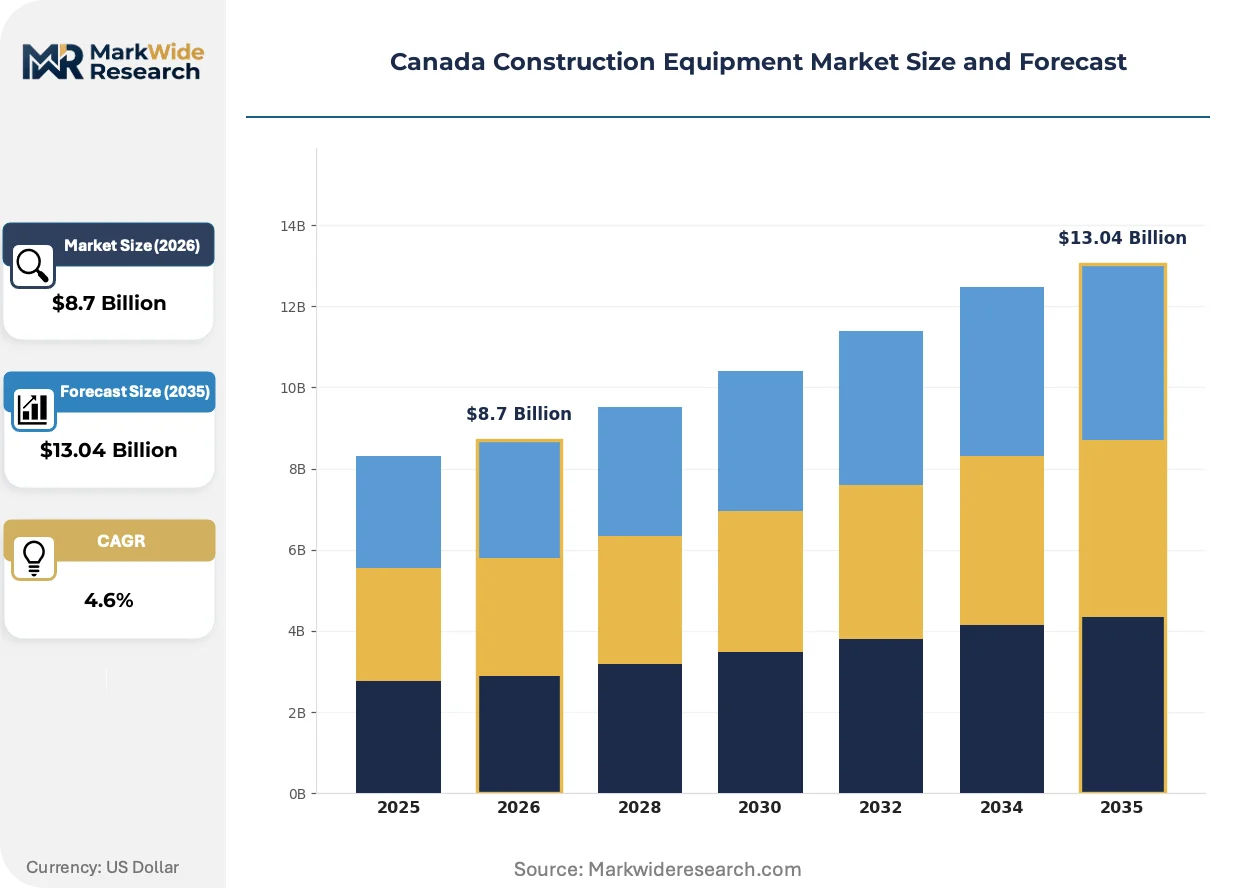
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Loaders, Cranes Deployment Model: On-Road, Off-Road, Compact, Heavy-Duty End User: Residential, Commercial, Infrastructure, Mining Service Type: Rental, Sales, Maintenance, Repair |
| Companies Covered | Caterpillar, Komatsu, Hitachi Construction Machinery, Volvo Construction Equipment, SANY, XCMG, Liebherr, John Deere, JCB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Construction Equipment Market Trends and Innovations
Digitalization and emission compliance are restructuring how Canadian construction equipment is specified, financed, and maintained across project types.
Hybrid diesel-electric powertrains are migrating from underground mining loaders to surface construction excavators. Mid-size fleet operators in Quebec's urban demolition sector are piloting these configurations to reduce fuel consumption during intermittent duty cycles. The technology is migrating from niche mining applications to mainstream roadbuilding and utility installation contracts where idle time dominates operational profiles.
Environment and Climate Change Canada's evolving carbon pricing framework is tightening the cost gap between conventional diesel and lower-emission alternatives. The Clean Fuel Regulations are incrementally raising compliance costs for high-carbon intensity fuels used in off-road equipment. Western Canadian contractors with exposure to oil sands and mining clients are pre-emptively specifying Tier 4 Final or hybrid units to lock in carbon cost visibility over multi-year project horizons.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-tier general contractors. Rental providers are bundling maintenance, telematics, and emission compliance verification into single monthly rates that transfer residual value risk. This restructuring is most visible in Ontario's institutional construction segment, where school boards and hospital authorities prefer operational expenditure treatment for equipment access.
Canada Construction Equipment Market Segmentation
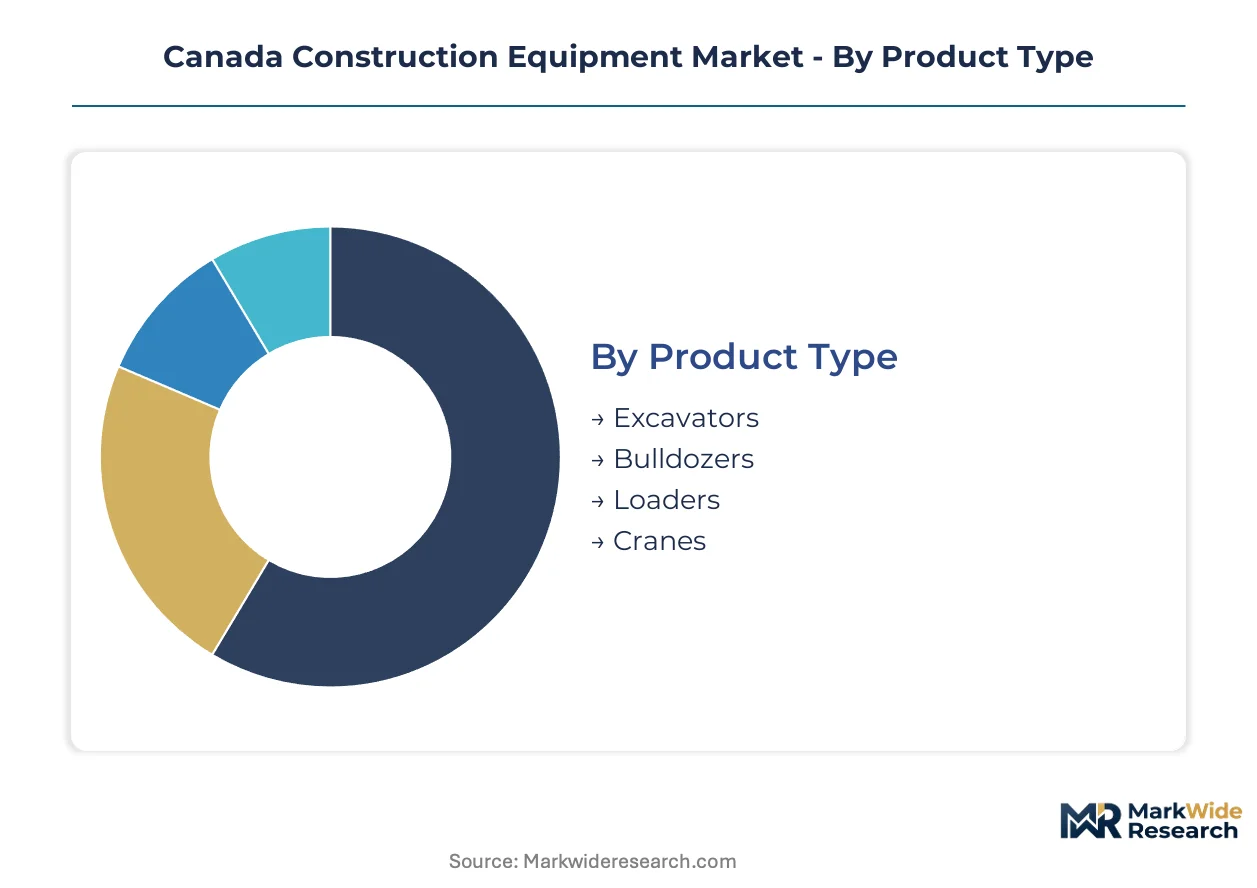
Equipment specification in Canada diverges sharply between urban infrastructure corridors and remote resource extraction zones. Segmentation reveals how procurement patterns split across emission compliance tiers, project scale, and service delivery models.
Product Type:
Application versatility determines equipment selection across Canadian construction verticals, with trenching intensity and material density driving specification requirements.
- Excavators:Hydraulic systems rated between 75 and 750 horsepower dominate earthmoving operations through interchangeable boom and bucket configurations. Alberta oil sands remediation and Ontario transit tunneling concentrate demand for extended-reach and high-lift variants capable of operating in confined or contaminated environments.
- Loaders:Articulated steering and hydrostatic transmissions enable material handling across uneven terrain. Saskatchewan grain handling infrastructure and British Columbia hydroelectric maintenance projects favor compact wheel loaders with quick-attach couplers for seasonal versatility.
- Bulldozers:Tracked undercarriages with elevated sprocket designs deliver traction for grading and pushing operations in unimproved conditions.
- Cranes:Lattice boom and hydraulic crawler configurations serve structural lifting demands across urban density corridors and remote industrial sites.
Excavators command the established base. The steepest expansion runs through compact loader configurations serving agricultural-adjacent construction segments.
Deployment Model:
Operating environment severity dictates chassis reinforcement, emission system protection, and mobility architecture across Canadian project types.
- Off-Road:Sealed hydraulic systems and reinforced undercarriages withstand unimproved terrain exposure. Northern Alberta mining remediation and British Columbia run-of-river hydroelectric sites specify these units for amphibious and slope-stability applications where road access is absent.
- Heavy-Duty:Frame structures and powertrains engineered for continuous high-load cycles support mass earthmoving and quarry operations. Tier 4 Final after-treatment integration adds weight and thermal management complexity that manufacturers address through enlarged cooling packages.
- On-Road:Transport Canada Motor Vehicle Safety Regulations govern equipment variants traveling between project sites on public highways.
- Compact:Reduced footprint and lower ground pressure enable operation in urban demolition and utility installation corridors with space constraints.
Heavy-duty configurations anchor fleet investment in resource extraction territories. Compact deployment is gaining share fastest in Quebec urban demolition and institutional construction segments.
End User:
Project ownership structure shapes procurement authority, financing treatment, and equipment lifecycle expectations across Canadian construction demand.
- Infrastructure:Federal and provincial Crown corporations specify emission-compliant fleets through multi-year capital programs. Ontario subway expansion and British Columbia hydroelectric maintenance generate sustained tender volumes with extended warranty and telematics requirements.
- Mining:Oil sands lease operators and hard rock extractors prioritize uptime guarantees and dealer network proximity over acquisition cost. Alberta remediation mandates and Saskatchewan potash expansion drive replacement cycles for underground and surface loading equipment.
- Residential:Single-family and low-rise developers favor rental flexibility over ownership for project-specific equipment access.
- Commercial:Private sector general contractors balance capital efficiency against fleet availability for institutional and retail construction.
Mining end users concentrate the highest per-unit expenditure. Infrastructure procurement is expanding most quickly as federal stimulus programs accelerate fleet absorption.
Service Type:
Revenue model selection reflects capital constraint severity, utilization predictability, and residual value risk tolerance among Canadian equipment users.
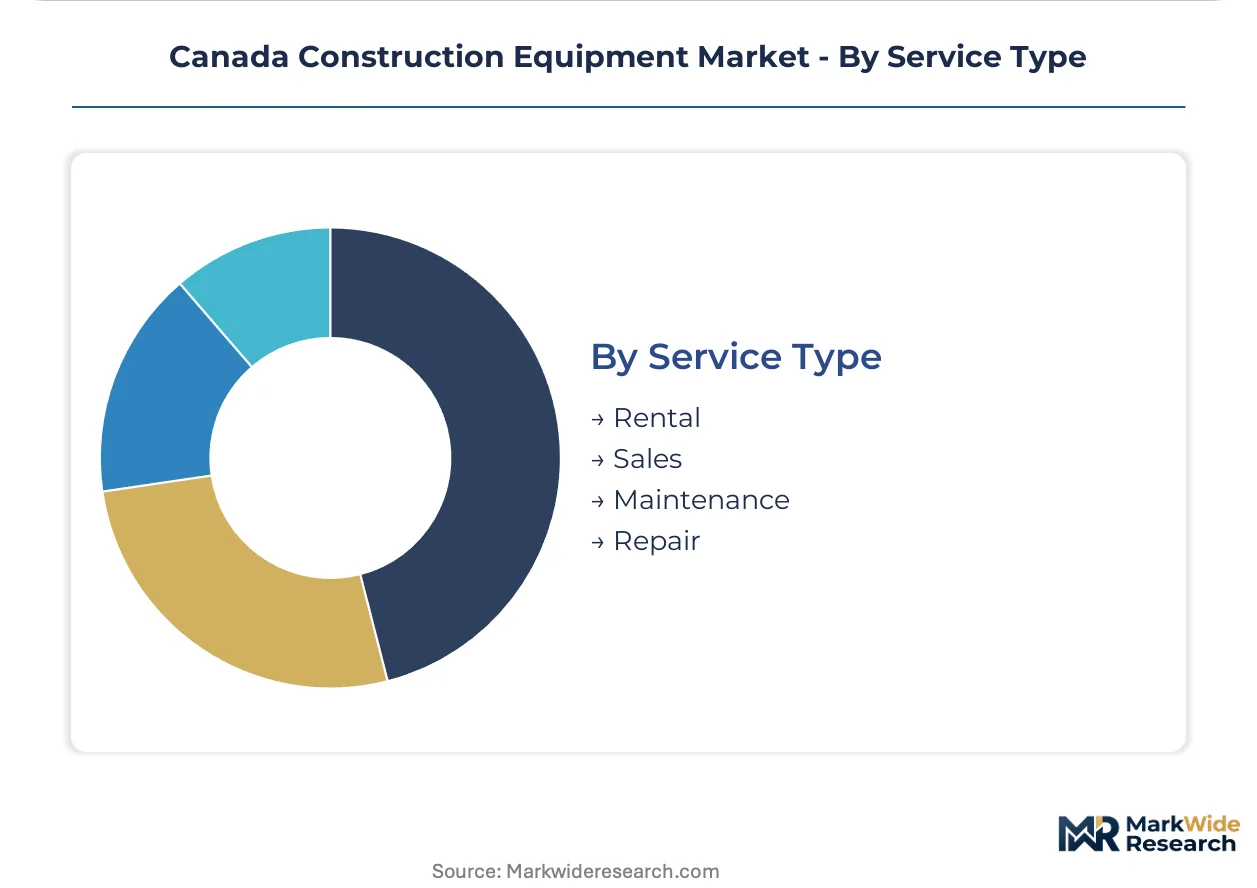
- Rental:Monthly rates bundling maintenance, telematics, and emission compliance verification transfer residual value risk to providers. Ontario school boards and hospital authorities prefer operational expenditure treatment, accelerating adoption among mid-tier general contractors with irregular project pipelines.
- Maintenance:Predictive service contracts tied to IoT sensor data reduce unplanned downtime through component replacement scheduling. Remote mining territories depend on concentrated dealer networks for these agreements.
- Sales:Direct purchase concentrates margin pools in heavy-duty mining configurations with specialized attachment packages.
- Repair:Event-based service addresses component failures outside warranty coverage, particularly for legacy fleet integration challenges.
Sales transactions dominate heavy mining equipment procurement. Rental service is climbing the fastest as institutional project owners shift capital expenditure toward operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alberta mining operators exhibit lowest price elasticity, absorbing premium equipment costs for uptime guarantees. Ontario institutional buyers prioritize operational expenditure treatment over capital efficiency. Quebec contractors show highest sensitivity to financing terms and rental rate structures.
Alberta
Oil sands remediation mandates and potash expansion projects drive excavator and loader procurement across northern lease territories. Environment and Climate Change Canada enforces Tier 4 Final standards that compress replacement cycles for diesel fleets operating in Fort McMurray and Edmonton corridor sites. Calgary anchors dealer network concentration for remote mining service contracts.
Ontario
Subway and light rail corridor investments generate sustained demand for tunnel boring equipment and specialized material handlers. Infrastructure Ontario procurement programs mandate telematics integration and extended warranty coverage for Crown corporation fleet specifications. Greater Toronto Area contractors are shifting toward equipment-as-a-service models for institutional construction access.
Quebec
Urban demolition contractors pilot hybrid diesel-electric excavators to reduce fuel consumption during intermittent duty cycles. The province's carbon pricing framework tightens cost gaps between conventional diesel and lower-emission alternatives. Montreal construction clusters are adopting compact equipment configurations for space-constrained utility installation corridors.
British Columbia
BC Hydro Crown corporation procurement for dam maintenance and run-of-river projects creates specialized demand for amphibious excavators. Transport Canada Motor Vehicle Safety Regulations govern equipment variants traveling between remote hydroelectric sites on public highways. Vancouver Island and mainland coastal contractors specify sealed hydraulic systems for slope-stability applications.
Saskatchewan
Grain handling infrastructure and rural road maintenance programs generate underpenetrated demand for compact wheel loaders with quick-attach couplers. Provincial agricultural-adjacent construction segments favor seasonal versatility over year-round fleet utilization. Regina and Saskatoon equipment distributors are expanding rental service coverage for irregular project pipelines.
Canada Construction Equipment Market Competitive Landscape
Integrated full-line manufacturers and specialized regional fabricators split the market along capital intensity and service network density vectors. Dealer network proximity determines competitive position in remote mining territories where downtime costs exceed equipment price premiums. Three archetypes dominate: North American heritage brands with dense service infrastructure, Asian scale manufacturers with cost-optimized production, and European precision engineering specialists. Consolidation pressure is accelerating through telematics platform integration and predictive maintenance service bundling.
Within the heritage-brand tier, Caterpillar and John Deere exemplify dealer-network-dependent competitive positioning. Komatsu anchors the Asian-scale manufacturer archetype with integrated fleet management program offerings. These three companies represent distinct strategic approaches to emission compliance integration and aftermarket service revenue capture across Canadian provincial procurement channels.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Hitachi Construction Machinery |
| Volvo Construction Equipment |
| SANY |
| XCMG |
| Liebherr |
| John Deere |
| JCB |
| Others |
Pricing and Supply Chain Analysis
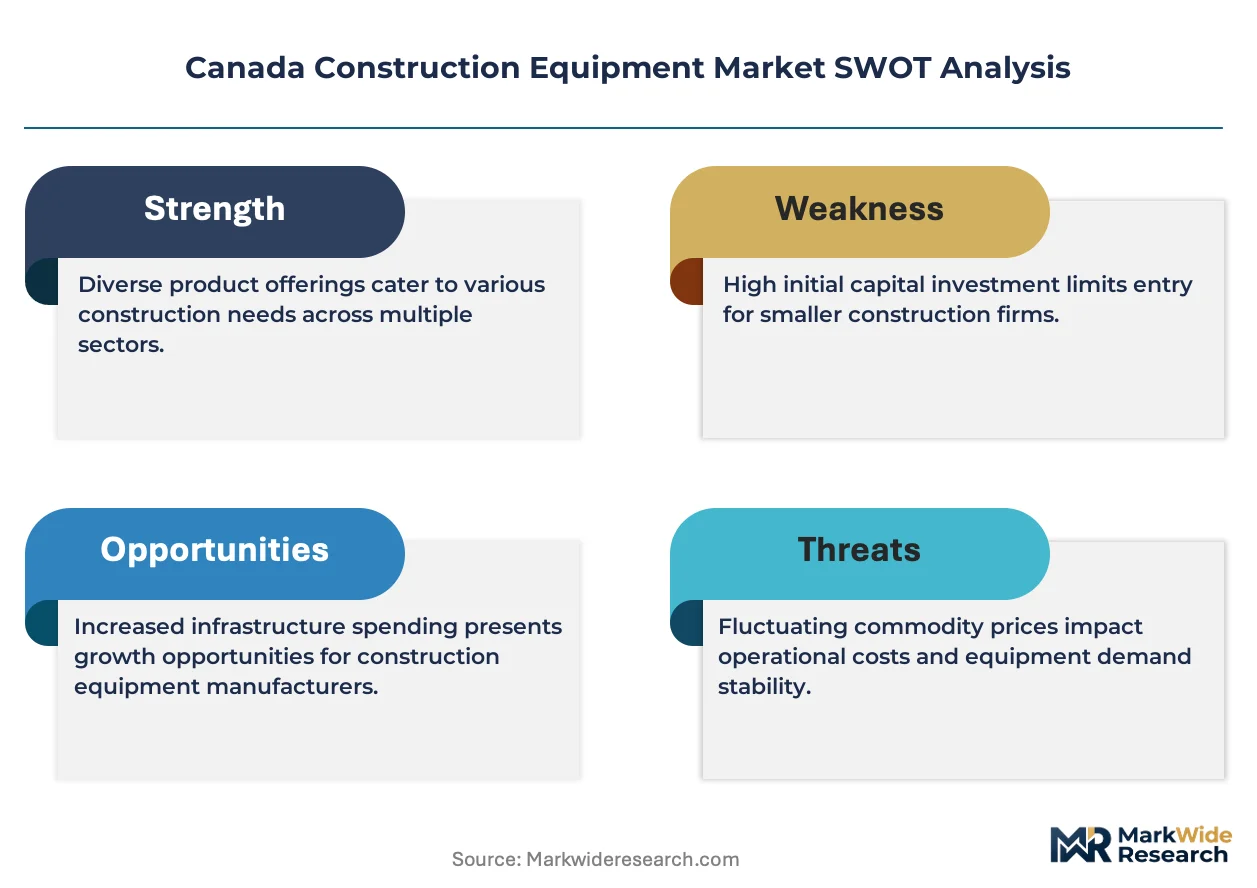
Undercapacity in North American steel production and precision hydraulic component manufacturing is compressing supplier margins and forcing equipment manufacturers toward longer-term contract structures that lock in cost visibility for Tier 4 Final powertrain integration.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture more than initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates mining-grade configurations with uptime guarantees from institutional rental bundles and compact utility lines. Cost compression in mid-size excavator segments is intensifying because Asian scale manufacturers are expanding Canadian dealer coverage. Mining operators in Alberta exhibit lowest price sensitivity, absorbing premium costs for remote service access, while Quebec urban contractors show highest sensitivity to financing terms.
Supply Chain Analysis
High-grade steel feedstock draws from integrated mills in the United States, South Korea, and Japan, while precision hydraulic systems rest on German and Japanese component specialists. Diesel engine after-treatment modules hinge on platinum group metal supply concentrated in South Africa and Russia. Tariff exposure on steel and aluminum inputs creates margin volatility for manufacturers assembling in Ontario and Alberta. Distribution runs through manufacturer-authorized dealer networks with captive parts warehousing in Calgary, Toronto, and Montreal corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canadian construction equipment procurement is bottlenecked by certified technician scarcity for Tier 4 Final diagnostics and telematics integration, creating competitive advantage for stakeholders who control training pipeline access or predictive maintenance data platforms.
For Market Incumbents: Pre-empt emerging Asian scale manufacturers by expanding captive remanufacturing capacity in Edmonton and Hamilton corridors to control residual value capture on retired fleets. Anchor dealer network density in northern Alberta mining territories where service proximity outweighs acquisition cost in procurement decisions. Invest in telematics platform standardization to lock in subscription revenue before competitors achieve interoperability.
For New Entrants and Emerging Players: Pursue Saskatchewan agricultural-adjacent construction segments where seasonal equipment demand and thin incumbent service coverage create white-space opportunity. Target compact wheel loader configurations with quick-attach versatility for grain handling infrastructure projects outside traditional urban procurement channels. Enter through rental service bundling that transfers residual value risk and bypasses capital-intensive direct sales infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward telematics-integrated fleet management platforms with established recurring revenue bases and proprietary predictive maintenance algorithms. Long-term viability over the coming decade favors asset-light service providers over capital-heavy manufacturing positions in emission-compliant equipment categories. Monitor federal infrastructure commitment continuity and provincial mining lease approval velocity as inflection indicators for fleet absorption capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables subscription-based uptime guarantees that shift revenue from equipment sales to recurring service contracts. |
| Backward Integration into Remanufacturing | Captures residual value from Tier 4 Final fleet retirements while reducing new equipment cost exposure. |
| Dealer Network Expansion in Remote Territories | Secures competitive position in Alberta oil sands and northern mining corridors where downtime costs exceed price premiums. |
| Hybrid Powertrain Development | Addresses Environment and Climate Change Canada carbon pricing pressure while circumventing full electrification technical barriers. |
| Equipment-as-a-Service Contracting | Aligns with Ontario institutional procurement preferences for operational expenditure treatment over capital efficiency. |
Research Methodology
A standing panel of maintenance directors at mining operators, plant engineers at provincial Crown corporations, OEM procurement teams at tier-one manufacturers, and aftermarket service heads at authorized dealers provided ongoing calibration across primary interview rounds. Secondary validation drew from Environment and Climate Change Canada emission compliance filings, Transport Canada Motor Vehicle Safety Regulations, provincial infrastructure procurement databases, and customs trade data on steel and hydraulic component imports. Bottom-up equipment shipment tracking and top-down provincial construction expenditure analysis were triangulated to anchor volume estimates.
Scenario-bracketing around federal infrastructure stimulus continuity and provincial mining lease approval velocity bounded the projection horizon. Segmentation modeling captured product type, deployment model, end user, and service type dimensions alongside provincial regulatory cluster differentiation. CAGRs were derived from equipment replacement cycle compression under Tier 4 Final mandates and rental service expansion trajectories in institutional construction segments.
Sensitivities concentrate around federal election cycles affecting infrastructure commitment continuity, steel tariff regime shifts, and battery energy density breakthroughs that could accelerate electrification timelines. Cross-checking against provincial capital budget disclosures and Crown corporation fleet procurement schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Global Hot Runner Market
Construction Equipment
Fogging Machine Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Used Construction Equipment Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Fixed Crane Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Bucket Teeth and Tips Market