
 Asia-Pacific Building Automation System Market | 2026-2036
Asia-Pacific Building Automation System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Building Automation System Market Insights
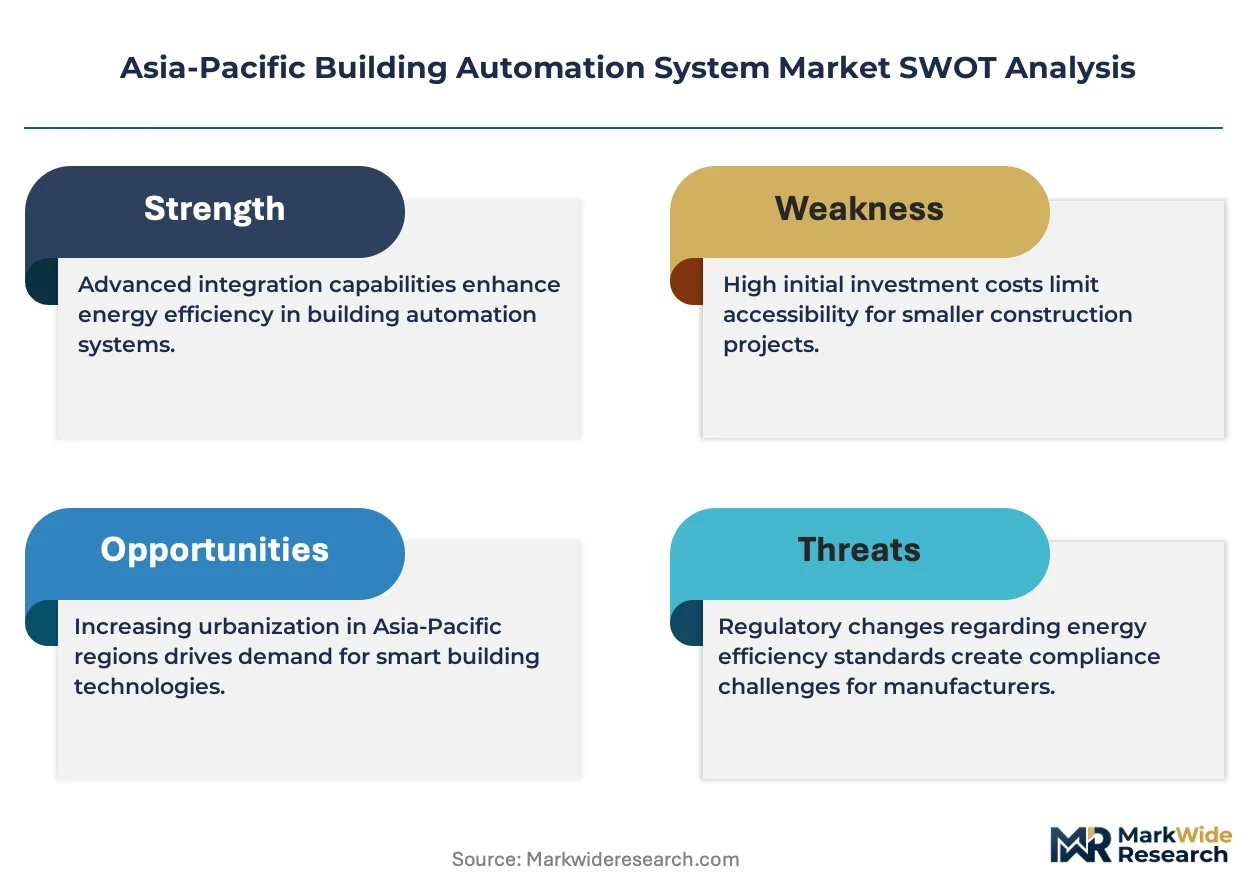
The Asia-Pacific building automation system market is restructuring around a widening gap between premium integrated platforms and commodity sensor hardware. Johnson Controls leverages its control software stack to command higher-margin installation and managed service contracts. Siemens competes through deep domain expertise in HVAC optimization, while Honeywell International anchors its position with security-system integration into broader building management platforms.
Building automation systems comprise networked controllers, sensors, actuators, and software platforms that regulate HVAC, lighting, security, and energy consumption through centralized or distributed architectures operating on BACnet, Modbus, or proprietary protocols. Their primary purpose is to reduce operational energy expenditure while maintaining occupant comfort and safety compliance. HVAC Control and Energy Management Systems lead product type deployment because retrofit cycles align with regulatory efficiency deadlines, while Cloud-Based Solutions represent the fastest-growing technology segment as facility managers shift from on-premise servers to subscription-based remote monitoring. Commercial Buildings dominate end-user demand, though Institutional Buildings carry higher per-square-meter technology intensity due to stringent compliance requirements.
China's MEE enforces building energy consumption disclosure rules that directly expand demand for metering and analytics subsystems. Japan's METI oversees Top Runner standards that push equipment replacement toward intelligent control compatibility. India's BIS certification requirements for electrical control panels create compliance-driven procurement patterns across its construction sector. Stakeholders must weigh cloud dependency against data sovereignty requirements as ASEAN member states draft divergent cybersecurity frameworks for critical infrastructure.
Market Dynamics
Cloud-native building management platforms are compressing installation cycles and displacing on-premise server architectures across Southeast Asian commercial developments. This infrastructure shift reconfigures vendor economics toward recurring software revenue and away from one-time hardware margins.
Growth Catalysts
- China's dual carbon goals:Mandatory building energy consumption disclosure rules enforced by the MEE are accelerating metering subsystem deployment in tier-one cities.
- Smart city developments:India's urban infrastructure programs are embedding integrated control platforms into new institutional construction across Delhi-Mumbai industrial corridors.
- Edge computing convergence:Localized data processing at the controller level is reducing latency for real-time HVAC optimization in Australian healthcare facilities.
Market Restraints
- Semiconductor input volatility:Controller and sensor production faces concentrated sourcing exposure to East Asian foundry capacity.
- Proprietary protocol lock-in:Legacy BACnet and Modbus installations create switching costs that slow platform consolidation in Japan's existing building stock.
- Skilled technician scarcity:Commissioning and calibration of integrated systems requires certified specialists whose training pipelines lag demand in Indonesia and Vietnam.
Strategic Opportunities
- Philippines commercial retrofit wave:Aging mall and office infrastructure presents untapped demand for energy management retrofits ahead of anticipated efficiency mandates.
- Subscription-based remote monitoring:Facility management outsourcing firms are adopting SaaS control platforms to serve distributed retail portfolios.
- Thailand's green building incentives:Tax advantages for LEED-equivalent certifications are pulling intelligent lighting and occupancy sensor bundles into new construction specifications.
Industry Challenges
- Cybersecurity framework fragmentation:Divergent ASEAN national standards for critical infrastructure protection complicate cross-border platform deployment.
- Interoperability certification delays:Multi-protocol gateway testing timelines extend project delivery schedules and strain contractor cash flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Building Automation System Market |
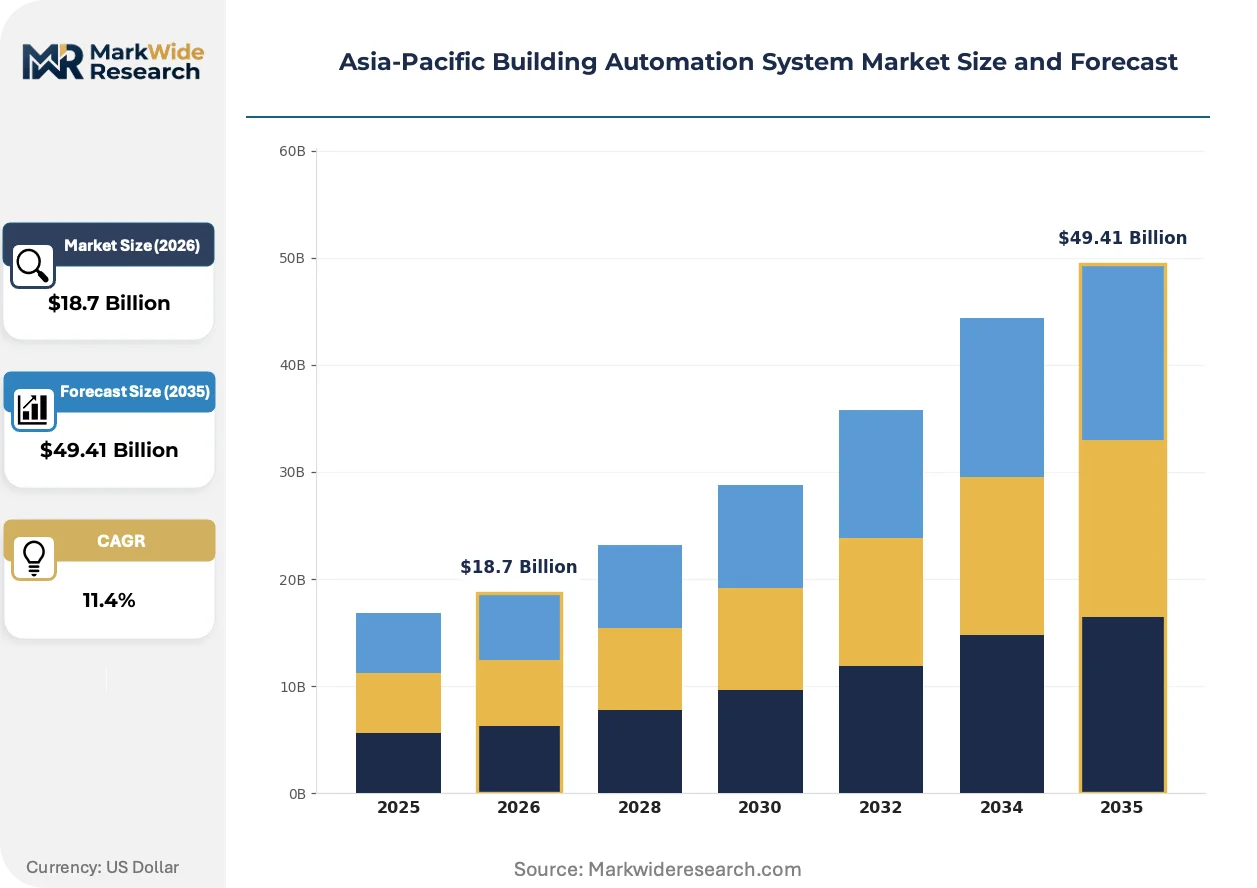
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control, HVAC Control, Security Systems, Energy Management Systems End User: Commercial Buildings, Residential Buildings, Industrial Facilities, Institutional Buildings Technology: Wired Technologies, Wireless Technologies, Hybrid Technologies, Cloud-Based Solutions Service Type: Installation Services, Maintenance Services, Consulting Services, Managed Services |
| Companies Covered | Johnson Controls, Siemens, Honeywell International, Schneider Electric, ABB, Mitsubishi Electric, Carrier Global, Bosch Sicherheitssysteme, Trane Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Building Automation System Market Trends and Innovations
Digital twin technology is penetrating building operations, creating virtual replicas that enable predictive maintenance and scenario simulation before physical intervention. This capability is restructuring how facility managers justify capital upgrades and negotiate service contracts.
Digital twin software is expanding into mid-rise commercial portfolios in Singapore and Sydney, where property technology funds are underwriting pilot deployments. Asset managers are compressing due diligence cycles by simulating energy retrofit outcomes virtually. The technology is expanding into smaller building footprints previously excluded from advanced analytics.
Japan's METI Top Runner standards are mandating intelligent control compatibility for replacement HVAC equipment, forcing manufacturers to embed native connectivity. Equipment suppliers are redesigning product lines to avoid exclusion from government procurement channels. Commercial building operators in Osaka and Tokyo are accelerating replacement schedules to capture efficiency incentives.
Facility management procurement is consolidating around performance-guarantee contracts that bundle hardware, software, and energy savings commitments. Traditional equipment vendors are ceding margin to integrators who assume operational risk. This restructuring is most visible in Australian healthcare and education verticals where budget certainty outweighs capital ownership preferences.
Asia-Pacific Building Automation System Market Segmentation
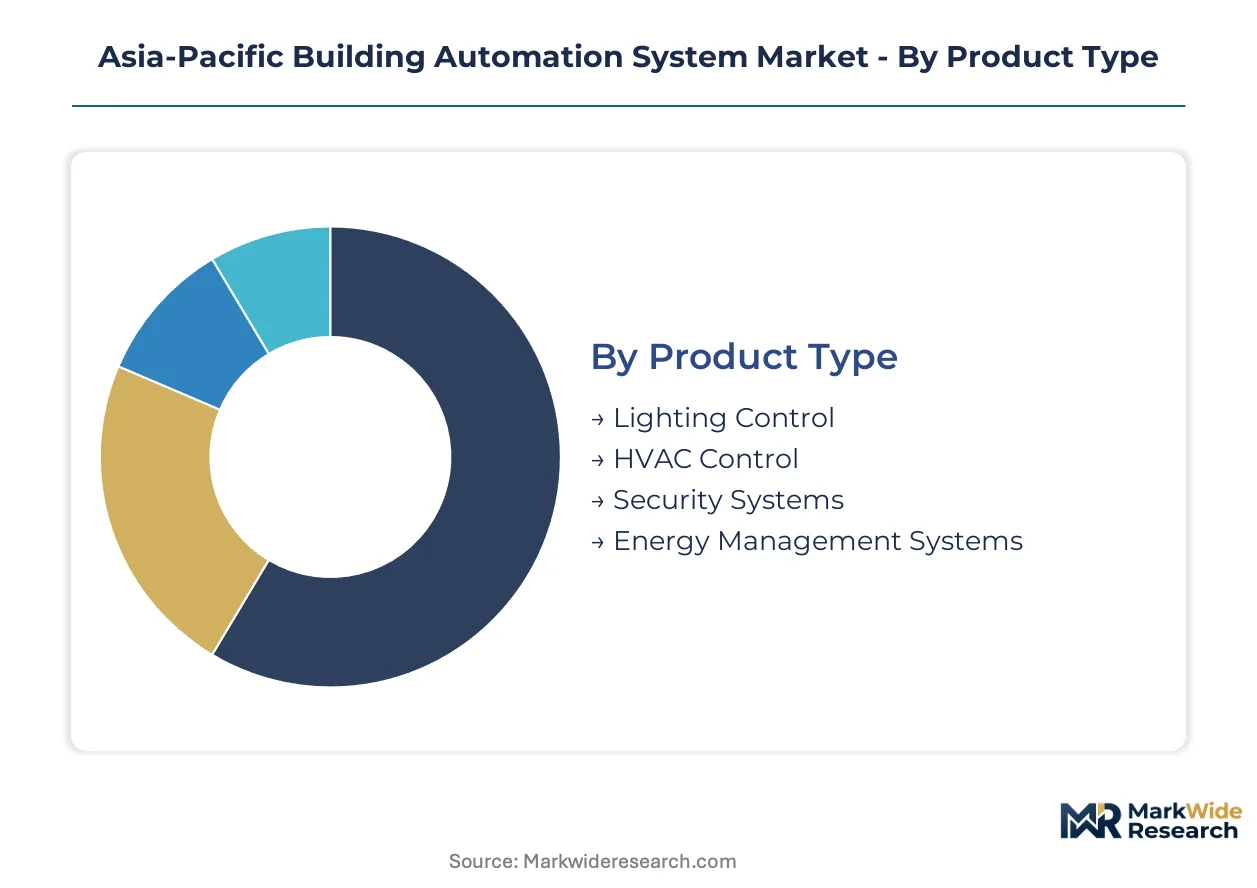
Building automation system procurement in Asia-Pacific follows distinct technical and economic logics across product architectures, end-use requirements, and service delivery models. Understanding these segment boundaries reveals where integration complexity drives margin concentration versus where standardization enables scale.
Product Type:
Integration depth varies sharply across this category, with some segments functioning as standalone retrofit entry points while others demand full-building platform embedding from inception.
- HVAC Control:Controllers, variable air volume terminals, and chiller optimization software regulate thermal environments through BACnet or Modbus protocols. Demand clusters in Japan's existing commercial stock where METI Top Runner standards force equipment replacement toward intelligent compatibility.
- Energy Management Systems:Metering infrastructure, analytics dashboards, and demand response interfaces track consumption patterns and automate load shedding. China's tier-one cities are accelerating deployment as MEE disclosure rules mandate granular consumption visibility for buildings above threshold sizes.
- Lighting Control:Occupancy sensors, daylight harvesting controllers, and networked dimming systems.
- Security Systems:Access control, video surveillance, and intrusion detection integrated into broader management platforms.
Volume placements concentrate in HVAC Control; the faster expansion belongs to Energy Management Systems.
End User:
Cost tier separation dominates this category, with premium technology intensity correlating to compliance burden rather than building scale.
- Commercial Buildings:Office towers, retail complexes, and hospitality properties deploy integrated platforms to reduce operational expenditure and meet tenant sustainability expectations. Southeast Asian mall operators in Bangkok and Jakarta are retrofitting aging infrastructure ahead of anticipated efficiency mandates.
- Institutional Buildings:Hospitals, universities, and government facilities carry higher per-square-meter technology intensity due to stringent safety and compliance requirements. Australian healthcare verticals are consolidating procurement around performance-guarantee contracts that bundle hardware with operational risk transfer.
- Industrial Facilities:Manufacturing plants and logistics centers requiring environmental control for process integrity.
- Residential Buildings:Multi-family developments and luxury condominiums with varying smart home integration depth.
Commercial Buildings absorb the greatest absolute deployment volume; Institutional Buildings command the steepest technology spend per square meter.
Technology:
Application context determines architecture choice, with new construction favoring embedded connectivity while retrofits accommodate hybrid or overlay approaches.
- Cloud-Based Solutions:Subscription platforms enabling remote monitoring, predictive analytics, and multi-site portfolio management through browser-based interfaces. Facility management outsourcing firms across India are adopting these platforms to serve distributed retail footprints without on-premise server investment.
- Wireless Technologies:Zigbee, LoRaWAN, and proprietary mesh networks reduce installation disruption in existing structures. Australian healthcare facilities are deploying wireless sensor networks to minimize construction downtime during control system upgrades.
- Wired Technologies:Ethernet, BACnet/IP, and dedicated control cabling for new construction and high-reliability environments.
- Hybrid Technologies:Combined wired backbone with wireless edge extension for phased deployment scenarios.
Cloud-Based Solutions are climbing the fastest as facility managers shift from capital-intensive server ownership to operational expenditure models; Wireless Technologies dominate retrofit applications where structural disruption carries prohibitive cost.
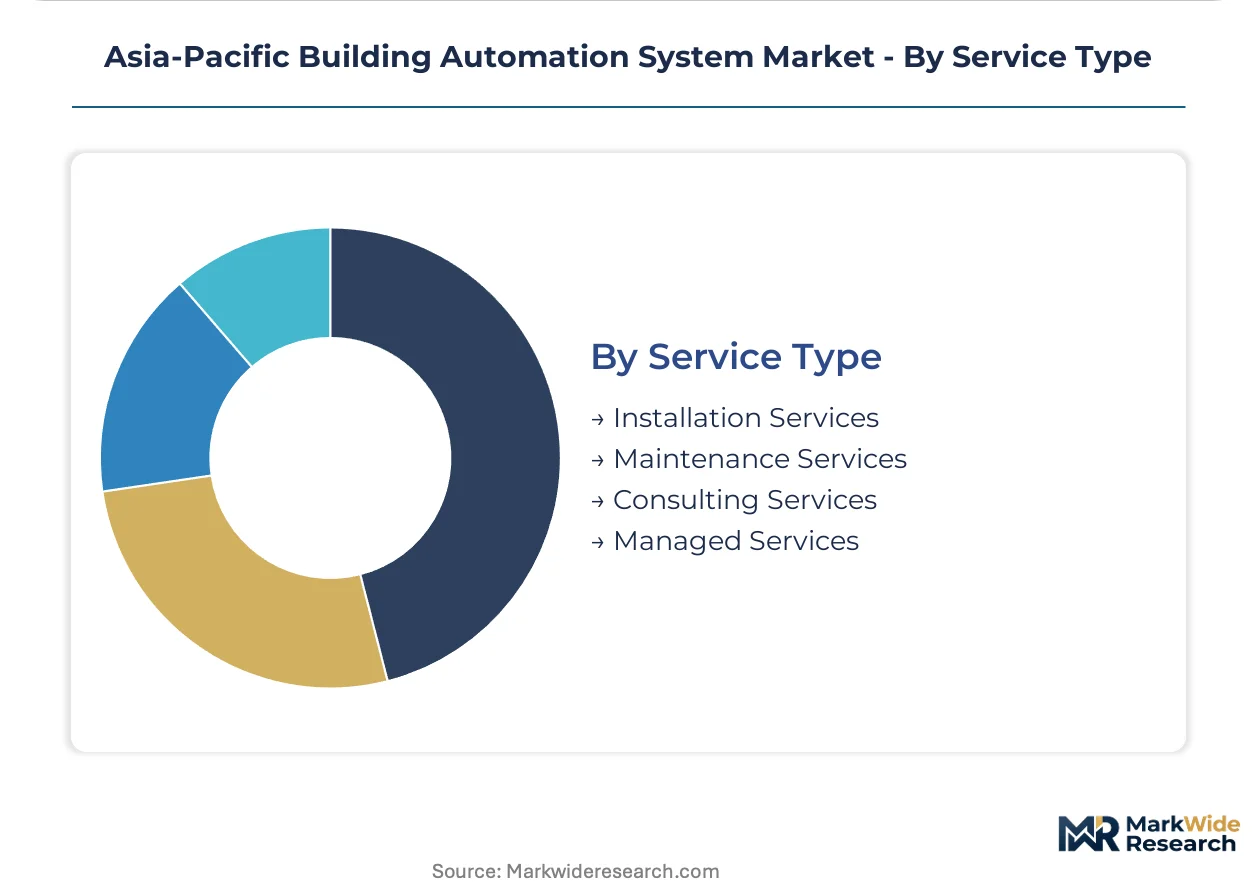
Service Type:
Customer type and internal capability gaps shape procurement patterns, with sophisticated operators favoring risk-transfer arrangements while fragmented ownership prefers transactional relationships.
- Managed Services:Long-term contracts covering system operation, energy performance guarantees, and continuous optimization. Australian education and healthcare sectors are consolidating around these arrangements where budget certainty outweighs capital ownership preferences.
- Installation Services:Controller programming, sensor commissioning, and protocol integration during construction or retrofit. Skilled technician scarcity in Indonesia and Vietnam is extending project timelines and straining contractor cash flows.
- Maintenance Services:Preventive and corrective support for hardware and software components.
- Consulting Services:Energy audits, system design, and compliance advisory for owner-operators and developers.
Installation Services generate the greatest immediate revenue capture; Managed Services are expanding most quickly as performance contracting restructures vendor economics toward recurring streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Marina Bay district and Punggol Digital District anchor the region's most advanced smart building deployments, where integrated automation platforms serve as testbeds for city-scale digital infrastructure rollouts.
China
Shanghai and Beijing's tier-one commercial towers are retrofitting centralized energy management systems ahead of MEE disclosure deadlines. The Ministry of Ecology and Environment enforces consumption transparency rules for buildings exceeding threshold sizes. The Yangtze River Delta manufacturing corridor is embedding automation subsystems into new industrial facilities at scale.
Japan
Osaka and Tokyo commercial operators are accelerating HVAC replacement cycles to capture METI Top Runner efficiency incentives. METI mandates intelligent control compatibility for new equipment procurement across government channels. The Kansai region's aging office stock presents concentrated retrofit demand for multi-protocol integration gateways.
India
Delhi-Mumbai industrial corridor developments are specifying cloud-native control platforms for new institutional construction. BIS certification requirements for electrical control panels shape procurement patterns across the construction sector. Bangalore's technology park expansions are driving demand for subscription-based remote monitoring services.
Australia
Sydney and Melbourne healthcare facilities are consolidating procurement around performance-guarantee automation contracts. The country's national building energy regulator enforces efficiency disclosure through NABERS ratings that reward integrated system deployment. Queensland's education sector is adopting managed service arrangements that transfer operational risk to vendors.
Southeast Asia
Bangkok and Jakarta mall operators are retrofitting aging infrastructure ahead of anticipated efficiency mandates. Divergent ASEAN national cybersecurity frameworks complicate cross-border platform standardization. Vietnam's skilled technician scarcity extends commissioning timelines for complex system integrations.
Asia-Pacific Building Automation System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software integration depth, with control-stack ownership determining service contract economics. The vendor base stratifies into three tiers: full-stack platform providers, equipment-specialist integrators, and regional installation contractors. Strategic consolidation centers on cloud-native platform acquisitions and managed service capability buildouts.
Within the full-stack tier, Johnson Controls and Siemens exemplify divergent margin capture strategies. Johnson Controls leverages control software ownership to anchor higher-margin installation and managed service relationships. Siemens competes through HVAC optimization domain expertise embedded in equipment-software bundles. Schneider Electric occupies a position bridging hardware manufacturing and digital service platforms across the region's commercial retrofit wave.
| Leading Market Players |
|---|
| Johnson Controls |
| Siemens |
| Honeywell International |
| Schneider Electric |
| ABB |
| Mitsubishi Electric |
| Carrier Global |
| Bosch Sicherheitssysteme |
| Trane Technologies |
| Others |
Pricing and Supply Chain Analysis
Copper and semiconductor price indices cascade through controller and sensor manufacturing into three distinct pricing tiers across the Asia-Pacific building automation system market, compressing margins for commodity hardware vendors while insulating software-integrated platform providers from input cost volatility.
Pricing Analysis
Outcome-based pricing anchored to energy savings guarantees dominates the Australian healthcare and education verticals, where facility managers prioritize budget certainty over capital ownership. Three-tier pricing structure across premium, standard, and economy levels separates full-stack platform providers from equipment-specialist integrators and regional installation contractors. Cost compression in the hardware tier intensifies because foundry capacity constraints elevate semiconductor input costs. Small-to-mid commercial building operators exhibit the greatest price sensitivity, while institutional buyers with stringent compliance burdens accept premium positioning.
Supply Chain Analysis
Dual-sourcing requirements from tier-one commercial developers in Singapore and Australia mandate multi-supplier qualification for critical controllers and sensors, fragmenting procurement across qualified vendor lists. Manufacturing concentrates in China, Taiwan, and South Korea for semiconductor components, with Japan and Germany supplying precision actuators and HVAC equipment. Controller production draws from concentrated East Asian foundry capacity, sensor assemblies rest on rare earth magnet supply from Chinese processors, and software development centers on Indian engineering hubs. Single-source vulnerability in advanced node semiconductor fabrication creates structural exposure. Distribution runs through authorized system integrators and direct OEM channels to end-user facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where China's MEE disclosure rules and Japan's METI Top Runner standards erect barrier-to-entry moats favoring certified platform providers over unqualified hardware assemblers.
For Market Incumbents: Anticipate margin compression in standalone sensor hardware as cloud-native platforms displace on-premise architectures across Southeast Asian commercial developments. Consolidate around managed service capabilities that transfer operational risk to vendors, and deepen software stack ownership to anchor recurring revenue streams against commodity hardware price erosion. For New Entrants and Emerging Players: Direct-to-facility-manager SaaS channels offer the most penetrable route into India's distributed retail portfolio management segment, where outsourcing firms seek subscription control platforms without server infrastructure investment. Target the Philippines commercial retrofit wave ahead of anticipated efficiency mandates, and position around wireless retrofit solutions that minimize structural disruption in aging Bangkok and Jakarta mall infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native platform specialists with established ASEAN regulatory compliance frameworks during periods of semiconductor input volatility. Long-term viability hinges on recurring revenue share expansion over hardware shipment volumes. Watch for consolidation signals when multi-protocol gateway testing timelines strain contractor cash flows and force capability exits.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Subscription revenue restructuring displaces one-time hardware margins across Southeast Asian commercial portfolios. |
| Multi-Protocol Gateway Certification | Accelerated interoperability testing reduces project delivery delays in Japan's BACnet-Modbus legacy building stock. |
| Managed Service Capability Buildout | Performance-guarantee contracts capture Australian healthcare procurement consolidation around operational risk transfer. |
| Edge Computing Controller Integration | Localized data processing reduces latency for real-time HVAC optimization in bandwidth-constrained facilities. |
| Digital Twin Technology Deployment | Virtual retrofit simulation compresses due diligence cycles for Singapore and Sydney property technology funds. |
Research Methodology
Regulatory filings from China's MEE, Japan's METI, and India's BIS formed the secondary backbone for compliance-driven demand quantification, supplemented by customs data on controller and sensor trade flows, SEC disclosures from listed building technology vendors, and smart city procurement databases across Delhi-Mumbai and Bangkok-Jakarta corridors. Primary interviews with facility management directors, system integration contractors, HVAC equipment procurement leads, and building energy auditors combined with secondary validation through bottom-up installation tracking and top-down construction spend analysis.
Historical trendline analysis of building automation system deployment against regulatory deadline cycles established baseline penetration rates across commercial, institutional, and industrial end-use segments. The modeling framework projected technology adoption across product type, end user, deployment architecture, and service delivery dimensions throughout the forecast period. CAGRs derived from segmented growth rate differentials weighted by construction pipeline data and retrofit cycle timing. Industry-specific inputs included MEE disclosure threshold building counts, METI Top Runner equipment replacement schedules, and ASEAN cybersecurity framework divergence indices.
The model holds under stable regulatory enforcement timelines and continued cloud infrastructure investment; deviation in semiconductor supply availability or abrupt cybersecurity standard fragmentation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
United States Smart Windows Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Vinyl Strip Door and Curtains Market
Building Automation Systems
Traction Elevator Market