
 Electrochromic Glass Market | 2026-2036
Electrochromic Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Electrochromic Glass Market Intelligence
China is narrowing its electrochromic glass supply gap through expanded tungsten oxide deposition capacity and government-backed smart-city pilots. Saint-Gobain S.A. leverages vertical integration from float glass to sputtering equipment, sustaining cost advantages across European project pipelines. SageGlass dominates North American commercial retrofit specifications, while View, Inc. competes on software-integrated tinting algorithms for building management systems.
Electrochromic glass consists of multilayer thin-film assemblies, typically incorporating tungsten oxide cathodes and nickel oxide anodes separated by solid polymer electrolytes, that modulate visible and solar transmittance upon applied voltage. The technology primarily reduces building energy consumption by dynamically controlling solar heat gain and glare without mechanical shading. Architectural glass leads installed value due to premium facade contracts, while smart windows represent the fastest-growing product category as residential builders adopt plug-and-play retrofit kits. Ion-intercalation technology anchors current production volumes, though metal oxide variants are gaining share in automotive sunroof applications where switching speed requirements intensify.
REACH compliance governs chemical transparency in European electrochromic coatings, while the EU Green Deal's building performance standards directly mandate dynamic glazing for near-zero-energy structures. The US EPA Energy Star certification program and California Title 24 building codes accelerate electrochromic adoption by crediting automated daylight responsive controls. Stakeholders must monitor electrolyte material substitutions as environmental regulators scrutinize lithium and cobalt supply chains for next-generation devices.
Market Dynamics
The EU Green Deal's tightening energy performance standards for facades is compressing retrofit timelines and forcing commercial building owners toward dynamic glazing solutions that reduce HVAC loads without structural modifications.
Growth Catalysts
- Building Performance Mandates:The EU Green Deal mandates dynamic glazing for near-zero-energy structures, compelling commercial retrofits across Germany, France, and the Netherlands.
- Automotive Sunroof Adoption:Metal oxide variants with faster switching speeds are displacing mechanical shades in premium electric vehicle programs.
- China:Government-backed smart-city pilots in Beijing and Shenzhen are standardizing electrochromic facades in municipal buildings.
Market Restraints
- Tungsten Oxide Supply Concentration:Deposition capacity clusters in Chinese and German chemical processing zones, creating single-source vulnerability for cathode materials.
- Lithium Electrolyte Scrutiny:ECHA is examining lithium supply chains under REACH extended obligations, threatening next-generation device certification timelines.
- Mechanical Shading Cost Gap:Automated roller blinds and external louvers retain a 60-70% installed cost advantage in budget-constrained projects.
Strategic Opportunities
- Residential Retrofit Kits:Plug-and-play smart window systems for single-family homes remain underpenetrated in the US and Australian markets.
- California Title 24 Credits:Automated daylight responsive controls now receive mandatory credit in commercial compliance calculations.
- Building Management System Convergence:Integration with IoT sensor networks and predictive HVAC algorithms creates software-layer value capture.
Industry Challenges
- Thin-Film Deposition Talent Scarcity:Sputtering equipment operators and vacuum process engineers command premium wages in Stuttgart, Dresden, and Shanghai industrial clusters.
- Multi-Certification Overlap:REACH chemical transparency, CE marking for electrical safety, and national building codes require sequential rather than parallel approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrochromic Glass Market |
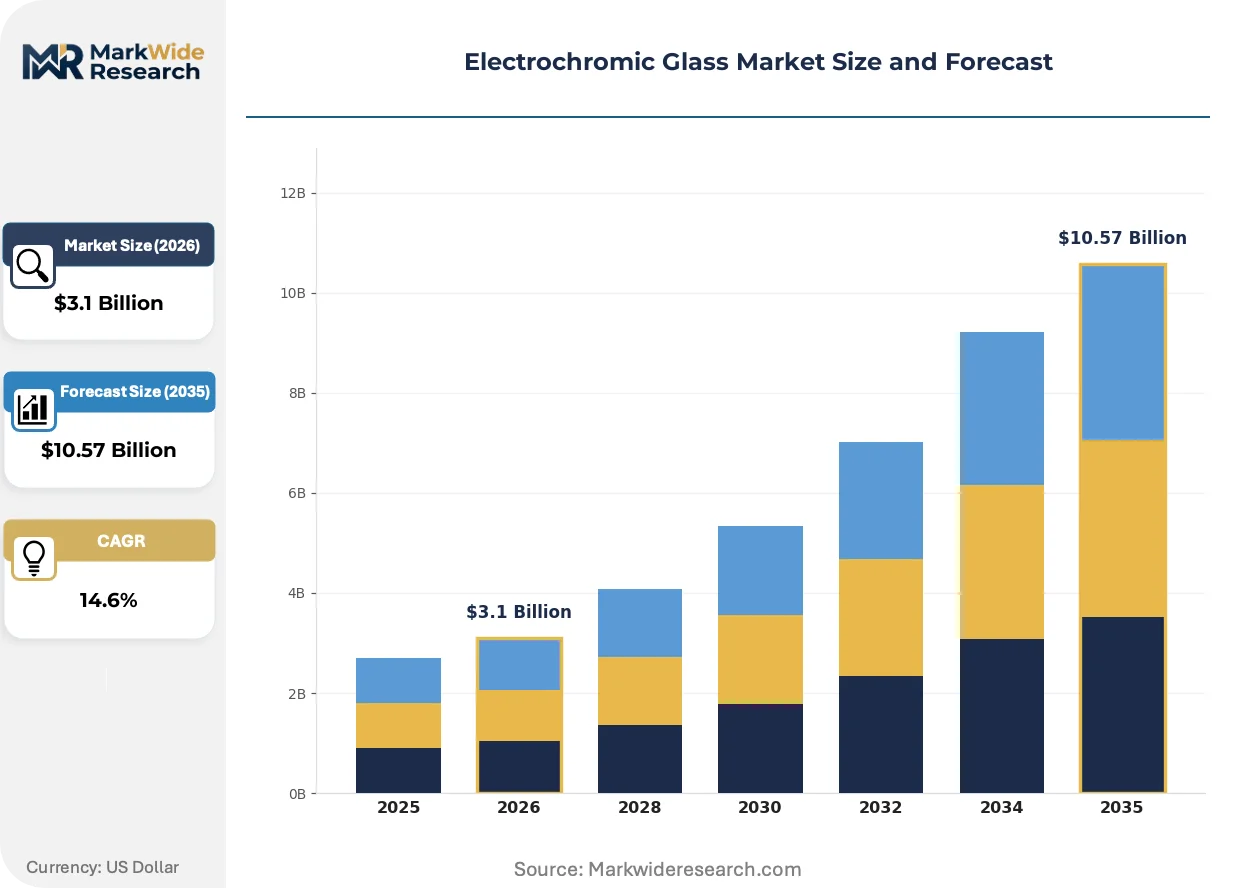
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $10.57 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Windows, Rear-View Mirrors, Displays, Architectural Glass Technology: Ion-Intercalation, Electrochemical, Liquid Crystal, Metal Oxide Application: Residential, Commercial, Automotive, Aerospace End User: Homeowners, Architects, Vehicle Manufacturers, Contractors |
| Companies Covered | Saint-Gobain S.A., Chromogenics AB, SageGlass, PPG Industries, Inc., Guardian Industries, View, Inc., AGC Inc., Nippon Sheet Glass Co., Ltd., Gentex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrochromic Glass Market Strategic Shifts & Innovations
Sputtering equipment manufacturers are compressing deposition cycle times while solid-state electrolyte formulations promise to eliminate liquid-based failure modes in extreme climates.
Perovskite-structured electrochromic layers are virtualizing the traditional tungsten oxide stack by offering comparable optical density modulation at reduced voltage thresholds. Residential developers in Scandinavian markets are piloting these formulations for faster tinting response in low-light winter conditions. The technology is virtualizing the cost structure of ion-intercalation production by enabling roll-to-roll manufacturing on flexible polymer substrates.
REACH extended obligations for chemical transparency in coatings are forcing reformulation of electrolyte precursors across European supply chains. Manufacturers must now submit full substance dossiers for lithium salts and cobalt oxides before market placement. German facade contractors are responding by qualifying alternative alkali-ion chemistries to preempt authorization delays.
Building owners are consolidating glazing procurement under performance-based specifications that guarantee energy savings rather than material properties. General contractors in California and New York now bundle electrochromic installation with measurement-and-verification clauses. This contractual shift is most visible in LEED Platinum-targeted commercial towers where capital allocation favors operational expenditure models.
Electrochromic Glass Market Segmentation
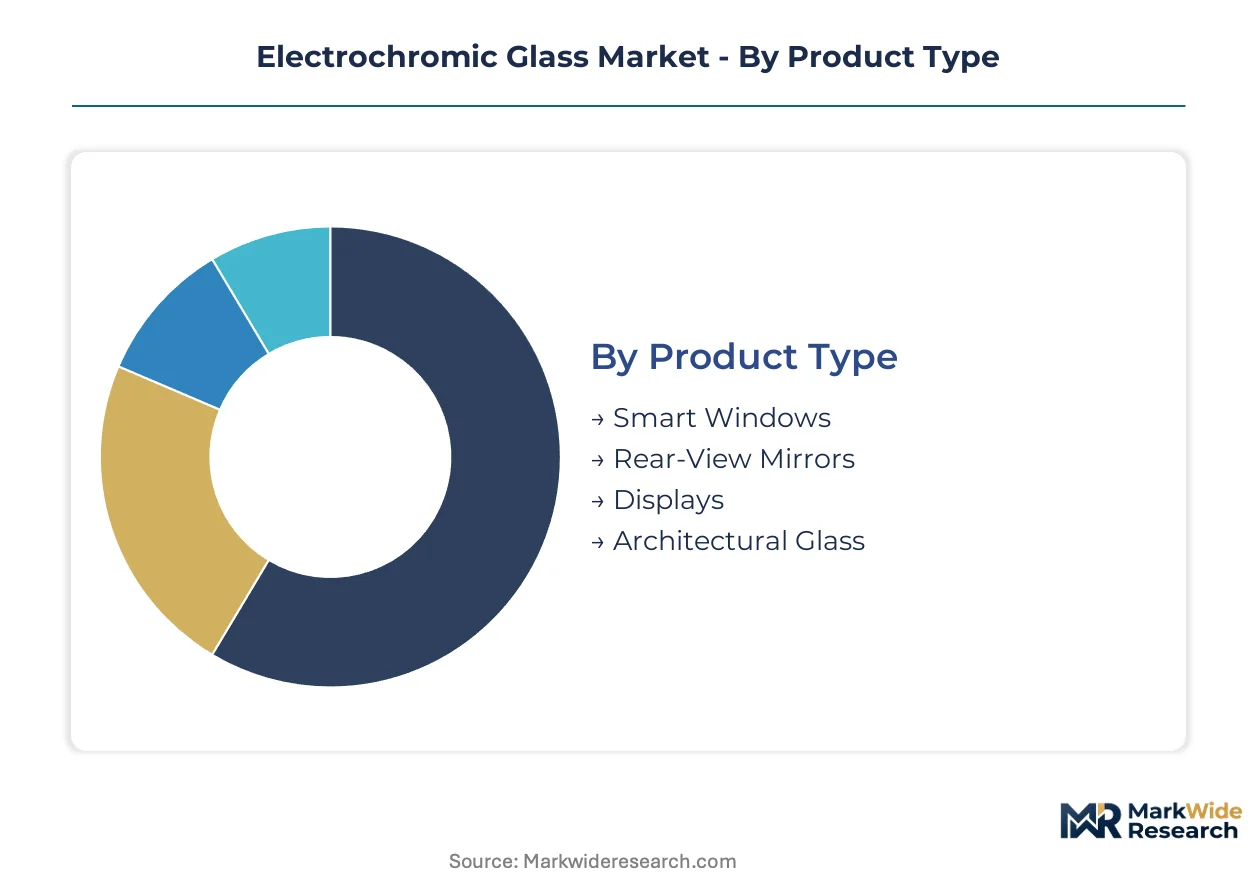
Electrochromic glass segmentation reveals how technology maturity, installation complexity, and buyer sophistication fragment commercial opportunity. Product architecture and deposition chemistry determine margin pools, while application verticals impose divergent certification and performance requirements.
Product Type:
Application maturity and contract value separate these categories, with facade-scale installations commanding fundamentally different procurement cycles than component-integrated formats.
- Architectural Glass:Large-format facade panels incorporate tungsten oxide multilayer stacks with solid polymer electrolytes for commercial building envelopes. Premium contracts in Germany and California concentrate here, driven by EU Green Deal energy performance mandates and Title 24 daylight credit requirements.
- Smart Windows:Self-contained retrofit units with plug-and-play connectivity target residential replacement cycles. Scandinavian builders are piloting perovskite-structured layers for faster winter response, while Australian single-family markets remain underpenetrated.
- Rear-View Mirrors:Automotive-integrated dimming modules with nickel oxide anode configurations serve premium vehicle programs. Faster switching specifications from German and Japanese OEMs are displacing mechanical alternatives.
- Displays:Small-area electrochromic elements for information panels and signage applications. Shenzhen smart-city pilots are standardizing municipal display networks with dynamic tinting.
Architectural Glass holds installed capacity. Smart Windows is rotating up the share rankings.
Technology:
Deposition chemistry and ion mobility characteristics create distinct performance envelopes that match specific switching speed and durability requirements.
- Ion-Intercalation:Tungsten oxide cathodes paired with lithium or proton electrolytes anchor current production volumes through proven vacuum sputtering processes. Stuttgart and Shanghai industrial clusters concentrate thin-film deposition talent for this mature stack architecture.
- Metal Oxide:Alternative cathode formulations including nickel oxide and vanadium pentoxide enable faster switching for automotive sunroof applications. Chinese tungsten oxide supply concentration is accelerating qualification of these variants in European supply chains.
- Liquid Crystal:Electrically modulated birefringence without ion migration offers intermediate switching speeds for interior partition applications. CE marking and electrical safety compliance pathways differ from solid-state electrochromic categories.
- Electrochemical:Solution-phase redox systems with distinct failure modes from thin-film architectures. REACH extended obligations for chemical transparency are forcing reformulation of electrolyte precursors before market placement.
Ion-Intercalation dominates current output. Metal Oxide is climbing the fastest as automotive specifications intensify.
Application:
Building codes and procurement authority structures shape how electrochromic specifications penetrate each vertical, with commercial real estate presenting fundamentally different buyer dynamics than residential or mobility segments.
- Commercial:Office tower retrofits and new construction in Germany, France, and the Netherlands integrate dynamic glazing for HVAC load reduction. Performance-based specifications now guarantee energy savings rather than material properties, with measurement-and-verification clauses bundled into general contractor agreements.
- Automotive:Premium electric vehicle sunroof programs specify metal oxide variants with sub-second switching. German KBA type approval and Japanese METI safety standards govern deployment timelines.
- Residential:Single-family retrofits and new construction present fragmented demand with price-sensitive procurement. California Title 24 credits for automated daylight controls are accelerating adoption in compliance-driven markets.
- Aerospace:Cabin window dimming for commercial aviation with extreme reliability requirements and extended certification cycles. FAA airworthiness standards and EASA CS-25 compliance impose sequential rather than parallel approval pathways.
Commercial commands contract value concentration. Automotive is gaining share fastest on electric vehicle platform expansion.
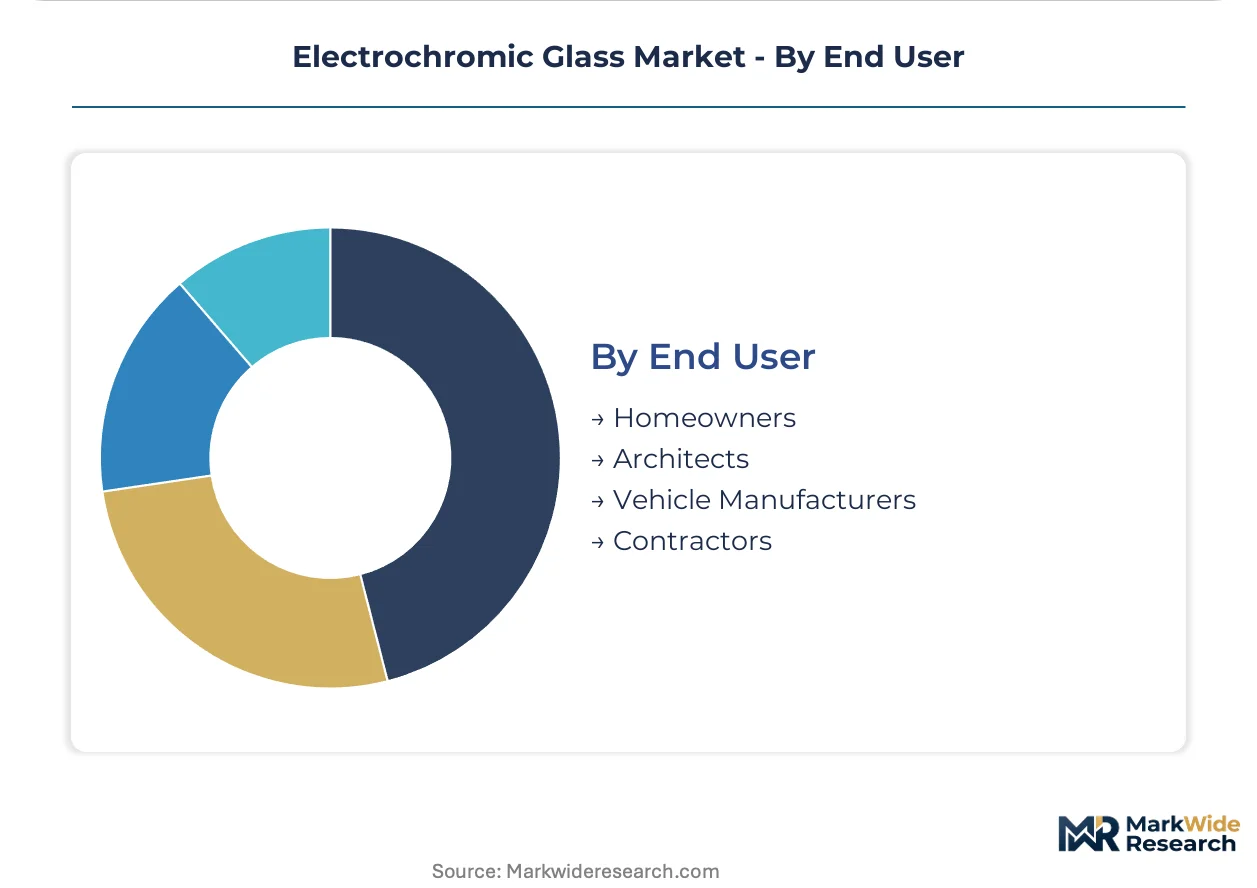
End User:
Technical sophistication and specification authority determine how electrochromic value propositions translate into purchase decisions across these buyer categories.
- Architects:Design-phase specification authority for facade systems in LEED Platinum-targeted towers. EU Green Deal building performance standards directly inform glazing selection criteria for near-zero-energy structures.
- Vehicle Manufacturers:Tier-1 supplier integration requirements for sunroof and mirror programs. Sputtering equipment operators command premium wages as OEMs consolidate qualified deposition capacity.
- Contractors:Installation and procurement consolidation under performance-based contracts with energy savings guarantees. California and New York general contractors now bundle electrochromic deployment with operational expenditure models.
- Homeowners:Fragmented retail demand for plug-and-play smart window retrofit kits. Australian and US single-family markets show underpenetrated adoption despite software-integrated tinting algorithm availability.
Architects control premium specification. Vehicle Manufacturers are rotating up the share rankings on automotive program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten oxide deposition capacity clusters in Chinese and German chemical processing zones, concentrating cathode material supply. Commercial building retrofits concentrate contract value in Germany, California, and the Netherlands as energy performance mandates tighten.
United States
California Title 24 building codes mandate automated daylight responsive controls in commercial compliance calculations. The EPA Energy Star certification program credits dynamic glazing for HVAC load reduction. Los Angeles and San Francisco office tower retrofits bundle electrochromic installation with measurement-and-verification clauses under performance-based specifications.
Germany
The EU Green Deal's near-zero-energy building standards compel facade retrofits across Stuttgart and Dresden industrial clusters. ECHA REACH extended obligations scrutinize lithium electrolyte supply chains for next-generation device certification. Bavarian facade contractors qualify alternative alkali-ion chemistries to preempt authorization delays.
China
Government-backed smart-city pilots in Beijing and Shenzhen standardize electrochromic facades in municipal buildings. MIIT industrial policy supports expanded tungsten oxide deposition capacity to narrow domestic supply gaps. Shanghai thin-film deposition talent commands premium wages as vacuum process engineers concentrate in Yangtze River Delta manufacturing zones.
Netherlands
EU Green Deal energy performance standards for facades compress retrofit timelines for Amsterdam and Rotterdam commercial portfolios. CE marking requirements for electrical safety govern dynamic glazing approval pathways. Eindhoven-region building contractors consolidate procurement under operational expenditure models with energy savings guarantees.
Japan
METI safety standards govern deployment timelines for premium electric vehicle sunroof programs specifying faster-switching metal oxide variants. Japanese OEMs consolidate qualified sputtering deposition capacity for automotive-integrated dimming modules. Nagoya industrial clusters concentrate nickel oxide anode qualification for rear-view mirror applications.
Electrochromic Glass Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in thin-film deposition and electrolyte formulation. The vendor base separates into consolidated glass majors with captive coating capacity, independent smart window assemblers, and automotive-focused dimming module suppliers. Three archetypes dominate: vertically integrated float-to-coating operators, software-layer platform vendors, and tier-1 automotive electronics integrators. Competitive moves concentrate on strategic partnerships for building management system convergence and geographic expansion through qualified installer networks.
Within the vertically integrated tier, Saint-Gobain S.A. exemplifies upstream control from float glass through sputtering equipment. Among North American platform specialists, SageGlass and View, Inc. occupy positions on the commercial retrofit and software-integrated algorithm vectors respectively. These three anchors represent distinct strategic postures: European manufacturing depth, established specification authority, and building automation convergence.
| Leading Market Players |
|---|
| Saint-Gobain S.A. |
| Chromogenics AB |
| SageGlass |
| PPG Industries, Inc. |
| Guardian Industries |
| View, Inc. |
| AGC Inc. |
| Nippon Sheet Glass Co., Ltd. |
| Gentex Corporation |
| Others |
Cost & Logistics Intelligence
Stuttgart and Dresden industrial clusters concentrate thin-film deposition talent, anchoring cathode material supply that feeds downstream pricing power to facade contractors and automotive integrators. REACH extended obligations for lithium electrolyte transparency compress certification timelines, forcing German manufacturers to qualify alternative alkali-ion chemistries at elevated qualification costs that transmit into project premiums.
Pricing Analysis
EU Green Deal building performance mandates dictate the pricing tier structure across electrochromic glazing markets. Three-tier pricing structure across premium facade contracts, standard commercial retrofits, and economy residential kits separates buyers by certification complexity and project scale. Cost compression in economy residential tiers is intensifying because mechanical shading alternatives retain installed cost advantages. Contractors represent the most price-sensitive buyer archetype, while architects specifying LEED Platinum towers show minimal price elasticity.
Supply Chain Analysis
Sputtering equipment operators in Yangtze River Delta manufacturing zones and Stuttgart industrial parks hold captive deposition capacity for tungsten oxide multilayer stacks. Raw material flows draw from Chinese tungsten oxide processing zones, German nickel oxide anode suppliers, and solid polymer electrolyte formulators in Japan and South Korea. Single-source vulnerability concentrates in Chinese cathode material supply, threatening European project timelines. Distribution runs through qualified installer networks bundling performance guarantees with hardware deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochromic glass demand tracks commercial construction cycles, with EU Green Deal retrofit mandates and California Title 24 compliance deadlines providing cyclical uplift through mandated replacement windows.
For Market Incumbents: Pre-empt lithium electrolyte supply chain disruptions by qualifying sodium-ion and proton-conducting alternatives before ECHA authorization delays cascade through certification pipelines. Consolidate sputtering deposition capacity in Stuttgart and Shanghai industrial clusters to capture premium wages for vacuum process engineers. Backward integration into tungsten oxide precursor supply hedges against Chinese supply concentration risks. For New Entrants and Emerging Players: Australian single-family residential retrofits present underpenetrated demand with software-integrated plug-and-play kits. Scandinavian perovskite-structured layer pilots demonstrate faster winter tinting response that commands specification interest. California Title 24 credit arbitrage offers immediate go-to-market traction through compliance-driven contractor procurement. For Investors and Strategic Acquirers: Long-term, this sits as a building-automation convergence play because electrochromic glazing integrates with IoT sensor networks and predictive HVAC algorithms that capture software-layer value. Acquisition targets center on independent smart window assemblers with qualified installer networks in Germany and California. Monitor ECHA substance dossier approval velocities for lithium salts as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Oxide Supply | Captive cathode material supply hedges against Chinese processing zone concentration. |
| Perovskite-Structured Layer Qualification | Faster switching formulations penetrate Scandinavian winter response specifications. |
| Building Management System Convergence | Software-layer integration with View, Inc. tinting algorithms creates recurring revenue. |
| Alternative Alkali-Ion Chemistry Investment | Sodium-ion electrolyte R&D preempts REACH authorization delays for lithium precursors. |
| Residential Retrofit Kit Distribution | Plug-and-play smart window systems address Australian underpenetration. |
Research Approach
A standing panel of facade contractors, vacuum process engineers, building automation integrators, and automotive Tier-1 procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA substance dossier filings, EU Green Deal implementation progress reports, California Title 24 compliance databases, and SEC 10-K disclosures from glass majors. Bottom-up project pipeline aggregation triangulated against top-down energy performance mandate impact modeling.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchors. Segmentation dimensions spanned product architecture, deposition chemistry, application vertical, and regional regulatory cluster. CAGRs derived from installed base turnover rates and replacement cycle compression under EU near-zero-energy building deadlines. Forecast inputs incorporated tungsten oxide deposition capacity expansion timelines and smart-city pilot standardization velocities.
Practitioners should monitor ECHA extended obligation enforcement patterns and MIIT industrial policy shifts for early signals of supply chain reconfiguration. Forecasts embed assumptions around REACH chemical transparency timelines and Title 24 credit permanence that material changes could revise. Quarterly review of substance dossier approval velocities and municipal smart-city tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Global Door Closers Market
Building Automation Systems
Energy Efficient Elevators Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Signage Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Building Information Management System Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Building Analytics Market