
 Automatic Ducting Machine Market | 2026-2036
Automatic Ducting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Ducting Machine Market Outlook
Modular system bundling is repositioning how mid-sized HVAC contractors evaluate capital outlays, shifting preference from standalone units to integrated lines with coil handling and seam-closing attachments. Trumpf Inc. leverages its laser-cutting heritage to anchor premium positioning in CNC-configured ducting systems. Spiro International SA sustains geographic dominance across European markets through specialized spiral-duct machinery. Lockformer Company competes on manufacturing scale in North America with broad portable-to-fixed product coverage.
Automatic ducting machines are electromechanical or hydraulically actuated fabrication systems that form, notch, fold, and seam sheet metal into rectangular, round, or oval duct sections with tolerances typically within 0.5 mm. These systems serve the HVAC supply chain by converting flat coil stock into finished air-distribution components at throughputs exceeding manual methods by an order of magnitude. CNC machines capture the highest margin pools as programmable back-gauging and parametric nesting reduce material scrap rates for custom commercial jobs. Electric systems are displacing hydraulic alternatives in regions with aggressive carbon-reduction frameworks due to cleaner operation and lower energy intensity. Portable machines remain the volume backbone for on-site construction firms requiring mobility across multiple job locations.
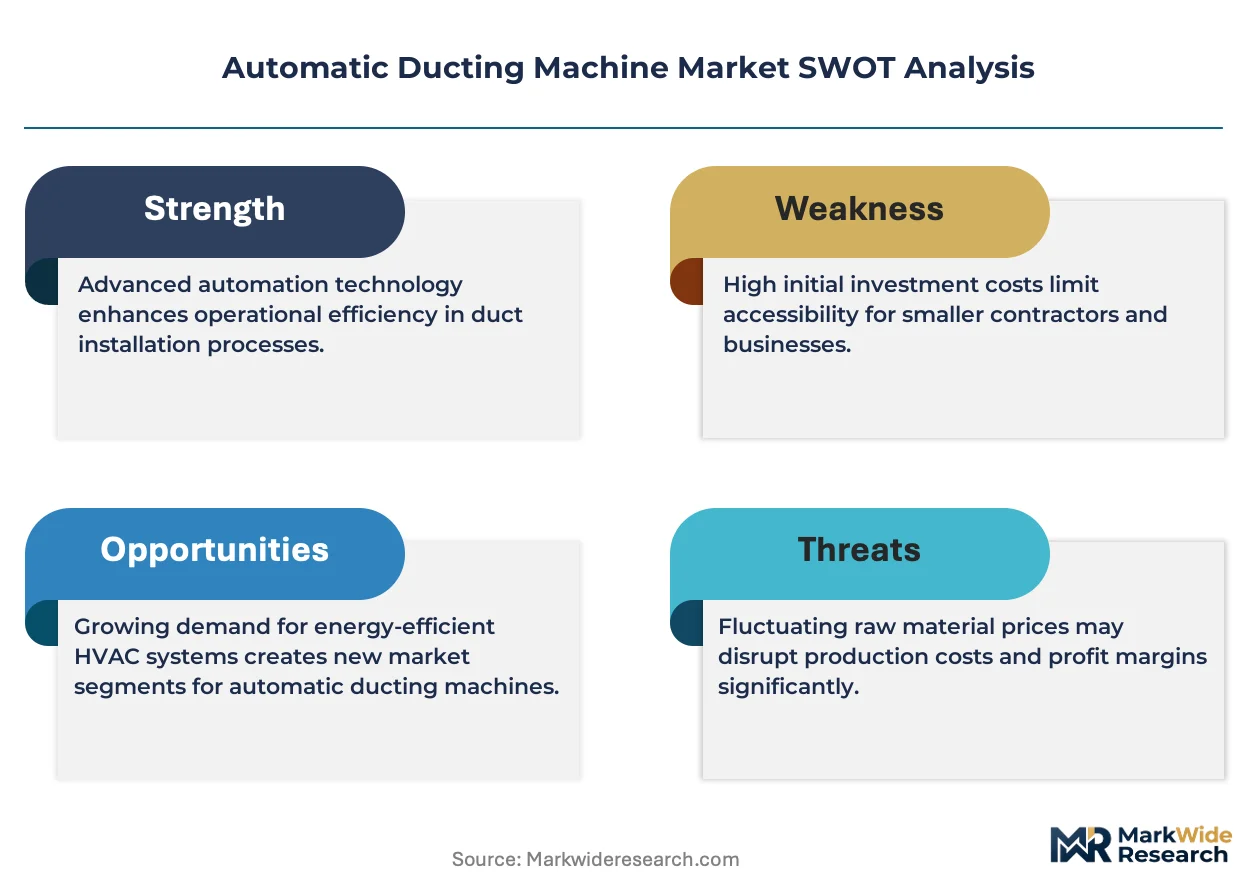
The US EPA's energy-efficiency standards for commercial buildings and the EU F-Gas Regulation jointly elevate demand for airtight duct fabrication, compelling contractors to replace legacy equipment with machines capable of producing lower-leakage joints. China's SAMR enforces GB standards on industrial ventilation equipment, creating compliance-driven replacement cycles in manufacturing hubs. Stakeholders must monitor how evolving carbon-border adjustment mechanisms reshape equipment sourcing decisions between domestic fabrication and imported systems.
Market Dynamics
Modular system architecture is compressing capital deployment cycles for HVAC contractors, forcing equipment manufacturers to bundle coil handling and seam-closing attachments into integrated lines rather than standalone units. This shift is reshaping competitive positioning between premium CNC-configured suppliers and volume-oriented portable equipment producers.
Growth Catalysts
- EU F-Gas Regulation:Airtightness mandates for commercial ventilation systems are compelling contractors across Germany, France, and Italy to replace legacy fabrication equipment with machines capable of producing sub-1% leakage duct joints.
- China's dual carbon goals:SAMR enforcement of GB standards on industrial ventilation equipment is triggering compliance-driven replacement cycles in manufacturing hubs around Shanghai and Guangdong.
- Spiral-duct specialization:Rising specification of round ductwork in data center cooling and pharmaceutical cleanroom applications is pulling demand toward dedicated spiral-forming machinery with parametric programming capabilities.
Market Restraints
- Steel coil price volatility:Input cost fluctuations for galvanized sheet metal directly compress margins for job-shop fabricators operating on fixed-price commercial contracts.
- Component supply concentration:Precision servo motors and linear motion systems for CNC back-gauging remain concentrated among Japanese and German component suppliers, exposing equipment builders to extended lead times.
- Hydraulic system obsolescence risk:Electric actuation is displacing hydraulic alternatives in regions with aggressive carbon-reduction frameworks, stranding capital in legacy equipment with limited resale value.
Strategic Opportunities
- India's PLI scheme for HVAC components:Domestic manufacturing incentives are creating localized demand for mid-tier automatic ducting equipment serving the country's expanding commercial real estate sector.
- Convergence of laser cutting and forming:Integration of fiber laser blanking with inline folding and seaming is collapsing process steps for custom commercial jobs, enabling same-day turnaround on complex geometries.
- Rental and leasing channels:Equipment-as-a-service models are emerging for portable ducting machines, reducing capital barriers for smaller mechanical contractors in fragmented construction markets.
Industry Challenges
- CNC programming talent scarcity:Parametric nesting and back-gauge calibration require skilled operators that sheet-metal job shops struggle to recruit and retain in competitive labor markets.
- CE marking compliance timelines:Machinery Directive certification for European market entry demands extensive documentation and third-party assessment, extending product launch cycles by 8-14 months.
- Legacy system integration friction:Retrofitting automated ducting lines into existing shop layouts with constrained floor space and legacy material handling infrastructure requires costly custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Ducting Machine Market |
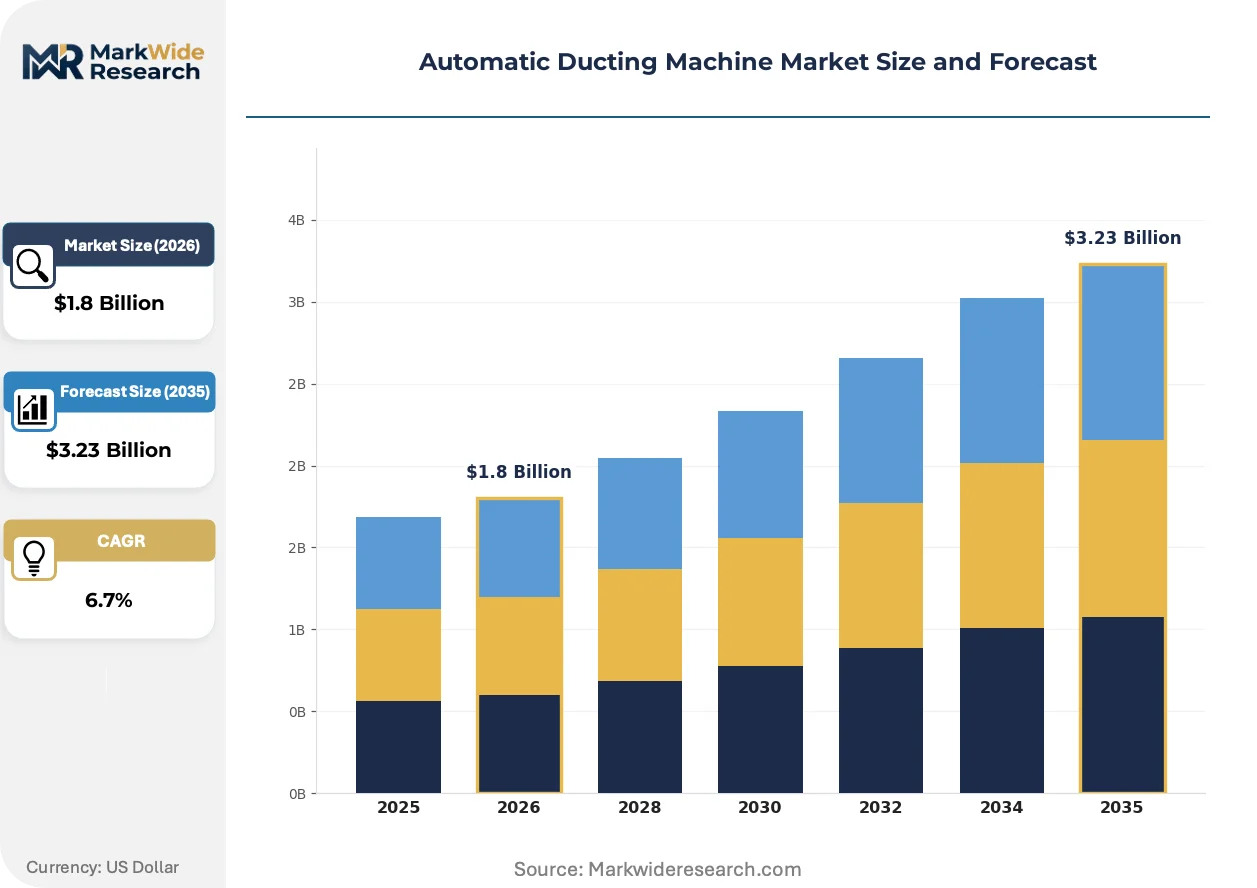
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Machines, Fixed Machines, High-Speed Machines, CNC Machines Technology: Hydraulic Systems, Pneumatic Systems, Electric Systems, Hybrid Systems End User: Manufacturing Plants, HVAC Contractors, Construction Firms, Automotive Industry Application: Residential Ventilation, Commercial Ventilation, Industrial Ventilation, HVAC Installations |
| Companies Covered | Trumpf Inc., Spiro International SA, Lockformer Company, Fasti Ducting Machines, Mestek Machinery, BLKMA Machinery, Ductformer Inc., Prima Power, RAS Reinhardt Maschinenbau GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Ducting Machine Market Strategic Shifts
Equipment architecture is fragmenting into configurable subsystems that contractors assemble based on job-type mix rather than purchasing monolithic production lines. This modularity is compressing capital requirements and expanding addressable demand among mid-tier mechanical contractors.
Electric servo-actuated folding and seaming systems are modularizing machine architecture across European and North American markets. Mid-sized HVAC contractors in Germany's industrial corridor are adopting these configurable platforms to handle mixed rectangular and round duct workloads without dedicated lines for each geometry. The technology is modularizing supplier relationships, enabling fabricators to source attachments from specialized vendors rather than single-source turnkey providers.
The EU F-Gas Regulation is tightening leakage-rate specifications for commercial ventilation systems installed after 2027. Equipment manufacturers are responding with enhanced seam-closing technologies and inline quality verification systems that certify joint integrity during production. German sheet-metal shops serving pharmaceutical and data center end-uses are most affected, accelerating replacement of mechanical lockforming equipment with servo-controlled seaming systems.
Service unbundling is separating equipment hardware from software subscriptions and predictive maintenance contracts. North American distributors are repositioning around remote diagnostics and consumable replenishment rather than transactional sales, capturing recurring revenue from installed machine fleets. This shift is most visible among HVAC contractors operating across multiple states, where centralized fleet management reduces downtime and spare parts inventory carrying costs.
Automatic Ducting Machine Market Segmentation
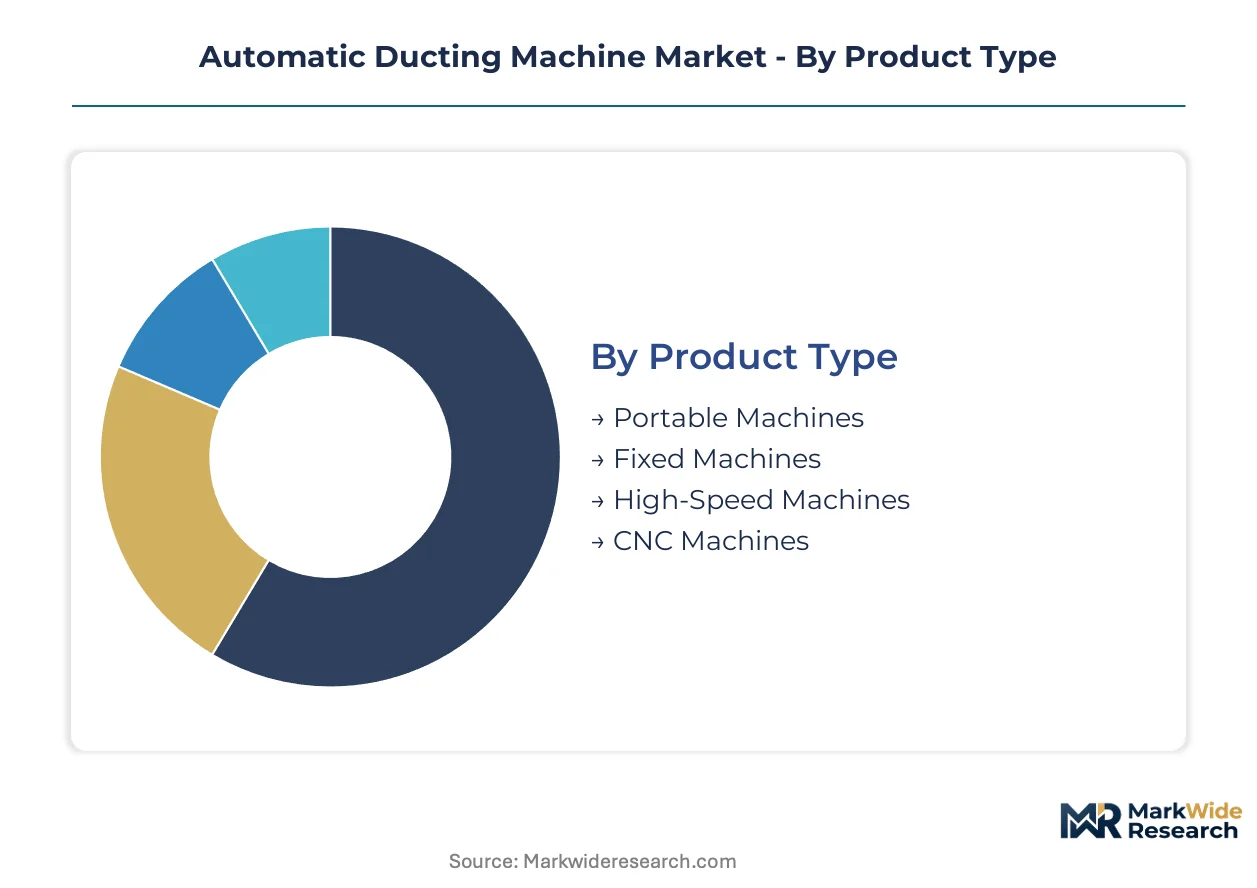
Automatic ducting machines serve heterogeneous buyer profiles with divergent capital constraints, throughput requirements, and mobility needs. Segmentation reveals how equipment specifications align with contractor scale, project type, and regional regulatory pressure.
Product Type:
Capital intensity and job mobility dictate equipment selection across contractor tiers.
- CNC Machines:Programmable back-gauging and parametric nesting reduce material scrap rates below 3% for custom commercial fabrication. Demand concentrates among German sheet-metal shops serving pharmaceutical cleanrooms and data center cooling projects where GB standards and EU F-Gas Regulation mandate sub-1% leakage joints.
- Portable Machines:Electromechanical systems weighing under 800 kg enable on-site fabrication across multiple job locations per week. HVAC contractors in fragmented US construction markets deploy these units for residential retrofit programs where transportability outweighs throughput.
- Fixed Machines:Permanent shop installations with integrated coil handling and inline seaming serve high-volume production environments.
- High-Speed Machines:Dedicated lines for standardized duct geometries achieve throughputs exceeding 50 meters per minute in repetitive commercial applications.
Volume sits with portable units; growth tilts toward CNC-configured systems.
Technology:
Regional carbon frameworks and energy pricing reshape actuation preferences.
- Electric Systems:Servo-actuated folding and seaming deliver precision within 0.5 mm tolerance while eliminating hydraulic fluid maintenance. German and French contractors favor these systems under EU Green Deal pressure, displacing legacy hydraulic units with limited resale value.
- Hydraulic Systems:High-force actuation remains cost-advantaged for thick-gauge industrial ductwork above 1.2 mm sheet thickness.
- Pneumatic Systems:Compressed-air mechanisms dominate entry-level portable equipment for developing market contractors.
- Hybrid Systems:Combined electric-pneumatic architectures balance precision and capital cost in mid-tier shop environments.
Electric configurations are gaining share fastest in regulated European markets; hydraulic retains position in heavy-gauge industrial segments.
End User:
Procurement sophistication varies sharply across buyer categories.
- HVAC Contractors:Mixed residential-commercial portfolios drive demand for modular systems with quick changeover between rectangular and round duct geometries. German mid-sized contractors in the industrial corridor source configurable platforms to serve both domestic retrofit programs and export markets.
- Manufacturing Plants:Captive fabrication facilities for automotive and electronics assembly require dedicated high-throughput lines with inline quality verification.
- Construction Firms:General contractors with mechanical divisions prioritize portable equipment for multi-site deployment.
- Automotive Industry:Paint shop ventilation and battery facility climate control specify precision spiral-duct systems with pharmaceutical-grade cleanliness.
Equipment-as-a-service models are penetrating HVAC contractor fleets; manufacturing plants favor outright purchase with predictive maintenance contracts.
Application:
Leakage-rate specifications and energy-efficiency mandates segment demand by building type.
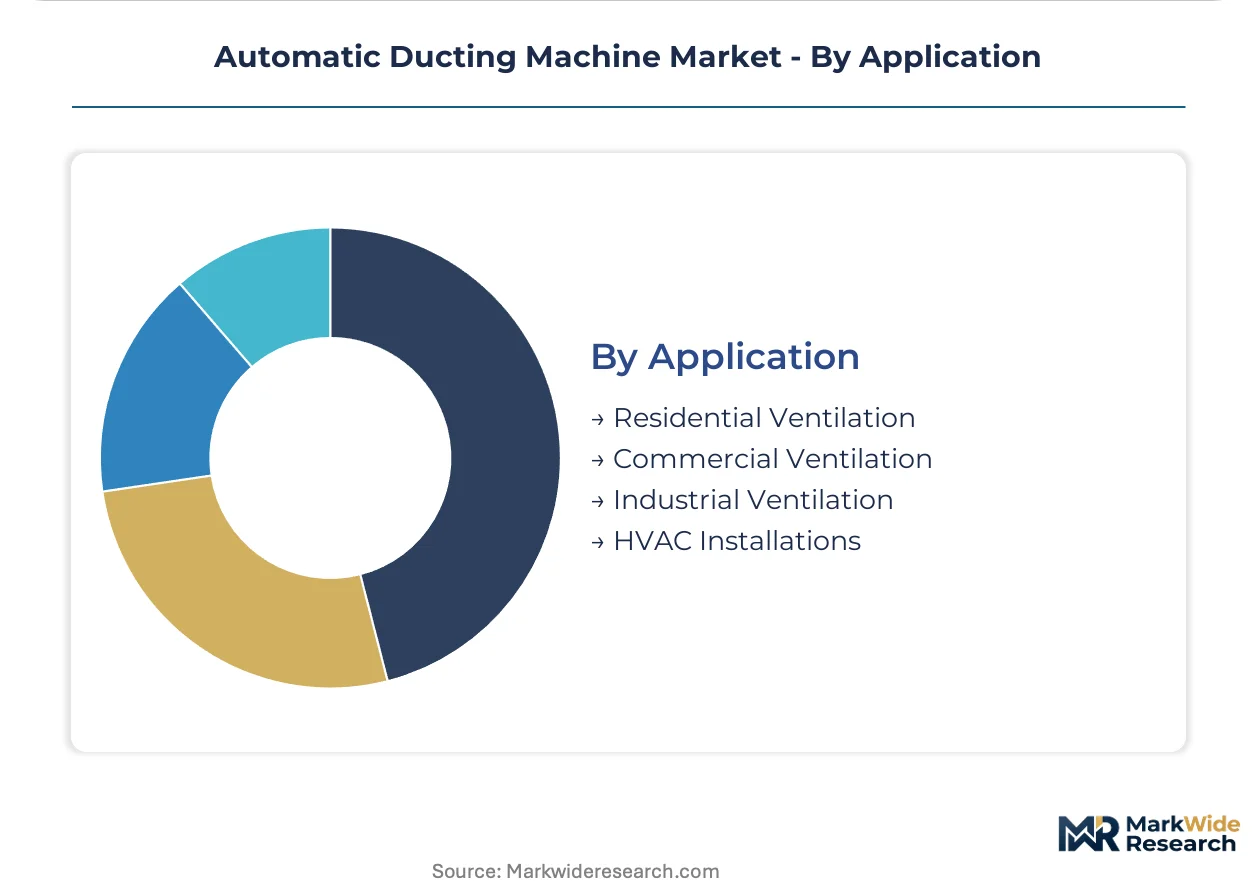
- Commercial Ventilation:Office towers, retail complexes, and healthcare facilities specify airtight ductwork under EPA energy-efficiency standards and EU F-Gas Regulation. German fabricators serving this segment invest in servo-controlled seaming systems with inline joint integrity certification.
- Industrial Ventilation:Heavy manufacturing and chemical processing require corrosion-resistant materials and explosion-rated fabrication environments.
- Residential Ventilation:Single-family and multi-family construction tolerates higher leakage rates, sustaining demand for mechanical lockforming equipment at lower price points.
- HVAC Installations:Retrofit replacement cycles in aging US commercial building stock drive demand for custom-fabricated replacement ductwork.
Commercial applications command premium pricing; industrial ventilation shows steepest expansion trajectory in China's manufacturing hubs under SAMR enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor concentrates European ducting machine demand through clustered sheet-metal fabrication zones serving cross-border HVAC retrofit programs.
United States
EPA energy-efficiency standards for commercial buildings drive equipment replacement cycles among mechanical contractors. The Inflation Reduction Act subsidizes building electrification retrofits in legacy office stock. Fabrication demand clusters in Chicago's industrial belt and Texas Gulf Coast petrochemical corridors.
Germany
EU F-Gas Regulation mandates sub-1% leakage joints for ventilation systems installed after 2027. SAMR-aligned GB standards influence export-oriented machinery specifications. Stuttgart and Munich industrial zones anchor precision fabrication capacity for pharmaceutical cleanroom and data center cooling projects.
China
Dual carbon goals accelerate compliance-driven replacement in Shanghai and Guangdong manufacturing hubs. MIIT enforcement of industrial ventilation standards triggers fleet modernization. Yangtze River Delta fabricators serve both domestic HVAC expansion and Belt and Road export markets.
India
PLI scheme incentives for HVAC components create localized demand for mid-tier automatic ducting equipment. BIS standards on commercial building ventilation tighten fabrication tolerances. Maharashtra and Gujarat commercial real estate corridors drive contractor capital expenditure on modular forming systems.
Japan
METI carbon-neutral building roadmaps elevate airtight duct specifications for post-2025 construction. JIS standards on industrial ventilation equipment mandate precision joint integrity. Osaka-Kobe manufacturing belt fabricators supply automotive paint shop and battery facility climate control systems.
Automatic Ducting Machine Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. Equipment manufacturers fragment across three strategic archetypes: premium CNC-configured system integrators, volume-oriented portable equipment producers, and specialized spiral-duct machinery builders. Consolidation pressure intensifies as modular system bundling reshapes procurement patterns. Strategic moves center on geographic expansion into India's PLI-subsidized manufacturing zones and technology licensing partnerships for electric servo-actuated architectures.
Among German precision machinery builders, RAS Reinhardt Maschinenbau GmbH exemplifies the premium CNC-configured archetype, while Trumpf Inc. anchors diversified laser-cutting heritage extending into ducting system integration. Spiro International SA occupies the specialized spiral-duct machinery tier with concentrated European market presence. These three represent distinct competitive positioning vectors: programmable precision, diversified technology platforms, and geometric specialization respectively.
| Leading Market Players |
|---|
| Trumpf Inc. |
| Spiro International SA |
| Lockformer Company |
| Fasti Ducting Machines |
| Mestek Machinery |
| BLKMA Machinery |
| Ductformer Inc. |
| Prima Power |
| RAS Reinhardt Maschinenbau GmbH |
| Others |
Value Chain & Pricing Dynamics
German mid-sized HVAC contractors concentrated in the Ruhr industrial corridor anchor pricing power for CNC-configured ducting systems, with procurement patterns favoring bundled equipment-as-a-service contracts over transactional unit sales. This buyer concentration enables premium positioning for integrated lines while compressing margins for standalone portable equipment producers serving fragmented construction markets.
Pricing Analysis
Short lead-time premiums of 15-25% apply to precision servo-actuated systems sourced from Japanese and German component suppliers, while spot inventory of hydraulic units trades at discounts amid obsolescence risk. Three-tier pricing structure across premium CNC, standard fixed-line, and economy portable levels differentiates on certification grade and after-sales bundling. Cost compression in mid-tier electric systems is intensifying because steel coil price volatility directly transfers to job-shop fabricators on fixed-price commercial contracts. Residential retrofit contractors exhibit highest price sensitivity; pharmaceutical cleanroom fabricators show lowest.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Chicago, and Shanghai anchor hub-and-spoke patterns for spare parts and consumables, with field service technicians deployed from these nodes to minimize machine downtime. Manufacturing concentration rests on Germany, China, and the United States for complete system assembly, while precision servo motors and linear motion systems draw from Japan and Germany. Single-source vulnerability around CNC back-gauging components exposes equipment builders to extended lead times. Distribution runs through authorized dealer networks with captive service contracts in developed markets and direct OEM relationships in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around modular system integrators capable of bundling hardware, software, and predictive maintenance, with capital intensity and CNC programming talent scarcity forcing weaker pure-play fabricators toward exit or acquisition.
For Market Incumbents: Deepen backward integration into precision servo motor supply chains to insulate margin structures from Japanese component lead-time volatility. Acquire distressed portable equipment producers in North American fragmented construction markets to consolidate channel control and cross-sell service contracts. Electric actuation R&D investment represents the critical defensive lever against hydraulic system obsolescence risk under EU Green Deal pressure. For New Entrants and Emerging Players: Servo-actuated folding attachments for mixed rectangular-round duct geometries offer the most penetrable technology-first wedge into Germany's industrial corridor mid-tier contractor segment. Target India's PLI-subsidized HVAC component manufacturing zones with mid-tier automatic ducting equipment localized for BIS compliance. Equipment-as-a-service subscription models reduce capital barriers for smaller mechanical contractors and establish recurring revenue foundations. For Investors and Strategic Acquirers: Distressed-cycle entries favor CNC-configured system integrators with established pharmaceutical cleanroom and data center cooling project portfolios in German-speaking Europe. Long-term viability across the analysis window hinges on software subscription attach rates and predictive maintenance contract penetration. Monitor CE marking compliance timeline extensions as the inflection signal for European market entry difficulty and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Components | Mitigates Japanese supplier concentration risk and compresses lead-time premiums for CNC systems. |
| Equipment-as-a-Service Launch | Converts transactional portable machine sales into recurring revenue from HVAC contractor fleets. |
| Pharmaceutical Cleanroom Certification | Unlocks premium positioning under EU F-Gas Regulation sub-1% leakage mandates. |
| India PLI Zone Manufacturing | Captures localized demand from Maharashtra and Gujarat commercial real estate expansion. |
| Laser-Forming Convergence R&D | Collapses process steps for same-day turnaround on complex custom commercial duct geometries. |
Study Parameters
Document review covered equipment manufacturer technical specifications, regulatory filings with EPA and SAMR, and trade flow data from customs authorities, complemented by interviews with HVAC contractor operations managers, sheet-metal shop engineers, OEM procurement leads, and aftermarket service heads. Secondary validation drew from SEC 10-K disclosures, EU Machinery Directive certification databases, and industry association production statistics. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, and end-user segments.
Historical shipment data cross-referenced against expert panel input on replacement cycle timing and regulatory compliance deadlines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include machine configuration tier, actuation technology, mobility class, end-user procurement sophistication, and regional regulatory stringency. CAGRs derived from elasticity-adjusted demand curves incorporating steel coil price volatility and carbon-reduction policy trajectories. Industry-specific inputs encompassed SAMR enforcement intensity and EU F-Gas Regulation implementation phasing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acute steel price spikes or extended Japanese component supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Commercial Air Conditioner (AC) Market