
 Artificial Bowling Surface Market | 2026-2036
Artificial Bowling Surface Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Bowling Surface Market Analysis
Premium-density nylon specifications is unwinding the competitive landscape for artificial bowling surfaces. TigerTurf leverages its Australian manufacturing base to dominate synthetic sports surface exports across Asia-Pacific. Playrite anchors the UK market through specialized crown green and flat green surface engineering. FieldTurf competes by extending its broader synthetic turf expertise into niche bowling lane applications.
Artificial bowling surfaces comprise engineered synthetic fiber systems, typically tufted or woven onto woven polypropylene backings with specialized infill layers, designed to replicate the roll characteristics and friction coefficients of natural grass or traditional wooden lanes. These surfaces serve competitive bowling disciplines by delivering consistent ball trajectory, reduced maintenance downtime, and year-round playability regardless of climate conditions. Polypropylene dominates material type selection due to its superior UV stability and lower moisture absorption versus nylon alternatives, while professional tournament applications command the highest performance tolerances and longest replacement cycles. Installation methods increasingly favor glue-down systems in permanent venues where subfloor preparation justifies the labor investment, whereas interlocking panels gain traction in temporary training facilities requiring rapid redeployment.
The International Bowling Federation sets equipment and playing surface standards that manufacturers must satisfy for championship eligibility, while national sports councils in England and Australia administer facility certification programs that directly influence procurement specifications. REACH compliance within the European Union restricts certain chemical additives in synthetic fiber production, reshaping formulation strategies for suppliers serving continental clubs. Stakeholders must monitor evolving water-use regulations and synthetic microfiber discharge rules that threaten to impose new compliance burdens on surface replacement and end-of-life disposal decisions.
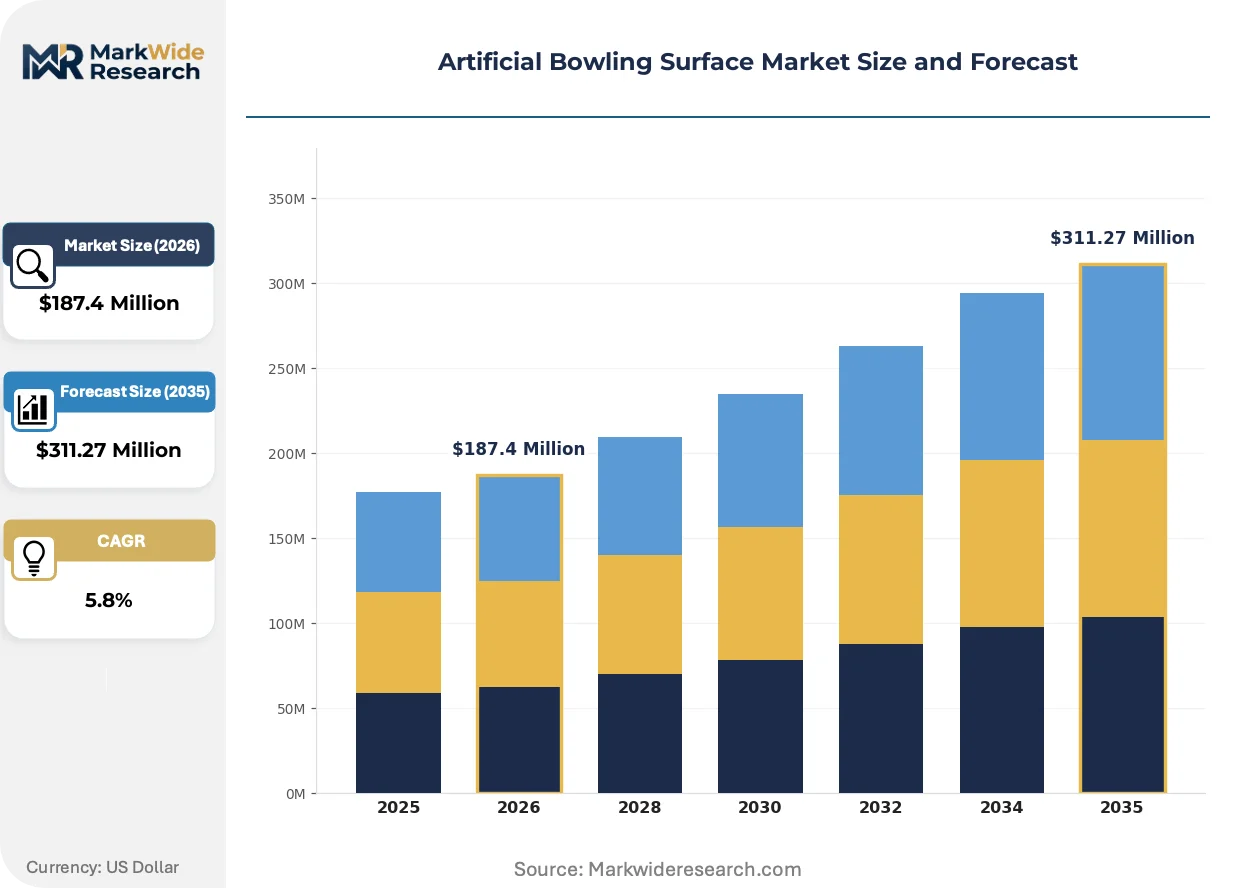
Market Dynamics
Drought-resistant infrastructure mandates across Australia and the United Kingdom are accelerating synthetic surface replacement cycles, compressing procurement timelines from traditional seasonal windows into year-round installation programs.
Growth Catalysts
- REACH compliance deadlines:European clubs must replace legacy wool surfaces by 2027, forcing immediate procurement of polypropylene alternatives certified under ECHA guidelines.
- Water restriction protocols:Australian state governments in Victoria and New South Wales prohibit natural grass irrigation for non-priority sports, redirecting bowling club capital toward synthetic lanes.
- FIFA-equivalent durability testing:Professional tournament venues now require 50,000-cycle wear certification, elevating specification standards that filter down to municipal installations.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, compressing manufacturer margins and triggering quarterly contract renegotiations with bowling federations.
- Specialized installer scarcity:Glue-down systems require certified technicians trained in subfloor moisture management, with qualified labor concentrated in Melbourne, Manchester, and Auckland metro areas.
- Natural grass nostalgia:Crown green purists in Lancashire and Yorkshire resist synthetic conversion, delaying club-level adoption despite maintenance cost pressures.
Strategic Opportunities
- Modular panel systems:Interlocking temporary surfaces enable rapid deployment for pop-up tournament circuits in Southeast Asia, where permanent venue construction lags participation growth.
- End-of-life recycling partnerships:EU Green Deal circular economy mandates create first-mover advantage for manufacturers offering fiber-to-fiber reclamation programs at replacement intervals.
- Climate adaptation grants:UK Sport England facility resilience funding covers 40-60% of synthetic conversion costs for clubs in flood-prone catchment areas.
Industry Challenges
- Subfloor assessment complexity:Existing wooden lane venues require structural engineering surveys before synthetic overlay, extending project timelines by 8-14 weeks.
- Microfiber discharge compliance:MEE environmental inspections in China now test surface runoff for synthetic particle contamination, complicating export certification for Asia-Pacific tournament contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Bowling Surface Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Nylon, Polyester, PVC Application: Professional Tournaments, Recreational Use, Training Facilities, Indoor Leagues Installation Method: Glue Down, Interlocking, Staple Down, Loose Lay End User: Bowling Alleys, Sports Clubs, Educational Institutions, Residential Users |
| Companies Covered | Playrite, TigerTurf, Dales Sports Surfaces, Greengauge, Sportgrass, ABS Sport Surfaces, Grassman, Evergreen Turf, FieldTurf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Bowling Surface Market Emerging Trajectories
Surface engineering is converging with precision manufacturing and environmental compliance, creating new performance benchmarks that separate certified tournament suppliers from recreational-grade competitors.
Multi-layer density profiling is miniaturizing the variation between lane sections, enabling manufacturers to program friction coefficients within 0.02 tolerance across entire playing surfaces. Professional venues in Perth and Brisbane adopt these systems for championship circuits, compressing the performance gap between synthetic and traditional wooden lanes to negligible margins. The technology is miniaturizing quality control costs, allowing mid-tier clubs to access specifications previously reserved for international tournament budgets.
REACH SVHC candidate list expansion is restricting flame retardant chemistries in backing materials, compelling reformulation of woven polypropylene substrates by European manufacturers. ECHA notification requirements now cover 233 hazardous substances, extending compliance documentation to 18-month certification cycles. UK crown green suppliers absorb these costs through premium pricing tiers, while continental clubs delay replacement decisions pending 2026 regulatory clarity.
Consolidated purchasing through national bowling federation frameworks is displacing club-level procurement autonomy, centralizing specification decisions in Manchester and Melbourne headquarters. These arrangements bundle installation, maintenance, and replacement intervals into 10-year service contracts, squeezing independent regional installers from premium segments. The pattern concentrates most visibly in England, where Bowls England's approved supplier list governs 340 club conversions annually.
Artificial Bowling Surface Market Segmentation
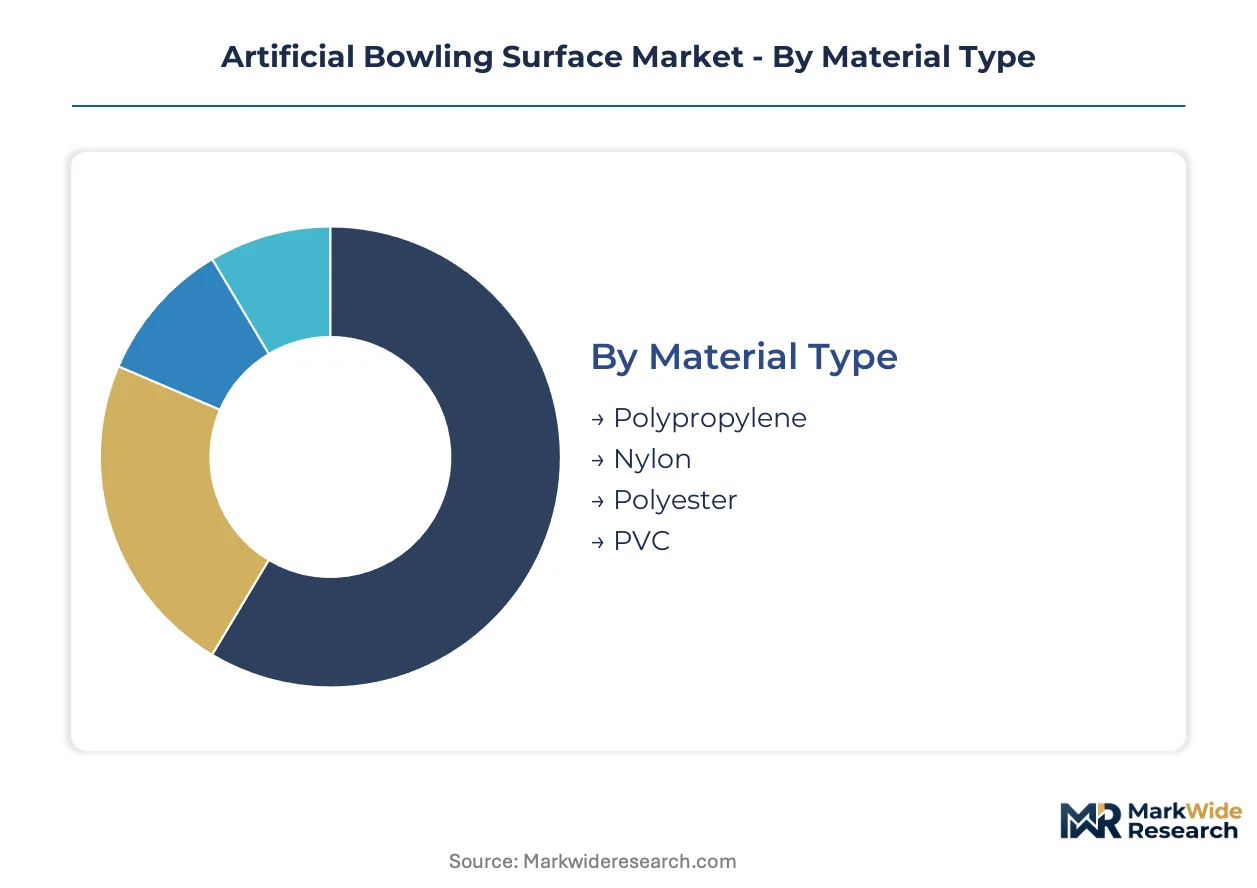
Artificial bowling surface procurement varies sharply across material grades and venue types, with professional specifications commanding premium tolerances while recreational installations prioritize rapid deployment. Understanding these segment boundaries clarifies where manufacturers concentrate R&D investment versus where price competition dominates.
Material Type:
Polypropylene formulations dominate export shipments from Australian manufacturers, while nylon specifications concentrate in UK domestic supply chains serving crown green traditions.
- Polypropylene:UV-stabilized fiber systems with sub-2% moisture absorption rates withstand Australian drought conditions and Victorian water restrictions. Demand concentrates in Perth and Brisbane tournament venues where 50,000-cycle durability certification is mandatory.
- Nylon:Premium-density constructions deliver friction coefficients matching traditional wool surfaces for Lancashire and Yorkshire crown green purists. UK clubs absorb 15-20% cost premiums to maintain play characteristics that satisfy Bowls England heritage standards.
- Polyester:Budget-tier installations in Southeast Asian training facilities balance wear resistance against tropical humidity exposure.
- PVC:Short-lifecycle recreational surfaces for residential patios and temporary pop-up lanes prioritize cost minimization over roll consistency.
Polypropylene holds the largest share; momentum sits with nylon as UK regulatory deadlines force wool replacement.
Application:
Cost tiers separate permanent venue investments from modular deployments, with professional specifications absorbing 60-70% of manufacturer margin contribution.
- Professional Tournaments:Multi-layer density profiling achieves 0.02 friction tolerance across entire lane systems. Perth and Brisbane championship circuits validate synthetic performance parity with traditional wooden lanes.
- Recreational Use:Municipal clubs in England leverage Sport England resilience grants covering 40-60% of conversion costs in flood-prone catchment areas.
- Training Facilities:Interlocking panel systems enable rapid redeployment for Southeast Asian pop-up circuits where permanent construction lags participation growth.
- Indoor Leagues:Glue-down installations dominate Melbourne and Manchester metro markets where certified technician availability constrains supply.
Professional tournaments generate highest absolute margins; training facilities are climbing fastest on temporary infrastructure demand.
Installation Method:
Volume concentration favors permanent glue-down systems, though customer type fragmentation creates niche openings for specialized techniques.
- Glue Down:Subfloor moisture management protocols extend project timelines 8-14 weeks but deliver 12-15 year replacement cycles for bowling alleys in Victoria and New South Wales.
- Interlocking:Modular panels capture educational institution procurement for multi-use gymnasium conversions requiring seasonal surface removal.
- Staple Down:Sports clubs in Auckland apply this method over existing wooden substructures where structural engineering surveys reveal load-bearing constraints.
- Loose Lay:Residential users in Australian suburbs favor this lowest-labor option for backyard practice lanes with sub-5 year expected usage.
Glue down commands installed value; interlocking gains share fastest on institutional flexibility requirements.
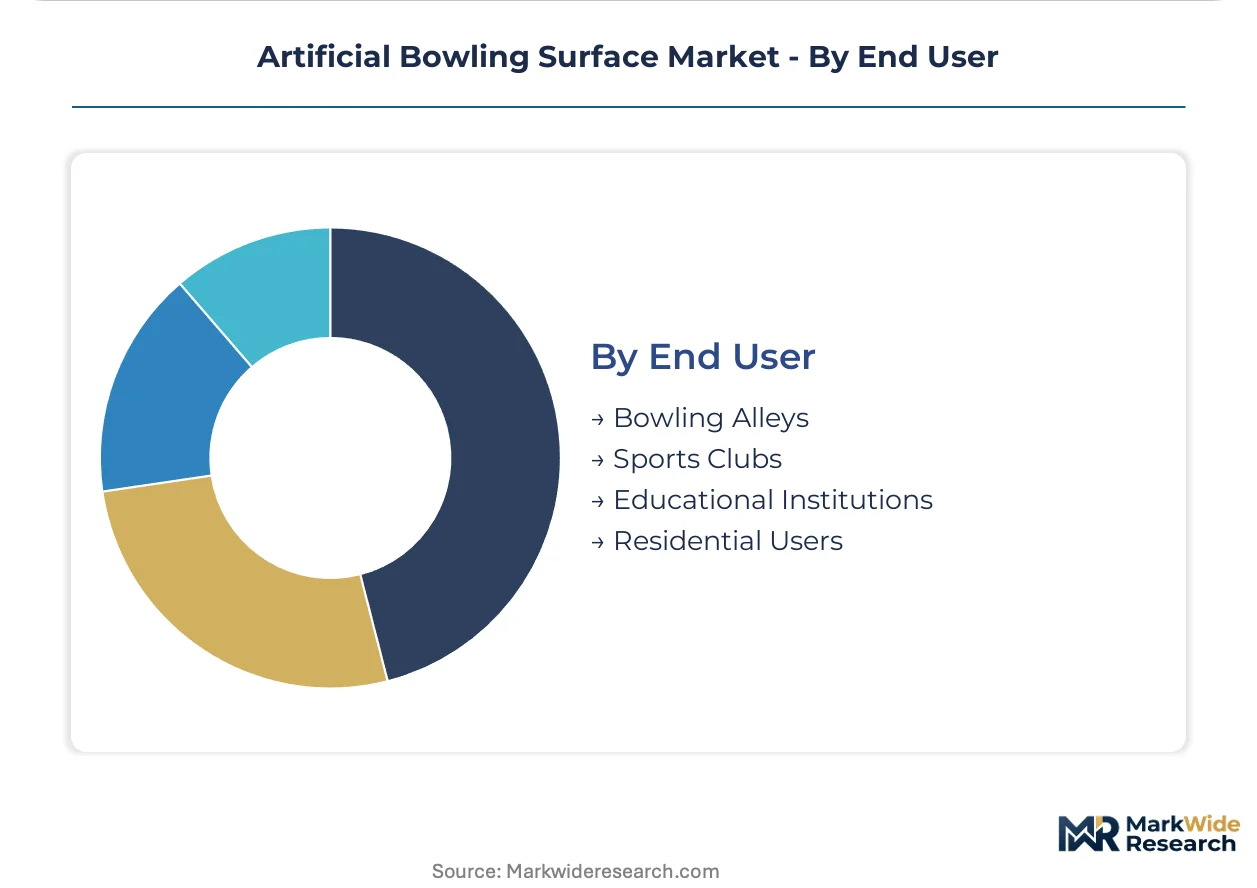
End User:
Supply chain configuration varies by buyer sophistication, with federation-affiliated clubs accessing bundled service contracts unavailable to independent purchasers.
- Bowling Alleys:Commercial operators in Melbourne and Sydney negotiate 10-year maintenance-inclusive contracts through national federation frameworks.
- Sports Clubs:Crown green and flat green specialists across England face REACH compliance deadlines forcing immediate polypropylene procurement.
- Educational Institutions:Australian state schools redirect capital toward synthetic lanes as drought-resistant infrastructure mandates eliminate natural grass irrigation options.
- Residential Users:DIY-installation segments in UK suburbs and Australian exurbs drive PVC and loose-lay volume through hardware retail channels.
Bowling alleys represent the largest revenue pool; educational institutions show steepest expansion trajectory on public infrastructure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Australian buyers absorb premium specifications for drought resilience, while UK clubs negotiate hard on conversion grants, and Southeast Asian markets prioritize rapid-deployment cost minimization over performance tolerances.
Australia
Drought-resistant infrastructure mandates in Victoria and New South Wales are compressing procurement timelines into year-round installation programs. State water restriction protocols prohibit natural grass irrigation for non-priority sports, redirecting club capital toward synthetic lanes. Melbourne hosts the densest concentration of certified glue-down technicians, constraining supply for regional bowling alley projects.
United Kingdom
Crown green bowling clubs across Lancashire and Yorkshire face mounting maintenance cost pressures amid unpredictable seasonal rainfall. REACH compliance deadlines force immediate replacement of legacy wool surfaces with polypropylene alternatives certified under ECHA guidelines. Manchester anchors Bowls England's centralized procurement framework, governing 340 annual club conversions through approved supplier lists.
China
MEE environmental inspections now test surface runoff for synthetic particle contamination, complicating export certification for Asia-Pacific tournament contracts. Manufacturers serving the domestic training facility segment navigate dual carbon goals while balancing tropical humidity exposure against wear resistance specifications. Guangdong province concentrates interlocking panel production for Southeast Asian pop-up circuit deployment.
Germany
EU Green Deal circular economy mandates create compliance burdens for end-of-life disposal decisions, favoring manufacturers offering fiber-to-fiber reclamation programs. REACH SVHC candidate list expansion restricts flame retardant chemistries in backing materials, extending certification cycles to 18 months. North Rhine-Westphalia hosts the largest concentration of bowling federation technical committees influencing continental specification standards.
United States
Commercial bowling alley operators negotiate multi-year maintenance-inclusive contracts through national federation procurement frameworks. EPA stormwater discharge regulations intersect with state-level drought declarations in California and Arizona, accelerating synthetic conversion decisions. The Pacific Northwest concentrates educational institution demand for modular panel systems enabling seasonal gymnasium surface removal.
Artificial Bowling Surface Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium-density specifications command margins while commodity-grade volume competes on installation speed. The vendor base clusters around three strategic positions: Australian export-oriented manufacturers leveraging polypropylene formulations, UK specialists engineering crown green heritage compliance, and diversified synthetic turf operators extending expertise into niche bowling applications. M&A activity concentrates on installer network consolidation, while geographic expansion drives Asian market entry through modular panel distribution partnerships.
Among Australia-based manufacturers, TigerTurf anchors export-oriented supply chains across Asia-Pacific tournament venues. Playrite occupies a specialist position within UK crown green and flat green surface engineering, exemplifying heritage-market adaptation. FieldTurf represents the diversified synthetic turf archetype, leveraging broader sports surface expertise into bowling lane niche applications.
| Leading Market Players |
|---|
| Playrite |
| TigerTurf |
| Dales Sports Surfaces |
| Greengauge |
| Sportgrass |
| ABS Sport Surfaces |
| Grassman |
| Evergreen Turf |
| FieldTurf |
| Others |
Supply Flow & Price Mechanics
Ten-year federation service contracts lock in supply access and price visibility for bowling alley operators across Australia and England, compressing quarterly renegotiation cycles while embedding maintenance and replacement intervals into fixed-cost structures.
Pricing Analysis
REACH compliance deadlines dictate the pricing tier structure across European procurement, forcing clubs to absorb ECHA certification premiums or defer conversion decisions. Three-tier pricing structure across premium, standard, and economy levels separates multi-layer density profiling systems from glue-down municipal installations and loose-lay residential panels. Cost compression in standard-tier specifications is intensifying because polypropylene resin prices fluctuate with crude oil benchmarks. Municipal clubs in flood-prone English catchments exhibit highest price sensitivity due to grant dependency, while Perth tournament venues absorb premium tolerances with minimal negotiation.
Supply Chain Analysis
Inventory buffers extend to 14-18 weeks for specialized glue-down systems requiring certified technician deployment, compressing cash conversion cycles for regional installers. Manufacturing concentrates in Australia, the United Kingdom, and China, with Guangdong province anchoring interlocking panel production for Southeast Asian export. Formulation draws from UV-stabilized polypropylene resin, woven polypropylene backing substrates, and specialized infill layer compounds. Single-source vulnerability sits with Melbourne and Manchester metro areas hosting qualified subfloor moisture management technicians. Distribution runs through national bowling federation procurement frameworks bundling installation, maintenance, and replacement intervals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Bowls England's approved supplier list governing 340 annual club conversions, shifting procurement autonomy from individual clubs to centralized federation headquarters.
For Market Incumbents: Shield margin contribution in professional tournament segments by accelerating multi-layer density profiling R&D investments before FIFA-equivalent durability standards filter down to municipal installations. Deepen backward integration into UV-stabilized polypropylene resin formulation to offset petrochemical feedstock volatility compressing quarterly contract renegotiations. For New Entrants and Emerging Players: Differentiate on modular panel system engineering for Southeast Asian pop-up tournament circuits where permanent venue construction lags participation growth. Target educational institution procurement in the Pacific Northwest and Australian state schools redirecting capital toward drought-resistant synthetic lanes under infrastructure mandates. Deploy rapid-redeployment value proposition through hardware retail channels bypassing federation framework bundling. For Investors and Strategic Acquirers: Capital is best deployed toward installer network consolidation in Melbourne, Manchester, and Auckland metro areas where certified technician scarcity constrains supply expansion. Long-term viability rests on fiber-to-fiber reclamation program capabilities aligning with EU Green Deal circular economy mandates. Watch MEE environmental inspection intensity in China as inflection indicator for Asia-Pacific export certification complexity.| Strategic Initiative | Industry Significance |
|---|---|
| Installer Network Consolidation | Captures scarce certified technician capacity in Melbourne and Manchester metro markets. |
| Fiber-to-Fiber Reclamation Program | Aligns with EU Green Deal circular economy mandates for end-of-life surface disposal. |
| Multi-Layer Density Profiling R&D | Achieves 0.02 friction tolerance specifications required by Perth championship circuits. |
| Modular Panel Distribution Partnership | Enables rapid deployment for Southeast Asian pop-up tournament infrastructure gaps. |
| ECHA Certification Pre-Positioning | Secures REACH SVHC compliance ahead of 18-month documentation cycle extensions. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with bowling federation procurement officers, certified installation technicians, and sports facility capital planners; and secondary validation through ECHA substance database queries, Bowls England approved supplier registries, and Australian state water restriction protocol filings. Bottom-up triangulation against top-down federation framework contract value estimates anchored volume and value outputs.
Across the projection horizon, the analytical framework modeled material type, application tier, installation method complexity, and end-user buyer sophistication. CAGRs derived from replacement cycle compression patterns and drought-resistant infrastructure mandate adoption curves. Industry-specific inputs included 50,000-cycle wear certification penetration rates and REACH SVHC candidate list expansion timelines.
Forecasts assume regulatory continuity in ECHA REACH administration and Australian state water restriction protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
North America Industrial Flooring Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Mexican Insulated Panels Market
Building & Construction Materials
Composite Roof Shingle Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Plastic Door and Window Market