
 Work Order Management Market | 2026-2036
Work Order Management Market Size, Share, and Industry Trends Forecast 2026-2036
Work Order Management Market Analytics
North American software vendors is realigning capacity toward API-first architectures that interoperate with industrial IoT layers. SAP leverages its ERP-installed base to anchor enterprise work order workflows across process industries. ServiceNow competes on IT-OT convergence, extending service management primitives into plant-floor maintenance orchestration.
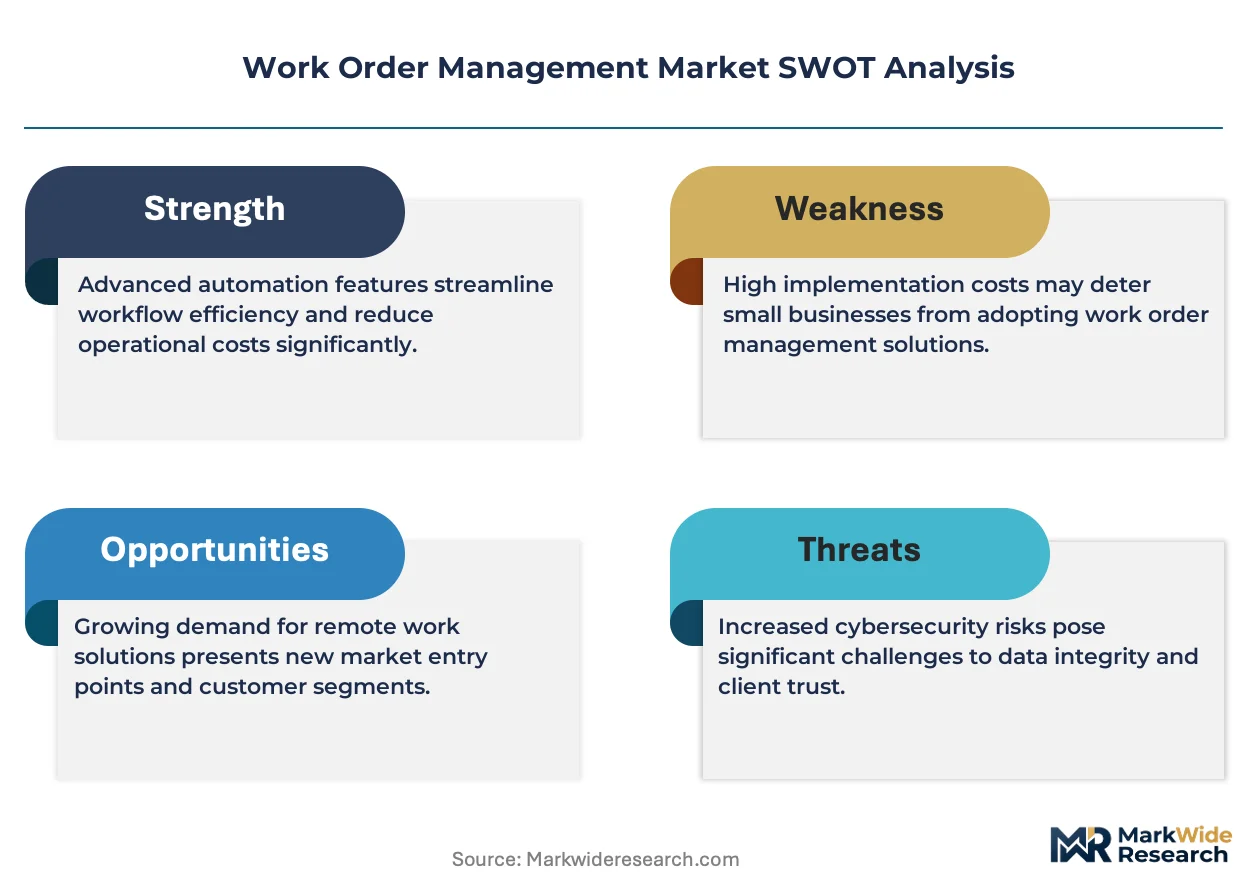
Work order management systems constitute software platforms that coordinate task origination, resource allocation, scheduling, execution tracking, and closure verification for physical asset maintenance, typically integrating with CMMS or EAM databases through standardized protocols such as OPC-UA or REST APIs. Cloud-based deployment leads structural expansion due to lower capital barriers and faster rollout cycles for distributed workforces, while on-premise installations retain dominance in regulated environments where data residency requirements restrict off-premises hosting. The solution layer shows workflow automation capturing margin pools as manufacturers prioritize predictive trigger-to-action pipelines over static preventive schedules.
The EU AI Act, OSHA recordkeeping mandates in the United States, and ISO 55000 asset management standards collectively shape product roadmaps by requiring explainable automation logic and auditable safety documentation within work order platforms. FDA 21 CFR Part 11 obligations in pharmaceutical manufacturing further constrain system validation protocols for electronic signatures and batch record integration. Stakeholders must evaluate whether their vendor's compliance architecture can absorb impending algorithmic transparency requirements without fragmenting user experience.
Market Dynamics
Cloud-native work order platforms are compressing replacement cycles for legacy CMMS installations as manufacturers prioritize predictive trigger-to-action pipelines over static preventive maintenance schedules.
Growth Catalysts
- Industrial IoT penetration:Sensor networks on plant floors generate real-time asset health data that feeds automated work order generation. United States manufacturing facilities lead this deployment wave.
- EU AI Act compliance pressure:Algorithmic accountability mandates force vendors to embed explainable automation logic and audit trails into dispatch systems. This accelerates platform modernization.
- Legacy CMMS replacement cycles:On-premise systems installed during the 2010-2015 expansion window reach end-of-life. Cloud migration lowers capital barriers for distributed workforces.
Market Restraints
- Data residency requirements:FDA 21 CFR Part 11 and national pharmaceutical regulations constrain off-premises hosting. Regulated environments retain on-premise dominance.
- Integration complexity:OPC-UA and REST API standardization remains incomplete across brownfield asset bases. Fragmented protocol support extends implementation timelines.
- Skill scarcity:IT-OT convergence demands hybrid competencies spanning industrial automation and enterprise software. Talent pools concentrate in specific metropolitan technology corridors.
Strategic Opportunities
- Process industry expansion:Chemical and pharmaceutical manufacturers require batch record integration with electronic signature validation. This vertical demands specialized workflow modules.
- IT-OT convergence:Service management primitives extend into plant-floor maintenance orchestration. Converged platforms capture margin pools previously split between separate systems.
- API-first architectures:North American software vendors realign capacity toward interoperable layers. Open integration frameworks attract ecosystem developers and reduce customer switching costs.
Industry Challenges
- Brownfield system integration:Decades-old SCADA and DCS installations lack standardized data export capabilities. Custom middleware development consumes implementation resources.
- Algorithmic transparency requirements:Automated dispatch logic must generate human-interpretable decision trails. Engineering teams balance explainability against optimization performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Work Order Management Market |
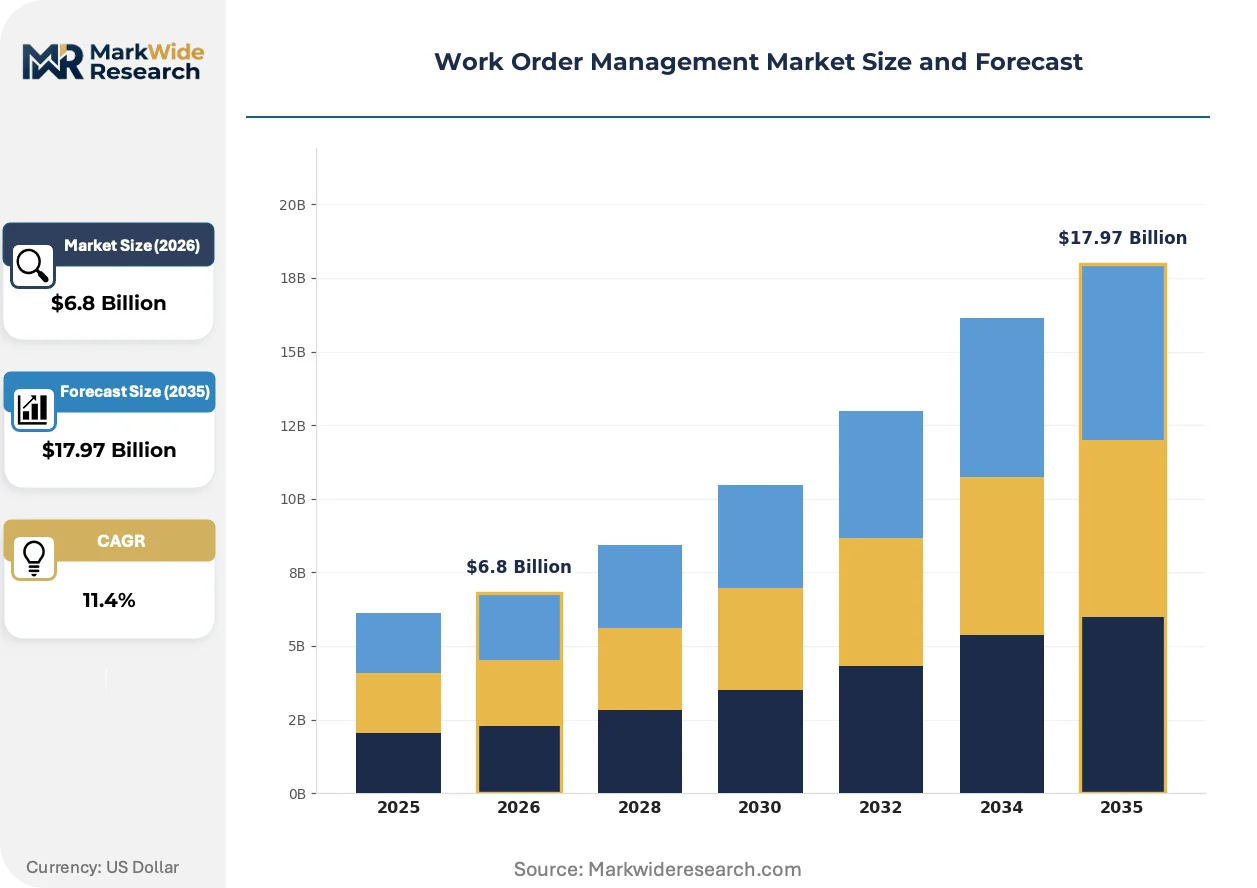
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Maintenance, Construction, Manufacturing, Utilities Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Facilities Management, Energy Sector, Manufacturing Facilities, Service Providers Solution: CMMS, EAM, Workflow Automation, Asset Management |
| Companies Covered | IBM, SAP, Oracle, ServiceNow, ServiceTitan, UpKeep, Microsoft, Salesforce, Infor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Work Order Management Market Evolving Landscape
Work order management systems are evolving from static scheduling tools into predictive orchestration layers that anticipate equipment degradation before functional failure occurs.
Digital twin technology is integrating with work order platforms to simulate asset degradation scenarios and optimize maintenance timing. Heavy process manufacturers in petrochemical and power generation sectors deploy these capabilities at scale. The technology is integrating physical asset models with real-time operational data to compress mean-time-to-repair metrics.
OSHA recordkeeping mandates in the United States now require auditable safety documentation within maintenance workflows. Industrial facilities must link work order completion to incident investigation protocols. Pharmaceutical and food processing plants face the strictest enforcement, driving demand for platforms with embedded compliance modules.
Buyer procurement patterns favor subscription-based deployment over perpetual licensing. Capital-constrained mid-market manufacturers prefer operational expenditure models that align software costs with production output. This preference shift concentrates in United States industrial clusters where private equity ownership pressures short-term cash flow optimization.
Work Order Management Market Segmentation
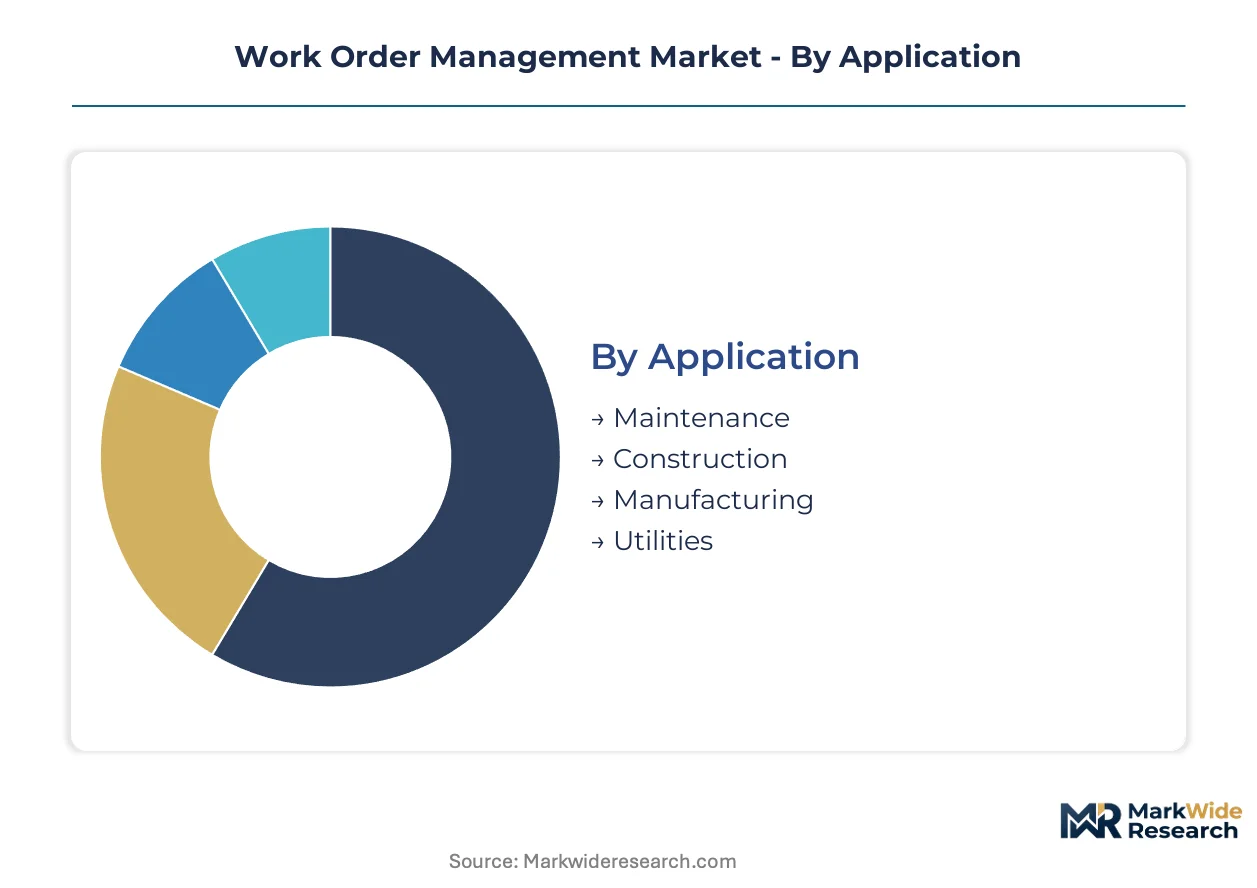
Work order management platforms serve heterogeneous operational environments, from pharmaceutical batch processing to distributed utility infrastructure. Segmentation reveals how deployment constraints, regulatory exposure, and asset complexity shape procurement decisions across buyer categories.
Application:
Replacement cycles for legacy maintenance systems are accelerating as facilities prioritize predictive trigger-to-action pipelines over static preventive schedules.
- Maintenance:Platforms coordinate corrective, preventive, and condition-based work orders through integration with vibration analysis and thermal imaging diagnostics. Demand concentrates in United States petrochemical complexes where OSHA process safety management mandates require auditable maintenance documentation.
- Manufacturing:Systems orchestrate production-line asset uptime through real-time integration with MES and SCADA layers. German automotive OEMs and their tier suppliers lead procurement, driven by ISO 55000 asset management certification requirements and just-in-sequence production dependencies.
- Utilities:Grid operators deploy field service management for transmission and distribution asset maintenance.
- Construction:Project-based work order tracking manages subcontractor coordination and equipment deployment.
Maintenance sits at the top of the volume ranking, with Manufacturing climbing the fastest.
Deployment:
Cost tier differentiation separates capital-intensive on-premise installations from operational-expenditure cloud subscriptions favored by mid-market buyers.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server procurement and reduce implementation timelines from months to weeks. United States industrial clusters with private equity ownership pressure short-term cash flow optimization, concentrating demand here.
- On-Premise:Single-tenant deployments retain dominance where FDA 21 CFR Part 11, EU GMP Annex 11, or national pharmaceutical regulations constrain off-premises hosting. Validation protocols for electronic signatures and batch record integration extend sales cycles.
- Hybrid:Edge computing nodes process sensitive operational data locally while transmitting aggregated analytics to cloud dashboards.
- Mobile:Native iOS and Android applications extend work order access to field technicians without continuous connectivity.
Cloud-Based captures the dominant revenue position, with Hybrid gaining share fastest among brownfield facilities seeking phased migration paths.
End User:
Customer type fragmentation reflects divergent compliance burdens, with regulated process industries demanding specialized validation modules that commodity facilities management buyers rarely require.
- Manufacturing Facilities:Discrete and process manufacturers integrate work order platforms with ERP, MES, and quality management systems. Japanese electronics fabricators and South Korean semiconductor foundries drive procurement for cleanroom maintenance protocols and contamination control documentation.
- Energy Sector:Oil and gas operators, renewable asset managers, and electric utilities require geospatial work order dispatch and mobile offline capabilities for remote site access.
- Facilities Management:Commercial real estate operators prioritize tenant service request portals and SLA tracking.
- Service Providers:Third-party maintenance contractors need multi-tenant architectures to segregate client data.
Manufacturing Facilities lead absolute spending, with Energy Sector expanding most quickly on renewable asset buildouts.
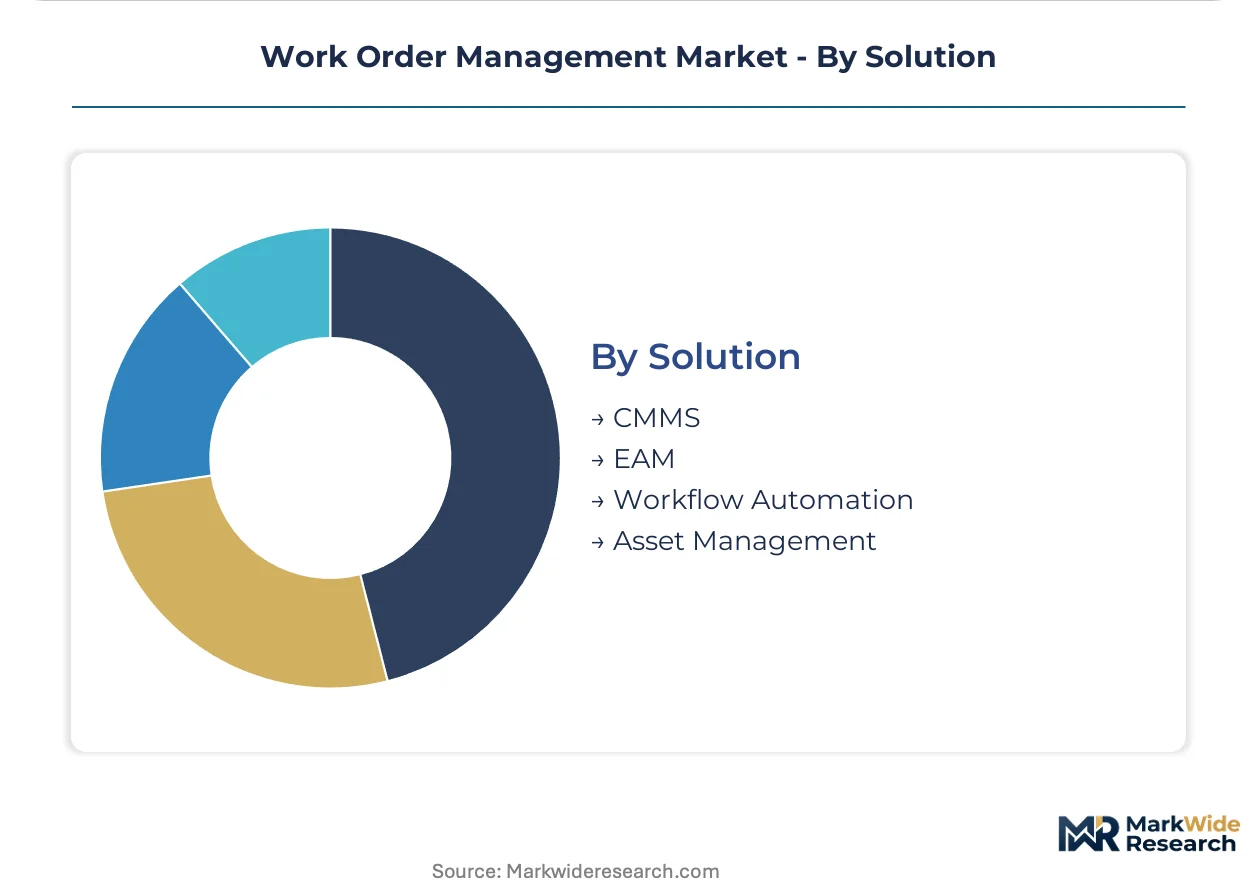
Solution:
Margin concentration follows workflow automation capabilities that compress mean-time-to-repair through predictive trigger generation, leaving commoditized CMMS functionality with thinner pricing power.
- Workflow Automation:Rule engines and machine learning models automatically generate, prioritize, and route work orders based on sensor thresholds, calendar schedules, or regulatory deadlines. EU AI Act algorithmic accountability mandates are forcing vendors to embed explainable decision trails, accelerating platform modernization investments.
- Asset Management:Lifecycle cost tracking and reliability-centered maintenance modules optimize capital deployment for critical infrastructure. Australian mining operations and Canadian oil sands producers deploy these capabilities at scale given remote location maintenance cost structures.
- CMMS:Core work order origination, resource scheduling, and closure verification functionality.
- EAM:Enterprise-scale asset registries with financial depreciation integration and strategic portfolio planning.
Workflow Automation commands premium pricing, with Asset Management showing the steepest expansion trajectory on digital twin integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs deploy work order platforms with tighter CMMS-EAM integration than United States petrochemical operators, reflecting divergent regulatory pressures on maintenance documentation.
United States
Industrial IoT penetration in manufacturing facilities generates real-time asset health data for automated work order generation. OSHA process safety management mandates require auditable maintenance documentation in petrochemical complexes. Houston-Gulf Coast chemical corridor operators lead procurement of cloud-native platforms with predictive trigger-to-action pipelines.
Germany
Automotive OEMs and tier suppliers prioritize ISO 55000 asset management certification and just-in-sequence production dependencies. The EU AI Act pressures vendors to embed explainable automation logic into dispatch systems. Stuttgart and Munich industrial clusters drive demand for workflow automation with MES-SCADA integration.
China
MIIT industrial internet initiatives accelerate smart factory deployments with sensor-network-driven maintenance orchestration. GB standards for equipment management constrain platform validation protocols. Yangtze River Delta electronics fabricators procure systems with cleanroom maintenance protocols and contamination control documentation.
Japan
METI Society 5.0 roadmaps push predictive maintenance adoption in semiconductor and precision manufacturing. JIS standards for asset reliability shape vendor product roadmaps. Kyushu and Tohoku manufacturing belts concentrate demand for digital twin-integrated work order platforms.
India
PLI scheme incentives for electronics and pharmaceutical manufacturing expand CMMS replacement cycles. CDSCO pharmaceutical regulations constrain electronic signature validation requirements. Maharashtra and Gujarat industrial corridors attract cloud-based platform deployments for distributed workforce coordination.
Work Order Management Market Competitive Landscape
United States software vendors anchor the cloud-native tier; German and Japanese specialists hold positions in regulated on-premise installations. Market structure shows moderate consolidation around ERP-anchored incumbents and API-first challengers. Three archetypes dominate: ERP-extenders leveraging installed bases, IT-OT convergence platforms, and vertical SaaS specialists. Competitive moves concentrate on M&A for IoT connectivity assets and strategic partnerships with industrial automation vendors.
Within the ERP-extender archetype, SAP and Oracle occupy positions anchored to enterprise financial systems, while ServiceNow exemplifies the IT-OT convergence play extending service management primitives into plant-floor orchestration. These three represent distinct strategic vectors rather than direct substitution competitors.
| Leading Market Players |
|---|
| IBM |
| SAP |
| Oracle |
| ServiceNow |
| ServiceTitan |
| UpKeep |
| Microsoft |
| Salesforce |
| Infor |
| Others |
Value Network & Pricing Analysis
Mid-market manufacturers with private equity ownership concentrate procurement authority in United States industrial clusters, driving subscription-based SaaS pricing dominance over perpetual licensing models. This buyer archetype pressures vendors toward operational expenditure structures that align software costs with production output cycles.
Pricing Analysis
Capacity additions in North American cloud infrastructure are reshaping price floors for work order platforms as hyperscaler competition intensifies. Three-tier pricing structure across premium, standard, and economy levels segments by workflow automation depth and CMMS-EAM integration complexity. Price differentiation hinges on FDA 21 CFR Part 11 validation tier and predictive analytics module inclusion. Pricing pressure stems from API-first challengers commoditizing core CMMS functionality. Mid-market discrete manufacturers exhibit highest price sensitivity; pharmaceutical facilities with batch record integration requirements show lowest.
Supply Chain Analysis
Dual-sourcing requirements from regulated pharmaceutical and food processing buyers mandate multi-supplier qualification for cloud hosting and edge computing hardware. Software development concentrates in United States, Germany, and India. Platform delivery draws from Taiwan semiconductor foundries for edge devices, Irish data centers for EU residency compliance, and domestic cloud regions for latency-sensitive deployments. Single-source vulnerability exists in specialized industrial IoT sensor supply. Distribution runs through direct enterprise sales with systems integrator channel partners for brownfield implementation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Work order management represents a late-cycle quality story as buyer procurement shifts toward predictive trigger-to-action pipelines over static preventive maintenance specifications. Premium workflow automation modules command expanding margin pools.
For Market Incumbents: Extend API-first architecture investments to neutralize IT-OT convergence challengers. Consolidate position through embedded compliance modules for EU AI Act algorithmic accountability mandates. Acquire specialized industrial IoT connectivity assets to close brownfield integration gaps. Capacity addition in Indian development centers reduces implementation cost structures for mid-market penetration. For New Entrants and Emerging Players: EU AI Act compliance pressure in Germany and France opens a window for explainable automation logic specialists. Target pharmaceutical batch record integration as the most penetrable vertical given validation protocol complexity that incumbents execute slowly. Pursue OEM partnership go-to-market angle with German automotive tier suppliers seeking MES-SCADA convergence. For Investors and Strategic Acquirers: Industrial automation vendors are the most active acquirer in this space, seeking service management primitives for plant-floor orchestration. Five-to-ten year viability centers on predictive maintenance algorithm differentiation rather than CMMS commoditization. Acquire vertical SaaS specialists with pre-built FDA validation documentation. Watch OSHA process safety management enforcement intensity as inflection indicator for compliance-module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures interoperate with industrial IoT layers through OPC-UA standardization. |
| Acquisition of Specialist Firm | Industrial IoT connectivity assets close brownfield SCADA integration gaps for cloud-native vendors. |
| Strategic Partnership | Systems integrator alliances accelerate brownfield implementation timelines for mid-market manufacturers. |
| Product Launch | Digital twin-integrated modules compress mean-time-to-repair for petrochemical operators. |
| Geographic Expansion | Indian development centers reduce implementation costs for PLI-scheme electronics manufacturers. |
Research Methodology
Coverage spans United States, Germany, China, Japan, and India, with primary inputs from each market. The approach combines structured interviews with maintenance directors, plant engineers, IT-OT integration specialists, and aftermarket service heads with secondary validation. Sources include SEC 10-K filings, EIA industrial energy data, EU AI Act implementation guidance, and customs records for industrial software trade flows. Bottom-up facility-level demand estimates triangulate against top-down vendor revenue analysis.
Granularity-level modeling deploys deployment mode, organization size, vertical industry, and integration complexity as core segmentation dimensions across the analysis window. CAGRs derive from logistic adoption curve fitting for cloud migration and replacement cycle timing. Industry-specific inputs include industrial IoT sensor deployment rates from manufacturing census data and CMMS end-of-life replacement schedules from facility age distributions.
Revisions become necessary when EU AI Act enforcement intensity, OSHA recordkeeping mandate expansion, or industrial IoT protocol standardization breakthroughs materialize. Deviation in pharmaceutical regulatory validation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Excavating Contractor Market
Construction Services
NDT and Inspection Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Global Pipeline Maintenance Services Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Gutter Cleaning Services Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Grease Trap Service Market
Construction Services
Construction TIC Market
Construction Services
Construction Project Management Services Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Die Casting Services Market
Construction Services
Construction Materials Testing Equipment Market