
 High-Voltage Isolation and Leakage Sensor Components Market | 2026-2036
High-Voltage Isolation and Leakage Sensor Components Market Size, Share, and Industry Trends Forecast 2026-2036
High-Voltage Isolation and Leakage Sensor Components Market Insights
Modular sensor-subsystem bundling is repositioning procurement patterns as buyers seek pre-certified isolation-leakage modules rather than discrete components. Texas Instruments leverages its analog front-end integration to anchor design-ins across energy storage system developers. Analog Devices specializes in high-precision magnetic isolation architectures that sustain premium positioning in electric traction applications. Vishay Intertechnology competes through scaled manufacturing of optocouplers for circuit protection segments.
High-voltage isolation and leakage sensor components comprise engineered sensing elements and signal-conditioning circuitry designed to measure electrical isolation integrity and detect current leakage across galvanically separated domains, typically operating at dielectric withstand ratings exceeding 2.5 kVrms and response thresholds in the milliampere range for human-safety protection. Their primary purpose centers on preventing electric shock hazards, equipment damage, and fire risks in power-electronic systems where high-voltage buses interface with low-voltage control domains. Optocouplers and Hall effect sensors dominate unit volumes, with capacitive sensors representing the fastest-growing product category as silicon-on-insulator processes enable higher integration density. Digital technology architectures command expanding share as microcontroller-integrated diagnostics replace analog-only signal chains, particularly in fault detection and renewable energy inverter applications where predictive maintenance protocols demand serial data outputs.
IEC 61508 functional safety standards, UL 1741-SA grid interconnection requirements, and the EU F-Gas Regulation collectively mandate traceable isolation performance validation and refrigerant-leakage monitoring in electrified thermal systems, directly shaping product roadmaps and market access conditions for component suppliers. NHTSA electrical safety protocols and China's GB/T standards for electric vehicles impose additional dielectric-test regimes that filter non-compliant suppliers from qualified vendor lists. Stakeholders must monitor evolving certification reciprocity agreements between jurisdictions to anticipate qualification cost shifts and sourcing strategy adjustments.
Market Dynamics
Modular subsystem bundling is compressing procurement cycles as battery management system developers abandon discrete component sourcing in favor of pre-certified isolation-leakage modules that slash qualification timelines.
Growth Catalysts
- UL 1741-SA grid interconnection rules:US utility-scale storage developers face mandatory anti-islanding and rapid shutdown compliance, forcing inverter OEMs to source certified isolation sensors for every megawatt-hour deployed.
- Silicon-on-insulator processes:Capacitive isolation architectures fabricated on SOI wafers achieve 5 kVrms dielectric ratings with 40% smaller footprints than optocouplers, accelerating design-ins across compact onboard chargers.
- Germany's grid-scale storage buildout:The KBA and Bundesnetzagentur jointly enforce IEC 61508 SIL-2 requirements for battery energy storage systems, creating qualified vendor list bottlenecks that favor certified sensor suppliers.
Market Restraints
- Silicon carbide substrate costs:High-voltage isolation ICs requiring SiC-based isolation barriers face input cost volatility as 150mm wafer supply concentrates among three foundry operators.
- Functional safety certification friction:IEC 61508 SIL-3 validation cycles extend 18-24 months, filtering fabless entrants from automotive qualified supplier lists regardless of technical performance.
- Magnetic isolation substitution:Giant magnetoresistive sensors from industrial automation suppliers encroach on Hall effect strongholds in sub-1000V traction inverter applications.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Cell manufacturing capacity expansion under the 18 GWh production-linked incentive program creates first-mover advantage for isolation sensor vendors establishing local calibration facilities.
- Refrigerant-leakage convergence:EU F-Gas Regulation mandates electrified thermal system monitoring, opening cross-selling pathways for isolation sensor suppliers with capacitive moisture-detection IP.
- Direct OEM contracting:Tier-1 module suppliers are disintermediating traditional distribution as NIO, BYD, and Tesla establish captive sensor qualification programs with die-level traceability requirements.
Industry Challenges
- Functional safety engineer scarcity:IEC 61508 certified system architects command 40% salary premiums, constraining product development velocity for mid-cap sensor vendors.
- Legacy analog integration complexity:400V-to-800V platform transitions force simultaneous redesign of signal conditioning chains and microcontroller interface protocols, extending validation cycles.
- Dielectric test equipment lead times:Partial discharge analyzers required for 2.5 kVrms validation face 26-week delivery backlogs from German and Japanese metrology equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Voltage Isolation and Leakage Sensor Components Market |
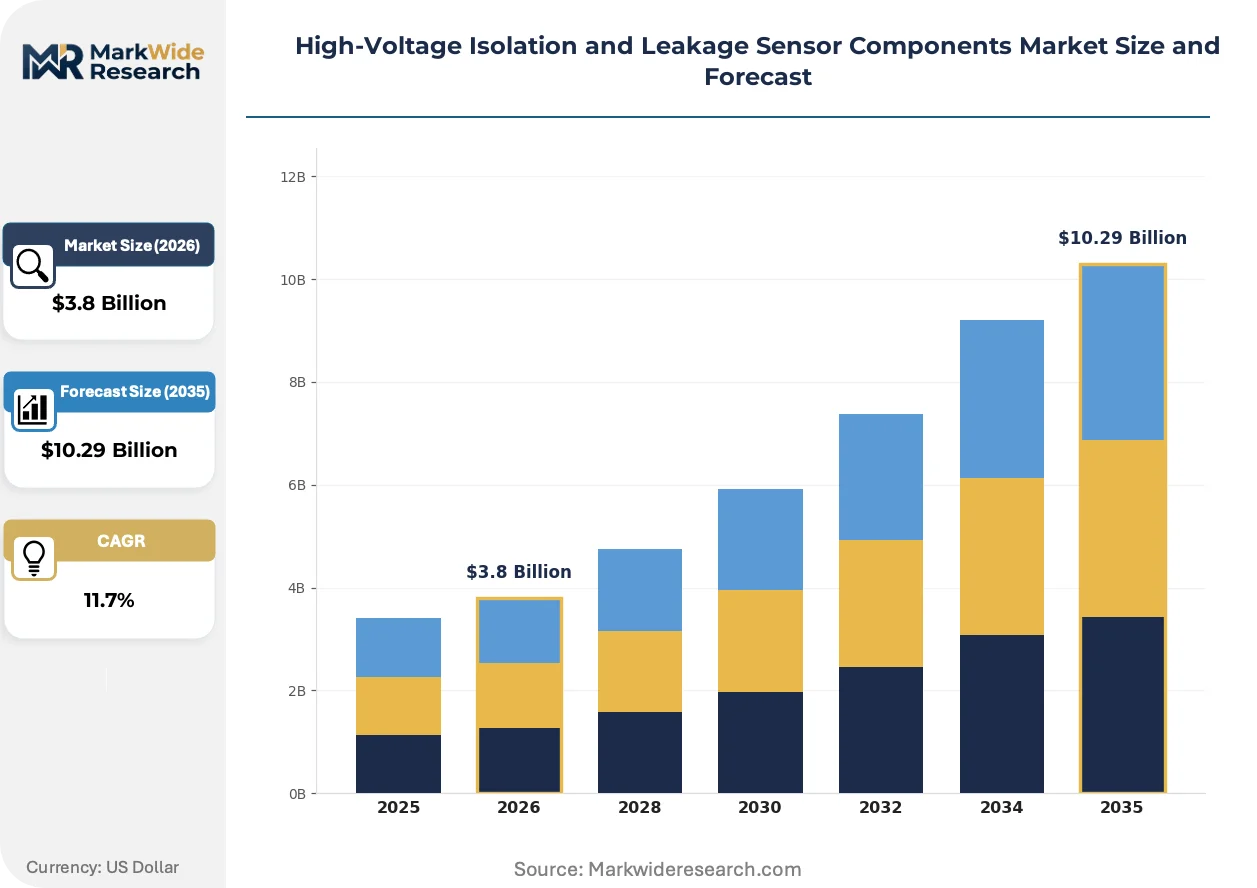
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optocouplers, Hall Effect Sensors, Capacitive Sensors, Resistive Sensors, Magnetoresistive Sensors Technology: Analog, Digital, Fiber Optic, Magnetic, Piezoelectric, Thermal Application: Energy Storage Systems, Renewable Energy Inverters, Electric Traction, Fault Detection, Circuit Protection End User: Power Electronics Manufacturers, Renewable Energy Integrators, Electric Vehicle Assemblers, Industrial Automation Firms |
| Companies Covered | Bender, Texas Instruments, Analog Devices, Vishay Intertechnology, Renesas Electronics, LEM International, Honeywell, Sensata Technologies, Isabellenhütte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Voltage Isolation and Leakage Sensor Components Market Trends and Innovations
Digital diagnostic architectures are displacing analog-only signal chains as predictive maintenance protocols in renewable energy inverters demand serial data outputs with fault location granularity.
Capacitive isolation technology leveraging silicon-on-insulator wafers is electrifying the medium-voltage sensor segment. The technology achieves 150 Mbps data rates across 5 kVrms barriers while eliminating LED aging failure modes inherent to optocouplers. Onboard charger designers at European and Chinese automotive OEMs are adopting these devices for 11-22 kW AC charging modules. This displacement is compressing optocoupler incumbents into circuit protection applications below 1 kVrms.
EU F-Gas Regulation phase-down mandates are forcing refrigerant-leakage sensor integration into heat pump and thermal management systems. The regulation requires ppm-level detection sensitivity for fluorinated gases with global warming potential above 150. Isolation sensor suppliers with capacitive humidity-sensing IP are repurposing these architectures for refrigerant-specific chemiresistive detection. German HVAC OEMs and French heat pump assemblers represent the most affected buyer segments, with qualification programs accelerating ahead of 2027 enforcement deadlines.
Subsystem-level procurement is consolidating vendor relationships as energy storage system developers source pre-certified isolation-leakage modules rather than discrete Hall effect sensors and signal conditioning ICs. This bundling eliminates die-level qualification overhead but compresses margin pools for component specialists. The shift is most visible in US utility-scale storage procurement, where EPC contractors now specify module-level functional safety documentation rather than component datasheets.
High-Voltage Isolation and Leakage Sensor Components Market Segmentation
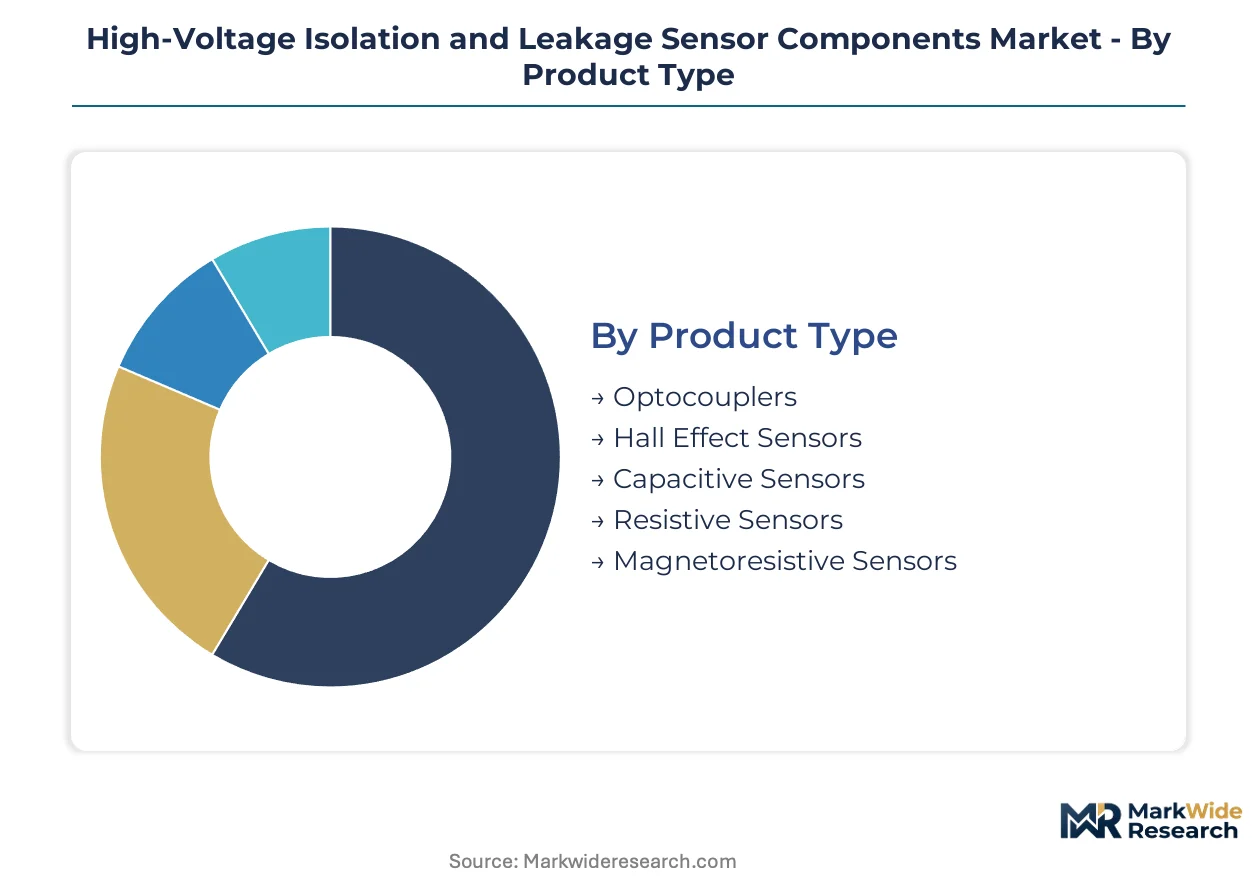
Component selection in this market hinges on dielectric withstand ratings, response latency thresholds, and certification compatibility with target end-use environments. Procurement patterns diver sharply between discrete component sourcing and pre-certified module integration, reshaping how suppliers position across each segment category.
Product Type:
Standardization dominates optocoupler and Hall effect categories, while capacitive and magnetoresistive variants command premium customization for specialized isolation barriers.
- Optocouplers:LED-to-phototransistor architectures deliver galvanic isolation up to 5 kVrms with decades of field-proven reliability. German automotive OEMs and US industrial drive manufacturers specify these for circuit protection below 1 kVrms where cost sensitivity outweighs speed requirements.
- Hall Effect Sensors:Magnetic field sensing elements measure current leakage through isolated conductors without physical electrical contact. Electric vehicle assemblers in China source these for battery management systems, though giant magnetoresistive alternatives now encroach on sub-1000V traction applications.
- Capacitive Sensors:Silicon-on-insulator fabrication enables 150 Mbps data rates across 5 kVrms barriers with 40% smaller footprints than optocoupler equivalents. European onboard charger designers lead adoption for 11-22 kW AC charging modules.
- Resistive Sensors:Voltage-divider architectures suit low-cost isolation monitoring in legacy industrial equipment with modest bandwidth demands.
- Magnetoresistive Sensors:Giant magnetoresistive elements from industrial automation suppliers displace Hall effect devices in precision current sensing applications.
Most installed capacity flows through optocouplers. Expansion is steepest in capacitive sensors.
Technology:
Analog architectures retain volume leadership in cost-constrained applications, while digital and fiber optic technologies capture share where predictive maintenance protocols demand serial diagnostic outputs.
- Analog:Continuous voltage-output signal chains dominate legacy inverter designs and price-sensitive circuit protection segments. German grid-scale storage developers specify these for SIL-2 compliant battery management systems where proven reliability trumps feature integration.
- Digital:Microcontroller-integrated diagnostics with fault location granularity enable predictive maintenance in renewable energy inverter applications. US utility-scale storage EPC contractors now require module-level functional safety documentation with serial data outputs.
- Fiber Optic:Immunity to electromagnetic interference suits high-voltage switchgear and medical imaging equipment with extreme isolation requirements.
- Magnetic:Coreless transformer architectures eliminate LED aging failure modes in high-temperature automotive underhood environments.
- Piezoelectric:Mechanical stress-to-electrical conversion supports specialized pressure-monitoring isolation in industrial process control.
- Thermal:Temperature-differential sensing enables overcurrent protection in compact power module packages.
Revenue concentrates in analog implementations. Digital architectures are gaining share fastest in new energy storage deployments.
Application:
Application selection tracks voltage platform transitions, with 400V-to-800V migrations forcing simultaneous redesign of isolation barriers and signal conditioning chains.
- Energy Storage Systems:Battery management systems require isolation sensors for cell-level voltage monitoring and high-voltage bus protection. UL 1741-SA compliance mandates certified components for every megawatt-hour of US utility-scale capacity deployed.
- Renewable Energy Inverters:Anti-islanding and rapid shutdown protection depend on isolation integrity verification across DC input and AC output domains. IEC 61508 SIL-2 requirements from Germany's Bundesnetzagentur filter non-compliant suppliers from qualified vendor lists.
- Electric Traction:Traction inverters and onboard chargers demand high-speed isolation with AEC-Q100 automotive qualification. China's GB/T standards impose additional dielectric-test regimes.
- Fault Detection:Ground-fault monitoring in solar arrays and EV charging infrastructure requires milliampere-range leakage sensitivity.
- Circuit Protection:Overcurrent and surge protection in industrial drives and power distribution equipment leverages optocoupler cost advantages.
Shipments concentrate in energy storage systems. Steepest expansion trajectory belongs to electric traction as 800V platforms proliferate.
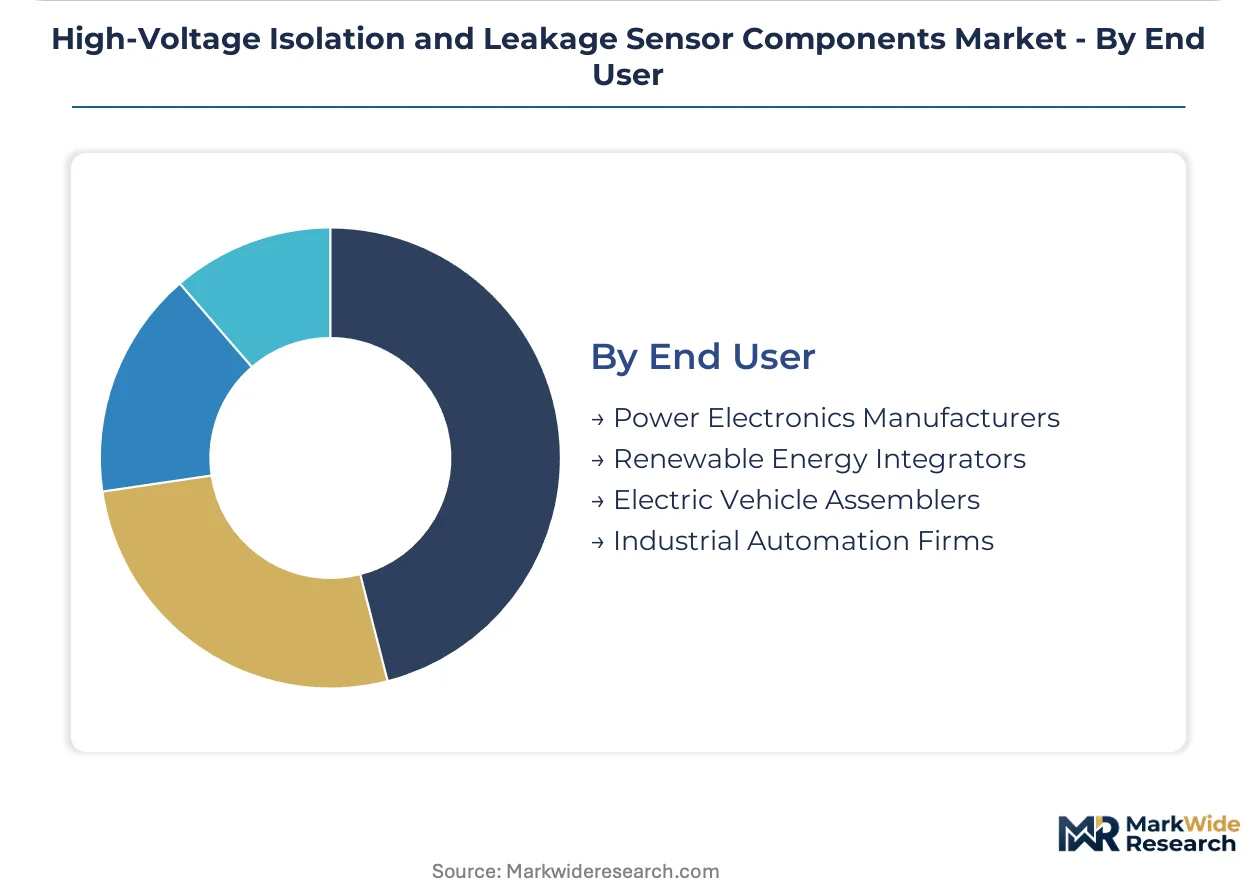
End User:
Customer type determines procurement modality, with power electronics manufacturers favoring discrete components while vehicle assemblers and energy integrators specify pre-certified subsystems.
- Power Electronics Manufacturers:Inverter and converter OEMs source discrete isolation sensors and signal conditioning ICs for custom designs. These buyers maintain internal functional safety engineering teams to manage IEC 61508 certification.
- Renewable Energy Integrators:EPC contractors and project developers specify module-level isolation-leakage documentation rather than component datasheets, compressing vendor relationships.
- Electric Vehicle Assemblers:NIO, BYD, and Tesla establish captive sensor qualification programs with die-level traceability requirements, disintermediating traditional distribution channels.
- Industrial Automation Firms:Drive and motion control suppliers integrate isolation sensors into motor control systems with varying safety integrity level requirements.
Volume flows through power electronics manufacturers. Procurement velocity is highest among electric vehicle assemblers establishing captive qualification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial isolation sensor standardization through IEC committee leadership dating to the 1980s functional safety movement. This regulatory heritage now shapes procurement protocols across automotive and grid storage applications worldwide.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg scale 800V platform deployments requiring SIL-2 certified isolation components. The KBA and Bundesnetzagentur jointly enforce IEC 61508 requirements for battery energy storage systems. Stuttgart's industrial cluster concentrates traction inverter development where magnetic isolation architectures dominate design specifications.
China
BYD, NIO, and CATL expand captive sensor qualification programs with die-level traceability mandates. GB/T standards impose additional dielectric-test regimes beyond international baselines. Shenzhen and Shanghai host the densest concentrations of onboard charger manufacturers adopting capacitive isolation for 11-22 kW modules.
United States
Utility-scale storage developers under FERC Order 841 procurement guidelines require UL 1741-SA certified components for every megawatt-hour deployed. NHTSA electrical safety protocols filter non-compliant suppliers from automotive qualified vendor lists. Texas and California project pipelines concentrate EPC contractor demand for pre-certified isolation-leakage modules.
Japan
Industrial drive manufacturers in Nagoya and Osaka maintain legacy optocoupler specifications for circuit protection below 1 kVrms. METI efficiency standards for power electronics shape component selection criteria. Kyushu's semiconductor fabrication corridor supplies silicon-on-insulator wafers enabling next-generation capacitive isolation architectures.
India
ACC battery manufacturing expansion under the PLI scheme creates qualification demand for isolation sensors in cell formation and testing equipment. CEA technical standards for grid-connected storage mandate isolation monitoring for systems above 1 MWh. Tamil Nadu and Gujarat host the primary cell manufacturing clusters where calibration facility partnerships determine vendor selection.
High-Voltage Isolation and Leakage Sensor Components Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and automotive qualification timelines. The vendor base stratifies into three tiers: integrated semiconductor conglomerates with captive fabrication, specialized magnetic sensor houses with decades of field-proven architectures, and emerging capacitive isolation specialists leveraging SOI process partnerships. Strategic moves center on subsystem-level bundling to capture module procurement shifts and direct OEM contracting programs that disintermediate traditional distribution channels.
Within the integrated semiconductor tier, Texas Instruments and Analog Devices occupy positions anchoring design-in relationships across energy storage and traction applications. Vishay Intertechnology represents the scaled manufacturing archetype for optocoupler categories where cost optimization trumps speed requirements. LEM International exemplifies the specialized magnetic sensor house with established presence in industrial current sensing domains.
| Leading Market Players |
|---|
| Bender |
| Texas Instruments |
| Analog Devices |
| Vishay Intertechnology |
| Renesas Electronics |
| LEM International |
| Honeywell |
| Sensata Technologies |
| Isabellenhütte |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation phase-down mandates for refrigerant-leakage monitoring in electrified thermal systems gate qualified supply access and premium-tier pricing power for isolation sensor vendors with capacitive moisture-detection IP. Component suppliers lacking certified architectures face exclusion from German HVAC OEM and French heat pump assembler vendor lists regardless of unit cost position.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SIL-3 certified automotive components from industrial-grade SIL-2 variants and uncertified commodity optocouplers. Price differentiation centers on IEC 61508 certification grade and volume procurement scale, with electric vehicle assemblers least sensitive and circuit protection OEMs most cost-constrained. Cost compression in standard-tier Hall effect sensors is intensifying as giant magnetoresistive substitutes gain traction in sub-1000V applications.
Supply Chain Analysis
Functional safety engineer scarcity in Germany and Japan constrains validation throughput for isolation IC design houses seeking automotive qualification. Manufacturing concentrates in Taiwan for silicon-on-insulator wafer fabrication, China for onboard charger module assembly, and Germany for traction inverter subsystem integration. The supply chain draws from 150mm SiC wafer foundries, magnetic core materials, and specialized dielectric test equipment. Single-source vulnerability runs through German and Japanese metrology equipment suppliers for partial discharge analyzers. Distribution runs through direct OEM contracting programs that disintermediate traditional component distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement is shifting toward pre-certified isolation-leakage modules with die-level traceability, favoring suppliers with captive functional safety engineering and established automotive qualified vendor list positions.
For Market Incumbents: Hedge against magnetic isolation substitution by accelerating SOI-based capacitive platform roadmaps for 800V traction applications. Defensive consolidation through backward integration into silicon-on-insulator wafer supply secures input cost position against three-foundry concentration. Certification investment in India's PLI-linked calibration facilities captures cell manufacturing expansion before local qualification requirements harden. For New Entrants and Emerging Players: Capture white-space in refrigerant-leakage sensor convergence for EU F-Gas regulated heat pump systems, where capacitive humidity IP repurposing offers fastest path to design-in. India's ACC battery manufacturing cluster under PLI incentives represents the most penetrable geography with unformed vendor relationships. Go-to-market through EPC contractor module-level procurement bypasses discrete component qualification barriers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap magnetic sensor specialists because IEC 61508 SIL-3 validation timelines filter fabless entrants regardless of technical performance, creating scarcity value for field-proven architectures. Long-term viability favors platform consolidation plays with automotive qualification depth. Watch for dielectric test equipment delivery backlogs as inflection signal for qualification velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Subsystem-Level Bundling | Pre-certified isolation-leakage modules slash EPC contractor qualification timelines for utility-scale storage. |
| SOI Process Partnership | Capacitive isolation architectures achieve 5 kVrms ratings with 40% footprint reduction versus optocouplers. |
| Direct OEM Contracting | NIO, BYD, and Tesla captive qualification programs disintermediate traditional distribution channels. |
| Functional Safety Certification Investment | IEC 61508 SIL-3 validation cycles extend 18-24 months, filtering non-compliant suppliers from automotive QVLs. |
| Local Calibration Facility Expansion | India's PLI scheme for ACC batteries creates first-mover advantage for isolation sensor vendors establishing regional presence. |
Research Methodology
Coverage spans Germany, China, the United States, Japan, and India, with primary inputs from each market's automotive OEM platform engineers, battery energy storage system EPC contractors, power electronics procurement teams, and functional safety certification specialists. Secondary validation draws from IEC standards documentation, UL certification registries, KBA type-approval filings, and Bundesnetzagentur grid interconnection requirements. Bottom-up and top-down triangulation cross-references component shipment data with end-use installation tracking across energy storage, traction inverter, and onboard charger applications.
Granularity-level modeling disaggregates volume and value across product type, technology architecture, application voltage platform, and end-user procurement modality throughout the forecast period. CAGRs derive from segment-level growth rate synthesis with cross-validation against OEM platform deployment schedules and grid-scale storage procurement pipelines. Industry-specific forecast inputs include 400V-to-800V platform transition trajectories and UL 1741-SA compliance mandate implementation timing.
Silicon carbide substrate cost volatility, functional safety certification timeline extensions, and magnetic isolation technology substitution are the dominant revision risks that could compress or extend modeled growth trajectories. Forecasts reflect assumptions about certification reciprocity stability and foundry capacity expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
Russia Non-Contact Infrared Thermometer Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Active Sensor Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Hazardous Area Sensors Market