
 Dysprosium Titanate Market | 2026-2036
Dysprosium Titanate Market Size, Share, and Industry Trends Forecast 2026-2036
Dysprosium Titanate Market Insights
Advanced solid-state synthesis is rewriting material preparation protocols for rare earth titanates, replacing energy-intensive calcination with lower-temperature microwave-assisted routes. Shin-Etsu Chemical Co., Ltd. leverages its integrated rare earth separation infrastructure in Vietnam to secure upstream dysprosium feedstock. H.C. Starck GmbH anchors European supply through specialized powder metallurgy capabilities. Lynas Rare Earths Ltd. competes via its Mount Weld concentrate and Malaysian processing asset.
Dysprosium titanate denotes a ceramic compound of dysprosium oxide and titanium dioxide, typically formulated as Dy₂Ti₂O₇ with a pyrochlore crystal structure, synthesized via solid-state reaction of constituent oxides at temperatures exceeding 1300°C to yield neutron-absorbing, thermally stable ceramics. The material serves primarily as a control rod burnable poison in nuclear reactors and as a high-permittivity dielectric in advanced electronics. Powders dominate current output volumes owing to established feedstock availability for sintered ceramic fabrication, while films represent the fastest-expanding category as chemical vapor deposition techniques mature for microelectronic integration. Energy Storage applications command widening interest as solid-state battery developers evaluate rare earth titanates for electrolyte stabilization.
The US Nuclear Regulatory Commission governs fuel cladding and control material specifications, while China's Ministry of Ecology and Environment enforces dual carbon compliance and rare earth mining quotas. REACH registration requirements in Europe constrain importer flexibility for unregistered titanate formulations. Stakeholders must monitor evolving critical minerals list revisions and reactor deployment timelines to align capacity commitments with demand signals.
Market Dynamics
China's dual carbon goals and export licensing protocols for heavy rare earths are tightening supply chains, forcing downstream processors to secure alternative feedstock routes and accelerating investment in recycling infrastructure outside Chinese borders.
Growth Catalysts
- Neodymium-iron-boron magnet thermal stability mandates:High-performance motor manufacturers in Japan's precision electronics sector are expanding dysprosium titanate procurement to meet METI-backed domestic rare earth stockpiling initiatives.
- Solid-state battery electrolyte stabilization:Energy storage developers are evaluating rare earth titanates for next-generation solid-state designs, creating pull-through demand for high-purity powders.
- Microwave-assisted synthesis maturation:Advanced solid-state preparation protocols are replacing energy-intensive calcination, lowering barrier-to-entry for regional ceramic fabricators.
Market Restraints
- Heavy rare earth supply concentration:China's Ministry of Ecology and Environment enforces mining quotas and export licensing that constrain dysprosium oxide availability for non-domestic processors.
- REACH registration friction:European importers face constrained flexibility for unregistered titanate formulations under ECHA requirements, delaying market entry timelines.
- Chemical vapor deposition equipment costs:Thin-film fabrication requires specialized CVD systems that limit scale-up for mid-cap electronics integrators.
Strategic Opportunities
- Vietnam rare earth separation infrastructure:Integrated upstream feedstock assets outside Chinese jurisdiction offer procurement diversification for Japanese and Korean magnet manufacturers.
- Control rod burnable poison reactor deployment:Nuclear regulatory approvals for advanced reactor designs in multiple jurisdictions are expanding addressable demand for neutron-absorbing ceramics.
- Malaysian processing hub expansion:Southeast Asian rare earth concentrate-to-oxide capabilities are maturing, creating regional supply alternatives for European and North American buyers.
Industry Challenges
- Pyrochlore crystal structure quality control:Achieving consistent Dy₂Ti₂O₇ phase purity across batch scales requires specialized sintering expertise that remains concentrated among established ceramic houses.
- Cross-jurisdiction certification alignment:Reconciling US Nuclear Regulatory Commission fuel cladding specifications with divergent national reactor safety standards complicates product qualification for multi-market suppliers.
- Legacy calcination asset stranded risk:Established producers face write-down pressure as microwave-assisted routes achieve technical parity at lower energy intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dysprosium Titanate Market |
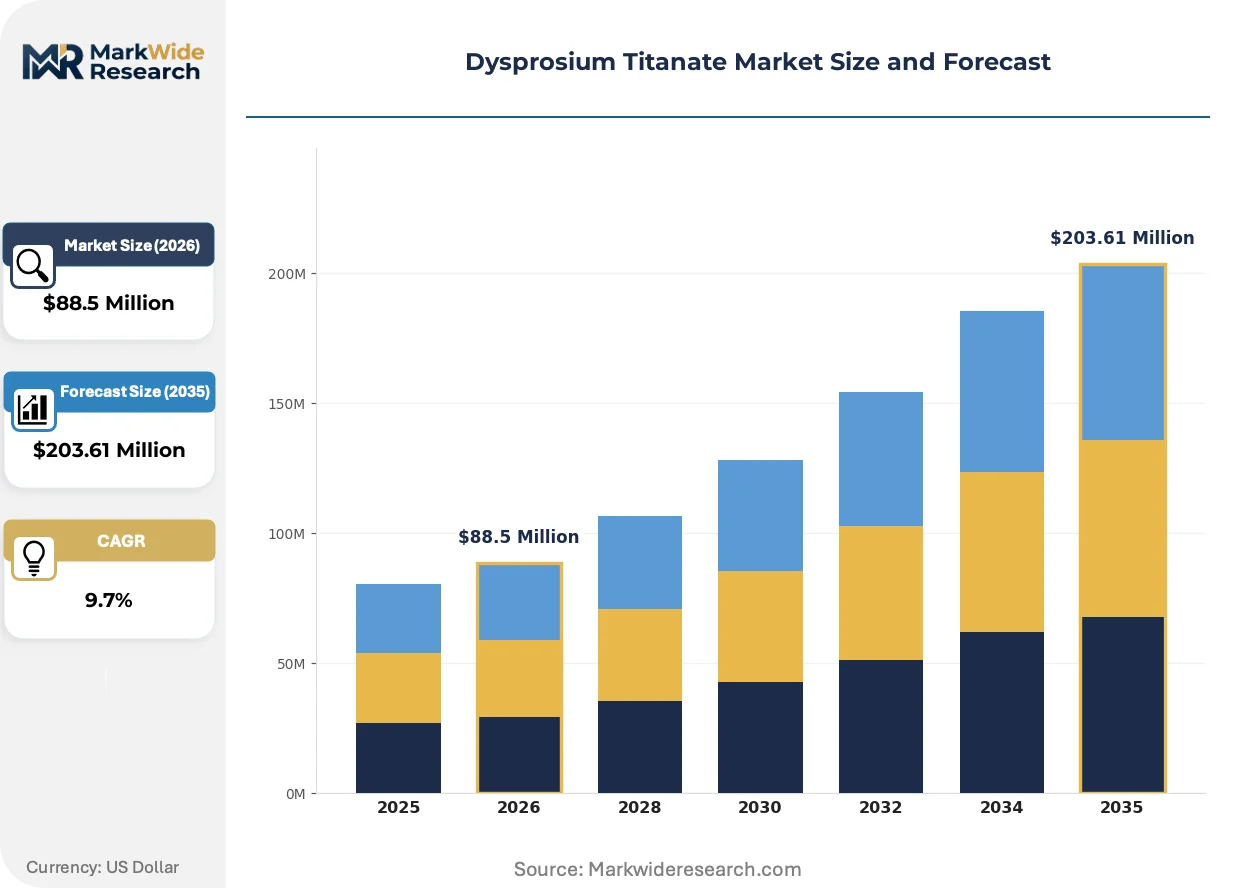
| Market Size in 2026 | $88.5 Million |
| Market Size in 2035 | $203.61 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powders, Crystals, Pellets, Films Application: Electronics, Energy Storage, Magnetic Materials, Optical Devices End User: Manufacturers, Research Institutions, Aerospace, Automotive Technology: Chemical Vapor Deposition, Solid State Synthesis, Sol-Gel Process, Microwave Synthesis |
| Companies Covered | American Elements, Shin-Etsu Chemical Co., Ltd., H.C. Starck GmbH, Nanochemazone, Lynas Rare Earths Ltd., Shenghe Resources Holding Co. Ltd, Energy Fuels, Arafura Rare Earths, China Northern Rare Earth Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dysprosium Titanate Market Trends and Innovations
Material preparation protocols and procurement patterns are undergoing simultaneous transformation, with synthesis technology advances converging with regulatory-driven supply chain restructuring to redefine competitive positioning.
Microwave-assisted solid-state synthesis is virtualizing traditional calcination-dependent production models. This lower-temperature route reduces energy input requirements by enabling direct oxide coupling without extended furnace residence. Japanese precision electronics manufacturers are adopting the technology for pilot-scale dielectric film production. The approach is virtualizing capital allocation patterns by compressing equipment footprint and permitting distributed fabrication closer to end-use clusters.
REACH registration requirements in Europe are tightening formulation flexibility for rare earth titanate importers. ECHA's evolving substance evaluation protocols are extending compliance timelines for novel ceramic compositions. Specialty chemical distributors are responding by consolidating registered product portfolios and deferring introduction of experimental titanate grades until full dossier completion.
Long-term offtake contracting is displacing spot market purchasing for high-purity dysprosium titanate powders. Nuclear fuel fabricators and advanced battery developers are locking in multi-year supply agreements directly with rare earth processors, bypassing traditional trading house intermediaries. This pattern is most pronounced in Japan and South Korea, where METI and MFDS critical mineral initiatives incentivize supply security over price optimization.
Dysprosium Titanate Market Segmentation
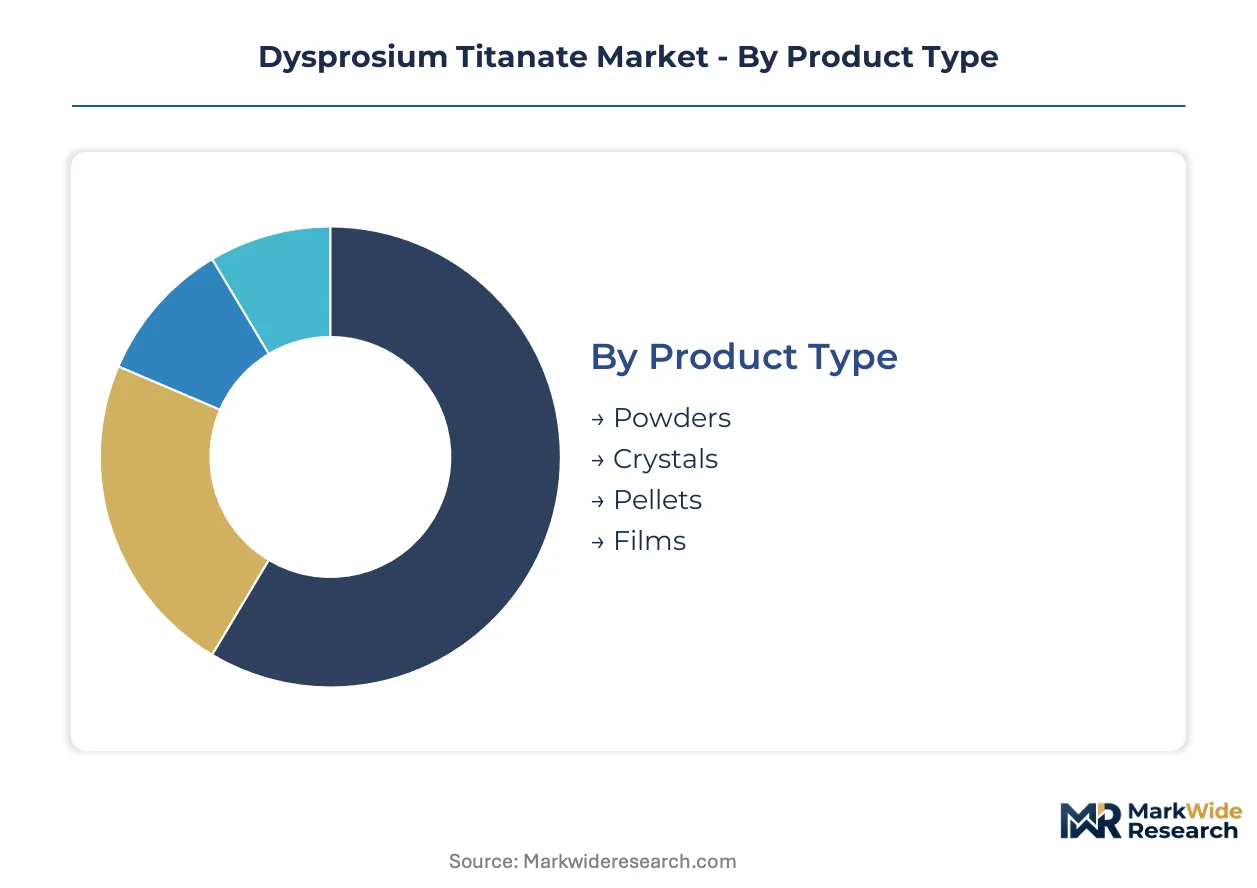
Segmentation reveals how dysprosium titanate demand fragments across incompatible technical specifications and procurement patterns. Each category carries distinct margin profiles, certification burdens, and customer concentration that reshape competitive positioning.
Product Type:
After-sales service intensity varies dramatically across physical forms, with films requiring specialized deposition support and powders demanding consistent batch certification for nuclear applications.
- Powders:Granular Dy₂Ti₂O₇ formulations serve as feedstock for sintered ceramic fabrication in control rod manufacturing. Demand concentrates among Japanese nuclear fuel fabricators seeking METI-compliant domestic stockpiles amid China's export licensing constraints.
- Films:Thin-film deposits enable high-permittivity dielectric layers in precision microelectronics. South Korean memory manufacturers and Japanese sensor producers are expanding procurement as chemical vapor deposition techniques mature for sub-micron integration.
- Crystals:Single-crystal boules target optical isolator substrates and specialized neutron detection arrays.
- Pellets:Pre-sintered cylindrical forms reduce downstream processing steps for reactor control rod assembly.
Powders hold the largest share; momentum sits with films.
Application:
Cost tier stratification separates qualification-intensive nuclear applications from price-sensitive electronics integration.
- Electronics:High-permittivity dielectric films and capacitive components leverage pyrochlore structure stability for miniaturized circuits. Japanese precision electronics clusters in Osaka and Nagoya are driving specification tightening for 5G infrastructure and automotive radar modules.
- Energy Storage:Solid-state battery developers evaluate rare earth titanates for electrolyte stabilization and interfacial passivation. Korean cell manufacturers under MFDS critical mineral initiatives are locking multi-year offtake agreements to secure supply outside Chinese jurisdiction.
- Magnetic Materials:Thermal stability additives for neodymium-iron-boron magnets improve high-temperature motor performance.
- Optical Devices:Faraday rotator substrates and magneto-optical isolators exploit the material's Verdet constant in laser systems.
Electronics commands the largest share; energy storage is climbing the fastest.
End User:
Customer type determines contract structure, with manufacturers demanding long-term supply security and research institutions tolerating spot purchasing.
- Manufacturers:Magnet producers, ceramic fabricators, and electronics integrators require consistent high-volume supply with batch certification. Japanese and Korean manufacturers are bypassing trading houses to contract directly with rare earth processors under government-backed critical mineral programs.
- Research Institutions:National laboratories and university consortia drive specification innovation for next-generation reactor designs and quantum device architectures. US Department of Energy facilities and Japan Atomic Energy Agency programs are expanding procurement for advanced neutron spectroscopy.
- Aerospace:Satellite radiation shielding and avionics thermal management applications impose stringent qualification protocols.
- Automotive:Traction motor magnet suppliers and solid-state battery developers are emerging as volume purchasers.
Manufacturers hold the largest share; momentum sits with automotive.
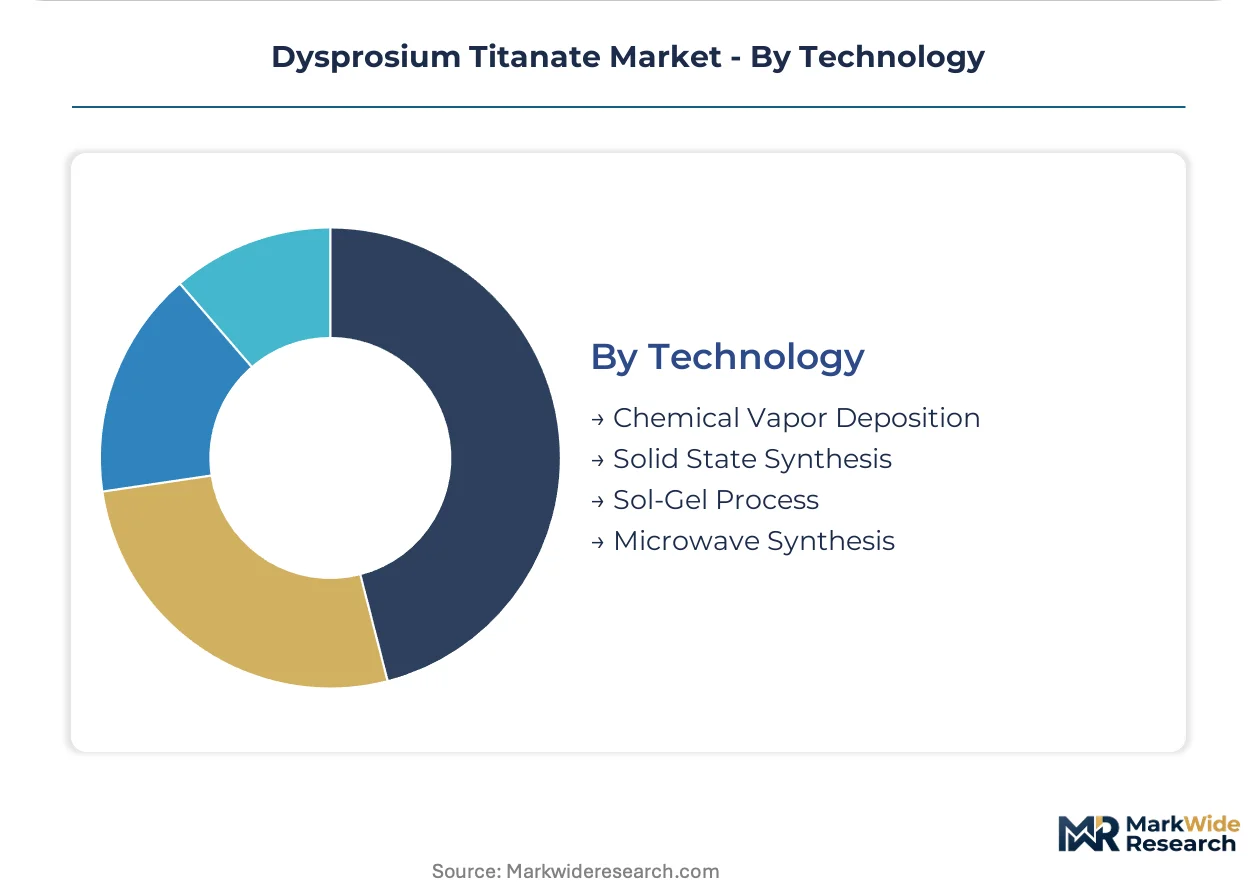
Technology:
Process maturity and capital intensity fragment the supplier base across synthesis routes.
- Solid State Synthesis:Conventional oxide calcination at temperatures exceeding 1300°C remains the baseline for nuclear-grade powder production. Established ceramic houses in Japan and Europe maintain capacity, though energy costs are eroding margin structures.
- Microwave Synthesis:Lower-temperature direct oxide coupling reduces furnace residence time and energy input. Japanese precision electronics manufacturers are piloting distributed fabrication closer to end-use clusters, compressing equipment footprint and permitting regional supply.
- Chemical Vapor Deposition:Thin-film deposition for microelectronic integration requires specialized reactor systems.
- Sol-Gel Process:Wet chemical routes enable precise stoichiometry control for optical-grade materials.
Solid state synthesis holds the largest share; microwave synthesis is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese precision electronics manufacturers and Korean battery developers dominate procurement, while Chinese mining quotas and export licensing reshape upstream availability. Regulatory divergence across jurisdictions is fragmenting supply chain configurations.
Japan
METI-backed critical mineral stockpiling drives dysprosium titanate procurement for neodymium-iron-boron magnet thermal stabilization. The Ministry of Economy, Trade and Industry mandates domestic rare earth reserves for strategic industries. Osaka and Nagoya electronics clusters are expanding dielectric film specifications for 5G infrastructure modules.
China
Dual carbon goals and heavy rare earth export licensing constrain dysprosium oxide availability for non-domestic processors. The Ministry of Ecology and Environment enforces mining quotas that tighten supply chains. Jiangxi and Inner Mongolia rare earth separation facilities are prioritizing domestic magnet manufacturer allocation.
South Korea
MFDS critical mineral initiatives incentivize supply security for solid-state battery electrolyte development. The Ministry of Food and Drug Safety coordinates with trade authorities to reduce Chinese feedstock dependence. Seoul Capital Area cell manufacturers are locking multi-year offtake agreements with Malaysian processors.
United States
Department of Energy reactor deployment timelines expand demand for neutron-absorbing control rod ceramics. The Nuclear Regulatory Commission governs fuel cladding and burnable poison specifications. Texas and Tennessee rare earth processing ventures are advancing separation capabilities outside Chinese jurisdiction.
Germany
REACH registration requirements constrain importer flexibility for unregistered titanate formulations. The European Chemicals Agency extends compliance timelines for novel ceramic compositions. Bavarian specialty chemical distributors are consolidating registered product portfolios to maintain market access.
Dysprosium Titanate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure anchored by integrated rare earth processors and regional ceramic fabricators. The vendor base separates into upstream concentrate-to-oxide operators, midstream powder metallurgy houses, and downstream application specialists. Strategic archetypes include vertically integrated miners, technology-licensing chemical groups, and niche synthesis boutiques. Capacity expansion outside Chinese jurisdiction and microwave-assisted route licensing represent the dominant competitive moves.
Among integrated rare earth processors, Shin-Etsu Chemical Co., Ltd. exemplifies the upstream-anchored archetype, while H.C. Starck GmbH occupies a position within European powder metallurgy specialization. Lynas Rare Earths Ltd. represents the non-Chinese concentrate-to-oxide model. These three entities anchor distinct competitive vectors: Japanese integrated separation, German ceramic fabrication, and Australian-Malaysian geographic diversification.
| Leading Market Players |
|---|
| American Elements |
| Shin-Etsu Chemical Co., Ltd. |
| H.C. Starck GmbH |
| Nanochemazone |
| Lynas Rare Earths Ltd. |
| Shenghe Resources Holding Co. Ltd |
| Energy Fuels |
| Arafura Rare Earths |
| China Northern Rare Earth Group |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Rotterdam container freight corridors transmit cost volatility directly into dysprosium titanate landed pricing, amplifying the leverage of Chinese rare earth processors while forcing Japanese and Korean buyers to absorb premium differentials for non-Chinese feedstock. This logistics-cost overlay compounds with METI and MFDS stockpiling mandates to stratify procurement economics across security-conscious and price-sensitive buyer tiers.
Pricing Analysis
Long-term offtake contracts indexed to Shanghai Metals Market dysprosium oxide quotations dominate nuclear-grade powder transactions, insulating Japanese fuel fabricators from spot volatility while locking in volume commitments. Price differentiation separates METI-compliant certified batches from standard commercial grades, with after-sales technical support bundled into premium tiers. Cost compression in standard-grade powders is intensifying as Vietnamese separation capacity expands, though spot buyers remain exposed to Chinese export licensing delays. Research institutions exhibit highest price sensitivity due to grant-funded procurement cycles, while automotive traction motor suppliers prioritize supply security over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for non-aligned processors. Upstream concentration rests on Chinese Jiangxi and Inner Mongolia mining jurisdictions, Vietnamese separation infrastructure, and Malaysian concentrate-to-oxide capabilities. Dysprosium oxide feedstock, titanium dioxide precursor, and specialized sintering furnaces constitute critical input dependencies. Distribution runs through direct processor-to-manufacturer contracting, displacing traditional rare earth trading houses as Japanese and Korean buyers seek supply chain transparency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against non-rare-earth magnet technologies and alternative neutron-absorbing ceramics. Incumbents must neutralize substitute threats through supply security investments and performance differentiation.
For Market Incumbents: Insulate core reactor ceramics and magnet additive positions by securing captive dysprosium feedstock through Vietnamese or Malaysian upstream assets, while accelerating microwave synthesis licensing to neutralize energy-cost disadvantages against emerging regional fabricators. METI and MFDS stockpiling programs offer offtake certainty that can anchor capacity expansion financing. For New Entrants and Emerging Players: European specialty chemical distribution channels present underpenetration opportunities given REACH registration barriers that constrain incumbent formulation flexibility. Target Bavarian and Benelux industrial ceramic houses seeking qualified alternative suppliers for dielectric film feedstock, entering through toll-processing arrangements that bypass capital-intensive separation investments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded rare earth titanate divisions lacking critical mineral strategy alignment. Five-to-ten-year viability hinges on successful geographic diversification outside Chinese jurisdiction. Monitor US Nuclear Regulatory Commission advanced reactor design certifications as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Separation | Vietnamese and Malaysian upstream assets reduce Chinese feedstock dependence for Japanese magnet manufacturers. |
| Microwave Synthesis Technology Licensing | Lower-energy production routes compress equipment footprint and enable distributed fabrication near Osaka-Nagoya electronics clusters. |
| Long-term Supply Agreement with Nuclear Fabricators | METI-backed stockpiling programs provide offtake certainty for multi-year capacity commitments. |
| REACH Registration Dossier Completion | ECHA compliance enables European market access for novel titanate formulations beyond legacy product portfolios. |
| Joint Venture with Solid-State Battery Developers | Korean MFDS critical mineral initiatives create pull-through demand for high-purity electrolyte stabilization materials. |
Research Methodology
A standing panel of nuclear fuel procurement officers, rare earth separation plant managers, ceramic fabrication technical directors, and solid-state battery R&D leads provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with downstream OEM procurement teams and channel distribution partners, validated against customs trade data, SEC filings from listed rare earth processors, IEA nuclear deployment tracking, and ECHA registration databases. Bottom-up volume build-ups from application-specific consumption rates were triangulated against top-down market sizing from concentrate production and trade flow analysis.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling demand trajectories under varying reactor deployment timelines and magnet thermal stability specification tightening. Segmentation dimensions included physical form, application end-use, synthesis technology route, and geographic regulatory cluster. CAGRs were derived from slope analysis of normalized adoption curves fitted to historical rare earth titanate consumption patterns, with nuclear regulatory approval schedules and battery electrolyte development milestones serving as industry-specific inflection inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Australian-Malaysian concentrate operators or breakthrough non-rare-earth magnet formulations would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
EV Capacitor Films Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Global Thermal Paste Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Semiconductor Silicon Wafer Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Asia Pacific Graphene Market