
 High Purity Germanium (Ge) Market | 2026-2036
High Purity Germanium (Ge) Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Germanium (Ge) Market Analysis
China is rewriting supply dynamics for high purity germanium through state-directed capacity expansions in Yunnan and Inner Mongolia. Teck Resources leverages integrated zinc-germanium refining to sustain concentrate feedstock security across North American operations. PPM Pure Metals GmbH anchors European supply with specialized zone-refining capabilities for semiconductor-grade material. Umicore competes through closed-loop recycling and urban mining of germanium from end-of-life electronics.
High purity germanium designates material exceeding 99.9999% elemental purity, produced through zone refining or chemical vapor transport to eliminate electrically active impurities below parts-per-billion thresholds; this extreme purity enables single-crystal growth for photodiodes, gamma-ray spectrometers, and infrared transparent windows. Wafer segments for radiation detectors command premium positioning due to nuclear safeguards certification requirements and multi-month crystal growth cycles. Powder and granule formats for optical coating feedstocks occupy faster-expanding niches as thermal imaging deployment broadens beyond military into automotive and industrial predictive maintenance. Electronics applications for substrate material remain structurally mature, with pricing power concentrated among ingot producers qualified to epitaxial device specifications.
China's MIIT governs germanium export through dual-use licensing under the country's critical minerals framework, while U.S. Department of Commerce Bureau of Industry and Security restrictions limit certain advanced detector technology transfers. REACH registration requirements in Europe compel detailed supply chain disclosure for germanium compounds used in optical coatings and electronics manufacturing. Stakeholders must monitor quota announcements from Beijing and alternative refining investments in Canada and Belgium to anticipate feedstock availability shifts.
Market Dynamics
China's MIIT export licensing regime for germanium concentrates is restructuring procurement patterns across defense and semiconductor supply chains, forcing buyers to secure alternative refining capacity in Canada and Belgium.
Growth Catalysts
- Infrared Optics Expansion:Defense ministries in the United States and Germany are accelerating thermal imaging deployments for night-vision systems and border surveillance, pulling detector-grade germanium through qualified crystal growers.
- Dual Carbon Goals:China's state-directed decarbonization mandates are redirecting domestic germanium output toward photovoltaic and battery applications, tightening export availability and elevating prices for international buyers.
- Nuclear Safeguards Programs:IAEA monitoring protocols and national laboratory procurement in the United States are sustaining demand for ultra-pure germanium crystals used in gamma-ray spectrometry.
Market Restraints
- Feedstock Concentration:Over 60% of global germanium-bearing zinc concentrates originate from Chinese smelters, creating single-source vulnerability for Western refiners.
- Zone-Refining Bottleneck:Semiconductor-grade material requires 20-30 sequential zone-refining passes, limiting output to a handful of specialized facilities in Germany and Japan.
- Arsenic Substitution:Silicon-germanium alloys and indium gallium arsenide compounds are displacing pure germanium in select photodetector applications where spectral range requirements permit.
Strategic Opportunities
- Automotive Thermal Imaging:German OEMs and Tier-1 suppliers are integrating long-wave infrared cameras into advanced driver-assistance systems, opening volume demand beyond military procurement.
- Urban Mining Infrastructure:The EU Critical Raw Materials Act is incentivizing closed-loop recycling of germanium from end-of-life fiber optics and infrared optics, reducing virgin concentrate dependence.
- Epitaxial Substrate Qualification:Power electronics manufacturers in Japan are qualifying germanium-on-silicon templates for high-efficiency transistor architectures, creating premium wafer demand.
Industry Challenges
- Crystal Growth Expertise Scarcity:Czochralski and Bridgman growth of dislocation-free germanium ingots requires operators trained in temperature gradient control and seed crystal orientation, skills concentrated at legacy nuclear instrumentation programs.
- Multi-Month Certification Cycles:Detector-grade material must demonstrate impurity profiles below 10 parts-per-billion across electrically active species, extending qualification timelines for new suppliers seeking entry into national laboratory supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Germanium (Ge) Market |
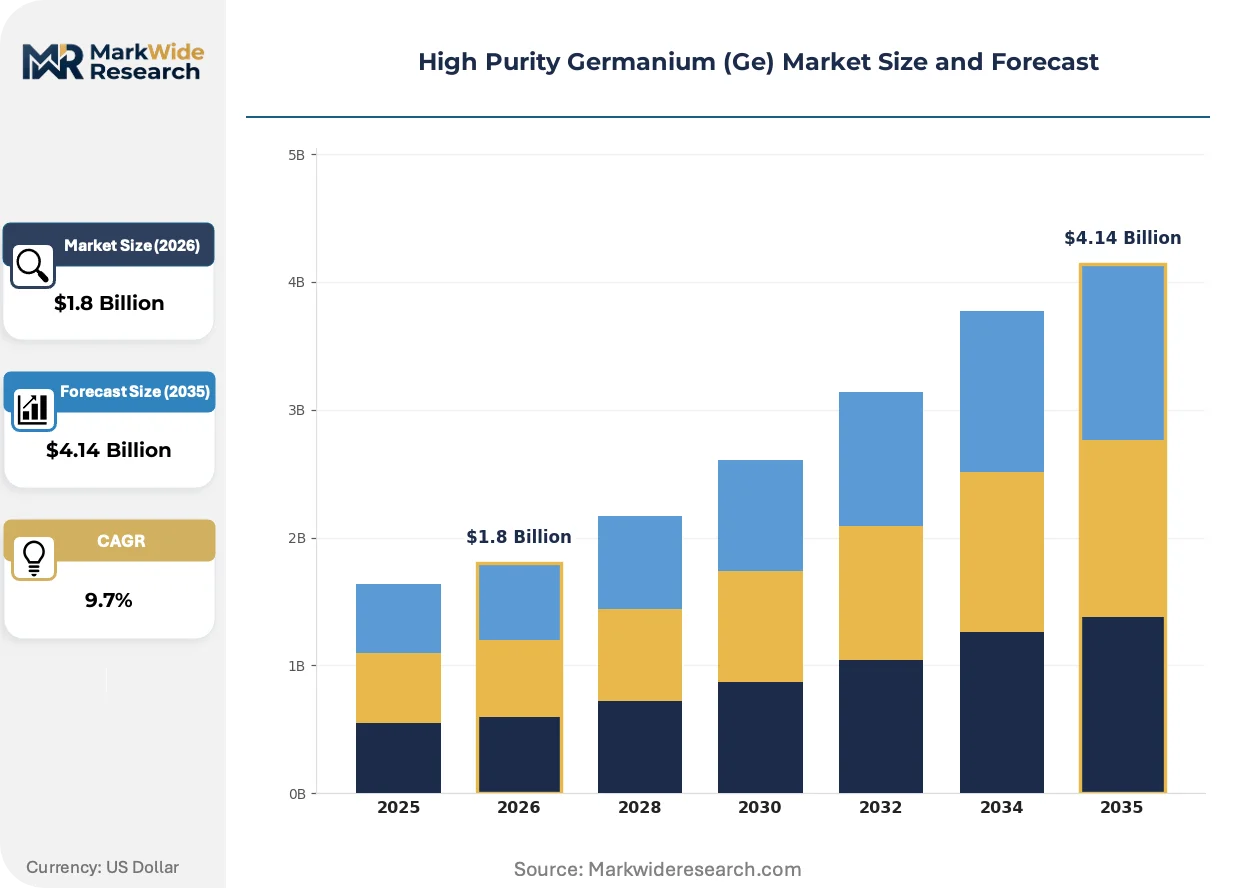
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ingot, Wafer, Powder, Granules Application: Electronics, Optics, Detectors, Renewable Energy End User: Aerospace, Telecommunications, Industrial Equipment, Research Labs Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Vital Materials, China Germanium, Teck Resources, PPM Pure Metals GmbH, AXT, 5N Plus, Yunnan Chihong Zinc & Germanium, Indium Corporation, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Germanium (Ge) Market Emerging Trajectories
Computational materials science and supply chain traceability platforms are compressing development cycles and reconfiguring how buyers verify provenance and purity claims across multi-tier supplier networks.
Zone-refining simulation software is digitizing process optimization for high purity germanium producers. Teck Resources and PPM Pure Metals GmbH are deploying machine-learning models to predict impurity segregation coefficients and reduce thermal cycle iterations. This capability is compressing lead times for semiconductor-grade material while tightening batch-to-batch consistency specifications demanded by epitaxial device manufacturers.
REACH registration requirements in Europe are mandating granular supply chain disclosure for germanium compounds used in optical coatings and electronics manufacturing. ECHA's expanded substance evaluation protocols are forcing importers to document refining origins and by-product recovery rates. Detector-grade crystal suppliers serving CERN and IAEA programs are responding by securing third-party audited chain-of-custody certifications from concentrate through final wafer.
Defense procurement offices in the United States are consolidating qualified supplier lists and extending multi-year offtake agreements to secure strategic germanium reserves. National laboratory buyers are shifting from spot-market purchasing toward inventory pre-positioning contracts with crystal growers holding active DOE/NNSA certifications. This behavioral change is most visible in the gamma-ray spectrometer segment, where Oak Ridge and Pacific Northwest National Laboratory are locking in three-year supply commitments.
High Purity Germanium (Ge) Market Segmentation
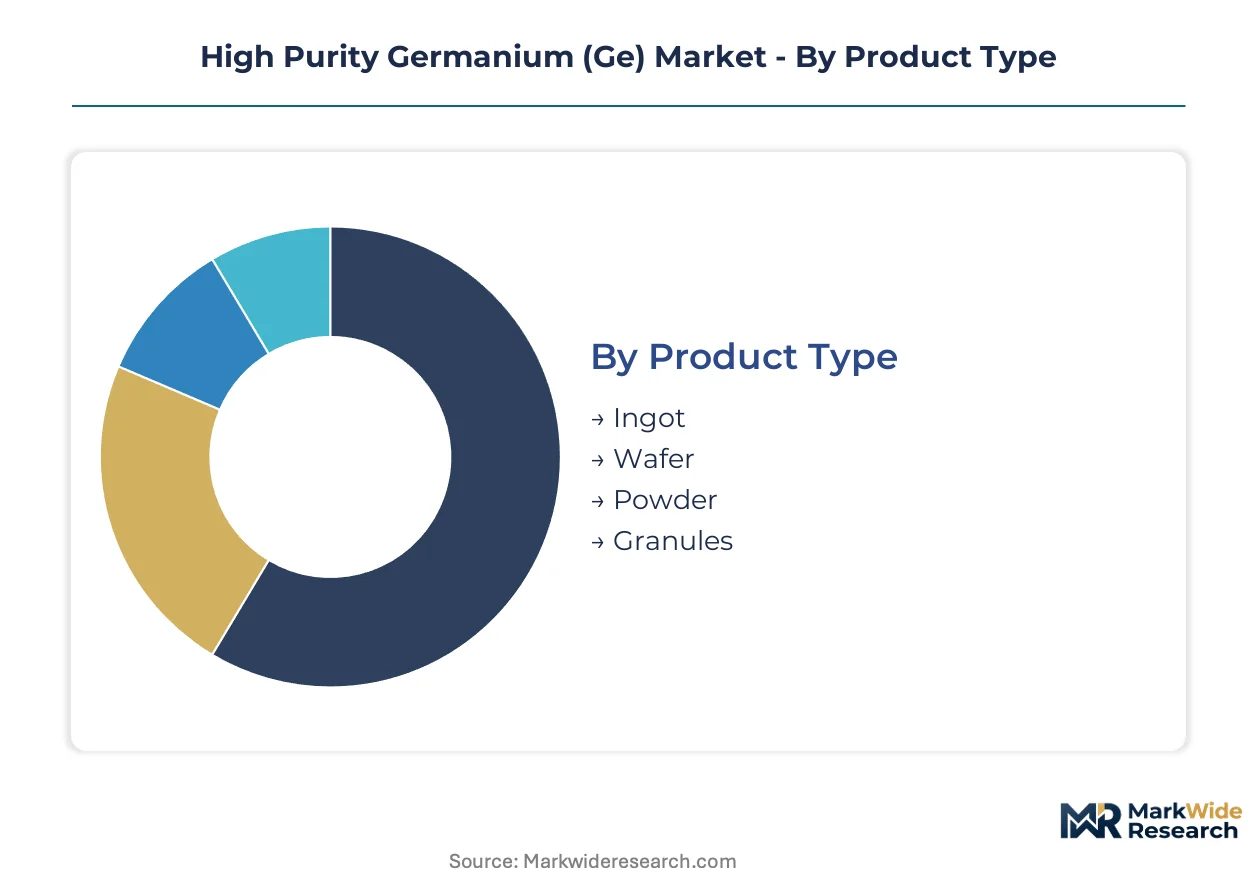
Segmentation in high purity germanium markets reveals stark divergences in production cycles, certification burdens, and margin structures. Crystal growth formats demand multi-month lead times while powder feedstocks turn inventory rapidly.
Product Type:
Cycle times stretch from days for powder batches to quarters for detector-grade ingots, compressing working capital efficiency at the refined end of the spectrum.
- Ingot:Monocrystalline or polycrystalline bars produced via Czochralski or Bridgman growth, requiring 20-30 zone-refining passes to reach semiconductor-grade purity. National laboratories in the United States and Germany anchor procurement through multi-year qualification programs, with Oak Ridge and Pacific Northwest National Laboratory pre-positioning three-year supply commitments.
- Wafer:Sliced substrates for epitaxial device manufacturing and radiation detector fabrication, commanding premium positioning due to nuclear safeguards certification requirements. Japanese power electronics manufacturers are qualifying germanium-on-silicon templates for high-efficiency transistor architectures, creating specialized demand.
- Powder:Fine particulate feedstock for optical coating deposition and chemical synthesis, produced through hydrometallurgical reduction or mechanical comminution of ingot material.
- Granules:Pelletized form factors for thermal evaporation sources and sputtering targets, serving infrared optics manufacturers requiring controlled feed rates.
Ingot formats anchor the volume base while powder gains share at the steepest rate as coating applications broaden beyond defense into automotive thermal imaging.
Application:
Margin structures invert across this dimension, with optics and detectors commanding certification premiums while electronics substrates compete on price.
- Electronics:Substrate material for discrete devices and integrated circuits, structurally mature with pricing power concentrated among ingot producers qualified to epitaxial specifications. Silicon-germanium alloys are displacing pure germanium in select photodetector applications.
- Optics:Infrared-transparent windows and lenses for thermal imaging systems, spanning defense night-vision, border surveillance, and emerging automotive ADAS integration. German OEMs and Tier-1 suppliers are driving volume expansion beyond traditional military procurement.
- Detectors:Gamma-ray spectrometers for nuclear safeguards and astrophysics instrumentation, requiring impurity profiles below 10 parts-per-billion across electrically active species. IAEA monitoring protocols sustain demand for ultra-pure crystals.
- Renewable Energy:Concentrator photovoltaic substrates and battery research applications, absorbing redirected Chinese domestic output under dual carbon mandates.
Electronics maintains the largest revenue footprint while optics expands most quickly as thermal imaging deployment accelerates across civilian sectors.
End User:
Procurement sophistication varies sharply, with research labs demanding chain-of-custody documentation and industrial buyers prioritizing volume pricing.
- Aerospace:Satellite-mounted infrared sensors and radiation-hardened electronics, requiring ESA and NASA qualification protocols. Defense ministries in Germany and the United States consolidate qualified supplier lists for strategic reserve positioning.
- Telecommunications:Fiber optic amplifiers and high-speed photodetectors, with closed-loop recycling of end-of-life components gaining traction under EU Critical Raw Materials Act incentives.
- Industrial Equipment:Predictive maintenance thermal cameras and process control sensors, representing the fastest-climbing demand category as manufacturing digitization spreads.
- Research Labs:CERN particle physics detectors and national laboratory gamma-ray spectrometry programs, mandating third-party audited certifications from concentrate through final wafer.
Aerospace commands the highest purity premiums while industrial equipment posts the steepest expansion trajectory as predictive maintenance adoption broadens.
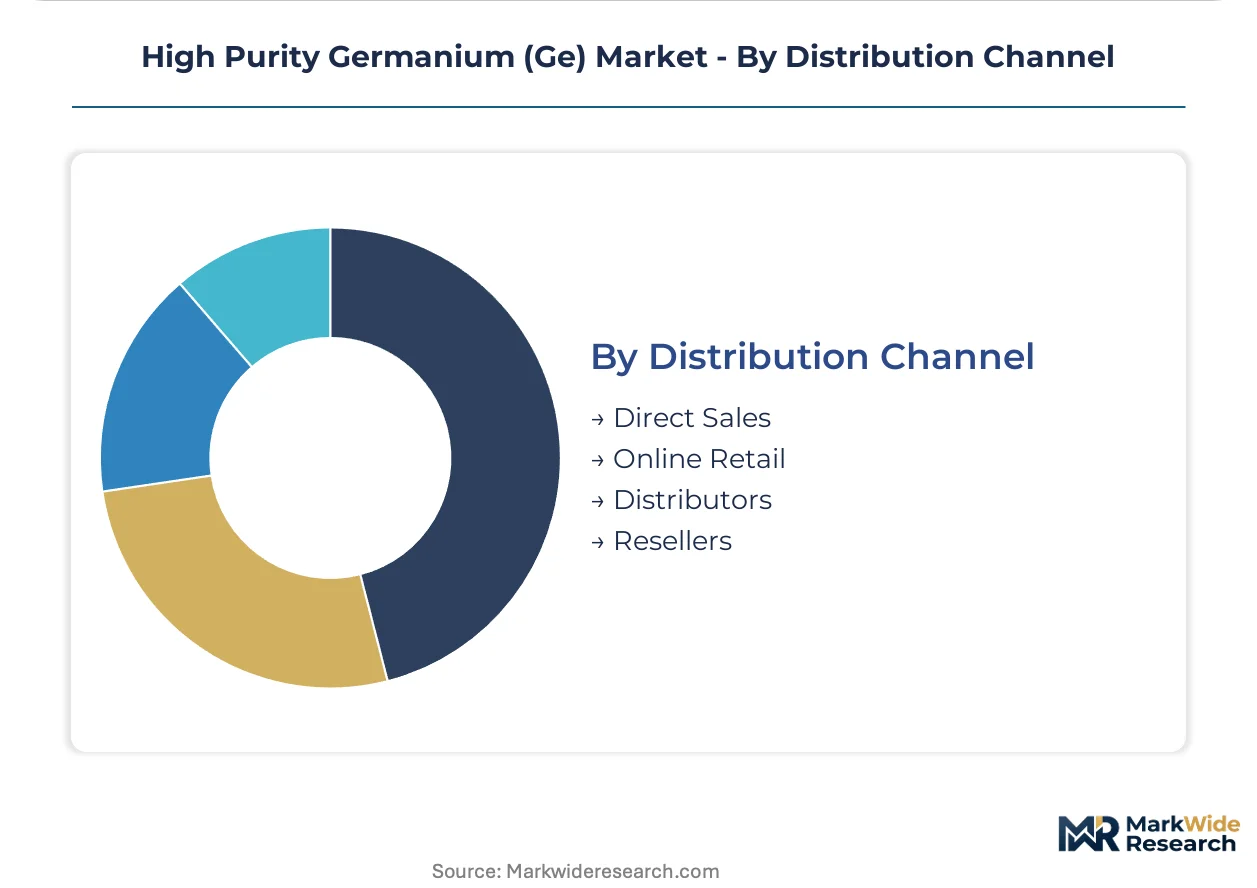
Distribution Channel:
Channel selection correlates with batch size and technical support requirements, fragmenting further at the specification-intensive end.
- Direct Sales:Long-term offtake agreements between refiners and qualified crystal growers, dominating detector-grade material flows. Teck Resources and PPM Pure Metals GmbH leverage direct relationships to secure concentrate feedstock security.
- Distributors:Specialized chemical and materials distributors serving mid-volume optical coating houses and electronics manufacturers, bridging geographic gaps between German refining capacity and Asian device fabrication.
- Online Retail:Catalog sales of standard-purity granules and powder for research quantities and prototype development, limited by REACH registration disclosure requirements.
- Resellers:Secondary market participants trading excess inventory and spot material, concentrated in Asian hubs handling Chinese export-licensed concentrates.
Direct sales capture the value concentration while distributors gain ground fastest as mid-tier optics manufacturers seek technical support integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese state-directed capacity expansions in Yunnan and Inner Mongolia dominate concentrate supply. Western refiners in Canada and Belgium scramble to secure alternative feedstock as Beijing tightens export licensing under MIIT protocols.
United States
National laboratory procurement at Oak Ridge and Pacific Northwest National Laboratory sustains detector-grade crystal demand. The Department of Commerce Bureau of Industry and Security restricts advanced detector technology transfers to safeguard nuclear safeguards capabilities. Domestic crystal growers concentrate in the Tennessee Valley and Pacific Northwest corridors, locking in three-year supply commitments with qualified refiners.
Germany
PPM Pure Metals GmbH anchors European zone-refining capacity for semiconductor-grade material. ECHA's REACH registration protocols mandate granular supply chain disclosure for germanium compounds entering optical coating applications. The Freiberg industrial cluster in Saxony hosts specialized crystal growth operations serving CERN particle physics detector programs with third-party audited chain-of-custody certifications.
China
Dual carbon mandates redirect domestic germanium output toward photovoltaic and battery applications, tightening international export availability. MIIT governs concentrate shipments through dual-use licensing under the critical minerals framework. State-directed expansions in Yunnan province and Inner Mongolia concentrate smelting capacity, with Yunnan Chihong Zinc & Germanium representing integrated zinc-germanium refining operations.
Belgium
Umicore competes through closed-loop recycling and urban mining of end-of-life electronics containing germanium. The EU Critical Raw Materials Act incentivizes feedstock recovery from fiber optic waste streams. Hoboken refining operations specialize in by-product recovery from complex secondary materials, reducing Western dependence on Chinese virgin concentrate.
Canada
Teck Resources leverages integrated zinc-germanium refining at Trail, British Columbia to sustain North American concentrate feedstock security. Federal critical minerals strategy prioritizes domestic germanium recovery from zinc smelter residues. The Kootenay region anchors primary production, with hydrometallurgical circuits optimized for germanium separation from zinc processing streams.
High Purity Germanium (Ge) Market Vendor Landscape
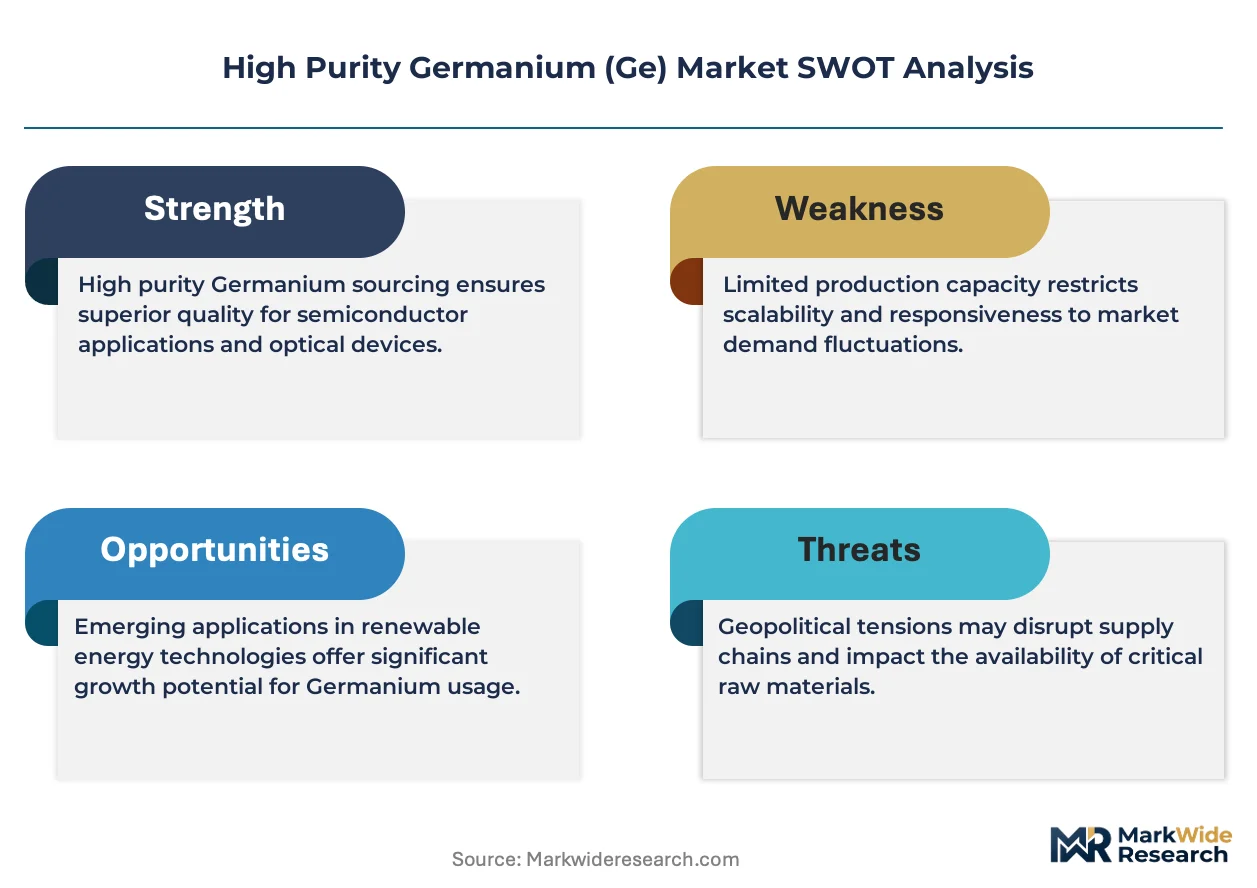
Platform integrators command the system tier; component specialists sit upstream with zone-refining and crystal growth capabilities. The vendor base stratifies across three tiers: state-backed Chinese smelters controlling concentrate supply, Western refiners with zone-refining expertise, and specialized crystal growers holding national laboratory qualifications. Archetypes include integrated mining-metals conglomerates, pure-play zone-refining specialists, and closed-loop recyclers. Capacity expansion in Southeast Asia and strategic partnerships between refiners and defense contractors dominate competitive moves.
Among integrated resource companies, Teck Resources represents the mining-metals conglomerate archetype with captive zinc-germanium feedstock integration. PPM Pure Metals GmbH and Umicore exemplify divergent Western strategies: the German zone-refining specialist versus the Belgian closed-loop recycler. Vital Materials and China Germanium occupy positions within the state-influenced concentrate supply tier, reflecting Beijing's industrial policy coordination of critical mineral output.
| Leading Market Players |
|---|
| Vital Materials |
| China Germanium |
| Teck Resources |
| PPM Pure Metals GmbH |
| AXT |
| 5N Plus |
| Yunnan Chihong Zinc & Germanium |
| Indium Corporation |
| Umicore |
| Others |
Supply Flow & Price Mechanics
The Vancouver-Yokohama container corridor carries germanium concentrates and refined material between Pacific Rim smelters and Asian crystal growers, with freight rate volatility amplifying cost differentials between Chinese state-directed output and Western zone-refined alternatives. This logistics backbone connects feedstock concentration in Yunnan province to detector-grade qualification facilities in Japan and Germany, embedding transport costs into the premium commanded by non-Chinese material.
Pricing Analysis
MIIT export licensing dictates the pricing tier structure across the high purity germanium market, separating licensed Chinese concentrate from Western-refined alternatives. Three-tier pricing stratifies across detector-grade certified, semiconductor-grade standard, and optical-grade economy levels, with certification burden and crystal growth cycle length as primary differentiation drivers. Cost compression in the standard tier intensifies because silicon-germanium alloys displace pure germanium in consumer photodetectors. Research laboratories demonstrate least price sensitivity due to nuclear safeguards mandates, while automotive thermal imaging suppliers exhibit greatest elasticity as they scale beyond defense procurement volumes.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for Western refiners seeking concentrate security. Geographic supply concentrates in China, Canada, and Belgium, with over sixty percent of germanium-bearing zinc concentrates originating from Chinese smelters. Raw material dependencies rest on zinc processing residues, coal fly ash, and end-of-life electronics recovery. Single-source vulnerability from Chinese state-directed output creates strategic exposure for detector-grade crystal growers. Distribution runs through direct long-term offtake agreements for qualified material, with specialized distributors bridging mid-volume optical coating demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate silicon-germanium alloy substitution in consumer photodetector applications, defending germanium's position in defense and nuclear instrumentation segments where spectral performance requirements resist displacement.
For Market Incumbents: Pre-empt qualification bottlenecks by securing three-year supply commitments with national laboratory buyers before alternative substrate technologies mature. Backward integration into zinc-germanium refining secures concentrate feedstock against MIIT licensing disruptions. Crystal growth expertise scarcity at legacy nuclear instrumentation programs represents a defendable moat if incumbents lock in operator training pipelines. For New Entrants and Emerging Players: Canadian and Belgian refining capacity expansion offers geographic underpenetration for zone-refining specialists seeking non-Chinese feedstock positioning. Automotive thermal imaging for advanced driver-assistance systems presents the most penetrable volume segment, with German OEM qualification protocols serving as the primary go-to-market pathway. Urban mining infrastructure under EU Critical Raw Materials Act incentives creates secondary feedstock access without virgin concentrate dependence. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors closed-loop recyclers with urban mining capabilities over pure-play refiners exposed to concentrate price volatility. Long-term viability across the next decade hinges on germanium's irreplaceability in gamma-ray spectrometry and long-wave infrared optics where alloy substitutes fail. The signal to watch is IAEA procurement volume shifts toward inventory pre-positioning contracts versus spot-market purchasing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Refining | Teck Resources demonstrates captive concentrate security through Trail, British Columbia operations. |
| Zone-Refining Capacity Expansion | PPM Pure Metals GmbH anchors European semiconductor-grade output against Chinese licensing constraints. |
| Closed-Loop Recycling Infrastructure | Umicore's Hoboken operations reduce Western dependence on Chinese virgin concentrate via urban mining. |
| National Laboratory Qualification | Oak Ridge and Pacific Northwest National Laboratory certifications lock in three-year supply commitments. |
| Automotive ADAS Partnership | German Tier-1 supplier integration opens volume demand beyond traditional military procurement channels. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from integrated zinc producers, ECHA REACH registration databases, and IAEA procurement disclosures. Crystal growth operators, national laboratory procurement officers, zinc smelter technical directors, and optical coating house supply chain managers provided operational perspective. Bottom-up unit economics from zone-refining throughput and top-down market sizing from end-use application volumes were triangulated against disclosed capacity figures from Teck Resources and Yunnan Chihong Zinc & Germanium.
Forecast inputs include detector-grade crystal growth cycle duration, MIIT export licensing quota announcements, and automotive thermal imaging adoption curves across the projection horizon. Segmentation dimensions modeled encompass product format, application category, end-user industry, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints. Industry-specific forecast inputs incorporate IAEA nuclear safeguards program funding trajectories and EU Critical Raw Materials Act recycling incentive deployment.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese smelters or silicon-germanium alloy developers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Graphene Oxide (GO) Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Glass Wafer Market