
 Global Merchant Embedded Computing Market | 2026-2036
Global Merchant Embedded Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Merchant Embedded Computing Market Outlook
Taiwan is tilting toward expanded foundry and advanced packaging capacity for embedded computing substrates. Advantech leverages its vertical integration across industrial IoT platforms to sustain design-in relationships with automation OEMs. Kontron anchors European supply security through manufacturing scale in Germany and extended service networks across industrial verticals.
Merchant embedded computing refers to standardized, commercially available computing platforms designed for integration into third-party equipment, typically operating across temperature ranges of -40°C to 85°C with fanless or ruggedized enclosures for deterministic control in industrial, medical, and transportation environments. ARM-based system-on-chip solutions are capturing the fastest expansion as power-constrained edge devices proliferate, while x86 industrial PCs retain the dominant margin pool in high-performance automation workloads. FPGA technology occupies specialized niches in signal processing and adaptive computing where DSP architectures compete on latency-sensitive medical imaging and radar applications.
The EU AI Act and CE marking under MDR shape product certification burdens for medical device integrators, while FCC Part 15 and FDA 21 CFR Part 820 govern electromagnetic compatibility and quality systems for US-bound shipments. REACH and RoHS compliance from ECHA constrain material selection for board-level components across European supply chains. Stakeholders must monitor divergence between EU and US regulatory timelines for embedded AI inference to avoid stranded inventory or redundant certification cycles.
Market Dynamics
Factory automation OEMs are consolidating compute procurement around ARM-based system-on-chip modules, compressing design cycles and displacing legacy x86 industrial PCs in power-constrained edge controllers.
Growth Catalysts
- EU AI Act compliance mandates:Medical device integrators must embed certified inference engines, accelerating replacement of non-compliant legacy controllers in diagnostic equipment.
- Industrial robotics densification:Collaborative robot deployments on German and Taiwanese factory floors demand deterministic real-time compute with sub-millisecond latency.
- Advanced packaging capacity expansion:Taiwan's foundry investments in fan-out wafer-level packaging enable higher-density embedded modules for automotive ECUs.
Market Restraints
- Silicon supply concentration:Taiwan and South Korea control over 80% of leading-edge logic wafer starts, exposing embedded module vendors to geopolitical disruption.
- Extended certification timelines:FDA 21 CFR Part 820 quality system audits and MDR technical documentation reviews stretch medical embedded product launches by 14-22 months.
- Copper and rare earth price volatility:PCB substrate materials and permanent magnet components in ruggedized enclosures face input cost swings of 30-40% annually.
Strategic Opportunities
- India manufacturing incentives:PLI scheme subsidies for electronics assembly attract embedded computing module production for domestic industrial automation demand.
- Functional safety convergence:IEC 61508 and ISO 26262 certification alignment creates cross-vertical module platforms serving both process automation and automotive.
- Edge AI inference unbundling:Medical imaging OEMs are separating AI acceleration hardware from base compute, opening subsystem supplier slots for specialized inference modules.
Industry Challenges
- Embedded Linux security patching:Long-life industrial deployments face CVE remediation gaps as kernel maintainers deprioritize aging LTS branches.
- Legacy fieldbus integration:EtherCAT and PROFINET protocol stacks require dedicated ASIC or FPGA co-processors, complicating ARM SoC software-defined I/O strategies.
- Thermal design talent scarcity:Fanless enclosure engineering for -40°C to 85°C operation demands specialized mechanical and materials expertise concentrated in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Merchant Embedded Computing Market |
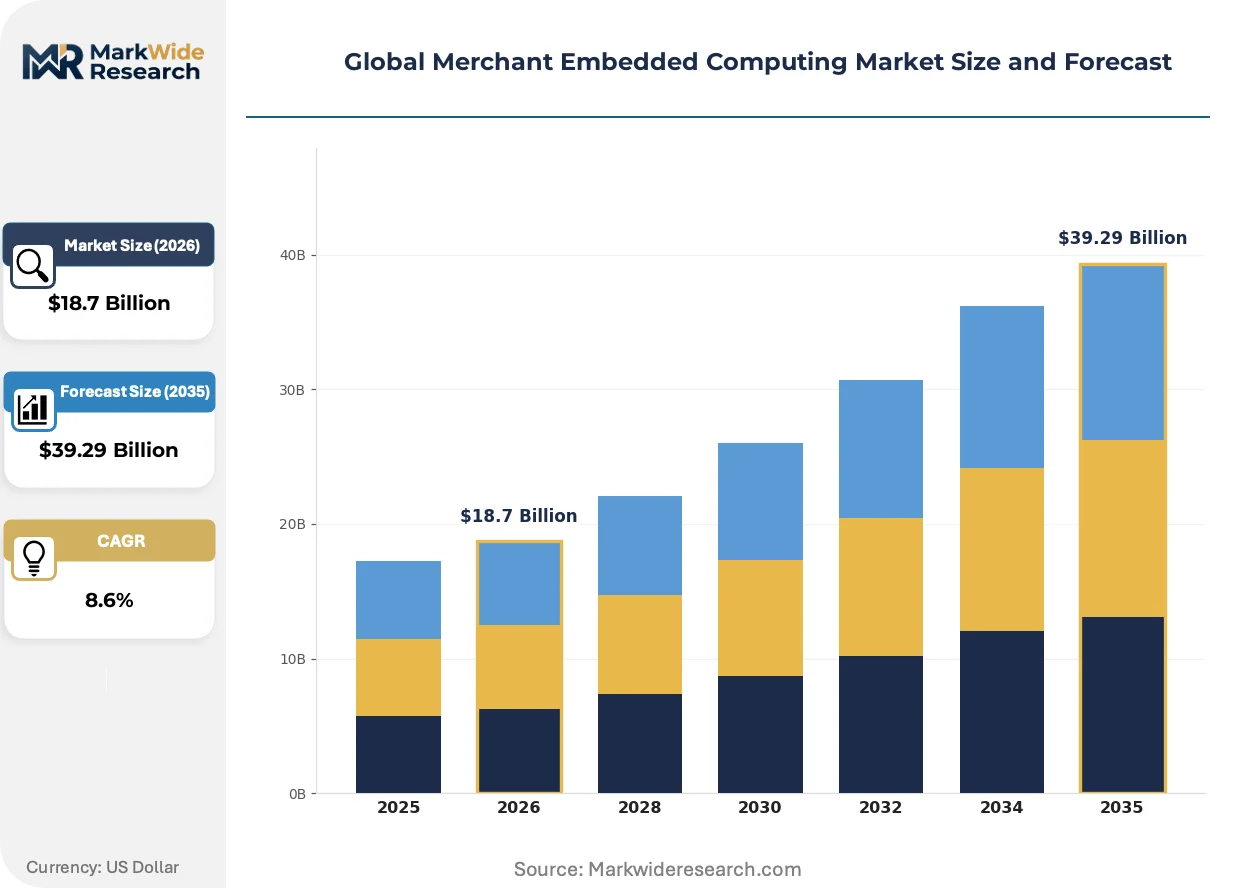
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Board Computers, System on Chip, Industrial PCs, Embedded Modules Technology: ARM, x86, FPGA, DSP Application: Automotive Systems, Medical Devices, Consumer Electronics, Smart Home Appliances End User: OEMs, Tier-1 Suppliers, Retailers, Aftermarket Providers |
| Companies Covered | Advantech, Kontron, Abaco, Artesyn Embedded, Curtiss Wright Controls, ADLINK, DFI, MSC Technologies, Congatec AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Merchant Embedded Computing Market Strategic Shifts
Compute architecture decisions are migrating from OEM engineering teams to semiconductor vendors, who now define thermal envelopes, security enclaves, and functional safety partitions in reference designs.
RISC-V open instruction set architectures are rendering obsolete proprietary DSP cores in radar and medical imaging signal chains. Automotive tier-1s in Germany and the United States are sampling RISC-V vector extensions for adaptive cruise control sensor fusion. The shift compresses licensing costs and enables customization previously locked behind ARM or Cadence IP walls.
REACH substance restrictions from ECHA are banning hexavalent chromium in PCB surface finishes and specific brominated flame retardants in enclosure plastics. Medical device manufacturers serving European markets must requalify board-level suppliers under revised material declarations. The compliance burden falls heaviest on mid-size automation OEMs lacking dedicated regulatory affairs functions.
Subscription-based firmware update contracts are displacing perpetual license models for embedded operating systems and hypervisors. Industrial automation distributors in the United States are bundling ten-year security patch agreements with hardware shipments. The model concentrates recurring revenue with OS vendors while transferring long-term liability to system integrators managing end-customer deployments.
Global Merchant Embedded Computing Market Segmentation
Merchant embedded computing procurement patterns diverge sharply across product architectures and customer tiers. Design cycle velocity and certification burden determine which segments turn inventory fastest versus which lock capital longest.
Product Type:
System on Chip modules refresh fastest as semiconductor vendors push annual reference design updates, while Industrial PCs carry the longest depreciation schedules.
- Single Board Computers:Compact, standardized compute platforms integrating processor, memory, and I/O on a single PCB. Demand clusters in German factory automation retrofits where EtherCAT protocol compatibility accelerates replacement of legacy PLCs.
- System on Chip:Highly integrated silicon combining CPU, GPU, and specialized accelerators on one die. Taiwanese robotics OEMs are standardizing procurement around ARM-based SoCs to compress bill-of-materials and reduce thermal design cycles in collaborative robot controllers.
- Industrial PCs:Ruggedized x86 platforms with expansion slots for deterministic I/O cards.
- Embedded Modules:Computer-on-module form factors mating carrier boards with standardized connectors.
Industrial PCs dominate installed base. System on Chip is where expansion concentrates.
Technology:
ARM licensing economics favor high-volume medical and automotive programs, while x86 retains margin premiums in performance-intensive automation workloads.
- ARM:Reduced instruction set architecture optimized for power efficiency and thermal constraints. Medical device integrators in the United States are embedding ARM Cortex-M and Cortex-A cores into portable diagnostic equipment to satisfy FDA 21 CFR Part 820 quality system requirements with lower thermal management overhead.
- x86:Complex instruction set architecture from Intel and AMD with mature software ecosystems. German automotive tier-1s specify x86 industrial PCs for in-vehicle test benches requiring real-time Windows compatibility and deterministic latency.
- FPGA:Field-programmable gate arrays enabling hardware reconfiguration post-deployment.
- DSP:Digital signal processors with specialized multiply-accumulate units for sensor fusion.
x86 captures the dominant margin pool. ARM is climbing the fastest in unit volume.
Application:
Automotive and medical verticals impose the heaviest certification burdens, stretching design-in cycles, while consumer electronics demands the shortest time-to-market windows.
- Automotive Systems:ECUs, infotainment platforms, and ADAS compute modules operating across -40°C to 125°C temperature ranges. German OEMs are consolidating procurement around ASIL-D certified embedded modules to satisfy ISO 26262 functional safety mandates for autonomous driving subsystems.
- Medical Devices:Diagnostic imaging, patient monitoring, and surgical navigation systems requiring IEC 60601-1 safety certification. EU AI Act compliance deadlines are forcing replacement of legacy controllers in European diagnostic equipment with inference-capable embedded platforms.
- Consumer Electronics:Smart appliances and wearable devices with shorter product lifecycles.
- Smart Home Appliances:Connected HVAC, security, and energy management controllers.
Automotive Systems anchor revenue concentration. Medical Devices is where regulatory-driven replacement cycles accelerate.
End User:
OEMs and tier-1 suppliers control specification authority, while aftermarket providers capture service revenue on extended lifecycle deployments.
- OEMs:Original equipment manufacturers with captive engineering teams defining embedded compute specifications. Industrial automation OEMs in Taiwan are consolidating procurement around ARM-based system-on-chip modules to compress design cycles and reduce qualification overhead.
- Tier-1 Suppliers:Subsystem integrators delivering complete modules to OEM customers. German automotive tier-1s are investing in captive embedded design centers to secure supply chain visibility for safety-critical ECU programs.
- Retailers:Distribution channels stocking standard embedded platforms for system integrators.
- Aftermarket Providers:Service organizations supporting fielded equipment with replacement modules and firmware updates.
OEMs dominate specification control. Tier-1 Suppliers is where backward integration into embedded design capabilities is concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulations in the United States anchor the dominant geography for medical embedded systems certification, while Taiwan's foundry investments and Germany's automation engineering clusters shape supply-side capacity and demand concentration across the forecast window.
United States
Medical device integrators in the United States are embedding ARM-based controllers into portable diagnostic equipment to satisfy FDA 21 CFR Part 820 quality system requirements. FCC Part 15 electromagnetic compatibility mandates govern shipments for industrial automation applications. Boston and Minneapolis medical device corridors concentrate design-in activity for surgical navigation and patient monitoring systems.
Germany
German automotive tier-1 suppliers specify x86 industrial PCs for in-vehicle test benches requiring real-time Windows compatibility and deterministic latency. KBA vehicle type approval and ISO 26262 functional safety mandates from EU regulators drive ASIL-D certified module procurement. Stuttgart and Munich anchor embedded design centers serving autonomous driving subsystem programs.
Taiwan
Taiwanese robotics OEMs are standardizing procurement around ARM-based system-on-chip modules to compress bill-of-materials and reduce thermal design cycles in collaborative robot controllers. The country's national semiconductor regulator under the National Science and Technology Council coordinates foundry investment incentives. Hsinchu Science Park and Tainan Technology Industrial Park concentrate advanced packaging capacity for automotive ECU substrates.
China
Industrial automation retrofits in China's Yangtze River Delta demand EtherCAT-compatible single board computers for legacy PLC replacement. MIIT standards and GB certification requirements constrain import-dependent module specifications. Shanghai and Shenzhen embedded design clusters serve domestic smart factory and electric vehicle controller markets.
Japan
Japanese medical imaging OEMs are separating AI acceleration hardware from base compute, opening subsystem supplier slots for specialized inference modules. METI technology roadmaps and PMDA medical device regulations shape product qualification timelines. Tokyo and Osaka metropolitan areas concentrate thermal engineering talent for fanless enclosure design in -40°C to 85°C operating ranges.
Global Merchant Embedded Computing Market Competitive Environment
Vertically integrated platform vendors and specialized module fabricators split the market between design-in relationships with automation OEMs and flexible subsystem supply to tier-1 integrators. The vendor base concentrates around three strategic archetypes: full-stack industrial IoT platform providers, European supply-security anchors with captive manufacturing, and Asia-Pacific scale manufacturers serving cost-optimized segments. Competitive moves center on backward integration into semiconductor reference design partnerships and geographic diversification of final assembly capacity to mitigate single-source exposure.
Within the platform-integrated tier, Advantech leverages vertical integration across industrial IoT platforms to sustain design-in relationships with automation OEMs. Kontron anchors European supply security through manufacturing scale in Germany and extended service networks across industrial verticals. Among Asia-Pacific scale manufacturers, DFI occupies a position serving cost-optimized automation controller demand.
| Leading Market Players |
|---|
| Advantech |
| Kontron |
| Abaco |
| Artesyn Embedded |
| Curtiss Wright Controls |
| ADLINK |
| DFI |
| MSC Technologies |
| Congatec AG |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Taiwan's foundry complex for ARM-based SoC substrates compresses margin spreads between premium-certified and standard-grade embedded modules while forcing tier-1 suppliers toward extended inventory positions. This concentration dynamic simultaneously widens pricing tiers for ASIL-D certified automotive modules against cost-optimized industrial controllers and reshapes procurement strategies around geographic diversification.
Pricing Analysis
German automotive tier-1s pay 15-25% premiums over Taiwanese robotics OEMs for identical ARM-based SoC modules due to ASIL-D certification overhead and localized technical support bundling. Pricing stratifies across premium, standard, and economy tiers where FDA 21 CFR Part 820 quality system documentation and EU AI Act compliance documentation drive the top-tier spread. Cost compression in standard-grade industrial PCs is intensifying because x86 vendors are absorbing Intel/AMD socket price volatility to defend share against ARM encroachment. Mid-size automation OEMs in China exhibit highest price sensitivity, while German medical device integrators prioritize certification assurance over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement contracts as Taiwanese foundries and German EMS providers deploy supply-chain finance facilities to ease working capital strain for tier-1 integrators. Manufacturing concentrates in Taiwan, Germany, and China where Hsinchu Science Park, Stuttgart industrial corridors, and Shenzhen electronics clusters anchor module assembly. The supply chain draws from copper-clad laminates, rare earth magnets for ruggedized enclosures, and leading-edge logic wafers as critical inputs. Single-source vulnerability in advanced packaging capacity at Taiwanese foundries poses the dominant structural risk. Distribution runs through industrial automation distributors in the United States and specialized electronics component channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ten-year firmware security patch subscriptions are expanding at double the rate of hardware shipments, transforming merchant embedded computing from a capital equipment sale into a recurring-revenue service relationship. This service-attach dynamic rewards vendors who bundle lifecycle management with initial module procurement.
For Market Incumbents: Pre-empt RISC-V open-ISA substitution by embedding proprietary security enclaves and functional safety partitions into reference designs before automotive tier-1s complete their Cadence/ARM license migration. Lock in German medical device OEMs through captive certification support teams that compress EU AI Act compliance timelines. Backward integration into fan-out wafer-level packaging partnerships with Taiwanese foundries secures substrate allocation priority during supply shocks. For New Entrants and Emerging Players: India's PLI-subsidized electronics assembly corridors offer the most penetrable geographic entry point for cost-optimized ARM-based modules serving domestic industrial automation demand. Target collaborative robot controller subsystems where Taiwanese OEMs are consolidating procurement but still tolerate second-source qualification. Lead with IEC 61508/ISO 26262 dual-certified platforms that cross-serve process automation and automotive without redundant certification investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors embedded design specialists with captive functional safety certification capabilities and established foundry partnerships. Long-term viability hinges on recurring firmware revenue attachment rates rather than hardware margin extraction. Watch for inflection signals in medical imaging OEM unbundling trends where AI acceleration hardware separation creates subsystem supplier acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Advanced Packaging | Taiwanese foundry partnerships secure substrate allocation priority for automotive ECU programs during supply constraints. |
| Dual Certification Platform Development | IEC 61508 and ISO 26262 alignment enables cross-vertical module deployment across automation and automotive. |
| Firmware Subscription Model Expansion | Ten-year security patch agreements concentrate recurring revenue and transfer long-term liability to system integrators. |
| Geographic Manufacturing Diversification | India PLI scheme assembly capacity mitigates single-source exposure to Taiwan foundry concentration. |
| AI Inference Module Unbundling | Medical imaging OEM separation of acceleration hardware from base compute opens specialized subsystem supplier slots. |
Study Parameters
A spread of perspectives from embedded design engineers at automation OEMs, procurement leads at German automotive tier-1s, regulatory affairs specialists navigating FDA and EU MDR pathways, and foundry account managers converged on the working assumptions through structured primary interviews. Secondary validation drew from SEC 10-K filings of merchant embedded computing vendors, ECHA REACH substance restriction updates, EU AI Act implementation guidance, and customs trade data for PCB substrate materials. Bottom-up module shipment estimates triangulated against top-down semiconductor vendor revenue disclosures.
Demand-supply balance modeling across the analysis window segmented volume and value by product architecture, instruction set technology, target application vertical, and end-user procurement authority. CAGRs derived from year-over-year growth rate convergence between historical shipment trajectories and forward-looking OEM design-in pipeline visibility. Forecast inputs incorporated foundry capacity expansion announcements from Taiwan's National Science and Technology Council and medical device regulatory timeline divergence between FDA and EU AI Act implementation.
Practitioners should monitor foundry utilization rates, EU AI Act compliance deadline acceleration, and RISC-V ecosystem maturity for early signals of forecast revision triggers. Forecasts reflect assumptions about sustained ARM licensing economics and x86 software ecosystem stickiness. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Spain Data Center Processor Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
NFC Chips Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
VR Gaming Hardware Chipsets Market