
 India Silicon Carbide (Sic) Market | 2026-2036
India Silicon Carbide (Sic) Market Size, Share, and Industry Trends Forecast 2026-2036
India Silicon Carbide (Sic) Market Foresight
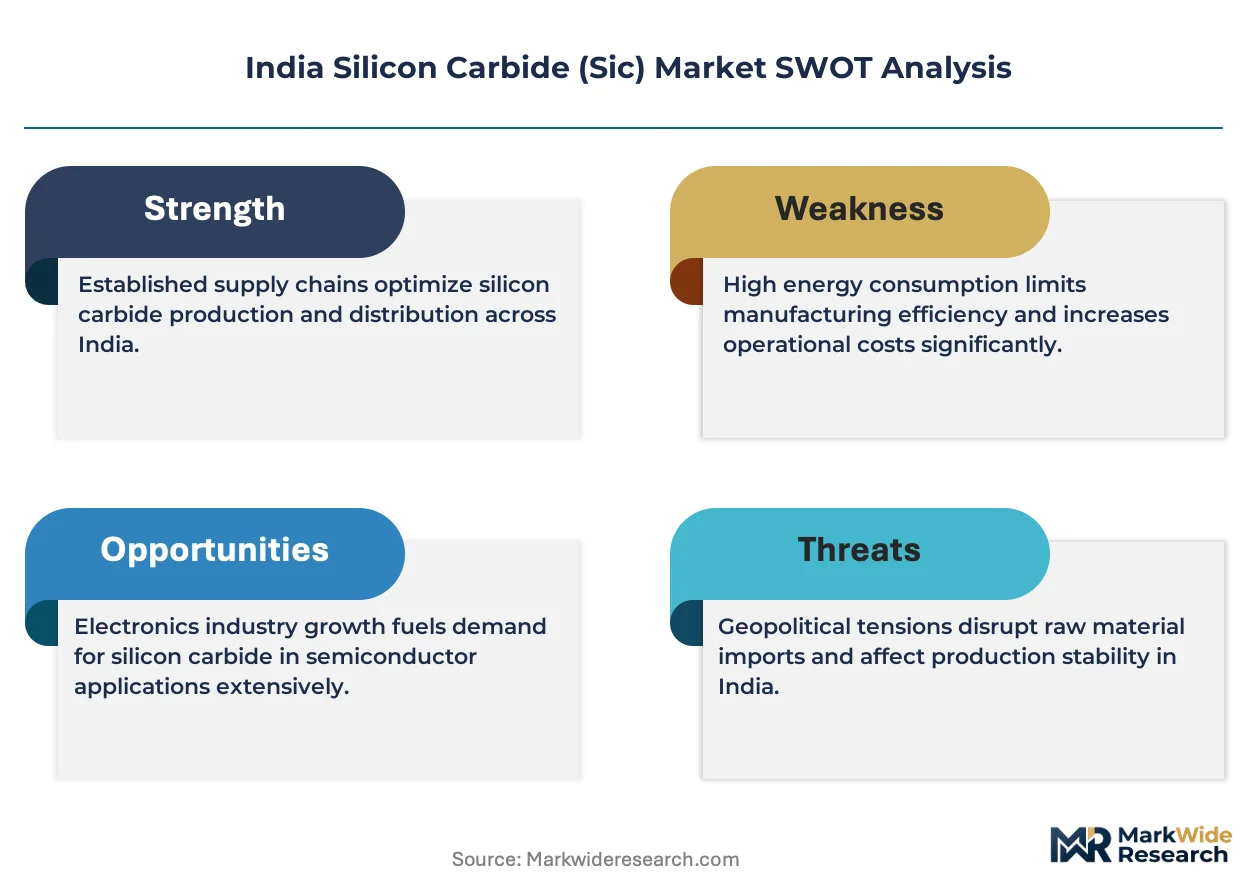
The PLI scheme for large-scale electronics and semiconductors is realigning the cost-of-entry calculus for domestic SiC substrate production. Carborundum Universal Limited leverages its integrated abrasives-to-ceramics portfolio to anchor supply security for industrial SiC grades. Saint-Gobain India Pvt. Ltd. competes through specialized refractory applications where thermal shock resistance commands premium positioning. Grindwell Norton Ltd. differentiates via precision abrasives for automotive and electronics finishing.
Silicon carbide is a compound semiconductor formed by bonding silicon and carbon in a tetrahedral crystal lattice, typically produced through the Acheson process at temperatures exceeding 2,200°C or via chemical vapor deposition for electronic-grade substrates; its wide bandgap of 3.26 eV enables operation at higher voltages, frequencies, and temperatures than silicon, making it essential for power electronics and high-performance thermal management systems. Black SiC dominates volume production for abrasives and metallurgical applications where cost efficiency outweighs purity requirements, while Green SiC commands structural margins in precision grinding wheels and semiconductor wafer processing. The substrate form category concentrates investment interest as domestic fab projects require qualified 150mm and 200mm SiC epitaxy-ready wafers.
BIS certification mandates and the CEA's grid code revisions for renewable integration are tightening material traceability standards for power devices deployed in utility-scale inverters. CDSCO and the Semiconductor Mission's quality frameworks are defining test protocols for SiC wafers destined for medical electronics and defense-rated systems. Stakeholders must monitor how the PLI scheme's disbursement timelines synchronize with equipment import lead times for crystal growth furnaces.
Market Dynamics
India's PLI scheme for semiconductors is redirecting capital toward domestic SiC substrate fabrication, compressing import dependency timelines while tightening qualification standards for power electronics deployed in electric vehicle powertrains.
Growth Catalysts
- Electric vehicle powertrain procurement:Traction inverter manufacturers are scaling SiC substrate orders as OEMs prioritize efficiency gains over silicon IGBTs in high-voltage architectures.
- CEA grid code revisions:Renewable integration mandates for utility-scale solar and wind farms are mandating SiC-based inverters capable of operating at elevated switching frequencies under thermal stress.
- Dholera Special Investment Region concentration:Gujarat's semiconductor cluster is attracting epitaxy equipment investments that reduce lead times for 150mm wafer qualification.
Market Restraints
- Graphite electrode input volatility:Acheson furnace operations depend on petroleum needle coke supplies concentrated in limited overseas sources, exposing domestic producers to price swings.
- Crystal growth furnace import concentration:Physical vapor transport equipment for electronic-grade boule production remains concentrated among German and Japanese vendors, creating equipment access bottlenecks.
- Silicon carbide-on-silicon substitution in cost-sensitive abrasives:Black SiC faces displacement in metallurgical applications where fused alumina offers adequate performance at lower unit economics.
Strategic Opportunities
- Karnataka Bengaluru-Tumkur corridor expansion:Electronics manufacturing clusters in this sub-region offer proximity to defense and aerospace qualification facilities for high-reliability SiC devices.
- Medical electronics certification pathway:CDSCO quality frameworks for implantable power systems create a regulated entry point for SiC substrates meeting biocompatibility and hermetic sealing standards.
- Silicon carbide-gallium nitride convergence:Hybrid power module architectures combining SiC MOSFETs with GaN HEMTs are opening design wins in telecom base station power supplies.
Industry Challenges
- Crystal defect engineering talent scarcity:Domestic workforce development lags demand for technicians capable of managing micropipe density reduction in 200mm boule growth.
- BIS certification timeline compression:Material traceability documentation for power devices must synchronize with PLI disbursement schedules that penalize qualification delays.
- Legacy silicon supply chain integration friction:Automotive Tier-1 suppliers face requalification costs when retrofitting SiC modules into existing inverter platforms designed for silicon components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Silicon Carbide (Sic) Market |
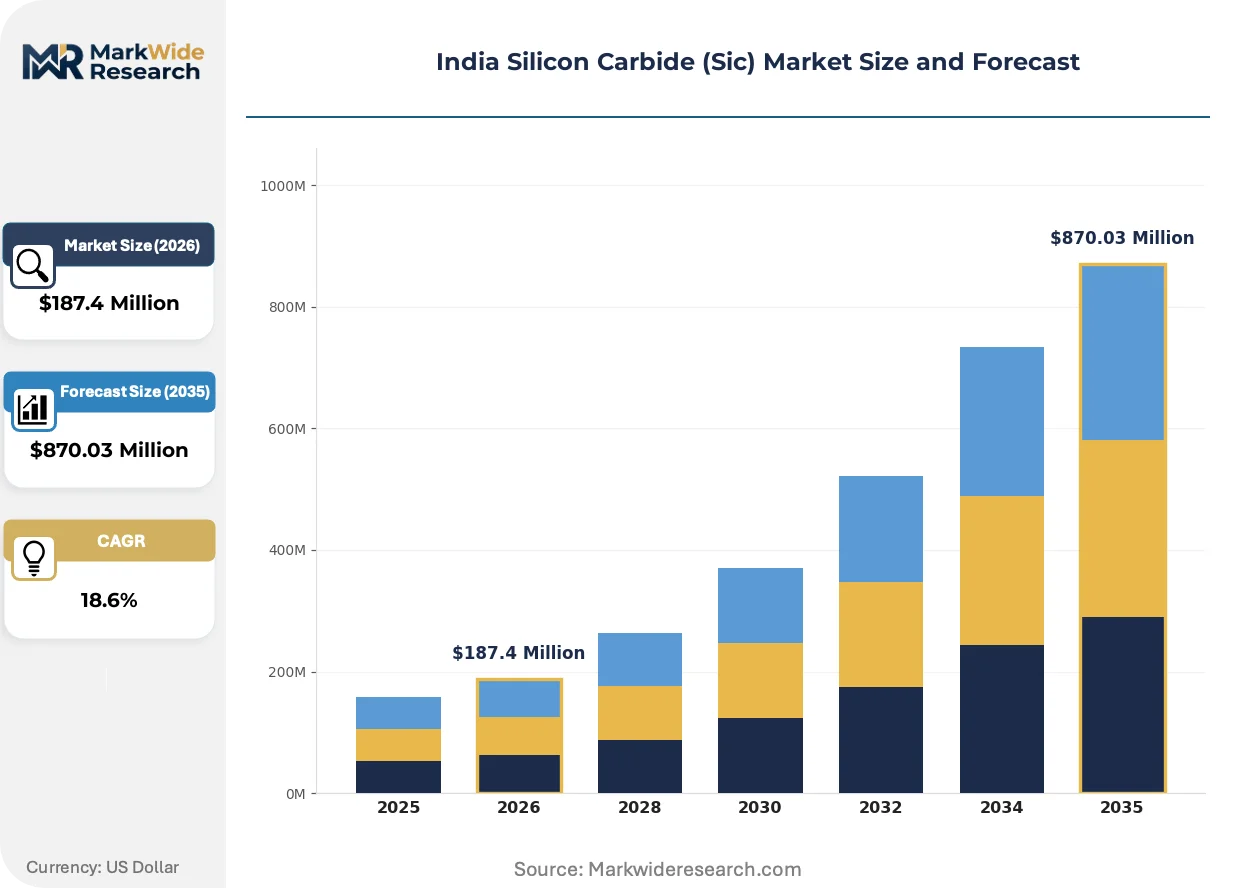
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black SiC, Green SiC, Micro SiC, Premium SiC End User: Electronics, Automotive, Aerospace, Power Generation Application: Power Devices, LEDs, Abrasives, Coatings Form: Wafer, Powder, Bulk, Substrate |
| Companies Covered | Carborundum Universal Limited, Saint-Gobain India Pvt. Ltd., Grindwell Norton Ltd., Orient Abrasives Ltd., Ruttonsha International Rectifier, Navratan Speciality Chemicals LLP, Industrial Mineral Company, Ascatron India Pvt. Ltd., Hi-Tech Abrasives Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Silicon Carbide (Sic) Market Shifts & Advancements
Wafer processing technologies and procurement models are converging to reshape how SiC substrates move from crystal growth to qualified power device deployment in India's emerging fab ecosystem.
Chemical vapor deposition for electronic-grade SiC substrates is expanding into volume production as domestic projects prioritize epitaxy-ready wafers over imported boules. Foundry operators in Gujarat are qualifying 150mm n-type substrates for MOSFET fabrication at compressed timelines. This technology is expanding into cost structures previously dominated by silicon carbide imported from established Asian suppliers.
BIS certification mandates for power electronics are tightening material traceability standards across the supply chain. The Semiconductor Mission's quality frameworks now require documented defect density for wafers deployed in defense-rated systems. Medical electronics and grid-tied inverter segments are responding by investing in in-house metrology capabilities rather than relying on vendor certificates.
Long-term supply agreements are displacing spot market purchases as the dominant procurement mechanism for qualified substrates. Automotive powertrain divisions are locking multi-year contracts directly with crystal growth houses, bypassing traditional distributor channels. This shift is most visible in Maharashtra and Tamil Nadu, where EV OEMs have established dedicated sourcing desks for SiC procurement.
India Silicon Carbide (Sic) Market Segmentation
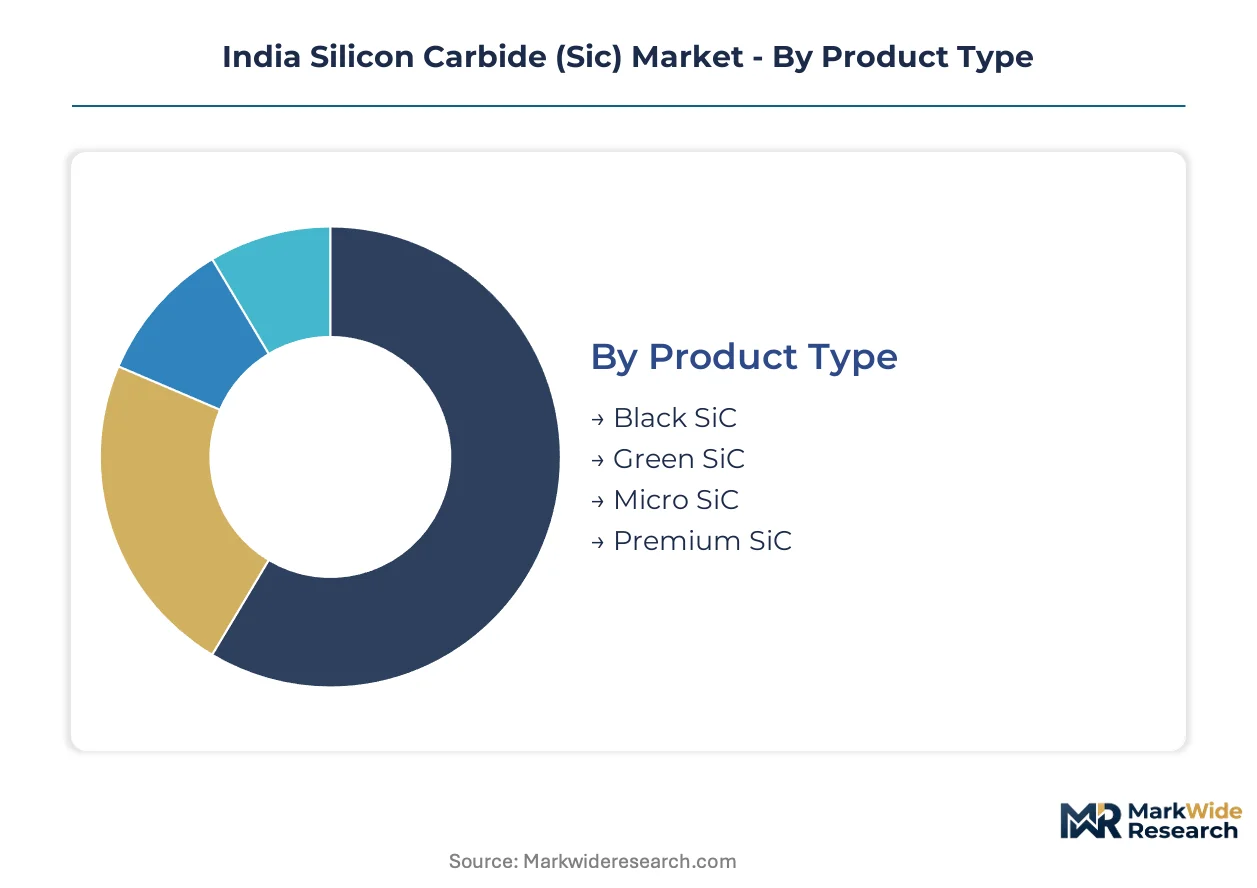
Segmentation in India's SiC market reveals how material purity grades, device architectures, and procurement channels split across divergent value capture models. Each dimension exposes different margin pressures and qualification barriers.
Product Type:
Volume production concentrates in lower-purity grades where Acheson furnace economics dominate, while premium grades command structural margins through chemical vapor deposition and defect engineering.
- Black SiC:Produced via the Acheson process at temperatures exceeding 2,200°C, this grade contains higher nitrogen and aluminum impurities suited for abrasives and metallurgical applications. Demand concentrates in Gujarat's Dholera corridor where refractory manufacturers supply steel and cement plants, though petroleum needle coke input volatility compresses margins.
- Green SiC:Higher purity from additional silica and petroleum coke refinement enables precision grinding wheels and semiconductor wafer processing. Karnataka's Bengaluru-Tumkur electronics cluster drives procurement for solar wafer slicing and LED substrate preparation, with BIS certification timelines creating qualification bottlenecks.
- Micro SiC:Sub-micron particle sizes serve specialized ceramic matrix composites and additive manufacturing feedstocks.
- Premium SiC:Electronic-grade material with micropipe density below 1 cm⁻² targets MOSFET and Schottky diode fabrication.
Mature deployment sits with Black SiC. Newer deployment is concentrated in Premium SiC.
End User:
Customer type determines specification stringency, with defense-rated systems and medical electronics imposing traceability requirements that industrial buyers waive.
- Electronics:Power semiconductor foundries in Gujarat require 150mm and 200mm epitaxy-ready wafers with documented defect density. The Semiconductor Mission's quality frameworks mandate material provenance for defense-rated systems, compressing qualification timelines for domestic crystal growth houses.
- Automotive:Traction inverter manufacturers scaling SiC MOSFET procurement prioritize efficiency gains over silicon IGBTs in 800V architectures. Maharashtra and Tamil Nadu EV OEMs have established dedicated sourcing desks, locking multi-year supply agreements directly with substrate vendors.
- Aerospace:Thermal protection systems and radar components demand high-reliability grades with hermetic sealing verification.
- Power Generation:CEA grid code revisions for renewable integration mandate SiC-based inverters capable of elevated switching frequencies under thermal stress at utility-scale solar and wind farms.
Procurement maturity differentiates Electronics from Power Generation, where deployment is climbing the fastest.
Application:
Functional use case determines whether SiC competes on performance premium or cost parity against incumbent materials.
- Power Devices:MOSFETs, Schottky diodes, and JFETs exploit the 3.26 eV bandgap for high-voltage, high-frequency operation. Traction inverters and grid-tied converters in Gujarat and Maharashtra drive substrate demand, with PLI scheme disbursement timelines synchronizing equipment import lead times for crystal growth furnaces.
- LEDs:Substrate material for gallium nitride epitaxy in solid-state lighting applications.
- Abrasives:Grinding wheels, cutting tools, and lapping compounds face displacement pressure from fused alumina in cost-sensitive metallurgical applications.
- Coatings:Thermal spray and chemical vapor deposition layers for wear resistance and corrosion protection.
Established penetration characterizes Abrasives. Power Devices represents the fastest-growing trajectory.
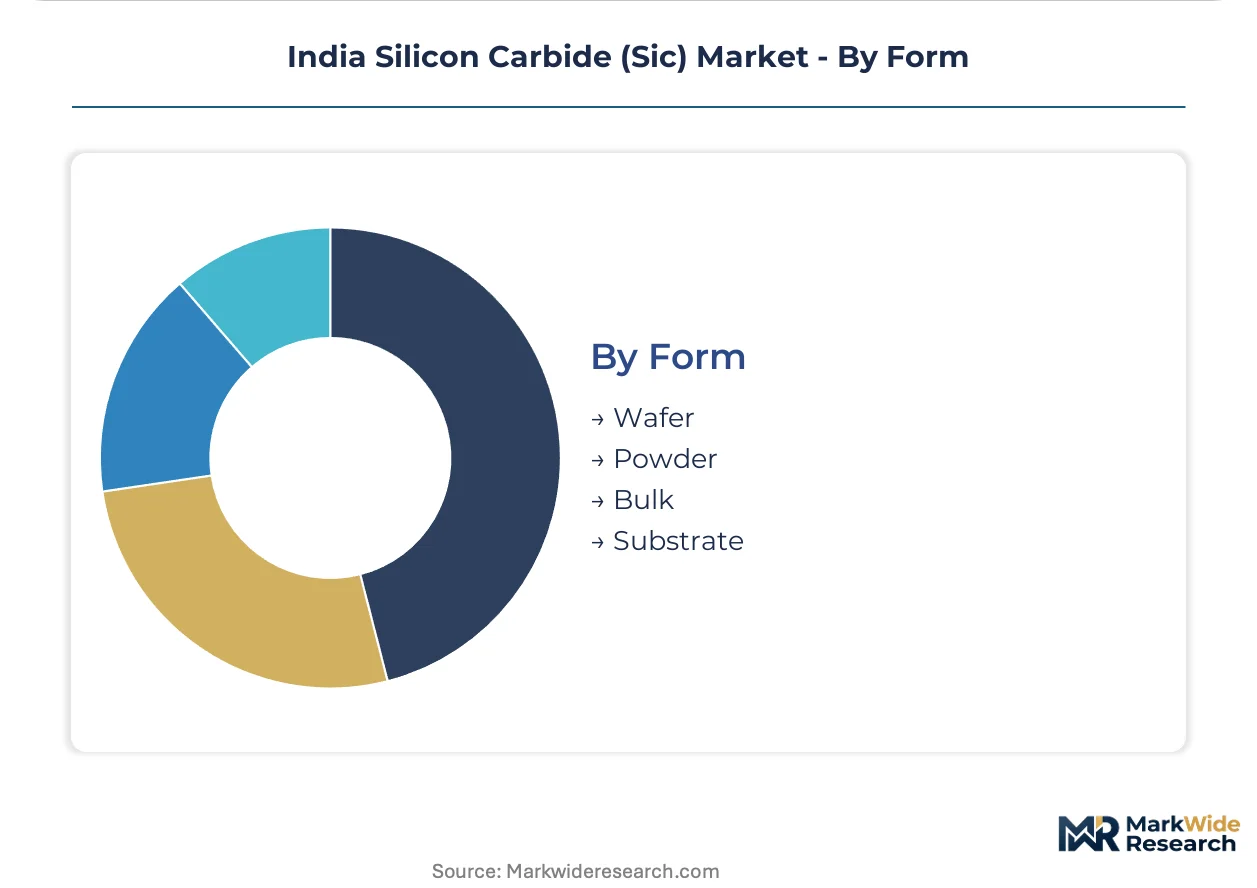
Form:
Physical configuration dictates capital intensity and customer proximity requirements across the value chain.
- Wafer:Diced slices from single-crystal boules undergo polishing and epitaxy for device fabrication. Dholera Special Investment Region attracts epitaxy equipment investments reducing lead times for 150mm qualification, though 200mm micropipe density reduction remains constrained by workforce development gaps.
- Substrate:Epitaxy-ready wafers with specified surface roughness and defect density command premium positioning in domestic fab projects.
- Powder:Granular material for refractory brick production and ceramic sintering.
- Bulk:Crushed and sized material for metallurgical additive and abrasive grain applications.
Volume concentration rests with Bulk. Substrate form is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Gujarat's Dholera Special Investment Region and Karnataka's Bengaluru-Tumkur corridor, where semiconductor fabs and electronics manufacturing clusters drive substrate procurement. State-level industrial policies and central PLI disbursements synchronize capital deployment across these zones.
Gujarat
Dholera Special Investment Region anchors India's emerging SiC substrate fabrication capacity, with crystal growth houses qualifying 150mm wafers for power device foundries. The state's semiconductor policy offers capital subsidies synchronized with PLI scheme timelines. Dahej and Sanand industrial zones host refractory manufacturers supplying steel plants with Black SiC.
Karnataka
Bengaluru-Tumkur corridor concentrates electronics manufacturing and defense qualification facilities for high-reliability SiC devices. CDSCO quality frameworks for medical electronics create regulated entry points for substrate vendors. Mysuru and Hubballi host precision abrasives producers serving solar wafer slicing operations.
Maharashtra
Pune and Mumbai metropolitan EV OEMs have established dedicated sourcing desks for SiC procurement, locking multi-year supply agreements directly with substrate vendors. The state's electric mobility policy mandates local content thresholds for power electronics. Chakan and Talegaon industrial belts host traction inverter manufacturers scaling MOSFET orders.
Tamil Nadu
Chennai and Coimbatore automotive clusters drive procurement for 800V traction inverter architectures. The state's advanced chemistry cell policy extends incentives to power semiconductor packaging operations. Sriperumbudur and Oragadam electronics manufacturing zones attract epitaxy equipment investments.
Telangana
Hyderabad's defense and aerospace research complex demands high-reliability SiC grades with hermetic sealing verification. The state's electronics policy targets compound semiconductor ecosystem development. Shamshabad and Medchal industrial corridors host emerging crystal growth operations serving niche qualification pathways.
India Silicon Carbide (Sic) Market Competitive Landscape
Gujarat-based producers anchor the abrasives and refractory tier; Karnataka and Maharashtra specialists hold positions in precision ceramics and electronics-grade material. The vendor base splits between integrated industrial conglomerates with captive raw material access and focused substrate fabricators dependent on imported boules. Three archetypes dominate: Acheson furnace operators serving metallurgical demand, CVD-based electronic-grade producers, and precision abrasives specialists. Capacity expansion and backward integration into petroleum needle coke sourcing represent the dominant competitive vectors.
Among established domestic operators, Carborundum Universal Limited and Saint-Gobain India Pvt. Ltd. occupy positions reflecting integrated materials portfolios, while Grindwell Norton Ltd. exemplifies precision abrasives specialization. These entities represent contrasting strategic postures—diversified industrial supply security versus focused technical ceramics positioning. Newer entrants in the substrate tier, including Ascatron India Pvt. Ltd., sit within the electronic-grade qualification pathway where crystal defect engineering capabilities determine competitive viability. The competitive dynamic pits legacy abrasives incumbents against venture-backed substrate specialists racing to meet domestic fab qualification timelines.
| Leading Market Players |
|---|
| Carborundum Universal Limited |
| Saint-Gobain India Pvt. Ltd. |
| Grindwell Norton Ltd. |
| Orient Abrasives Ltd. |
| Ruttonsha International Rectifier |
| Navratan Speciality Chemicals LLP |
| Industrial Mineral Company |
| Ascatron India Pvt. Ltd. |
| Hi-Tech Abrasives Ltd. |
| Others |
Supply & Pricing Matrix
Electronic-grade substrate premiums versus Acheson furnace commodity grades bifurcate India's SiC market into divergent cost structures and procurement configurations. PLI scheme disbursement timelines compress qualification windows for 150mm wafer producers while petroleum needle coke volatility destabilizes Black SiC margin stability in Gujarat's refractory belt.
Pricing Analysis
Volume-mass Black SiC commands thin margins through spot market sales to steel and cement plants, while premium electronic-grade substrates capture structural pricing power via long-term offtake agreements with automotive powertrain divisions. Three-tier pricing structure across premium, standard, and economy levels reflects defect density certification tiers mandated by BIS and the Semiconductor Mission. Cost compression in metallurgical grades intensifies because fused alumina substitutes erode unit economics in cost-sensitive applications. Automotive OEMs exhibit lowest price sensitivity given efficiency gains from SiC MOSFETs offset substrate premiums, whereas refractory buyers in Dholera's industrial zones resist price escalation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Maharashtra and Tamil Nadu EV manufacturers, displacing traditional distributor networks for qualified substrates. Crystal growth furnace supply concentrates in Germany, Japan, and the USA, creating equipment access bottlenecks for domestic boule production ramp-ups. Raw material dependencies span petroleum needle coke from limited overseas sources, high-purity silica sand, and graphite electrodes for Acheson operations. Single-source vulnerability in physical vapor transport equipment exposes Dholera fab projects to import lead time volatility. Distribution runs through long-term supply agreements directly with crystal growth houses, bypassing spot market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's SiC market sits in a technology-transition phase where silicon carbide MOSFETs displace silicon IGBTs in 800V electric vehicle architectures, compressing requalification timelines for power electronics supply chains.
For Market Incumbents: Deepen backward integration into petroleum needle coke sourcing to defend margin position against input volatility in Acheson furnace operations. Anchor supply security through captive raw material access while investing in BIS certification documentation to synchronize with PLI disbursement schedules. Crystal defect engineering talent scarcity threatens electronic-grade substrate qualification timelines; prioritize workforce development partnerships with Karnataka's technical institutes.
For New Entrants and Emerging Players: The 40-60% price-point gap between imported premium substrates and domestic Black SiC refractory grades opens white-space targeting in precision abrasives for solar wafer slicing. Karnataka's Bengaluru-Tumkur corridor offers the most penetrable geography given proximity to electronics manufacturing clusters and CDSCO medical electronics certification pathways. A go-to-market angle emphasizing hermetic sealing verification for defense-rated systems differentiates against commodity incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with electronic-grade substrate fabricators given PLI scheme capital subsidy synchronization and domestic fab qualification mandates. Long-term viability over the next decade hinges on micropipe density reduction capabilities for 200mm boule production. The signal to watch is equipment import lead times for crystal growth furnaces from German and Japanese vendors, which indicate domestic capacity expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petroleum Needle Coke | Reduces input cost volatility for Acheson furnace operators supplying Gujarat's refractory market. |
| Long-term Supply Agreement with Automotive OEMs | Locks volume commitments from Maharashtra and Tamil Nadu EV powertrain divisions. |
| BIS Certification Investment | Accelerates qualification timelines for defense-rated SiC wafers under Semiconductor Mission frameworks. |
| Crystal Growth Furnace Procurement | Secures physical vapor transport equipment from German and Japanese vendors for Dholera fab projects. |
| Workforce Development Partnership | Builds micropipe density reduction capabilities for 200mm boule production in Karnataka's technical ecosystem. |
Research Methodology
Independent corroboration across primary interviews with crystal growth technicians, power semiconductor foundry procurement leads, and CEA grid code compliance officers underwrites the qualitative findings. Secondary validation draws from BIS certification databases, Semiconductor Mission policy circulars, customs trade records for SiC substrate imports, and PLI scheme disbursement documentation. Bottom-up triangulation across wafer processing cost structures and top-down validation against end-use demand from automotive powertrain divisions anchor the analytical framework.
Comparable-period anchoring to historical SiC substrate import volumes and domestic Acheson furnace output establishes baseline trajectory calibration across the analysis window. Segmentation dimensions span product purity grade, end-user specification stringency, application performance tier, and physical form factor. CAGRs derive from equipment import lead time trajectories, PLI capital subsidy synchronization schedules, and EV powertrain adoption curves. Forecast inputs incorporate petroleum needle coke price volatility indices and crystal defect density improvement rates from domestic qualification programs.
Inputs from BIS certification registries and CEA grid code revision timelines were available through the study window; gaps in real-time crystal growth furnace order backlogs introduce uncertainty bands around domestic capacity expansion velocity. Forecasts reflect assumptions regarding PLI disbursement continuity and equipment import license processing efficiency. Periodic stress-testing of base assumptions against actual qualification timelines and substrate yield rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Yttrium Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Global Magnesium Oxide Nanopowder Market
Semiconductor Material
Europium Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Barium Titanate Market