
 Electronic Thermal Management Materials Market | 2026-2036
Electronic Thermal Management Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Thermal Management Materials Market Analysis
Asian polymer compounders is recalibrating capacity allocation toward high-thermal-conductivity formulations as data center buildouts accelerate. Henkel AG & Co. KGaA leverages its adhesive chemistry heritage to dominate thermal paste supply for telecommunications equipment. Boyd Corporation anchors North American production through vertically integrated die-cut gasket and thermal pad operations. 3M competes on fluoropolymer film technology leadership in thin-interface applications.
Electronic thermal management materials comprise engineered substances designed to conduct, dissipate, or store thermal energy at material interfaces, typically exhibiting thermal conductivities ranging from 1 W/m·K for filled polymers to 80 W/m·K for liquid metal alloys, manufactured through precision dispersion, calendering, or vapor deposition processes. These materials serve primarily to maintain semiconductor junction temperatures below critical thresholds, preventing thermal throttling and extending component operational life in power-dense electronics. Thermal interface materials command the largest volume share due to ubiquitous deployment across CPU-GPU packages and power module assemblies, while liquid metals within the form factor category represent the fastest-expanding margin pool as overclocking and high-performance computing segments tolerate premium pricing. Conductive polymers are gaining structural traction in automotive electronics where vibration resistance and conformal coating compatibility outweigh pure thermal performance metrics.
The EPA regulates fluorinated greenhouse gas emissions from semiconductor manufacturing processes, constraining material choices and pushing formulators toward PFAS-free thermal greases. REACH compliance in Europe mandates full substance disclosure for imported thermal management compounds, creating market access barriers for non-compliant Asian suppliers. China's GB standards for electronic product safety incorporate thermal cycling test protocols that effectively certify materials for domestic telecommunications equipment procurement. Stakeholders must monitor evolving substance restriction timelines to time formulation transitions ahead of regulatory enforcement windows.
Market Dynamics
EU F-Gas Regulation phase-down mandates are forcing thermal management compounders to eliminate high-GWP refrigerants and liquid carriers from interface material formulations, compressing R&D timelines and redirecting capital toward solid-state cooling substrates and PFAS-free chemistries.
Growth Catalysts
- Electric Vehicle Powertrain Thermal Loads:Battery pack energy densities above 300 Wh/kg generate heat flux exceeding 15 W/cm², necessitating advanced thermal interface materials between cells and cooling plates. Automotive OEMs in Germany's Stuttgart-Munich corridor are scaling procurement of phase-change materials and graphite sheets.
- REACH Substance Disclosure Mandates:Full chemical composition reporting requirements for imported thermal compounds create compliance-based market access barriers, advantaging European formulators with established substance registration databases over non-compliant Asian suppliers.
- Data Center Cooling Intensity:AI training clusters deploying H100 and MI300X accelerators push rack densities past 100 kW, driving demand for liquid metal thermal pastes and vapor chamber substrates in hyperscale facilities across Northern Virginia and Singapore.
Market Restraints
- Indium and Gallium Price Volatility:Liquid metal alloys depend on critical raw materials subject to export concentration from Chinese state-controlled refiners, creating input cost instability that constrains margin expansion for thermal paste formulators.
- PFAS Regulatory Friction:EPA fluorinated greenhouse gas emission limits and emerging state-level bans on perfluoroalkyl substances restrict fluoropolymer film options for thin-interface applications, eliminating established high-performance chemistries from qualified material lists.
- Thermal Grease Pump-Out Limitations:Silicone-based compounds suffer mechanical degradation under thermal cycling between -40°C and 150°C, limiting service life in automotive underhood environments and forcing premature replacement cycles.
Strategic Opportunities
- Solid-State Cooling Substrate Development:Electrocaloric and magnetocaloric ceramic materials offer refrigerant-free thermal management for precision electronics, with research programs at Fraunhofer Institute and MIT targeting commercialization for medical imaging equipment.
- India Electronics Manufacturing PLI Scheme:Production-linked incentives for semiconductor and telecom equipment assembly create localized demand for thermal pad and gap filler materials, with domestic compounders investing in calendering capacity near Chennai and Bengaluru.
- Telecom Infrastructure Thermal Retrofit:5G base station densification drives aftermarket replacement of legacy thermal greases with higher-conductivity formulations, particularly in Middle Eastern deployments where ambient temperatures exceed 50°C seasonally.
Industry Challenges
- Formulation Chemist Talent Scarcity:Expertise in boron nitride dispersion and silicone rheology modification concentrates among aging specialists at legacy Japanese and German material houses, constraining new entrant R&D velocity.
- Automotive Thermal Cycling Certification:OEM qualification protocols requiring 5,000-hour validated life testing extend new material approval timelines to 18-24 months, delaying revenue recognition for innovative substrate architectures.
- Multi-Physics Simulation Integration:Thermal interface material selection increasingly requires coupled thermal-mechanical-electrical modeling capabilities that exceed traditional supplier technical service competencies, creating specification support gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Thermal Management Materials Market |
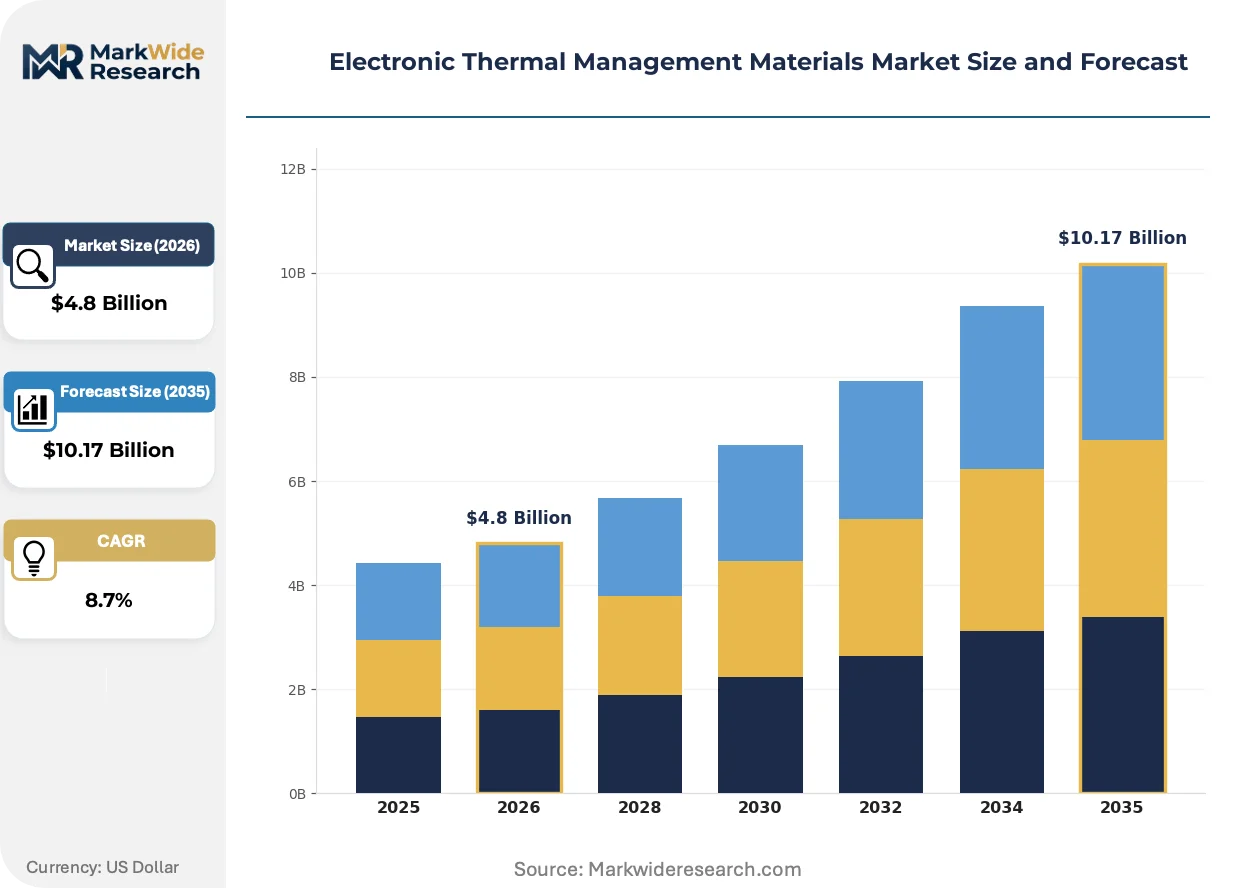
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Thermal Interface Materials, Phase Change Materials, Thermal Adhesives, Conductive Polymers Application: Consumer Electronics, Automotive Electronics, Telecommunications Equipment, Industrial Devices Form Factor: Films, Pastes, Liquid Metals, Coatings End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Electronics Manufacturers |
| Companies Covered | Boyd Corporation, Honeywell Electronic Materials, Indium Corporation, Carbice Corp., DuPont de Nemours, Henkel AG & Co. KGaA, Fujipoly, BNNano, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Thermal Management Materials Market Emerging Trajectories
Material science advances are compressing the performance gap between polymer composites and metal-based thermal solutions, while regulatory chemistry constraints accelerate bio-based and PFAS-free formulation development across automotive and consumer electronics supply chains.
Boron nitride nanotube fillers are converging with silicone elastomer matrices to produce thermal interface pads achieving 15-20 W/m·K conductivity without electrical conductivity. Electric vehicle battery pack engineers at multiple German OEMs are qualifying these formulations for cell-to-cell thermal isolation layers. This convergence is displacing traditional alumina-filled silicones in high-voltage applications where dielectric strength and thermal performance must coexist.
EPA fluorinated greenhouse gas emission reporting requirements for semiconductor fabrication facilities are constraining process chemical selections, indirectly pressuring thermal management material suppliers to eliminate fluorinated surfactants and carriers from gap filler formulations. Wafer processing equipment OEMs in Oregon and Arizona are now requiring full PFAS content disclosure from component suppliers. The restriction cascade is accelerating most acutely in advanced packaging applications where thin-interface films previously relied on fluoropolymer substrates.
Hyperscale data center operators are consolidating thermal material procurement under direct long-term supply agreements with compounders, bypassing traditional electronics distributor channels. Microsoft and Amazon Web Services qualification teams are conducting on-site audits of thermal paste blending operations in Malaysia and Thailand. This channel compression is most visible in Southeast Asian manufacturing clusters where captive supplier relationships now govern specification锁定 for GPU cooling assemblies.
Electronic Thermal Management Materials Market Segmentation
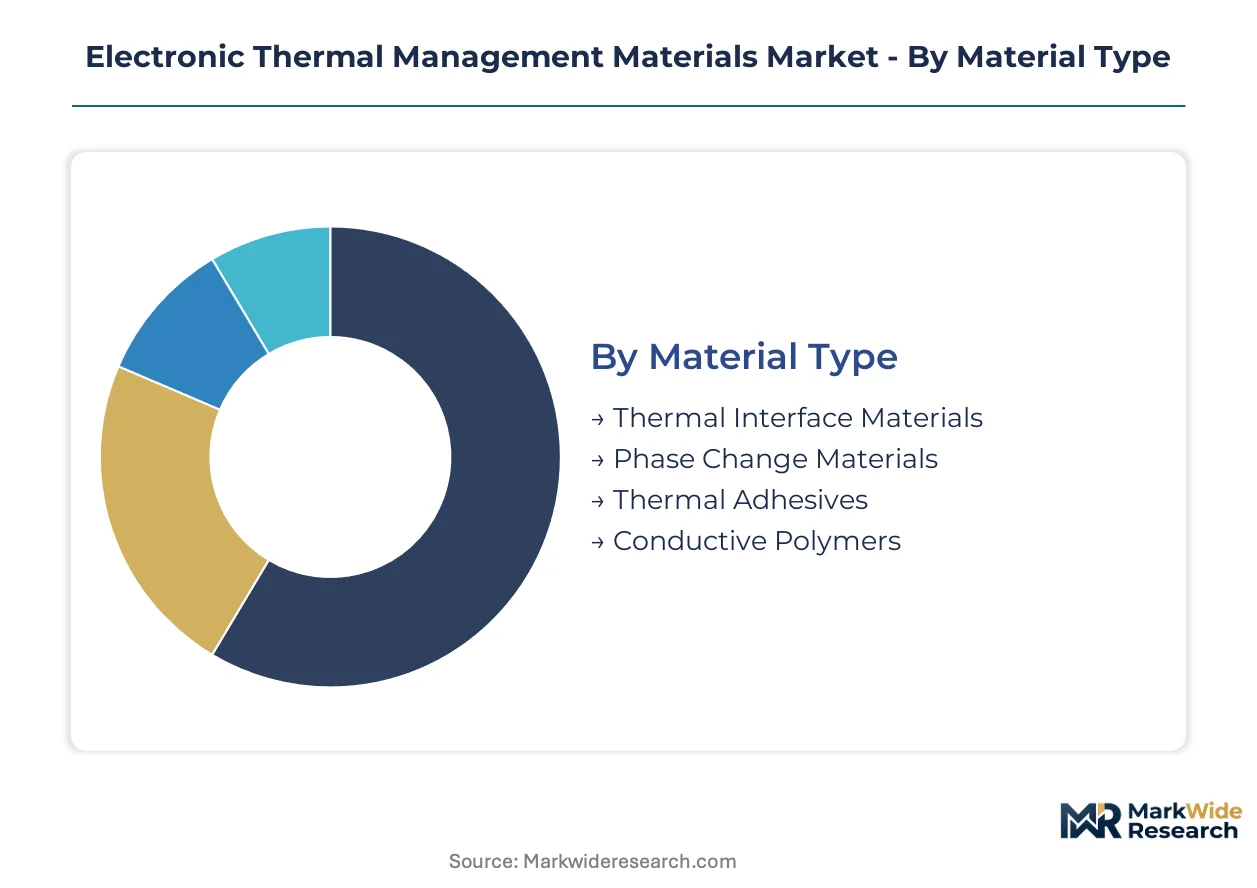
Thermal management materials serve divergent performance requirements across electronics ecosystems. Formulation chemistry, application environment, and supply chain proximity determine competitive positioning within each segment boundary.
Material Type:
Supply concentration clusters around formulators with captive boron nitride dispersion capabilities and silicone polymerization assets.
- Thermal Interface Materials:Silicone-based greases and gap fillers dominate volume deployment between heat spreaders and semiconductor packages. German automotive OEMs in Stuttgart and Munich are scaling procurement of phase-change variants for battery module assemblies.
- Phase Change Materials:Paraffin and salt hydrate formulations absorb latent heat at precise transition temperatures to buffer thermal spikes. EV powertrain engineers specify these for cell-to-cell isolation layers where passive thermal buffering prevents thermal runaway propagation.
- Thermal Adhesives:Henkel AG & Co. KGaA leverages adhesive chemistry heritage to supply telecommunications equipment manufacturers with conductive bonding compounds.
- Conductive Polymers:Automotive electronics applications favor these formulations where vibration resistance outweighs pure thermal conductivity metrics.
Today's leader: Thermal Interface Materials. Tomorrow's challenger: Phase Change Materials.
Application:
Cost tier stratification separates military-aerospace qualified formulations from consumer-grade commodity compounds.
- Consumer Electronics:Thin-film thermal pads and graphite sheets dissipate heat in smartphones and laptops. Assembly lines in Vietnam and Mexico specify standardized gap fillers under continuous cost-down pressure.
- Automotive Electronics:Underhood thermal cycling between -40°C and 150°C demands silicone formulations with validated 5,000-hour lifespans. Battery pack energy densities above 300 Wh/kg generate heat flux exceeding 15 W/cm², necessitating advanced interface materials between cells and cooling plates.
- Telecommunications Equipment:5G base station densification drives aftermarket replacement of legacy thermal greases with higher-conductivity formulations.
- Industrial Devices:Factory automation controllers and motor drives require thermally conductive encapsulants that withstand chemical washdown protocols.
Automotive Electronics commands premium pricing. Consumer Electronics drives volume scale.
Form Factor:
Application maturity separates established film and paste technologies from emerging liquid metal architectures.
- Films:Polyimide and fluoropolymer substrates with ceramic fillers provide thin-interface solutions for space-constrained assemblies. EPA fluorinated greenhouse gas emission constraints are eliminating fluoropolymer options from qualified material lists.
- Pastas:Silicone-based thermal greases remain the default solution for CPU-GPU packages despite pump-out limitations under thermal cycling. Hyperscale data center operators are consolidating procurement under direct long-term supply agreements with compounders.
- Liquid Metals:Eutectic gallium-indium-tin alloys achieve thermal conductivities up to 80 W/m·K for overclocking and AI accelerator applications. Indium and gallium price volatility from Chinese state-controlled refiners constrains margin expansion.
- Coatings:Spray-applied ceramic-filled polymers conform to complex geometries in automotive LED headlamp assemblies.
Pastas anchor current revenue. Liquid Metals are gaining share fastest in high-performance computing.
End User:
Customer type determines specification authority and procurement channel structure.
- OEMs:Automotive and consumer electronics brands retain direct relationships with material compounders for qualified product lists. German OEMs in the Stuttgart-Munich corridor specify thermal materials during platform development phases.
- Tier-1 Suppliers:Battery pack integrators and power module assemblers procure thermal interface materials under blanket orders tied to vehicle production schedules.
- Aftermarket Providers:Thermal paste replacement kits target enthusiast PC builders and telecom infrastructure maintenance contracts in Middle Eastern deployments where ambient temperatures exceed 50°C seasonally.
- Electronics Manufacturers:Contract assemblers in Malaysia and Thailand source thermal pads through distributor channels or captive supplier relationships under hyperscale operator qualification programs.
OEMs control specification. Tier-1 Suppliers concentrate procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest production footprint for boron nitride fillers, while Germany concentrates the most demanding automotive qualification standards. The United States anchors hyperscale data center procurement. Japan and South Korea supply precision dispersion equipment. India emerges as a contract manufacturing alternative.
United States
Hyperscale operators in Northern Virginia and Oregon drive liquid metal thermal paste procurement for AI training clusters. EPA fluorinated greenhouse gas emission reporting constrains fluoropolymer film options for semiconductor packaging. Oregon-based wafer processing equipment OEMs now require full PFAS content disclosure from thermal material suppliers.
Germany
Automotive OEMs in Stuttgart and Munich specify phase-change materials for battery packs exceeding 300 Wh/kg energy density. EU F-Gas Regulation phase-down mandates eliminate high-GWP refrigerants from thermal compound formulations. The Stuttgart-Munich corridor hosts the densest concentration of EV powertrain thermal engineering talent in Europe.
China
State-controlled refiners concentrate global indium and gallium supply, creating input cost volatility for liquid metal alloy formulators. GB standards for electronic product safety incorporate thermal cycling test protocols that certify materials for domestic telecommunications procurement. Yangtze River Delta compounders supply calendered thermal pads to Vietnam and Mexico assembly lines.
Japan
Legacy material houses concentrate expertise in boron nitride dispersion and silicone rheology modification. METI supports research programs targeting solid-state cooling substrates for medical imaging equipment. Chubu region specialists supply precision dispersion equipment to thermal paste blenders across Southeast Asia.
India
Production-linked incentives for semiconductor and telecom equipment assembly create localized demand for thermal pad materials. Domestic compounders invest in calendering capacity near Chennai and Bengaluru. Middle Eastern 5G base station retrofit contracts flow through Indian aftermarket distributors for high-conductivity thermal grease replacement.
Electronic Thermal Management Materials Market Vendor Landscape
German and Japanese producers anchor the premium tier with established automotive qualification databases; Chinese and Southeast Asian specialists hold volume positions in consumer electronics supply chains. The vendor base separates into three strata: legacy material houses with captive polymerization assets, mid-scale compounders serving regional electronics clusters, and niche innovators in nanostructured fillers. Consolidation pressures concentrate among thermal interface material formulators seeking boron nitride dispersion capabilities. Strategic moves center on backward integration into ceramic filler supply and geographic expansion toward Indian electronics manufacturing zones.
Among diversified industrial conglomerates, 3M and DuPont de Nemours occupy positions defined by fluoropolymer heritage now constrained by PFAS regulatory friction. Henkel AG & Co. KGaA exemplifies the adhesive-chemistry-to-thermal-materials extension path. These three represent how legacy industrial capabilities translate into thermal management market presence despite chemistry transition headwinds.
| Leading Market Players |
|---|
| Boyd Corporation |
| Honeywell Electronic Materials |
| Indium Corporation |
| Carbice Corp. |
| DuPont de Nemours |
| Henkel AG & Co. KGaA |
| Fujipoly |
| BNNano |
| 3M |
| Others |
Supply Flow & Price Mechanics
Specialist formulation chemists in Japan's Chubu region and Germany's Stuttgart-Munich corridor command wage premiums that widen pricing spreads between automotive-qualified thermal materials and consumer-grade commodity compounds. Labor-cost differentials between these heritage material houses and Southeast Asian compounders stratify the market into three performance tiers with distinct margin structures.
Pricing Analysis
Capacity additions in Malaysia and Thailand are reshaping price floors for silicone-based thermal greases and gap fillers, compressing margins for mid-scale compounders serving consumer electronics assembly lines. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified formulations with 5,000-hour thermal cycling certification from unvalidated commodity compounds. Price differentiation rests on REACH substance registration status and boron nitride filler dispersion quality. Cost compression in the standard tier intensifies because Vietnamese and Mexican contract assemblers prioritize landed cost over thermal performance metrics. Consumer electronics manufacturers exhibit highest price sensitivity, while German automotive OEMs tolerate premium positioning for qualified material lists.
Supply Chain Analysis
Workforce availability constraints in Japan and Germany limit expansion velocity for precision dispersion operations, pushing capacity growth toward Malaysia, Thailand, and India. Boron nitride filler supply concentrates in China, silicone polymer feedstock anchors in Germany and Japan, and liquid metal alloy production draws from Chinese state-controlled indium and gallium refiners. Raw material dependencies on critical mineral supply from single-source geographies create commodity price volatility that propagates through formulation costs. Single-source vulnerability in gallium supply from Chinese export licensing regimes exposes liquid metal thermal paste formulators to input cost instability. Distribution runs through hyperscale operator direct procurement agreements and traditional electronics distributor channels serving contract assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electronic Thermal Management Materials Market functions as a geographic-arbitrage play where compounders can capture margin expansion by relocating formulation capacity to India under PLI scheme incentives while maintaining automotive qualification relationships in Germany.
For Market Incumbents: Acquire boron nitride dispersion capability and captive silicone polymerization assets to defend against Asian compounders scaling high-thermal-conductivity formulations for data center procurement. Secure backward integration into ceramic filler supply chains to offset indium and gallium price volatility from Chinese state-controlled refiners. Invest in REACH substance registration databases to maintain compliance-based market access barriers against non-compliant suppliers. For New Entrants and Emerging Players: Indian telecom equipment assemblers represent an underserved buyer archetype where domestic compounders lack calendering capacity for thermal pad production. Target aftermarket retrofit contracts for 5G base stations in Middle Eastern deployments where ambient thermal stress accelerates replacement cycles. Pursue qualification partnerships with hyperscale data center operators consolidating procurement under direct supply agreements in Southeast Asia. For Investors and Strategic Acquirers: Adhesive chemistry specialists are the most active acquirer in this space, seeking thermal materials capabilities to extend formulation portfolios into power-dense electronics applications. Five-to-ten year viability hinges on successful PFAS-free chemistry transitions ahead of EPA enforcement windows and EU F-Gas Regulation phase-down mandates. Monitor indium and gallium export licensing patterns from Chinese state-controlled refiners as inflection indicator for liquid metal thermal paste margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Nitride Supply | Captive filler production insulates Henkel and 3M from Chinese supply concentration and price volatility. |
| PFAS-Free Formulation Transition | Elimination of fluorinated carriers ahead of EPA reporting mandates preserves qualification status with Oregon wafer equipment OEMs. |
| India Calendering Capacity Buildout | PLI scheme incentives enable domestic compounders near Chennai to serve localized telecom and semiconductor assembly demand. |
| Solid-State Cooling Substrate Development | Electrocaloric ceramics from Fraunhofer Institute programs offer refrigerant-free thermal management for medical imaging equipment. |
| Hyperscale Direct Supply Agreement | Microsoft and Amazon Web Services qualification programs in Malaysia bypass distributor channels and lock specification control. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with thermal interface material formulators, automotive OEM platform engineers, data center procurement specialists, and semiconductor packaging technologists with secondary validation against EPA fluorinated greenhouse gas emission filings, EU REACH substance registration databases, China GB standards documentation, and SEC 10-K disclosures from diversified material conglomerates. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Historical reference periods established baseline thermal conductivity performance tiers and pricing structures across material categories, with projection horizons extending through the analysis window. Segmentation dimensions modeled include material type chemistry, application environment severity, form factor maturity, and end-user procurement channel structure. CAGRs derived from coupled demand drivers spanning EV powertrain thermal load intensity, AI accelerator rack density trajectories, and regulatory chemistry constraint timelines. Forecast inputs incorporated indium and gallium price volatility patterns from Chinese state-controlled refiner export data.
Inputs from primary field interviews and secondary regulatory filings were available through the study window; gaps in real-time hyperscale operator procurement contract terms introduce uncertainty bands around direct supply agreement penetration rates. Forecasts reflect assumptions regarding EU F-Gas Regulation enforcement pacing and EPA PFAS restriction cascade timing. Material deviation in Chinese critical mineral export licensing regimes or automotive OEM thermal cycling certification protocol changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Tellurium Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Silicon Base Paper Market