
 Barium Titanate Market | 2026-2036
Barium Titanate Market Size, Share, and Industry Trends Forecast 2026-2036
Barium Titanate Market Analysis
Multi-source procurement of high-purity precursors is pivoting toward captive and near-shore arrangements as capacitor-grade specifications tighten. Sakai Chemical Industry Co., Ltd. leverages its integrated precursor-to-powder infrastructure to control batch consistency for MLCC manufacturers. Nippon Chemical Industrial Co., Ltd. anchors supply relationships with Japanese electronics OEMs through dedicated purity certification protocols. Shandong Sinocera Functional Materials Co., Ltd. competes on scale, operating some of the largest solid-state reaction furnaces outside Japan.
Barium titanate is a perovskite-structured ceramic oxide (BaTiO₃) with a Curie temperature near 120°C and dielectric constants exceeding 1,000 in polycrystalline form, manufactured primarily via solid-state calcination of barium carbonate and titanium dioxide or through hydrothermal and oxalate co-precipitation routes for submicron powders. Its primary commercial purpose centers on dielectric layers in multilayer ceramic capacitors, where thin-film formulations enable volumetric efficiency in compact electronics. The powder segment dominates volume throughput, though film-grade material commands premium pricing due to stringent particle size distribution requirements below 200 nanometers. Capacitor applications absorb the majority of output, while sensor and actuator demand in automotive pressure and piezoelectric systems represents the fastest-expanding application pool.
Japan's METI oversees national strategies for critical material security in electronic ceramics, while China's SAMR enforces GB standards for barium titanate purity and environmental discharge from calcination facilities. REACH registration requirements in Europe constrain import pathways for non-EU powder suppliers. Stakeholders must monitor divergence between Japanese JIS standards and Chinese GB specifications, as incompatible testing protocols threaten to fragment qualification pathways for global capacitor manufacturers.
Market Dynamics
Capacitor-grade barium titanate procurement is tightening around purity certification protocols as MLCC manufacturers consolidate supplier bases and China's GB standards diverge from Japanese JIS testing methodologies.
Growth Catalysts
- Automotive sensor electrification:Piezoelectric pressure and actuator systems in electric vehicles are absorbing specialized tetragonal-phase powders. German OEMs now specify sub-150 nanometer particle distributions for powertrain sensors.
- China's dual carbon goals:MEE discharge regulations are accelerating furnace upgrades at calcination facilities, inadvertently concentrating output among compliant producers with captive energy supply.
- Hydrothermal synthesis maturation:Continuous-flow reactor designs are reducing lot-to-lot variability for film-grade material. South Korean capacitor manufacturers are qualifying these powders for 5G base station modules.
Market Restraints
- Barium carbonate feedstock volatility:Mining concentration in Guizhou province creates price transmission risk to solid-state calcination economics.
- High-purity titanium dioxide supply concentration:Chloride-route pigment producers in Eastern China dominate electronics-grade TiO₂, constraining backward integration options for mid-tier powder manufacturers.
- Curie temperature limitation:Intrinsic 120°C phase transition restricts high-temperature automotive underhood applications, capping addressable market in power electronics thermal management.
Strategic Opportunities
- India's PLI scheme for electronics:Component manufacturing incentives are attracting MLCC assembly investment, creating virgin demand for qualified powder suppliers without incumbent relationships.
- Dielectric-piezoelectric convergence:Co-fired multilayer actuator structures are unifying capacitor and sensor material specifications, opening cross-selling to industrial automation OEMs.
- Direct material qualification platforms:Japanese electronics assemblers are bypassing trading houses to certify powder batches via blockchain traceability, shortening procurement cycles.
Industry Challenges
- Particle size metrology standardization:Incompatible laser diffraction protocols between JIS and GB testing methods are forcing dual certification costs on exporters.
- Calcination energy intensity:Solid-state reaction furnaces require sustained 1100°C operation, exposing producers to carbon border adjustment mechanisms under EU CBAM implementation.
- Thin-film deposition IP complexity:Sol-gel and chemical solution deposition patents held by Japanese research consortia complicate entry into film-grade material markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barium Titanate Market |
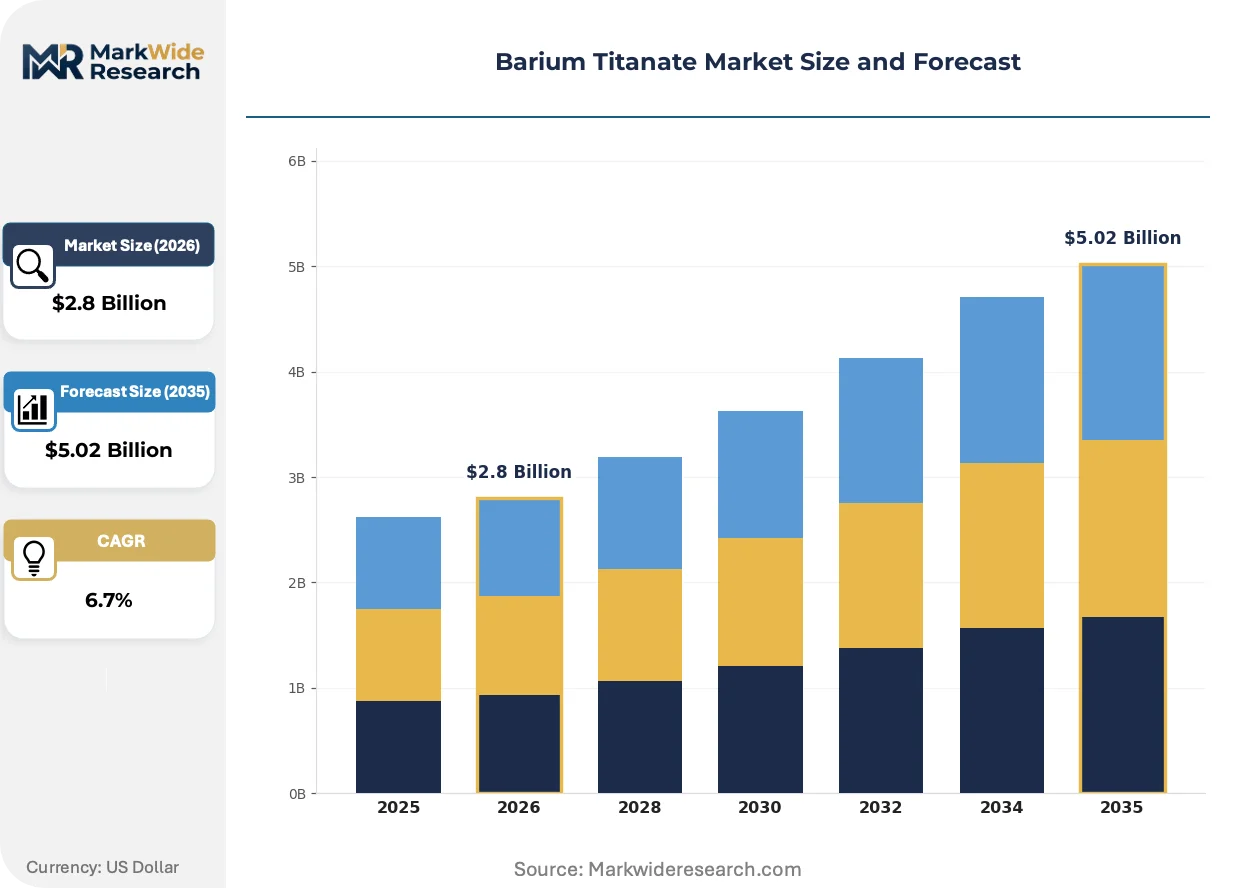
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Ceramic, Film, Single Crystal Application: Capacitors, Sensors, Actuators, Transducers End User: Electronics, Automotive, Healthcare, Telecommunications Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Sakai Chemical Industry Co., Ltd., Nippon Chemical Industrial Co., Ltd., Fuji Titanium Industry Co., Ltd., Shandong Sinocera Functional Materials Co., Ltd., Merck KGaA, KMC Corporation, Solvay, Guangdong Fenghua Advanced Technology Holding Co., Ltd., Divjyot Chemicals Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barium Titanate Market Emerging Trajectories
Barium titanate manufacturing is bifurcating between commodity powder for standard MLCCs and precision-engineered submicron material for advanced dielectric stacks, with process technology determining competitive position more than scale alone.
Hydrothermal barium titanate synthesis is unifying particle morphology control with dopant incorporation in a single reactor stage. Automotive tier-one suppliers are accelerating qualification timelines for these powders in pressure sensor membranes. This convergence is compressing the traditional separation between precursor preparation and crystallization phases, enabling lot-specific dielectric constant tuning.
REACH registration requirements for nano-scale ceramic powders are tightening substance characterization obligations for importers into the European Economic Area. ECHA guidance on perovskite oxide hazard classification is forcing reformulation of safety data sheets and downstream communication protocols. German capacitor distributors are consolidating supplier panels to reduce compliance administration burden, favoring established registrants over new market entrants.
Japanese electronics OEMs are compressing supplier qualification cycles from 18 months to 9 months for qualified second-source powder candidates. Trading houses in Osaka are losing intermediation value as direct manufacturer-to-assembler relationships deepen. This disintermediation is most visible in Kansai industrial corridor procurement patterns, where Sakai Chemical and Nippon Chemical Industrial now handle technical service directly rather than through regional distributors.
Barium Titanate Market Segmentation
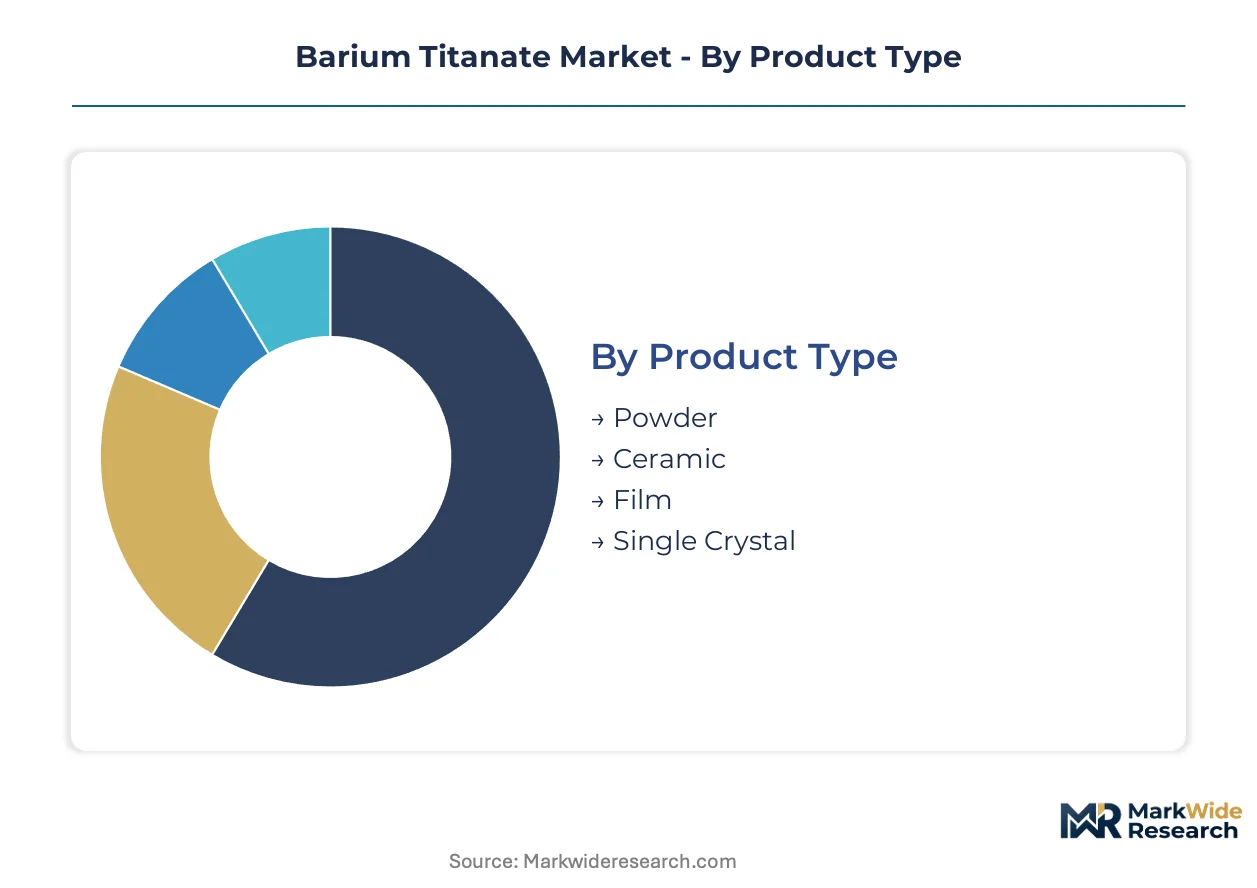
Barium titanate's commercial value hinges on precise material specifications that vary dramatically across capacitor dielectrics, piezoelectric sensors, and optical substrates. Segmentation by physical form and processing route determines pricing power, with sub-200 nanometer powders commanding multiples over standard calcined grades.
Product Type:
Particle morphology and crystallinity specifications differentiate competitive positioning across the four material formats.
- Powder:Polycrystalline BaTiO₃ manufactured via solid-state calcination or hydrothermal synthesis, with capacitor-grade material requiring submicron particle size distributions below 200 nanometers and tight dopant control for temperature-stable dielectric constants. Demand concentrates in Japan's Kansai industrial corridor where MLCC manufacturers specify lot-to-lot consistency for thin-film layer deposition. China's NMPA and evolving GB standards are tightening traceability requirements for high-purity precursor procurement.
- Ceramic:Sintered bulk ceramics for piezoelectric actuators and high-voltage capacitor discs, with tetragonal-phase stability and grain boundary engineering determining electromechanical coupling coefficients. German automotive OEMs now specify sub-150 nanometer particle distributions for powertrain pressure sensors, driving specialized powder demand.
- Film:Thin-film dielectric layers deposited via sol-gel, chemical solution deposition, or sputtering for embedded capacitors and frequency-tunable microwave devices. Patent complexity around deposition methodologies held by Japanese research consortia constrains new supplier entry.
- Single Crystal:Hydrothermally grown or top-seeded solution-grown monocrystalline BaTiO₃ for electro-optic modulators and high-sensitivity infrared detectors. Limited commercial volume reflects growth cycle economics and defect density challenges.
Powder leads on scale; film leads on momentum.
Application:
Functional requirements across the four application clusters create divergent material qualification pathways and pricing tiers.
- Capacitors:Multilayer ceramic capacitors absorb the majority of barium titanate output, with dielectric layer thickness reductions below one micron driving demand for ultra-fine hydrothermal powders. South Korean manufacturers are qualifying continuous-flow reactor material for 5G base station modules.
- Sensors:Piezoelectric pressure and acceleration sensors in electric vehicles represent the steepest expansion trajectory, with automotive tier-one suppliers accelerating qualification timelines for tetragonal-phase powders in sensor membranes.
- Actuators:Co-fired multilayer actuator structures are unifying capacitor and sensor material specifications, opening cross-selling opportunities to industrial automation OEMs requiring precision displacement control.
- Transducers:Ultrasonic medical imaging and industrial non-destructive testing equipment utilize doped barium titanate ceramics with tailored acoustic impedance matching.
Capacitors dominate volume throughput; sensors gain share fastest.
End User:
Customer technical capabilities and procurement sophistication determine supplier relationship structures and service intensity requirements.
- Electronics:Japanese electronics OEMs are compressing supplier qualification cycles from 18 months to 9 months for qualified second-source powder candidates, with direct manufacturer-to-assembler relationships displacing Osaka trading houses.
- Automotive:German OEM specifications for powertrain sensor materials are transmitting upstream to powder producers, with sub-150 nanometer particle distributions now mandatory for electrified vehicle platforms.
- Healthcare:Ultrasonic imaging equipment manufacturers require consistent piezoelectric response across temperature ranges, with REACH registration requirements for nano-scale ceramic powders tightening importer obligations into the European Economic Area.
- Telecommunications:5G infrastructure deployment is driving demand for high-frequency stable dielectrics, with base station module manufacturers qualifying new powder sources for reduced equivalent series resistance.
Electronics anchors procurement volume; automotive climbs the fastest.
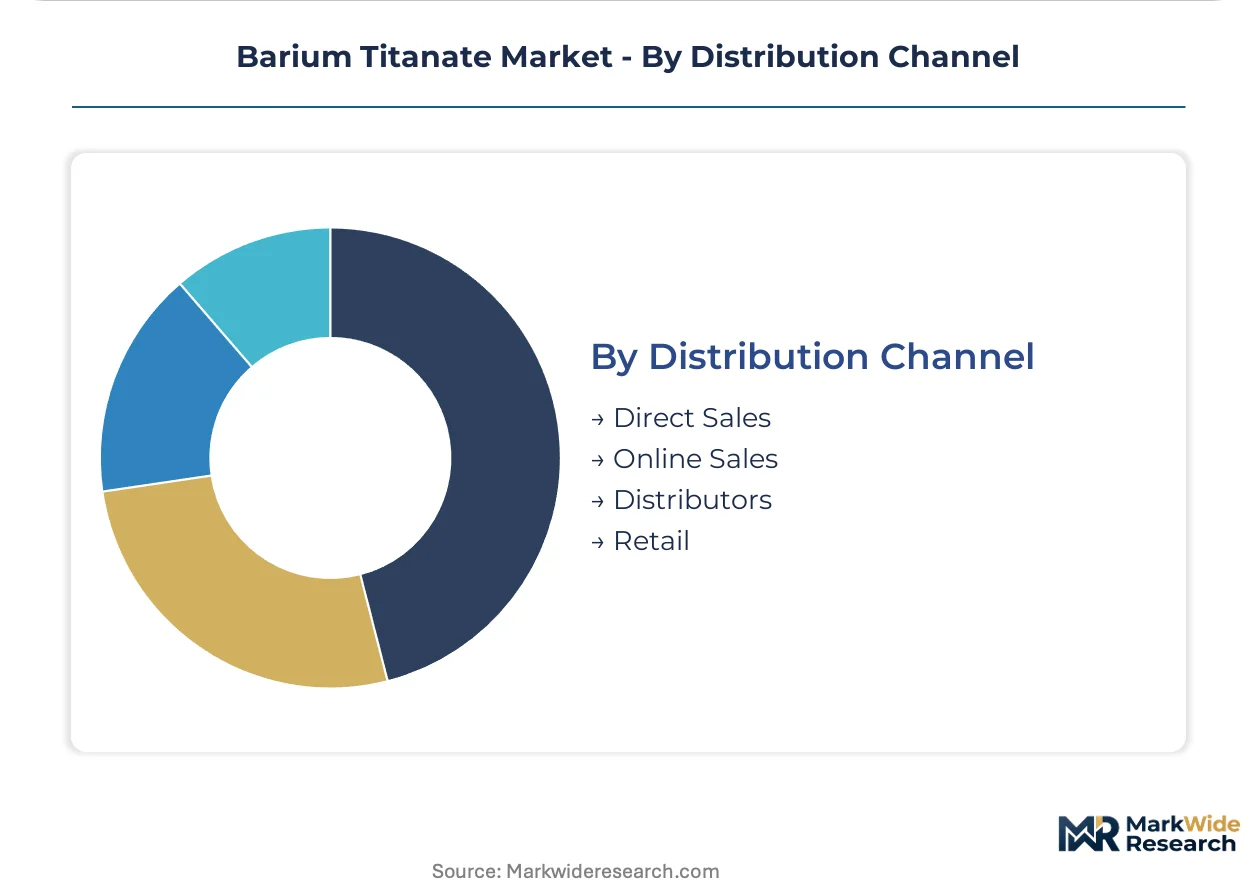
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and supply chain traceability mandates.
- Direct Sales:Large-volume MLCC manufacturers in East Asia negotiate directly with Sakai Chemical Industry and Nippon Chemical Industrial for captive supply arrangements with dedicated purity certification protocols.
- Online Sales:Research quantities and prototyping materials move through specialized chemical supply platforms serving universities and small-scale electronics developers.
- Distributors:German capacitor distributors are consolidating supplier panels to reduce REACH compliance administration burden, favoring established registrants over new market entrants.
- Retail:Limited to hobbyist electronics and educational supply, with minimal commercial significance for industrial-grade material.
Direct sales commands the premium tier; distributors handle compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Kansai industrial corridor anchors capacitor-grade barium titanate procurement, with MLCC manufacturers consolidating supplier bases around integrated precursor-to-powder producers. Procurement patterns across East Asia, Europe, and North America diverge sharply on purity certification protocols and regulatory alignment.
Japan
MLCC dielectric layer specifications below one micron drive demand for ultra-fine hydrothermal powders in Osaka and Kyoto manufacturing clusters. METI oversees national strategies for critical material security in electronic ceramics, tightening traceability mandates. Sakai Chemical Industry and Nippon Chemical Industrial anchor supply relationships through direct technical service rather than trading house intermediation.
China
Shandong province hosts some of the largest solid-state reaction furnaces outside Japan, with scale-driven producers competing on volume throughput. NMPA and evolving GB standards for electronic ceramics are tightening material traceability requirements, while MEE discharge regulations accelerate furnace upgrades. The Yangtze River Delta concentrates capacitor assembly operations demanding qualified powder supply.
Germany
Automotive OEMs specify sub-150 nanometer particle distributions for powertrain pressure sensors in electrified vehicle platforms. REACH registration requirements constrain import pathways for non-EU powder suppliers, favoring established registrants. German capacitor distributors consolidate supplier panels to reduce compliance administration burden across Bavaria and Baden-Württemberg industrial regions.
South Korea
5G base station module manufacturers qualify continuous-flow reactor powders for reduced equivalent series resistance in high-frequency applications. Domestic capacitor producers accelerate qualification timelines for hydrothermal synthesis material. The Seoul Capital Area concentrates electronics assembly investment absorbing specialized tetragonal-phase powders.
United States
Embedded capacitor and frequency-tunable microwave device research drives thin-film dielectric demand in Greater Boston and Pacific Northwest technology corridors. EPA environmental discharge oversight affects calcination facility planning, though domestic powder production remains limited. Research quantities move through specialized chemical supply platforms serving universities and small-scale developers.
Barium Titanate Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hydrothermal synthesis specialization and automotive sensor qualification pathways. The market structures around three tiers: integrated Japanese precursor-to-powder operators, scale-driven Chinese calcination specialists, and European chemical conglomerates with REACH-registered nano-material portfolios. Strategic archetypes include captive supply arrangers, purity certification protocol developers, and continuous-flow reactor technology adopters. Capacity expansion and direct manufacturer-to-assembler relationship building constitute the dominant competitive moves.
Among integrated Japanese operators, Sakai Chemical Industry Co., Ltd. and Nippon Chemical Industrial Co., Ltd. represent the precursor-to-powder archetype, occupying positions that emphasize batch consistency control. Shandong Sinocera Functional Materials Co., Ltd. exemplifies the scale-driven Chinese specialist tier. Merck KGaA and Solvay sit within the European chemical conglomerate archetype, leveraging REACH registration status to anchor supply relationships with consolidated distributor panels.
| Leading Market Players |
|---|
| Sakai Chemical Industry Co., Ltd. |
| Nippon Chemical Industrial Co., Ltd. |
| Fuji Titanium Industry Co., Ltd. |
| Shandong Sinocera Functional Materials Co., Ltd. |
| Merck KGaA |
| KMC Corporation |
| Solvay |
| Guangdong Fenghua Advanced Technology Holding Co., Ltd. |
| Divjyot Chemicals Private Limited |
| Others |
Supply Flow & Price Mechanics
Family-owned Japanese precursor-to-powder specialists anchor supply discipline through captive barium carbonate sourcing and long-term offtake contracts with Kansai corridor MLCC manufacturers. This ownership structure insulates batch consistency premiums from spot-market volatility while concentrating pricing power among integrated producers with METI-recognized critical material security status.
Pricing Analysis
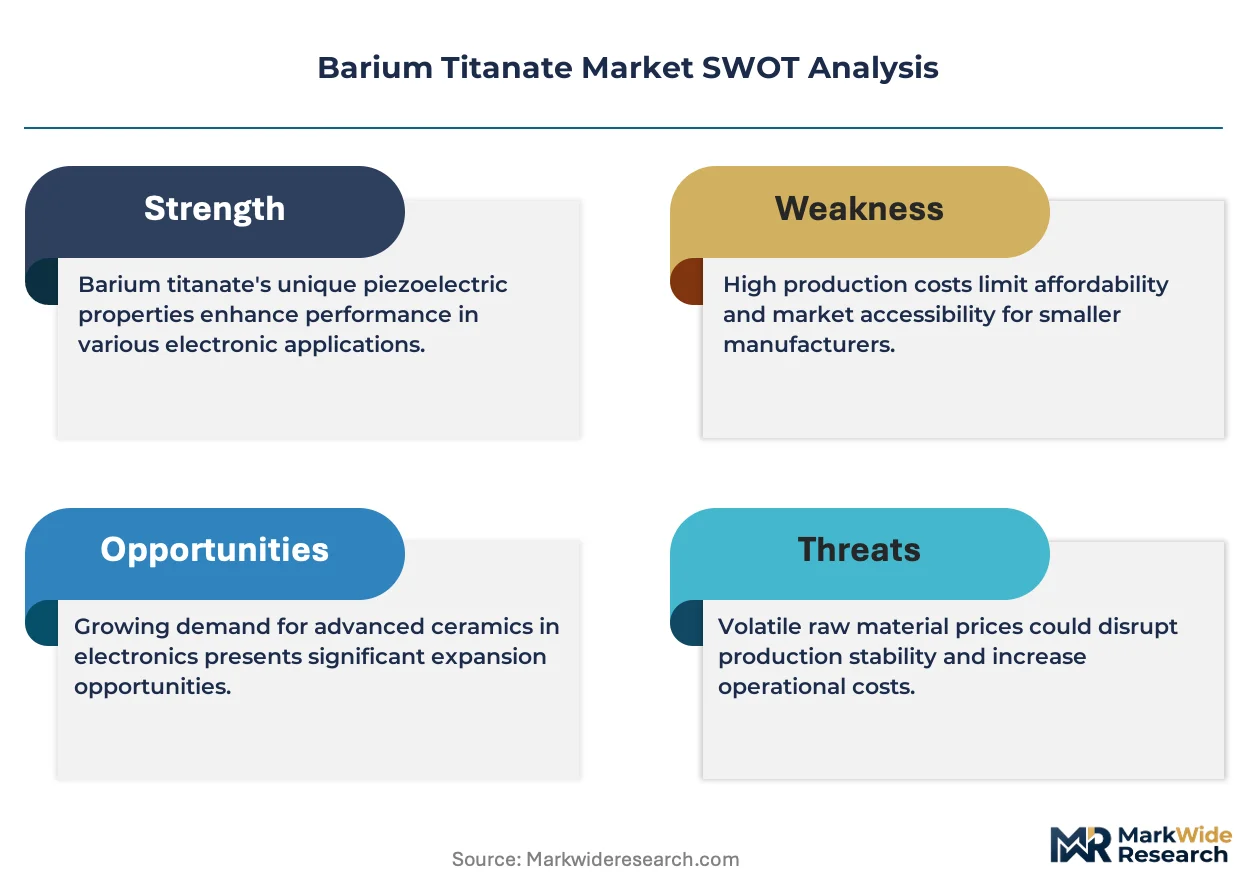
Barium carbonate feedstock volatility in Guizhou province transmits directly into solid-state calcination economics, forcing contract-based long-term offtake structures for volume buyers. Pricing stratifies across film-grade hydrothermal powders, standard capacitor-grade calcined material, and commodity ceramic grades, with certification to JIS versus GB testing protocols commanding spreads. Cost compression in standard-grade material is intensifying because Shandong furnace operators compete on scale without backward integration into titanium dioxide. Automotive sensor manufacturers show least price sensitivity due to sub-150 nanometer specification rigidity, while industrial ceramic disc buyers absorb greatest pressure from energy cost pass-through.
Supply Chain Analysis
Specialized chemical engineering talent scarcity in Shandong and Osaka constrains furnace operator training and continuous-flow reactor commissioning timelines. Supply concentrates in Japan, China, and South Korea, with hydrothermal synthesis capacity expanding fastest in the Seoul Capital Area. The chain draws from Guizhou barium carbonate mines, Eastern China chloride-route titanium dioxide, and Japanese dopant precursor specialists. Single-source vulnerability runs through electronics-grade TiO₂ concentration in Eastern China. Distribution runs through direct manufacturer-to-assembler relationships displacing Osaka trading houses, with REACH-registered European distributors handling compliance-heavy research quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with China's evolving GB standards and MEE discharge regulations accelerating furnace consolidation among compliant producers. The divergence between Japanese JIS and Chinese GB testing methodologies threatens to fragment qualification pathways for global capacitor manufacturers.
For Market Incumbents: Acquire continuous-flow reactor engineering teams to secure hydrothermal synthesis capability ahead of automotive sensor qualification waves. Consolidate backward integration into barium carbonate through offtake agreements with Guizhou mining operators, defending against scale-driven Chinese calcination specialists. METI critical material security designations offer leverage for captive supply arrangements with panicked MLCC manufacturers seeking dual-source redundancy. For New Entrants and Emerging Players: Indian MLCC assembly operators under the PLI scheme represent virgin demand without incumbent supplier relationships, offering entry without 18-month qualification cycles. Target automotive tier-one pressure sensor membrane specifications, where sub-150 nanometer tetragonal-phase powder shortages create technical moats against commodity competitors. Pursue blockchain traceability certification to bypass trading house intermediation and compress procurement cycles directly with Japanese electronics OEMs. For Investors and Strategic Acquirers: Valuations sit cheapest among scale-driven Chinese calcination specialists facing MEE compliance upgrade costs and carbon border adjustment exposure. Long-term viability favors hydrothermal synthesis technology holders with automotive qualification pipelines and REACH nano-material registration status. Watch for divergence resolution between JIS and GB particle size metrology protocols as inflection indicator for qualification cost normalization and cross-border supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barium Carbonate | Captive Guizhou mining offtake insulates Sakai Chemical and Nippon Chemical from feedstock volatility transmitted through spot carbonate markets. |
| Hydrothermal Synthesis Capacity Expansion | Continuous-flow reactor adoption by South Korean manufacturers enables qualification for 5G base station modules demanding reduced equivalent series resistance. |
| REACH Nano-Material Registration | Merck KGaA and Solvay leverage ECHA compliance status to anchor German distributor panel consolidation favoring established registrants. |
| Direct Manufacturer Certification Platforms | Blockchain traceability adoption by Japanese electronics OEMs disintermediates Osaka trading houses and compresses qualification cycles to nine months. |
| Automotive Sensor Material Qualification | Tetragonal-phase powder certification for German OEM powertrain specifications opens fastest-expanding application pool beyond traditional capacitor demand. |
Methodological Framework
Coverage spans East Asia, Europe, and North America, with primary inputs from each region combined with secondary validation. Interviews with MLCC procurement directors, hydrothermal synthesis plant managers, automotive tier-one sensor engineers, and REACH compliance officers anchored demand-side and supply-side perspectives. Secondary sources included Japan METI critical material security filings, China MEE environmental discharge records, ECHA nano-material registration databases, and SEC disclosures from electronics OEMs. Bottom-up powder volume estimates triangulated against top-down capacitor dielectric layer consumption models.
Rate-of-change decomposition separated volume growth from value growth across the projection horizon. Segmentation dimensions modeled included physical form tier, application cluster, end-user industry sophistication, and regional regulatory framework alignment. CAGRs derived from fitted growth curves incorporating hydrothermal synthesis adoption rates, automotive sensor content per vehicle trajectories, and 5G infrastructure deployment patterns. Industry-specific inputs captured furnace energy intensity trends under EU CBAM implementation and divergence momentum between JIS and GB testing protocols.
Inputs from METI strategy documents, MEE discharge filings, and ECHA guidance were available through the study window; gaps in real-time furnace utilization rates at Shandong calcination facilities introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented assumptions regarding GB-JIS protocol convergence timelines and automotive qualification acceleration curves. Material deviation in named regulatory triggers or hydrothermal synthesis yield breakthroughs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Polysilicon for Solar Semiconductor Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
Indium Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Fullerene Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Europium Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Big Size Synthetic Diamond Market