
 Yttrium Market | 2026-2036
Yttrium Market Size, Share, and Industry Trends Forecast 2026-2036
Yttrium Market Outlook
Australian rare earth concentrate output is rebalancing as Lynas Rare Earths scales downstream separation capacity at its Kalgoorlie facility. The company leverages integrated mine-to-oxide processing to secure supply chain autonomy. American Elements sustains a broad rare earth catalog spanning high-purity metals and compounds for North American buyers. China Minmetals Rare Earth anchors regional pricing through its control of ion-adsorption clay deposits in southern provinces.
Yttrium is a transition metal with atomic number 39, typically refined to 99.9% purity through solvent extraction of monazite or bastnäsite concentrates; its principal commercial purpose centers on phosphor production for displays and solid-state lighting, plus high-temperature superconducting films. Phosphors applications dominate volume consumption due to persistent demand from LED backlighting and fluorescent lamp sectors, while superconductors represent the fastest-expanding segment as second-generation coated conductors achieve commercial scale. Industrial grade material captures the largest revenue pool, though reagent grade commands premium pricing from medical device and aerospace contractors.
China's Ministry of Industry and Information Technology governs rare earth production quotas and export licensing, directly constraining international yttrium oxide availability. REACH registration requirements in Europe mandate full toxicological dossiers for yttrium compound importers, elevating compliance costs for non-EU suppliers. Stakeholders must monitor quota announcements from Beijing and stockpile strategies from Japanese METI-sponsored consortia to anticipate supply interruptions.
Market Dynamics
China's Ministry of Industry and Information Technology production quotas function as the decisive chokepoint, constraining international yttrium oxide flows while phosphor manufacturers in Japan and South Korea scramble for supply security.
Growth Catalysts
- Second-generation coated conductors:Superconductor manufacturers in Japan are scaling deposition capacity for YBCO tape, pulling high-purity yttrium demand upward as fusion and grid projects advance.
- RoHS compliance deadlines:European lighting manufacturers face mandatory mercury-free transitions, forcing LED phosphor reformulations that favor yttrium-based red emitters.
- Ion-adsorption clay deposits:Southern Chinese provinces retain the world's lowest-cost heavy rare earth extraction, sustaining price-competitive feedstock for oxide refiners.
Market Restraints
- Export licensing friction:Beijing's quota-to-license pipeline creates 6-12 month procurement lead times for non-Chinese buyers, forcing costly inventory buffers.
- Terbium substitution in phosphors:Lighting formulators are partially substituting yttrium-gadolinium systems where color rendering requirements permit, capping volume growth in mature applications.
- Solvent extraction capex intensity:Monazite cracking and multi-stage SX circuits require $200M-plus facility investments, blocking new Western entrants.
Strategic Opportunities
- Medical laser diodes:Yttrium aluminum garnet crystal demand from surgical equipment manufacturers in Germany and Switzerland is outpacing general industrial growth.
- Plasma-facing components:ITER and private fusion ventures are qualifying yttria coatings for divertor armor, opening a 10-year qualification pipeline.
- Japanese METI stockpiling:State-sponsored strategic reserves create offtake guarantees for qualified suppliers, de-risking capacity expansion decisions.
Industry Challenges
- Rare earth separation chemistry expertise:The pool of engineers capable of optimizing fractional crystallization and ion exchange circuits is concentrated in Chinese state laboratories and a handful of Australian operations.
- REACH dossier completion:European importers face 18-24 month toxicological study timelines for yttrium compound registrations, delaying market access.
- Legacy fluorescent lamp retirement curves:Phosphor demand forecasting requires precise modeling of regional lamp replacement rates, which vary dramatically between North American utility programs and European commercial retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yttrium Market |
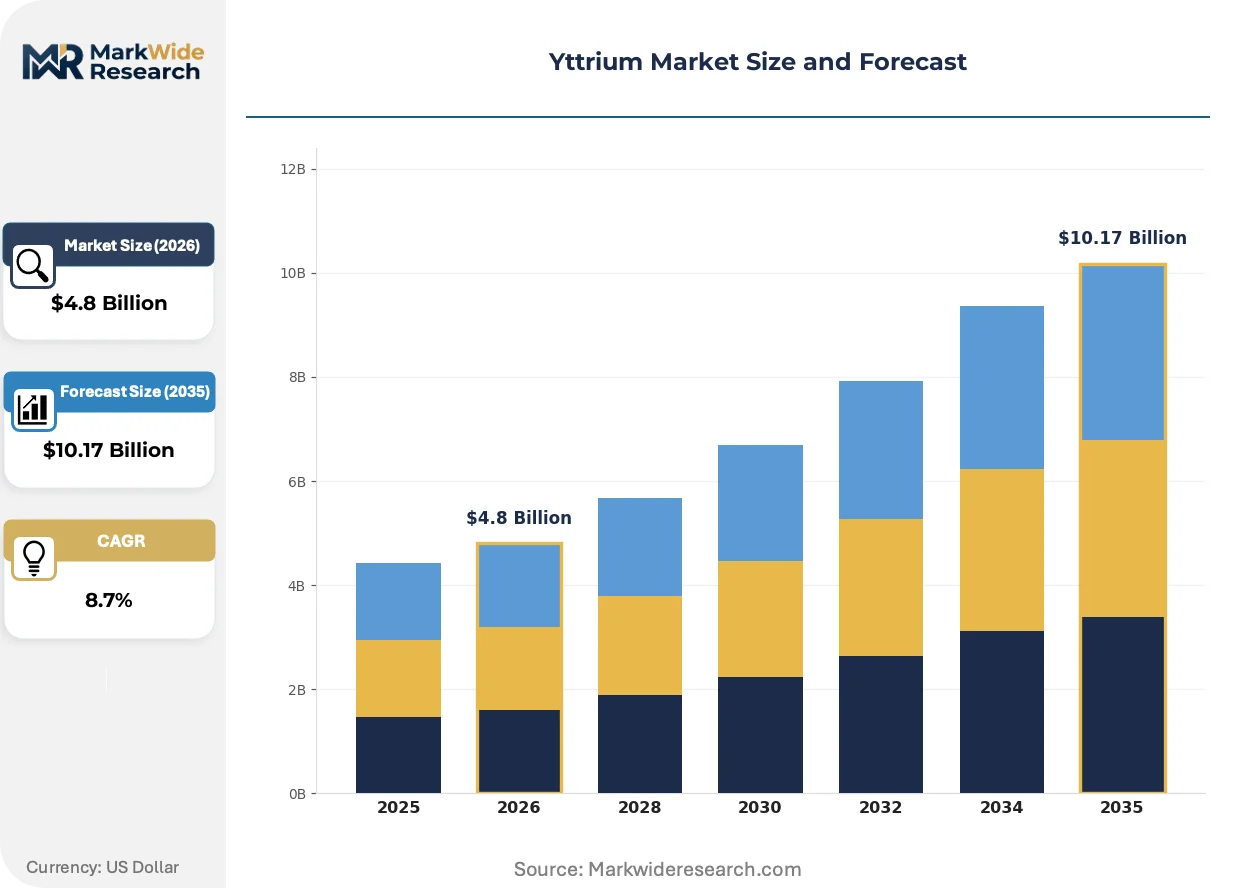
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yttrium Oxide, Yttrium Iron Garnet, Yttrium Aluminum Garnet, Yttrium Phosphate End User: Electronics, Energy, Aerospace, Medical Devices Application: Phosphors, Superconductors, Catalysts, Ceramics Grade: Industrial Grade, Reagent Grade, Analytical Grade, Others |
| Companies Covered | Alkane Resources, Metall Rare Earth Limited, Lynas Rare Earths, Ganzhou Rare Earth Mineral Industry, Nippon Yttrium Co., Ltd, China Minmetals Rare Earth, American Elements, The Nilaco Corporation, Goring Rare Earth Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yttrium Market Strategic Shifts
Technical and procurement patterns are converging around supply chain regionalization, with buyers prioritizing qualified non-Chinese sources even at cost premiums.
Sol-gel derived yttrium oxide nanopowders are consolidating as the preferred feedstock for advanced phosphor synthesis. LED manufacturers in Taiwan and South Korea are transitioning from conventional micron-scale powders to nanostructured precursors that enable higher packing densities and improved thermal quenching resistance. This material shift is consolidating supplier tiers, as only separation houses with spray pyrolysis or hydrothermal capabilities can meet specifications.
REACH Annex XVII restrictions on persistent organic pollutants are tightening impurity thresholds for rare earth imports into Europe. ECHA guidance documents now require sub-ppm certification for certain thorium and uranium decay chain elements in yttrium compounds used in consumer electronics. German and French lighting OEMs are responding by mandating dedicated supply chains with radiological screening at mine concentrate stage.
Long-term offtake contracting is displacing spot market purchasing for high-purity grades. Japanese superconductor wire producers and Korean display panel manufacturers are locking in 3-5 year supply agreements directly with Australian and Malaysian separation facilities. This procurement pattern is most visible in Tokyo-Osaka industrial corridor, where METI-backed consortia coordinate collective bargaining for strategic material security.
Yttrium Market Segmentation
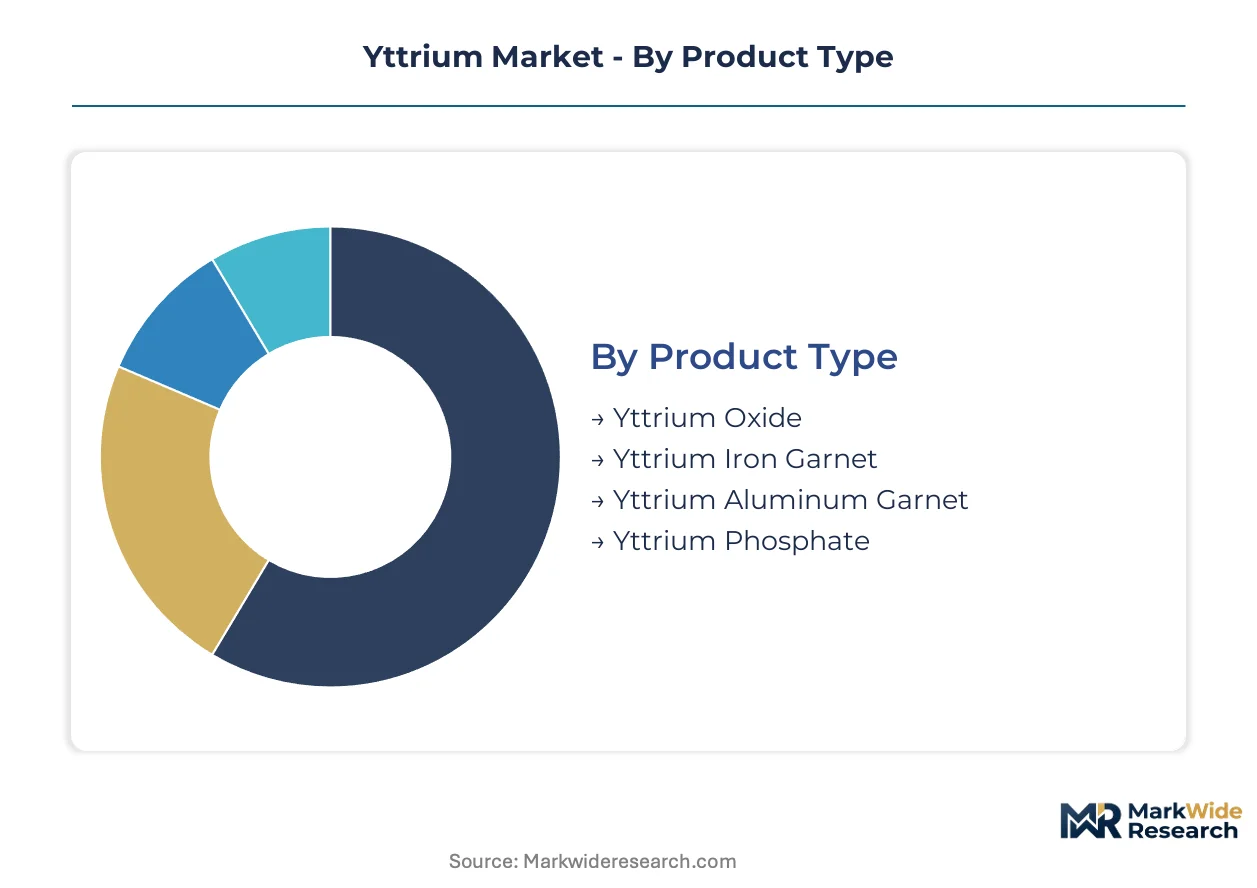
Yttrium's chemical versatility creates distinct value pools across purity levels and compound forms. Buyers prioritize specification matching over cost minimization, given the performance-critical nature of phosphor and superconductor applications.
Product Type:
Buyers select yttrium compounds based on thermal stability requirements and crystal lattice compatibility with target substrates.
- Yttrium Oxide:Refined to 99.9% purity through solvent extraction, this oxide serves as the foundational feedstock for phosphor synthesis and ceramic stabilization. LED manufacturers in Taiwan specify nanostructured powders with sub-micron particle distributions to maximize packing density in red-emitting phosphor layers.
- Yttrium Aluminum Garnet (YAG):Synthetic single crystals grown by the Czochralski method provide the gain medium for Nd:YAG lasers used in surgical equipment. German and Swiss medical device manufacturers account for concentrated demand as diode-pumped solid-state systems displace gas lasers in dermatology and ophthalmology.
- Yttrium Iron Garnet (YIG):Ferrimagnetic properties enable microwave isolators and circulators in radar systems.
- Yttrium Phosphate:Host lattice for europium-activated red phosphors in compact fluorescent lamps.
Yttrium oxide leads on scale; yttrium aluminum garnet leads on momentum.
End User:
Volume concentration tracks regional manufacturing specialization in display fabrication and advanced materials processing.
- Electronics:Display panel manufacturers in South Korea and Taiwan consume yttrium oxide for LED backlight phosphors and PDP electrode materials. RoHS compliance deadlines in Europe are accelerating mercury-free lamp transitions that favor yttrium-based formulations.
- Energy:Superconductor wire producers in Japan scale YBCO tape deposition capacity for grid stabilization and fusion magnet applications. ITER qualification protocols are extending procurement timelines for high-purity feedstock.
- Aerospace:Thermal barrier coatings on turbine blades utilize yttria-stabilized zirconia.
- Medical Devices:Solid-state laser crystals and radiopharmaceutical carriers.
Electronics dominates current offtake; energy applications are climbing the fastest.
Application:
Technical specifications diverge sharply between commodity phosphor feedstock and specialized superconducting film precursors.
- Phosphors:Europium-doped yttrium compounds generate red emission in white LED architectures. Korean and Taiwanese LED packagers specify tight particle size distributions to minimize thermal quenching in high-power devices.
- Superconductors:Metal-organic deposition of YBCO films on buffered metal substrates requires 99.99% purity yttrium with controlled impurity profiles. Japanese wire manufacturers are expanding deposition capacity as fusion projects advance toward reactor construction.
- Catalysts:Ethylene polymerization and automotive exhaust treatment.
- Ceramics:Stabilized zirconia for oxygen sensors and structural components.
Phosphors anchor volume consumption; superconductors show the steepest expansion trajectory.
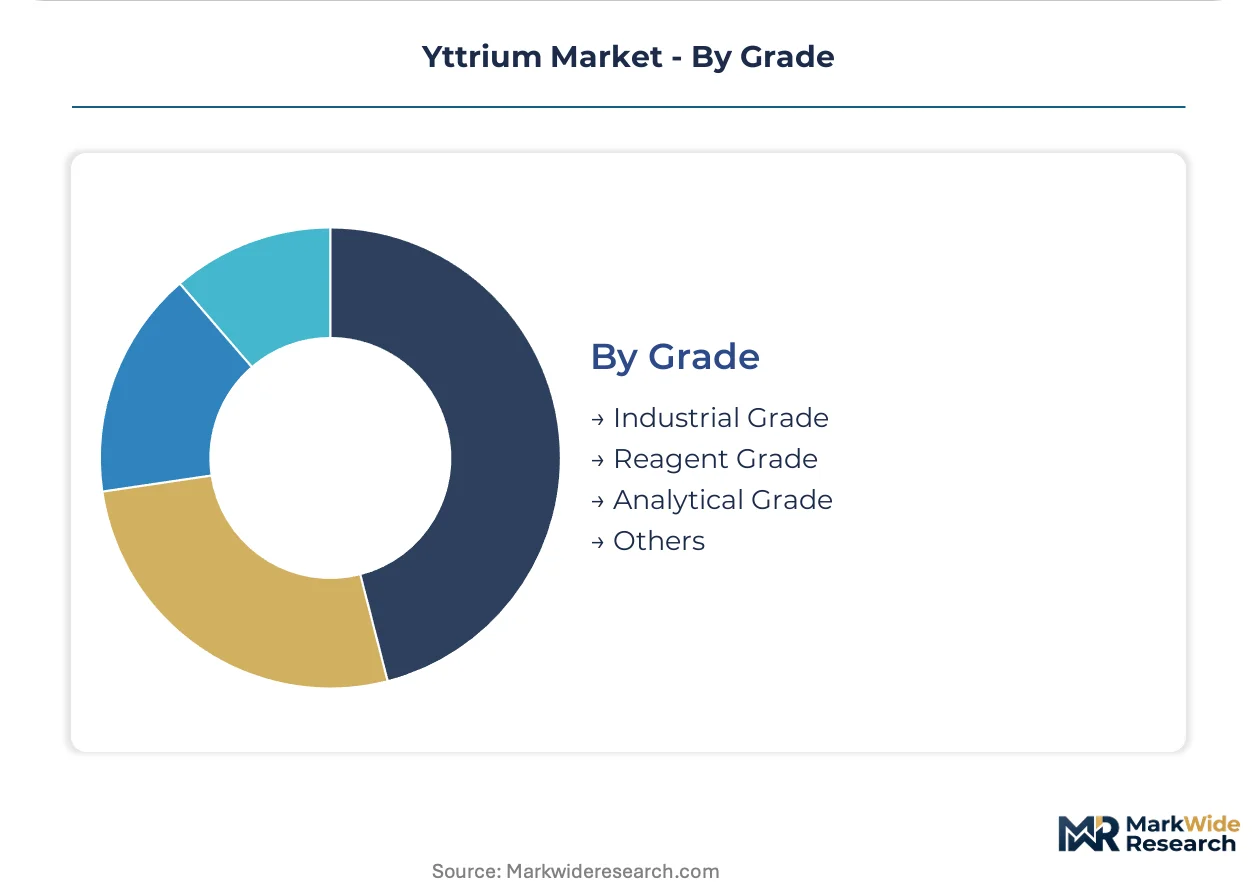
Grade:
Purity thresholds determine qualification for regulated applications in medical devices and aerospace systems.
- Industrial Grade:99.0-99.5% purity material satisfies phosphor synthesis and bulk ceramic applications. Chinese separation houses supply this tier through quota-licensed export channels with 6-12 month lead times.
- Reagent Grade:99.9%+ purity with certified impurity profiles enables pharmaceutical and analytical applications. REACH registration requirements in Europe mandate full toxicological dossiers that extend market access timelines for non-EU suppliers.
- Analytical Grade:Ultra-high purity for reference standards and research.
- Others:Custom specifications for specialized industrial processes.
Industrial grade captures the revenue base; reagent grade commands the widest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting rare earth processing investments toward jurisdictions with streamlined permitting, as China's export licensing creates compliance-cost gaps that Australian and North American operators exploit to capture premium-tier offtake.
China
MIIT production quotas and export licensing frameworks constrain international yttrium oxide flows, forcing Japanese and Korean buyers into extended procurement cycles. The dual carbon goals policy is accelerating environmental compliance costs at ion-adsorption clay operations in Jiangxi and Guangdong provinces. Ganzhou Rare Earth Mineral Industry anchors heavy rare earth separation capacity in the southern corridor.
Japan
METI-sponsored strategic stockpiling programs guarantee offtake for qualified non-Chinese suppliers, de-risking capacity expansion decisions by Australian separation houses. The PMDA regulates yttrium-containing medical devices through stringent purity certification requirements. Superconductor wire manufacturers in the Tokyo-Osaka industrial corridor are scaling YBCO tape deposition capacity for fusion magnet applications.
Australia
Lynas Rare Earths leverages integrated mine-to-oxide processing at its Kalgoorlie facility to secure supply chain autonomy for Western buyers. The country's national resources regulator oversees radiological handling standards that align with European REACH thresholds. Western Australian concentrate output is rebalancing toward downstream separation rather than raw ore export.
South Korea
Display panel manufacturers in the Seoul Capital Area consume yttrium oxide for LED backlight phosphors under tight particle size specifications. The MFDS regulates medical laser crystal imports through device registration pathways that favor established suppliers. Korean LED packagers are transitioning to nanostructured yttrium precursors for improved thermal quenching resistance.
Germany
ECHA REACH registration requirements mandate full toxicological dossiers for yttrium compound importers, elevating compliance costs for non-EU suppliers seeking market access. The country's national pharmaceutical regulator oversees yttrium-aluminum-garnet crystals in surgical laser systems. Medical device manufacturers in Bavaria and Baden-Württemberg specify reagent-grade material with certified impurity profiles.
Yttrium Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue integrated mine-to-oxide models that bypass Chinese export bottlenecks. The vendor base stratifies across state-linked Chinese separation houses, Australian integrated operators, and North American specialty chemical distributors. Three archetypes dominate: quota-licensed Chinese refiners with clay-deposit feedstock, Western integrated miners with separation autonomy, and regional distributors with reagent-grade catalog depth. Competitive moves center on backward integration into concentrate supply and long-term offtake contracting with Japanese METI-backed consortia.
Among Australian integrated operators, Lynas Rare Earths exemplifies the mine-to-oxide archetype through its Kalgoorlie separation facility. American Elements occupies a position within the North American specialty distribution tier, sustaining broad rare earth catalogs for qualified buyers. China Minmetals Rare Earth represents the state-linked refiner archetype, anchoring regional pricing through control of ion-adsorption clay deposits in southern provinces.
| Leading Market Players |
|---|
| Alkane Resources |
| Metall Rare Earth Limited |
| Lynas Rare Earths |
| Ganzhou Rare Earth Mineral Industry |
| Nippon Yttrium Co., Ltd |
| China Minmetals Rare Earth |
| American Elements |
| The Nilaco Corporation |
| Goring Rare Earth Corporation Limited |
| Others |
Value Chain & Pricing Dynamics
Rare earth separation chemists concentrated in Chinese state laboratories and select Australian operations drive labor-cost differentials that widen spreads between industrial-grade and reagent-grade pricing tiers. MIIT quota enforcement and REACH registration burdens compound these spreads by constraining qualified supplier pools.
Pricing Analysis
Distributor margins on high-purity yttrium oxide range from 15-25 percent above refinery gate prices, while direct-to-OEM contracts for Japanese superconductor manufacturers command volume discounts that compress these spreads. Pricing stratifies across reagent, industrial, and analytical tiers based on purity certification and impurity profiling depth. Cost compression in the industrial tier is intensifying as Chinese clay-deposit operators absorb environmental compliance investments. Japanese METI-backed buyers exhibit the least price sensitivity due to strategic stockpile mandates, while European lighting OEMs face acute cost pressure from REACH dossier amortization.
Supply Chain Analysis
Japan's METI-sponsored local-content initiatives and similar strategic-reserve programs in South Korea are reshaping sourcing patterns toward Australian and Malaysian separation facilities. Raw material flows concentrate in China, Australia, and Malaysia, with concentrate supply drawing from ion-adsorption clay deposits in Jiangxi province and monazite operations in Western Australia. Solvent extraction circuits and Czochralski crystal growth furnaces constitute critical equipment dependencies. Single-source vulnerability runs through Ganzhou Rare Earth Mineral Industry's heavy rare earth separation dominance. Distribution runs through long-term offtake contracting with state-backed consortia rather than spot-market trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yttrium market functions as a regulatory compounder where European RoHS mercury-free deadlines and REACH Annex XVII impurity thresholds are accelerating demand for certified high-purity feedstock.
For Market Incumbents: Acquire solvent extraction expertise concentrated in Chinese state laboratories through targeted hiring campaigns and Australian technical partnerships. Secure offtake visibility by locking 5-7 year supply agreements with Japanese METI-backed consortia before rival separation houses qualify. Counter terbium substitution threats in mature phosphor applications by deepening reagent-grade certification investments for medical laser crystal markets. For New Entrants and Emerging Players: Begin with nanostructured yttrium oxide precursor supply to Taiwanese and South Korean LED packagers transitioning from micron-scale powders. The medical laser diode segment in Germany and Switzerland offers the most penetrable white space due to PMDA and Swissmedic purity barriers that filter out commodity suppliers. Pursue a go-to-market angle built on radiological screening at mine concentrate stage to preempt ECHA sub-ppm thorium certification requirements. For Investors and Strategic Acquirers: Japanese superconductor wire manufacturers are the most active acquirer in this space, seeking captive yttrium supply for YBCO tape expansion. Long-term viability hinges on fusion project construction timelines and grid stabilization deployment curves. Target Australian integrated mine-to-oxide operators with Kalgoorlie-class separation autonomy. Monitor ITER qualification protocol announcements as the critical inflection signal for high-purity demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Supply | Lynas Rare Earths' Kalgoorlie facility demonstrates mine-to-oxide autonomy that bypasses Chinese export licensing chokepoints. |
| Long-term Supply Agreement | Japanese METI consortia lock in 3-5 year offtake contracts that de-risk Australian separation capacity expansion decisions. |
| REACH Registration Completion | ECHA toxicological dossiers enable European market access for non-Chinese yttrium compound importers facing 18-24 month study timelines. |
| Nanostructured Precursor Transition | Sol-gel derived yttrium oxide powders consolidate supplier tiers as Taiwanese LED manufacturers demand sub-micron particle distributions. |
| Strategic Stockpile Participation | METI-sponsored reserves guarantee offtake for qualified non-Chinese suppliers, creating procurement security premiums. |
Study Parameters
Direct dialogue with rare earth separation plant managers, phosphor procurement leads at Korean display panel manufacturers, Japanese superconductor wire deposition engineers, and ECHA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from MIIT production quota announcements, Japanese METI strategic reserve disclosures, customs trade data for yttrium oxide flows, and SEC filings from listed rare earth operators. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with macro consumption modeling across phosphor, superconductor, and medical laser applications.
Bottom-up modeling aggregated individual separation house throughput, purity-grade yields, and end-use qualification status to build volume estimates. Top-down approaches cross-referenced national rare earth production statistics against import-export parity checks. Segmentation dimensions spanned compound form, grade tier, application, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to MIIT quota trajectories, RoHS implementation schedules, and ITER project milestone disclosures. Fusion magnet qualification protocols and medical laser diode shipment data served as industry-specific forecast anchors.
Several conditions sit outside the modeled scope, including potential terbium substitution breakthroughs in phosphor formulations, abrupt MIIT quota suspensions, and radiological threshold tightening beyond current ECHA guidance. Forecasts reflect documented assumptions about sustained Chinese export licensing friction and stable Australian environmental permitting timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Quartz Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market