
 Neodymium Sputtering Target Market | 2026-2036
Neodymium Sputtering Target Market Size, Share, and Industry Trends Forecast 2026-2036
Neodymium Sputtering Target Market Insights
Direct procurement channels between sputtering target fabricators and semiconductor foundries is reshaping how neodymium feedstock moves from mine to deposition chamber. Mitsui Mining & Smelting Co., Ltd. leverages its integrated rare-earth smelting infrastructure to secure consistent ingot quality for downstream target manufacturing. Stanford Advanced Materials (SAM) anchors its position through specialized purity grades tailored to magnetron sputtering protocols in optoelectronics labs. Materion Corporation differentiates via geographic diversification of its bonding and machining operations across multiple regulatory jurisdictions.
A neodymium sputtering target consists of high-purity metallic neodymium, typically refined to 99.9% or greater, formed into geometrically precise discs, rectangles, or cylinders for physical vapor deposition systems. These targets function as the source material in magnetron sputtering chambers, where ionized argon dislodges neodymium atoms that deposit as thin films on semiconductor wafers, magnetic storage media, or photovoltaic substrates. Disc configurations dominate current procurement volumes due to their compatibility with rotating cathode assemblies in high-volume fabrication lines. Customized geometries represent the fastest-expanding category as research institutions and aerospace contractors specify non-standard dimensions for prototype magnetronic devices.
Japan's METI enforces strict rare-earth stockpiling mandates that directly influence target manufacturer inventory strategies and long-term supply agreements. China's SAMR regulates export quotas on neodymium oxide and metal, creating licensing bottlenecks that constrain non-Chinese target fabricators' access to primary feedstock. ISO 9001 and AS9100 certification requirements from aerospace end users impose additional quality system burdens on suppliers serving dual-use semiconductor and defense applications. Stakeholders must monitor evolving rare-earth export licensing protocols and assess captive mine-to-target integration investments before committing to multi-year foundry supply contracts.
Market Dynamics
China's SAMR export licensing protocols for neodymium oxide and metal are forcing semiconductor foundries to restructure long-term supply agreements around captive refining investments in alternative jurisdictions, compressing procurement timelines and elevating purity-grade specifications as non-negotiable contract terms.
Growth Catalysts
- Advanced node fabrication:Semiconductor foundries at 3nm and below require atomic-layer deposition precision that only 99.9%+ purity neodymium targets deliver, pulling volume from legacy magnetron systems into next-generation physical vapor deposition chambers.
- Japan's METI stockpiling mandates:Mandatory national rare-earth reserves compel Japanese target fabricators to maintain 60-day minimum inventory buffers, creating predictable offtake agreements that stabilize upstream smelter utilization rates.
- Dual carbon goals:China's MEE enforcement of carbon intensity caps on rare-earth processing is redirecting foreign direct investment toward Australian and Canadian mine-to-metal projects with integrated hydrometallurgical circuits.
Market Restraints
- Feedstock concentration:Over 85% of separated neodymium oxide originates from Chinese solvent extraction facilities, exposing non-Chinese target manufacturers to quota-driven supply interruptions under SAMR seasonal licensing windows.
- Energy cost volatility:Rare-earth electrolytic reduction requires 8-12 MWh per metric ton of metal, making European and North American smelters vulnerable to natural gas price spikes that Chinese coal-powered competitors do not face.
- Substitute magnet materials:Cerium-lanthanum mischmetal alloys and ferrite permanent magnets are capturing cost-sensitive automotive sensor applications where neodymium-iron-boron performance exceeds design requirements.
Strategic Opportunities
- Vietnamese refining corridor:Dong Pao mine development combined with Japanese trading house offtake agreements positions Vietnam as a non-Chinese rare-earth oxide source for ASEAN-based target fabricators serving South Korean foundries.
- Photovoltaic back-contact cells:Neodymium-doped transparent conductive oxide layers in heterojunction solar architectures represent an emerging deposition application outside traditional semiconductor and magnetic storage end uses.
- EU Critical Raw Materials Act:Domestic content mandates and strategic stockpile financing create regulatory tailwinds for European target manufacturers establishing bonded machining operations in Estonia and Finland.
Industry Challenges
- AS9100 certification timelines:Aerospace-defense dual-use contracts require 18-24 month quality system audits that delay market entry for new target suppliers even when metallurgical capabilities are proven.
- Bonding technician scarcity:Indium-based target-to-backing-plate diffusion bonding demands specialized vacuum furnace operators whose training pipelines have atrophied as semiconductor equipment manufacturing migrated to East Asia.
- Legacy sputtering system incompatibility:Rotating cathode assemblies in 200mm-era fabrication lines cannot accommodate the geometric tolerances of next-generation rectangular targets optimized for 300mm wafer uniformity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neodymium Sputtering Target Market |
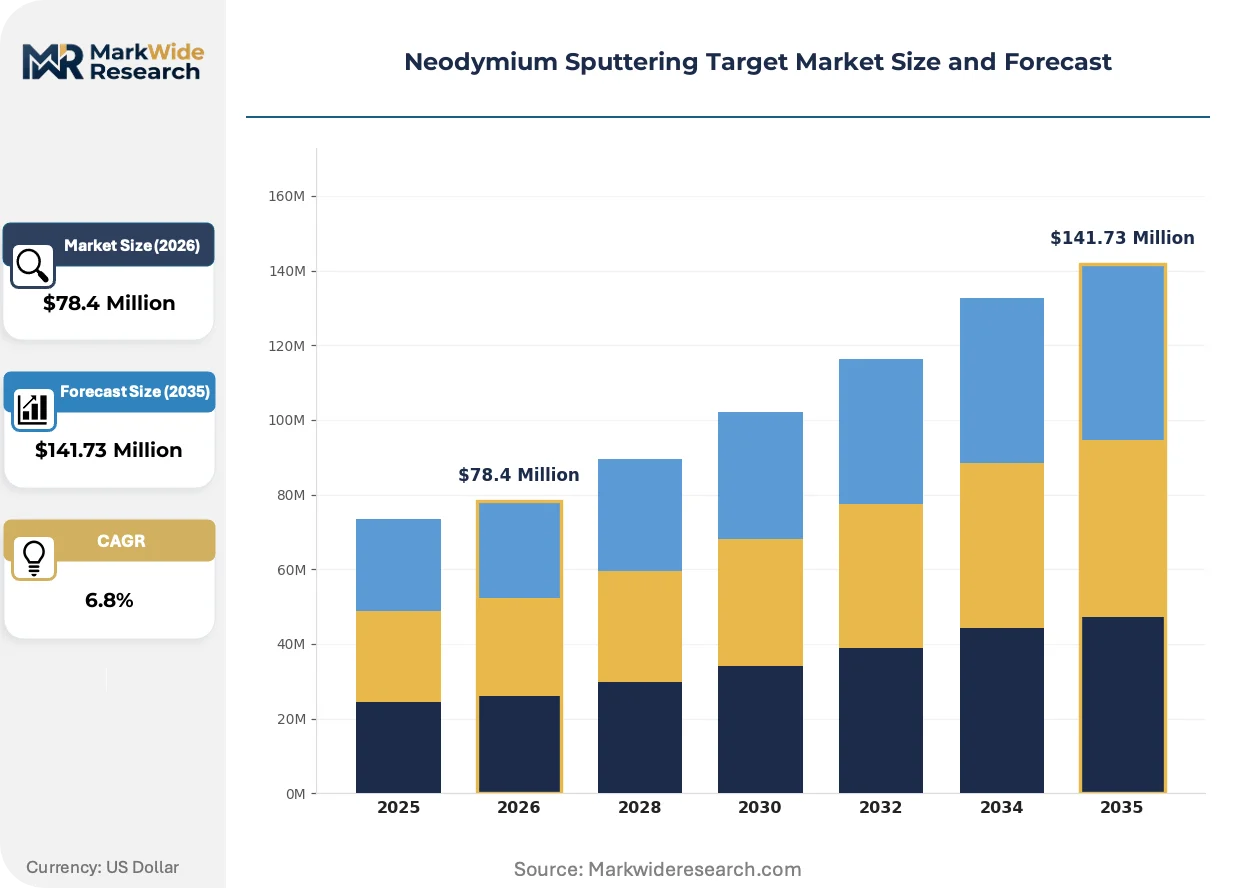
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc, Rectangle, Cylinder, Customized Application: Electronics, Renewable Energy, Optoelectronics, Automotive Components Technology: PVD, CVD, Magnetron Sputtering, Thermal Evaporation End User: Semiconductors, Aerospace, Consumer Electronics, Telecommunications |
| Companies Covered | MSE Supplies LLC, Mitsui Mining & Smelting Co., Ltd., Stanford Advanced Materials (SAM), Admat Inc., Vacuum Engineering & Materials (VEM), Materion Corporation, SCI Engineered Materials, American Elements, Kurt J. Lesker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neodymium Sputtering Target Market Trends and Innovations
Magnetron sputtering chamber architectures and feedstock purification protocols are undergoing simultaneous transformation as deposition uniformity requirements tighten and rare-earth supply geography diversifies.
Rotating cylindrical target geometries are collapsing the maintenance intervals that constrained planar disc configurations in high-volume foundry environments. TSMC and Samsung Foundry have standardized on 300mm-compatible rotating cathodes for their 3nm EUV lithography support layers, compressing target replacement cycles from quarterly to monthly intervals while improving film thickness uniformity to sub-3% variation across wafer lots. This geometry shift is collapsing the addressable market for legacy planar target fabricators lacking precision extrusion and CNC machining capabilities.
EU REACH Annex XVII restrictions on hexavalent chromium surface treatments are compelling target manufacturers to transition to trivalent chromium passivation or ceramic barrier coatings for corrosion protection. The industrial consequence is a 15-20% processing cost premium that European fabricators must absorb or pass through to aerospace and medical device end users. German and French target suppliers are responding by certifying alternative coating chemistries through ECHA's substitution assessment framework ahead of 2026 enforcement deadlines.
Direct long-term contracting between semiconductor foundries and rare-earth smelters is eliminating the trading house intermediaries that historically managed price volatility and logistics coordination. South Korean memory manufacturers now negotiate 36-month metal supply agreements with Australian miners, displacing the quarterly spot-market purchasing that dominated the 2015-2022 period. This behavioral shift is most visible in the Pyeongtaek semiconductor cluster, where Samsung and SK Hynix have established dedicated neodymium inventory buffers outside traditional distributor warehouses.
Neodymium Sputtering Target Market Segmentation
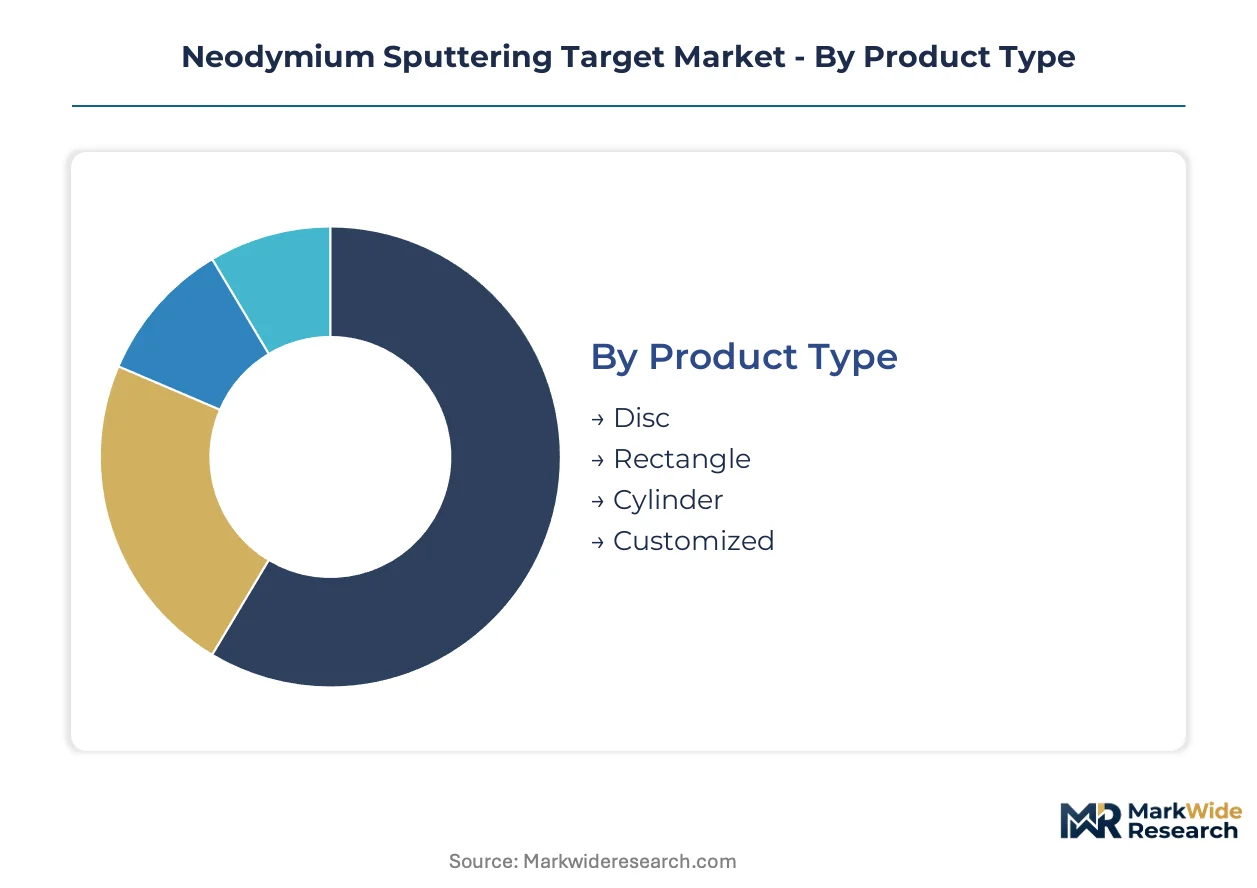
Target geometry and deposition technology choices lock semiconductor foundries into multi-year equipment commitments, making segmentation decisions irreversible once cathode assemblies are installed. Procurement teams weigh purity-grade availability against chamber retrofit costs when specifying target configurations for advanced node production lines.
Product Type:
After-sales service intensity varies sharply by geometry complexity, with rotating cylindrical configurations demanding specialized field technicians for cathode alignment and indium bonding refurbishment.
- Disc:Circular planar targets remain the default specification for legacy 200mm wafer fabrication lines and research-scale deposition systems. Samsung Foundry and TSMC consume disc configurations in highest volumes for their rotating cathode assemblies at 3nm EUV support layer production, though replacement cycles compress from quarterly to monthly intervals as uniformity tolerances tighten.
- Rectangle:Rectangular geometries optimize material utilization in linear magnetron systems for large-area photovoltaic back-contact cell manufacturing. Japanese magnetronics corridors in Sendai and Aomori Prefecture drive specification development for non-standard rectangular dimensions that maximize deposition zone coverage in prototype magnetronic device fabrication.
- Cylinder:Cylindrical targets enable continuous rotation during sputtering, extending operational life through uniform erosion profiles across the target surface.
- Customized:Non-standard geometries serve aerospace contractors and national laboratory research programs requiring proprietary chamber integrations.
By volume, Disc leads. By growth pace, Customized is ahead.
Application:
Cost tier stratification separates premium deposition applications with 99.9%+ purity mandates from standard-grade renewable energy segments tolerating 99.5% metal specifications.
- Electronics:Semiconductor interconnect layers and magnetic storage media deposition demand atomic-layer precision that only ultra-high-purity neodymium targets deliver. South Korean memory manufacturers at the Pyeongtaek cluster specify electronics-grade targets for MRAM and STT-MRAM device fabrication, with purity certificates traceable to individual smelter batches.
- Renewable Energy:Heterojunction solar cell architectures incorporate neodymium-doped transparent conductive oxide layers as back-contact interfaces. Australian and Canadian mine-to-metal projects with integrated hydrometallurgical circuits are capturing renewable energy procurement contracts as Chinese carbon intensity caps redirect foreign direct investment.
- Optoelectronics:Laser diode cavity coatings and optical isolator thin films require neodymium targets with controlled oxygen content below 500 ppm.
- Automotive Components:Position sensors and electric power steering systems utilize neodymium-iron-boron thin films deposited from standard-grade targets.
Electronics commands the premium pricing tier. Renewable Energy is climbing the fastest.
Technology:
Volume concentration in magnetron sputtering reflects the technology's dominance in high-throughput semiconductor fabrication, though thermal evaporation retains niche positions in research environments.
- PVD:Physical vapor deposition encompasses multiple source technologies including sputtering and evaporation, with equipment selection determining target geometry and bonding requirements. Stanford Advanced Materials anchors its market position through specialized purity grades tailored to PVD protocols in optoelectronics laboratories requiring batch-to-batch consistency.
- CVD:Chemical vapor deposition utilizes neodymium organometallic precursors rather than metallic targets, creating adjacent market dynamics for precursor chemical suppliers.
- Magnetron Sputtering:Magnetron configurations generate dense plasma confinement near the target surface, enabling high deposition rates at lower substrate temperatures. EUV lithography support layer fabrication at 3nm nodes has standardized on magnetron sputtering with rotating cylindrical targets, displacing planar diode systems from leading-edge production.
- Thermal Evaporation:Resistive heating of neodymium metal suits small-batch research applications where chamber contamination tolerance permits simpler source configurations.
Magnetron Sputtering dominates wafer fabrication volume. PVD maintains the broadest end-use diversification.
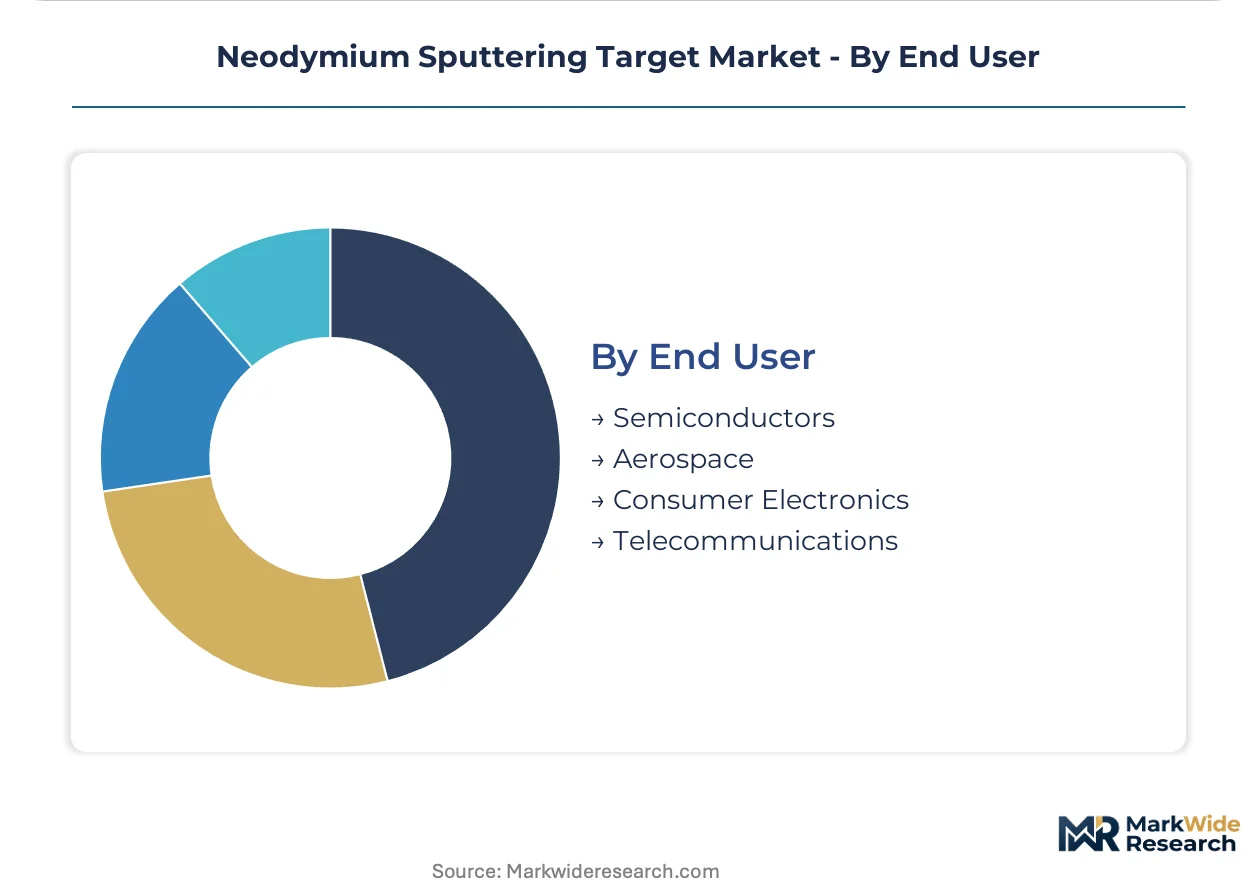
End User:
Customer type determines certification burden, with aerospace-defense dual-use contracts imposing 18-24 month AS9100 quality system audits that delay supplier qualification.
- Semiconductors:Foundry procurement of neodymium targets concentrates in East Asian manufacturing clusters, particularly South Korean fabrication complexes serving memory and logic device production. Direct long-term contracting between semiconductor manufacturers and Australian miners is eliminating trading house intermediaries that historically managed price volatility.
- Aerospace:Defense applications require AS9100 certification and ITAR compliance for targets incorporated in radiation-hardened electronics and satellite magnetronic systems. Materion Corporation differentiates via geographic diversification of its bonding and machining operations across multiple regulatory jurisdictions to satisfy aerospace supply chain security requirements.
- Consumer Electronics:Smartphone camera vibration motors and laptop hinge sensors utilize neodymium thin films in moderate volumes with compressed qualification timelines.
- Telecommunications:Base station filter coatings and optical fiber amplifier components specify neodymium-doped films for signal processing applications.
Semiconductors generates the largest absolute demand. Aerospace sustains the highest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR export licensing protocols for neodymium oxide are redirecting foreign direct investment toward alternative refining jurisdictions. Semiconductor foundries in South Korea and Japan are restructuring procurement around captive mine-to-metal projects. Japanese METI stockpiling mandates and EU Critical Raw Materials Act financing are creating parallel regulatory tailwinds for non-Chinese supply corridors.
China
Domestic rare-earth processing capacity concentrates in Inner Mongolia and Jiangxi Province, where carbon intensity caps under MEE enforcement are constraining electrolytic reduction output. SAMR seasonal licensing windows create quota-driven supply interruptions that expose non-Chinese target manufacturers to feedstock volatility. The Baotou rare-earth industrial cluster maintains dominant solvent extraction capacity for separated neodymium oxide.
Japan
METI mandates 60-day minimum inventory buffers for national rare-earth reserves, compelling Japanese target fabricators to maintain predictable offtake agreements with upstream smelters. The Sendai and Aomori Prefecture magnetronics corridors drive specification development for non-standard rectangular target geometries. Japanese trading houses are securing offtake agreements with Vietnamese mine developers to diversify oxide sourcing.
South Korea
The Pyeongtaek semiconductor cluster hosts Samsung Foundry and SK Hynix memory fabrication complexes that consume highest volumes of disc configurations for 3nm EUV support layer production. Direct 36-month metal supply agreements with Australian miners are displacing quarterly spot-market purchasing that dominated 2015-2022. Korean foundries have established dedicated neodymium inventory buffers outside traditional distributor warehouses.
United States
AS9100 certification requirements from aerospace-defense end users impose 18-24 month quality system audits on suppliers serving dual-use applications. The Mountain Pass rare-earth deposit in California provides domestic oxide feedstock, though separation capacity remains limited. Materion Corporation operates geographically diversified bonding and machining operations across multiple regulatory jurisdictions to satisfy supply chain security requirements.
Germany
ECHA's REACH Annex XVII restrictions on hexavalent chromium surface treatments are compelling target manufacturers to transition to trivalent chromium passivation ahead of 2026 enforcement deadlines. German fabricators face 15-20% processing cost premiums for alternative coating chemistries. The EU Critical Raw Materials Act creates regulatory tailwinds for establishing bonded machining operations in Estonia and Finland to serve European semiconductor demand.
Neodymium Sputtering Target Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: integrated rare-earth smelters with downstream target fabrication, specialized purity-grade specialists serving research and optoelectronics labs, and geographically diversified bonders serving aerospace certification requirements. Competitive positioning depends on captive feedstock access, AS9100 quality system credentials, and rotating cylindrical target machining capabilities. Dominant competitive moves include backward integration into Australian and Canadian mine-to-metal projects, and strategic partnerships between semiconductor foundries and non-Chinese oxide refiners.
Among Japanese-integrated fabricators, Mitsui Mining & Smelting Co., Ltd. anchors the smelter-integrated archetype through its rare-earth infrastructure. Stanford Advanced Materials occupies a position within the purity-grade specialist tier, serving optoelectronics laboratories with batch-to-batch consistency protocols. Materion Corporation exemplifies geographic diversification strategy across multiple regulatory jurisdictions to satisfy aerospace supply chain security mandates.
| Leading Market Players |
|---|
| MSE Supplies LLC |
| Mitsui Mining & Smelting Co., Ltd. |
| Stanford Advanced Materials (SAM) |
| Admat Inc. |
| Vacuum Engineering & Materials (VEM) |
| Materion Corporation |
| SCI Engineered Materials |
| American Elements |
| Kurt J. Lesker Company |
| Others |
Pricing and Supply Chain Analysis
The Baotou rare-earth industrial cluster in Inner Mongolia anchors global neodymium oxide separation capacity, and its carbon intensity caps under MEE enforcement are compressing electrolytic reduction output. This supply constraint feeds directly into elevated ingot premiums that Japanese and South Korean target fabricators must absorb or pass downstream to semiconductor foundries.
Pricing Analysis
Certification level creates the primary spread across the neodymium sputtering target market, with AS9100-aerospace grade commanding substantial premiums over standard electronics-grade specifications. Three-tier pricing structure across premium, standard, and economy levels reflects purity thresholds, with 99.9%+ metal for 3nm EUV layers, 99.5% for magnetic storage media, and 99% for research-scale deposition. Cost compression in the standard tier is intensifying because Vietnamese oxide refiners are undercutting Chinese spot quotations. Automotive sensor manufacturers exhibit highest price sensitivity, while aerospace-defense contractors prioritize supply security over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with Mitsui Mining & Smelting, Materion Corporation, and Stanford Advanced Materials, which collectively shape downstream availability. Geographic supply concentration draws from China, Vietnam, and Australia, with Japanese trading houses securing Dong Pao mine offtake to diversify oxide sourcing. Raw material dependencies hinge on neodymium oxide from solvent extraction facilities, indium bonding agents, and high-purity argon process gas. Single-source vulnerability from Chinese SAMR seasonal licensing windows creates structural risk. Distribution runs through direct long-term contracts between foundries and smelters, displacing quarterly spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity because indium bonding refurbishment and cathode alignment field services are expanding faster than raw target hardware sales. After-sales service intensity for rotating cylindrical configurations creates recurring revenue streams that stabilize fabricator margins.
For Market Incumbents: Build captive feedstock moats through backward integration into Australian and Canadian mine-to-metal projects with integrated hydrometallurgical circuits. Secure AS9100 certification extensions ahead of aerospace contract renewals to lock out emerging competitors. Capacity addition in Estonia and Finland under EU Critical Raw Materials Act financing will defend position against substitute magnet materials threatening cost-sensitive automotive segments. For New Entrants and Emerging Players: Vietnamese refining corridors near the Dong Pao development represent the most penetrable geographic white space, with Japanese trading house partnerships providing credibility cover. Target photovoltaic back-contact cell manufacturers in ASEAN jurisdictions where Chinese carbon intensity caps have redirected foreign direct investment. A specialized purity-grade positioning for heterojunction solar architectures offers the cleanest go-to-market angle against entrenched semiconductor-focused incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a critical minerals infrastructure play because rare-earth supply security has become non-negotiable for advanced node fabrication. Acquisition target archetypes include geographically diversified bonders with rotating cylindrical machining capabilities and existing aerospace certification. The signal to watch is South Korean foundry inventory buffer levels at Pyeongtaek, which indicate procurement behavior shifts before they appear in public trade data.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mine-to-Metal Projects | Australian and Canadian integrated hydrometallurgical circuits reduce SAMR licensing exposure for non-Chinese fabricators. |
| AS9100 Quality System Certification | Eighteen-month audit timelines create defensible moats against new entrants seeking aerospace-defense dual-use contracts. |
| Rotating Cylindrical Target Capacity Expansion | TSMC and Samsung Foundry standardization at 3nm EUV support layers compresses replacement cycles and locks in volume. |
| Vietnamese Oxide Refining Partnership | Dong Pao mine offtake agreements with Japanese trading houses diversify feedstock sourcing for ASEAN-based fabricators. |
| Indium Bonding Field Service Networks | Specialized vacuum furnace operator scarcity makes after-sales service attach rates a margin expansion lever. |
Research Methodology
Initial hypotheses were tested against primary input from semiconductor foundry procurement directors, rare-earth smelter operations managers, magnetron sputtering equipment engineers, and aerospace quality system auditors and refined through secondary validation. Foundry supply chain planners at Samsung and SK Hynix, Japanese METI rare-earth stockpile administrators, and EU Critical Raw Materials Act policy specialists contributed operational perspective. Secondary sources encompassed SAMR export licensing records, ECHA REACH Annex XVII substitution assessments, SEC 10-K filings from listed target fabricators, and customs trade data for neodymium oxide movements. Bottom-up demand modeling from wafer fabrication equipment installations was triangulated against top-down rare-earth metal production statistics.
Demand-supply balance across the analysis window was constructed from semiconductor capital expenditure disclosures, foundry capacity buildout announcements, and rare-earth separation facility utilization rates. Segmentation dimensions modeled include target geometry, purity grade tier, deposition technology protocol, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from equipment shipment forecasts and metal consumption coefficients per wafer layer. Industry-specific inputs incorporated EUV lithography node transition timelines and METI stockpiling mandate compliance schedules.
Practitioners should monitor SAMR seasonal licensing window announcements, MEE carbon intensity enforcement actions, and South Korean foundry inventory buffer accumulation for early signals of supply constraint or demand inflection. Forecasts reflect assumptions regarding continued 3nm node proliferation and stable aerospace certification requirements. Quarterly review of Vietnamese oxide refinery commissioning progress and rotating cathode assembly installation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Barium Titanate Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Germanium Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Global Thermal Paste Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Quartz Market