
 Display Port Adapters Market | 2026-2036
Display Port Adapters Market Size, Share, and Industry Trends Forecast 2026-2036
Display Port Adapters Market Outlook
The gap between DisplayPort 2.1 bandwidth capabilities and legacy HDMI output requirements is narrowing as monitor refresh rates climb past 240Hz. Apple leverages its proprietary ecosystem control to push USB-C to DisplayPort solutions across Mac and iPad lineups. Belkin International anchors retail channel presence through premium positioning in North American electronics stores. StarTech.com specializes in enterprise-grade active adapters with locking connector designs for AV installations.
Display Port Adapters are signal conversion interfaces that translate DisplayPort protocol output into HDMI, VGA, DVI, or alternate DisplayPort form factors, typically supporting bandwidths up to 80 Gbps in DisplayPort 2.1 implementations with UHBR20 link rates. These devices enable connectivity between computers, GPUs, and displays with incompatible physical ports or protocol versions, serving critical bridging functions in mixed-technology environments. Active adapters with built-in signal amplification lead volume shipments for high-resolution and long-cable-run applications, while USB-C adapters represent the fastest-expanding category as laptops shed dedicated video ports. Gaming end users concentrate margin pools through willingness to pay for certified 4K120Hz and 8K60Hz performance guarantees.
FCC electromagnetic interference standards in the United States and CE marking requirements under EU Radio Equipment Directive shape product certification costs and market access timelines for adapter manufacturers. RoHS substance restrictions and REACH chemical compliance in Europe further constrain solder alloys and cable jacket materials used in production. Stakeholders must monitor whether VESA certification programs expand to cover USB-C alt-mode interoperability as protocol convergence accelerates.
Market Dynamics
The Display Port Adapters Market pivots on the forced obsolescence of legacy video interfaces as USB-C alt-mode deployment accelerates across laptop OEM portfolios and EU regulatory mandates eliminate single-purpose ports.
Growth Catalysts
- EU USB-C Mandate:The Radio Equipment Directive's universal charging port requirement phases out proprietary and legacy connectors, forcing adapter demand for backward compatibility with existing display infrastructure.
- 240Hz+ Gaming Monitors:High-refresh-rate panels outpace HDMI 2.0 bandwidth limits, pushing enthusiast buyers toward DisplayPort 1.4 and 2.1 solutions for uncompressed 4K120Hz signal paths.
- Display Panel Manufacturing Clusters:Concentrated production in China generates captive adapter demand from panel integrators and ODMs serving downstream monitor assembly.
Market Restraints
- Copper and Gold Input Volatility:Connector plating and cable conductor costs fluctuate with precious metals markets, compressing margins on entry-grade passive adapters.
- Upstream Concentration Risk:VESA certification testing and controller IC supply concentrate among Taiwanese semiconductor foundries and test labs.
- Native USB-C Display Substitution:Direct USB-C to USB-C video cables bypass adapter conversion entirely in newer monitor deployments.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme subsidies for electronics assembly attract adapter production relocation from China-dominant supply chains.
- Active Adapter Enterprise AV:Locking-connector designs and amplified signal regeneration address professional installation markets with extended cable runs.
- DisplayPort 2.1 UHBR20 Convergence:80 Gbps bandwidth alignment with USB4 v2 creates unified controller platforms reducing SKU complexity.
Industry Challenges
- VESA Certification Backlogs:Extended test queue times at authorized facilities delay product launches and inventory positioning.
- HDMI Licensing Complexity:HDMI Forum patent pool administration and royalty verification create legal exposure for multi-protocol adapter manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Port Adapters Market |
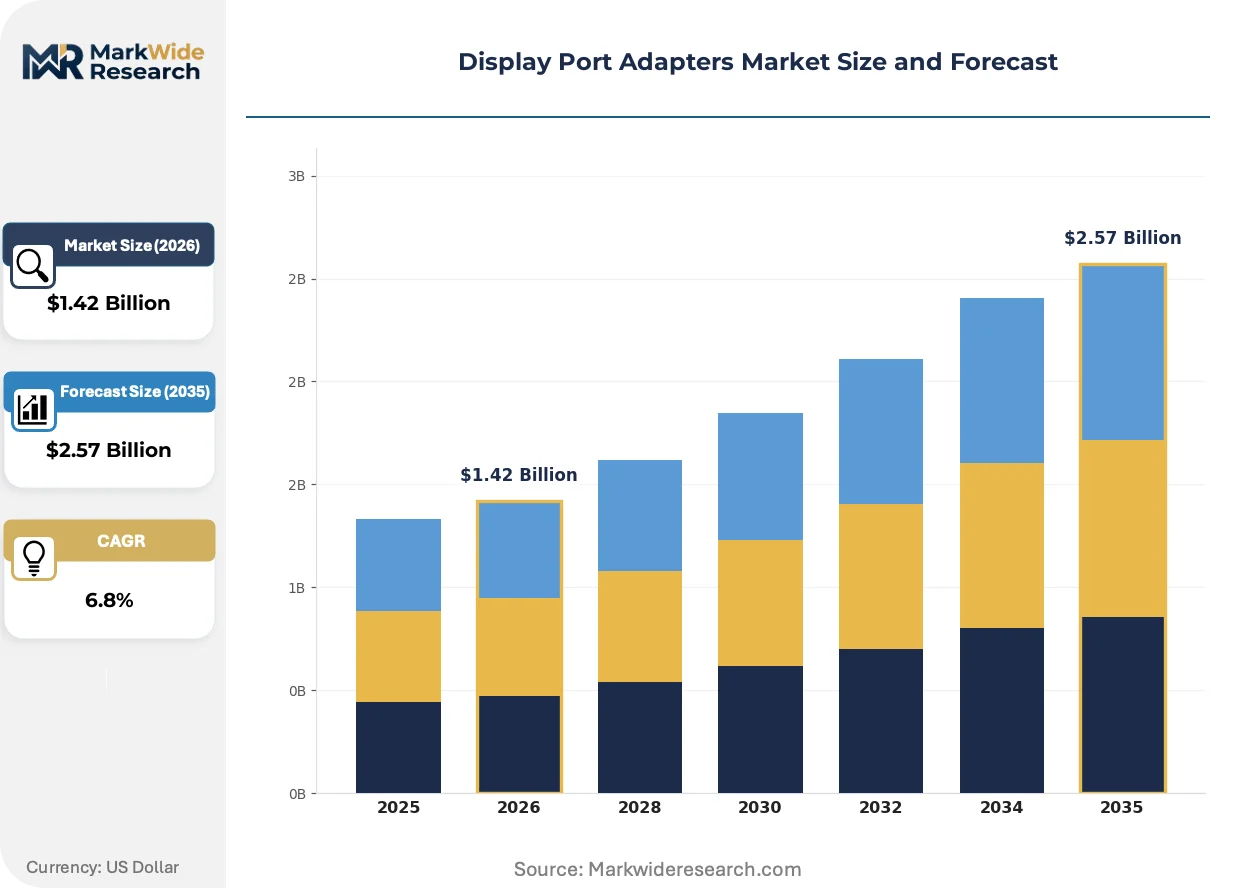
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Adapters, Passive Adapters, Mini DisplayPort Adapters, USB-C Adapters End User: Consumer Electronics, Corporate Offices, Educational Institutions, Gaming Transmission Mode: Single Link, Dual Link, Multi-Stream Transport, HDMI Compatibility Connector Type: Standard DisplayPort, Mini DisplayPort, USB-C, HDMI |
| Companies Covered | Apple, Monoprice, Plugable Technologies, StarTech.com, Cable Matters, Belkin International, Accell, Comsol, Extron Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Port Adapters Market Strategic Shifts
Signal virtualization and protocol unification are compressing the adapter category from discrete hardware toward integrated silicon solutions, while regulatory harmonization and procurement centralization reshape competitive access.
DisplayPort 2.1 source controllers with integrated USB4 retimers are virtualizing the traditional discrete adapter function. Laptop OEMs at Dell, HP, and Lenovo adopt these combined PHY solutions for flagship mobile workstation SKUs. This silicon consolidation is virtualizing the standalone adapter market by embedding conversion logic directly into motherboard designs.
EU REACH substance restrictions and RoHS recast directives tighten cadmium and lead exemptions for solder alloys in cable assemblies. Manufacturers reformulate production lines to tin-bismuth-copper compositions compliant with ECHA sunset dates. Adapter suppliers serving European distribution channels absorb certification retesting costs ahead of 2026 substance deadline enforcement.
Enterprise IT procurement teams centralize AV accessory purchasing through managed service contracts rather than ad-hoc retail acquisition. Distributors like Ingram Micro and TD Synnex capture adapter volume through blanket agreements with Fortune 500 technology refresh programs. This concentration is most visible in North American corporate deployments where standardization reduces support ticket volume.
Display Port Adapters Market Segmentation
Adapter selection hinges on signal integrity requirements, cable length constraints, and legacy port compatibility. Procurement teams segment purchases by installation environment rather than hardware specifications alone. Technical buyers prioritize VESA certification tiers over raw bandwidth ratings.
Product Type:
After-sales service intensity varies sharply across adapter architectures, with active designs demanding firmware update support and passive units requiring minimal post-sale intervention.
- Active Adapters:These units embed signal amplification chips and retimer circuits to regenerate degraded video signals across extended cable runs. Enterprise AV integrators in Germany specify active adapters for conference room deployments exceeding 15-meter HDMI extensions. The KBA's electromagnetic compatibility standards for automotive display applications indirectly drive demand for shielded active variants.
- USB-C Adapters: Alt-mode controllers translate USB4/Thunderbolt signaling into DisplayPort protocol for laptop docking scenarios. Dell and Lenovo enterprise fleets in the United States generate replacement volume as USB-C mandates phase out dedicated video ports. Firmware update requirements create recurring service touchpoints absent in passive designs.
- Passive Adapters: Pin-to-pin mapping without active electronics serves short-distance, same-protocol conversions. Consumer retail channels in Japan stock passive Mini DisplayPort to HDMI units for legacy MacBook compatibility.
- Mini DisplayPort Adapters: Compact form factor targeting space-constrained mobile workstations and embedded display modules. Microsoft's Surface device ecosystem sustains residual demand despite USB-C transition.
By volume, Passive Adapters leads. By growth pace, USB-C Adapters is expanding most quickly.
End User:
Cost tier stratification separates enthusiast gaming budgets from institutional procurement constraints.
- Gaming:High-refresh-rate monitor deployments demand certified 4K120Hz and 8K60Hz signal path guarantees. Enthusiast buyers in South Korea pay premiums for VESA-certified DisplayPort 2.1 adapters supporting 240Hz+ panels. Tournament organizers require redundant adapter inventory for broadcast reliability.
- Corporate Offices: Standardized refresh programs across Fortune 500 technology budgets drive volume through distributor consolidation. TD Synnex blanket agreements capture North American enterprise adapter procurement. IT departments prioritize locking-connector designs to prevent accidental disconnection.
- Consumer Electronics: Retail channel stocking decisions follow laptop OEM port configuration changes. Best Buy and Amazon marketplace sellers rotate SKUs as Apple and PC manufacturers shift connector strategies.
- Educational Institutions: K-12 and university technology grants fund bulk adapter purchases for classroom display upgrades. State-level procurement centralization in Texas and California reduces vendor fragmentation.
Gaming commands the highest per-unit pricing. Corporate Offices generates the largest absolute volume.
Transmission Mode:
Application requirements determine link configuration complexity, with multi-display installations demanding advanced transport protocols.
- Multi-Stream Transport:MST hubs split single DisplayPort 1.4 streams into multiple independent video outputs. Financial trading floors in London deploy MST adapters to drive quad-monitor arrays from single GPU outputs. Daisy-chain topology reduces cable clutter in space-constrained environments.
- HDMI Compatibility: Protocol translation bridges DisplayPort source devices to HDMI sink displays, requiring HDCP handshake negotiation. Hotel and hospitality digital signage networks in Dubai specify HDMI-compatible adapters for mixed-vendor display estates. EDID emulation challenges create support ticket volume for installation teams.
- Single Link: Basic bandwidth configuration for 1080p60 and lower resolution applications. Entry-level office monitors in India rely on single-link passive adapters for cost-sensitive deployments.
- Dual Link: Doubled lane count supporting higher bandwidth for QHD and early 4K implementations. Legacy monitor compatibility sustains residual demand despite DisplayPort 1.4 prevalence.
Single Link retains installed base dominance. Multi-Stream Transport is climbing the fastest as multi-monitor productivity configurations proliferate.
Connector Type:
Customer type segmentation separates mobile-first buyers seeking USB-C versatility from desktop users maintaining legacy Mini DisplayPort investments.
- USB-C:Reversible connector with alt-mode video capability replacing dedicated display ports across laptop portfolios. EU Radio Equipment Directive mandates accelerate OEM transitions, forcing adapter demand for backward compatibility. Samsung and LG monitor lines increasingly omit legacy inputs.
- Standard DisplayPort: Full-size connector dominating desktop GPU and monitor implementations. NVIDIA and AMD reference designs maintain DisplayPort as primary output, sustaining adapter demand for HDMI and legacy conversions.
- Mini DisplayPort: Compact variant prevalent in Apple MacBook generations and Microsoft Surface devices. Residual demand concentrates in replacement markets and embedded industrial displays.
- HDMI: Ubiquitous consumer display input requiring adapter conversion from DisplayPort sources. Television and projector installations in Brazil's corporate sector rely on HDMI adapters for laptop connectivity.
Standard DisplayPort leads current shipments. USB-C is gaining share fastest as laptop port consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports DisplayPort adapter controllers and finished assemblies to downstream electronics manufacturing clusters across Germany, the United States, and South Korea. Panel integrators in Shenzhen and Dongguan supply ODM partners assembling monitors for European and North American brands. This trade corridor shapes adapter demand patterns in destination markets.
China
Display panel manufacturing concentrates in Guangdong and Jiangsu provinces, generating captive adapter demand from monitor assemblers serving Dell, HP, and Samsung. MIIT's push for domestic semiconductor self-sufficiency accelerates local controller IC design. Dongguan's electronics corridor houses retimer chip packaging facilities supplying downstream adapter production.
Germany
Enterprise AV integrators specify active adapters with locking connectors for corporate conference room deployments exceeding 15-meter cable runs. The KBA's electromagnetic compatibility standards for automotive displays create niche demand for shielded variants. Bavaria's industrial automation sector sources ruggedized adapters for factory-floor HMI installations.
United States
Gaming enthusiasts drive premium adapter purchases supporting 240Hz+ monitor refresh rates and 8K60Hz signal paths. FCC electromagnetic interference standards shape product certification timelines and testing costs. TD Synnex and Ingram Micro consolidate enterprise procurement through blanket agreements with Fortune 500 technology refresh programs.
South Korea
Display panel leadership by Samsung and LG Display sustains upstream adapter demand for monitor integration. MFDS-equivalent consumer electronics safety frameworks govern adapter import compliance. Seoul's esports tournament infrastructure requires redundant certified adapter inventory for broadcast reliability.
India
Educational technology grants fund bulk adapter purchases for classroom display upgrades across state-level procurement programs. PLI scheme subsidies for electronics assembly attract adapter production relocation from China-dominant supply chains. Karnataka's Bangalore electronics cluster hosts emerging ODM operations serving domestic monitor brands.
Display Port Adapters Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tiers. The vendor base spans retail-anchored consumer electronics brands, enterprise-focused AV integrators, and semiconductor-originated controller suppliers. Three archetypes dominate: ecosystem-locked premium players, specification-driven enterprise specialists, and cost-optimized volume suppliers. Competitive moves concentrate on USB-C alt-mode controller integration and VESA certification queue positioning.
Among ecosystem-locked premium players, Apple exemplifies proprietary control by pushing USB-C to DisplayPort solutions across Mac and iPad lineups. Belkin International occupies a retail-channel position through premium positioning in North American electronics stores. StarTech.com represents the enterprise-specialist archetype with active adapter designs targeting AV installation markets. These three companies anchor distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| Apple |
| Monoprice |
| Plugable Technologies |
| StarTech.com |
| Cable Matters |
| Belkin International |
| Accell |
| Comsol |
| Extron Electronics |
| Others |
Value Chain & Pricing Dynamics
Dongguan's electronics corridor houses the densest concentration of DisplayPort adapter controller packaging and cable assembly operations, with capacity utilization swings at these facilities transmitting directly into OEM pricing leverage during contract renegotiations. Panel integrators in Shenzhen and Dongguan absorb margin compression when retimer chip foundries throttle output, forcing adapter assemblers to prioritize VESA-certified active units over passive alternatives.
Pricing Analysis
DisplayPort 2.1 UHBR20 adapters command substantial premiums over legacy DisplayPort 1.2 and 1.4 units, while next-generation USB4 v2 convergence silicon threatens to collapse the three-tier pricing structure across premium, standard, and economy levels into a consolidated performance band. Price differentiation separates VESA-certified active adapters with locking connectors from uncertified passive units, with gaming enthusiasts showing least price sensitivity and educational bulk procurement teams most. Pricing pressure stems from copper and gold plating cost volatility compressing entry-grade passive margins.
Supply Chain Analysis
Foxconn and Pegatron hold dominant contract manufacturing capacity for adapter assembly, with Quanta and Compal capturing laptop OEM bundled orders. Controller IC supply concentrates in Taiwan and South Korea, while cable conductor and connector plating draws from Chinese and Japanese metal refiners. Single-source vulnerability concentrates at Taiwanese semiconductor foundries producing DisplayPort retimer chips. Distribution runs through Ingram Micro and TD Synnex for enterprise AV, with Amazon and Best Buy anchoring consumer retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Display Port Adapters Market expansion sits in early-cycle phase as USB-C alt-mode mandates force backward compatibility demand against installed base legacy displays. EU Radio Equipment Directive universal charging requirements accelerate this replacement wave across European enterprise fleets.
For Market Incumbents: Insulate certification moats by accelerating VESA queue positioning and locking connector IP development before DisplayPort 2.1 controller integration virtualizes discrete adapter functions. Backward integration into retimer chip sourcing from Taiwanese foundries reduces single-source exposure. Channel control through distributor blanket agreements with Fortune 500 technology refresh programs defends volume positions against emerging USB-C direct-cable substitution.
For New Entrants and Emerging Players: Pursue India PLI scheme subsidies for electronics assembly relocation, targeting state-level educational technology procurement in Karnataka and Tamil Nadu with cost-optimized passive adapter portfolios. Enterprise AV installation markets in Germany present penetrable white space for active adapter specialists with KBA electromagnetic compatibility compliance. Direct-to-integrator sales bypassing established distributor tiers offers viable go-to-market angle for price-aggressive entrants.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-takeup play because EU and Indian mandate enforcement creates forced replacement demand independent of consumer upgrade cycles. Acquisition targets should screen for VESA certification pipeline depth and USB-C alt-mode controller integration capabilities. Monitor quarterly VESA authorized test facility queue lengths as inflection indicator for incumbent product launch velocity and inventory positioning advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| VESA Certification Acceleration | Reduces test queue delays at authorized facilities for DisplayPort 2.1 product launches. |
| USB-C Alt-Mode Controller Integration | Enables unified silicon platforms addressing laptop OEM motherboard embedding trends. |
| India Manufacturing Relocation | Captures PLI scheme subsidies while diversifying from China-dominant panel supply chains. |
| Enterprise AV Channel Partnership | Locks in TD Synnex and Ingram Micro blanket agreements for Fortune 500 refresh programs. |
| Active Adapter Locking Connector Development | Addresses German KBA standards and North American corporate IT physical security requirements. |
Study Parameters
Initial hypotheses were tested against primary input from adapter product managers at OEMs, procurement leads at enterprise AV integrators, VESA certification test engineers, and distribution channel partners at major electronics distributors, then refined through secondary validation. Primary interviews combined with SEC filings, customs trade data, FCC equipment authorization databases, and VESA member disclosure records. Bottom-up unit shipment estimates triangulated against top-down panel production forecasts.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning adapter architecture type, end-user vertical, transmission protocol configuration, and connector form factor. CAGRs derived from installed base turnover modeling against USB-C mandate phase-in schedules. Forecast inputs incorporated gaming monitor refresh rate adoption curves and EU regulatory enforcement timelines.
Sensitivities concentrate around VESA certification backlog durations, precious metals input volatility, and USB-C direct-cable substitution rates in new monitor deployments. Quarterly review of retimer chip foundry utilization, authorized test facility queue lengths, and laptop OEM port configuration announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Dual Relay Board Market
Electronic Components
Breadboards Market
Electronic Components
PTC Resettable Device Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Power Inductors Market
Electronic Components
GPIO Expanders Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
Capacitor Kits Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
VPX SBC Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Digital Isolator Market
Electronic Components
Wearable Technology Component Market