
 Optical Liquid Level Sensor Market | 2026-2036
Optical Liquid Level Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Liquid Level Sensor Market Analytics
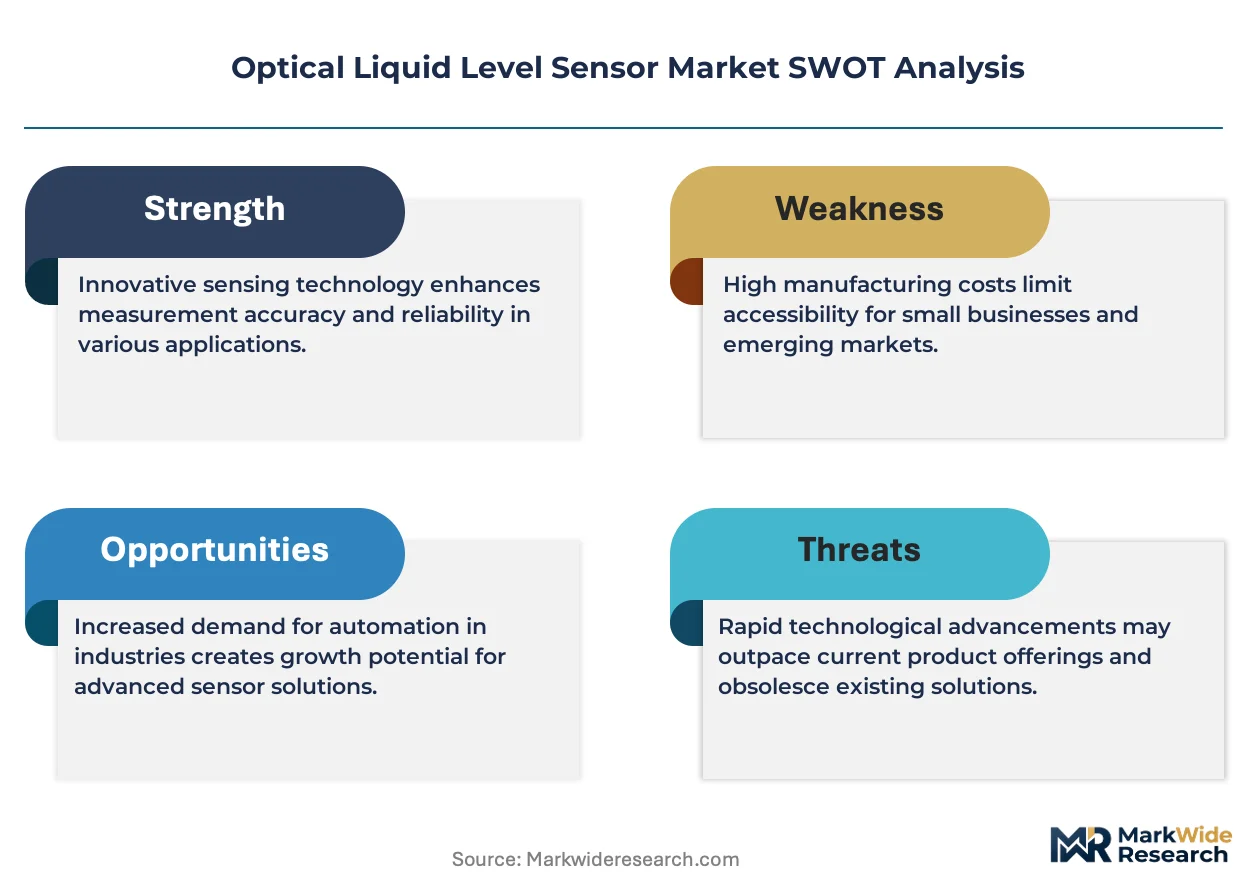
The optical liquid level sensor market is pivoting around a widening gap between precision-grade fiber optic units for pharmaceutical environments and cost-optimized LED-based sensors for bulk industrial tanks. Keyence leverages its automation channel dominance in East Asia to bundle level sensing with vision systems. Pepperl+Fuchs anchors its European position through hazardous-area certifications and process-industry relationships. SST Sensing Ltd specializes in compact infrared probes for medical and analytical instrumentation, occupying a defensible niche against larger competitors.
Optical liquid level sensors detect fluid presence or height using light-based principles, typically employing infrared or fiber optic elements with refractive index thresholds between 1.33 and 1.50 for common aqueous and hydrocarbon media. These devices serve critical functions in leak prevention, inventory accuracy, and process safety across continuous manufacturing operations. Fiber optic technology commands premium pricing in corrosive and high-temperature environments where electrical isolation proves essential. LED-based products compete aggressively on unit cost in water treatment and general industrial manufacturing applications. Infrared sensing leads automotive battery coolant monitoring and electric vehicle thermal management systems where rapid response times matter.
EMA medical device regulations and EU MDR conformity requirements in Europe compel pharmaceutical and biotechnology manufacturers to validate sensor materials for extractables and leachables. FDA 21 CFR Part 11 and ISO 13485 standards in the United States similarly shape product development roadmaps for suppliers targeting life science end users. IEC 61010 safety standards govern industrial deployment architectures globally. Stakeholders must monitor evolving cybersecurity annexes to medical device standards and assess whether firmware-enabled optical sensors trigger additional compliance obligations.
Market Dynamics
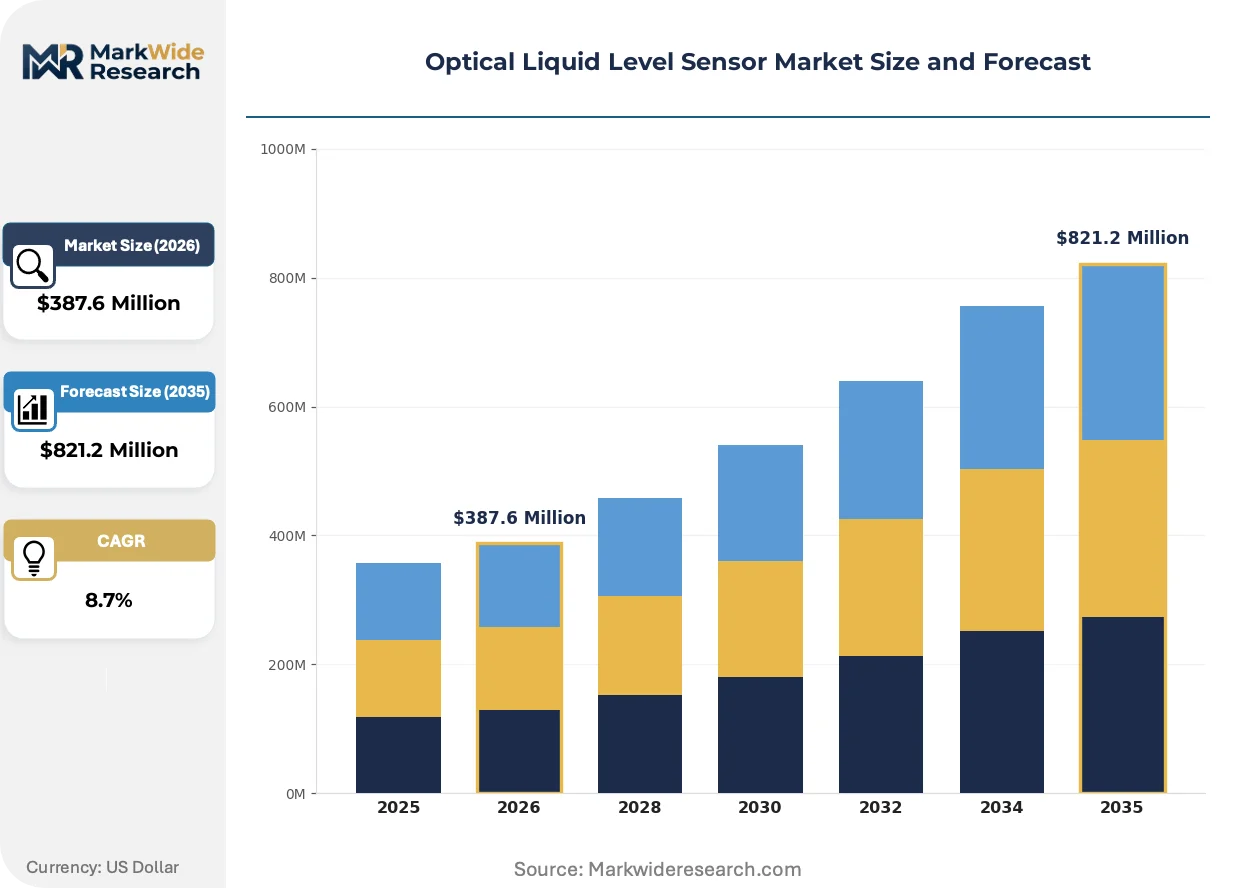
The optical liquid level sensor market is bifurcating around precision fiber optic units for sterile pharmaceutical environments versus cost-optimized LED sensors for bulk industrial tanks, with EU MDR material validation requirements accelerating this segmentation.
Growth Catalysts
- EU MDR Material Mandates:Pharmaceutical manufacturers in Germany and Switzerland now validate sensors for extractables and leachables, creating captive demand for certified fiber optic probes in sterile fluid handling.
- Electric Vehicle Thermal Systems:Infrared sensing technology is capturing automotive battery coolant monitoring applications where rapid response times prevent thermal runaway.
- Corrosive Process Environments:Chemical processing facilities deploy fiber optic level sensors for electrical isolation in high-temperature, acid-handling operations where metallic probes corrode.
Market Restraints
- Silicon Photonics Input Costs:Precision-grade fiber optic sensors depend on specialty silica and rare-earth doped fibers with volatile pricing tied to semiconductor material cycles.
- Single-Source Certification Bodies:EU Notified Bodies for MDR compliance concentrate in Germany and the Netherlands, creating bottlenecks for sensor material validation timelines.
- Capacitive Substitution:Low-cost capacitive level sensors displace optical units in water treatment and general industrial tanks where precision is secondary.
Strategic Opportunities
- Cell Therapy Manufacturing:Closed-system single-use bioreactors in the United States require disposable optical sensors with pre-validated sterile fluid pathways.
- Green Hydrogen Electrolysis:Alkaline and PEM electrolyzer stacks need corrosion-resistant level monitoring for potassium hydroxide and deionized water management.
- Sensor-Vision System Bundling:Industrial automation distributors now package level sensing with machine vision for integrated tank monitoring solutions.
Industry Challenges
- Multi-Standard Certification Overlap:Sensors targeting both pharmaceutical and industrial markets must simultaneously satisfy ISO 13485, IEC 61010, and emerging cybersecurity annexes.
- Legacy Analog Integration:Brownfield manufacturing facilities require optical sensors with 4-20mA output compatibility, constraining digital-native product architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Liquid Level Sensor Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Sensors, Ultrasonic Sensors, Optical Sensors, Magnetic Float Sensors End User: Industrial Manufacturing, Water Treatment, Food & Beverage, Automotive Technology: Infrared, Fiber Optic, Laser, LED Application: Level Monitoring, Leak Detection, Process Control, Inventory Management |
| Companies Covered | Keyence, Pepperl+Fuchs, Banner Engineering, Honeywell, Baumer, IFM Electronic, Omron, SST Sensing Ltd, SICK AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Liquid Level Sensor Market Evolving Landscape
Photonic integration and regulatory material mandates are compressing product development cycles while expanding the addressable sensor base into sterile processing and electric vehicle thermal management.
Micro-electromechanical systems are integrating photonic chips directly into optical level sensor housings, eliminating discrete fiber coupling losses. Medical device manufacturers in Stuttgart and Basel adopt these compact infrared probes for point-of-care diagnostic instruments. The technology is integrating sensing and signal processing into single packages that slash unit costs for high-volume disposable applications.
EMA guidance on extractables and leachables testing now requires pharmaceutical sensor suppliers to document material compatibility across full sterilization cycles. This compels fiber optic manufacturers to maintain dedicated validation dossiers for each wetted material. German and Swiss pharmaceutical clusters drive the strictest interpretation, forcing suppliers to segment product lines by certification grade.
Buyers in water treatment and general manufacturing now unbundle sensor procurement from system integrator contracts, sourcing optical level sensors directly through industrial distribution. This disintermediation compresses pricing power for bundled automation vendors. The pattern is most visible in East Asian manufacturing hubs where local distributors stock commodity LED-based sensors for same-day fulfillment.
Optical Liquid Level Sensor Market Segmentation
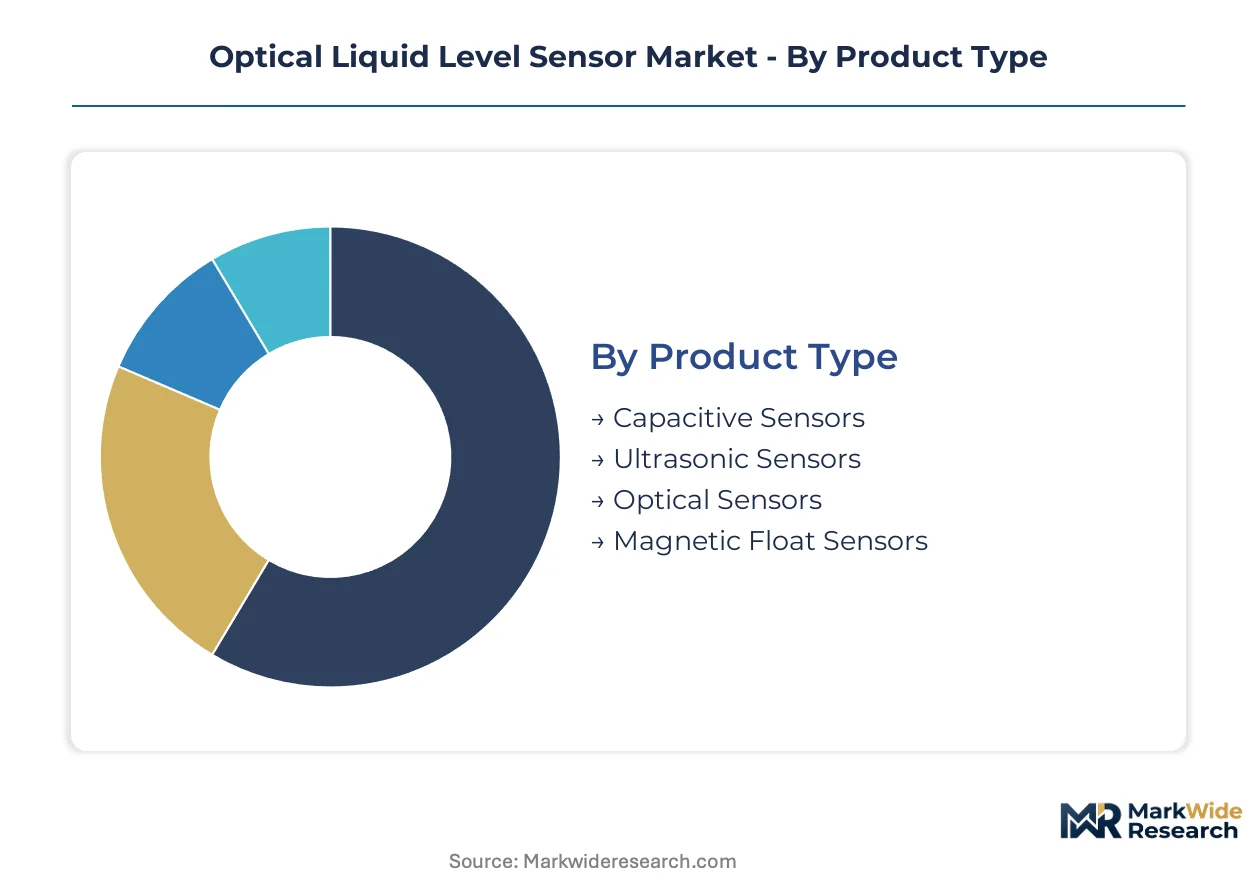
Optical liquid level sensor procurement patterns diverge sharply between precision-critical pharmaceutical environments and cost-sensitive bulk industrial applications. Understanding these segment boundaries clarifies where fiber optic premiums hold versus where LED commoditization accelerates.
Product Type:
Supply concentration clusters around optical and capacitive technologies, with sensor architecture determining margin structure and certification requirements.
- Optical Sensors:These units deploy infrared or fiber optic elements with refractive index thresholds calibrated between 1.33 and 1.50 for aqueous and hydrocarbon detection. Pharmaceutical manufacturers in Germany and Switzerland now mandate these for sterile fluid handling under tightened EU MDR extractables testing protocols.
- Capacitive Sensors:Electrode-based detection without moving parts dominates water treatment and general industrial tanks where electrical isolation is unnecessary. Low unit costs displace optical alternatives in applications where precision remains secondary to capital expenditure minimization.
- Ultrasonic Sensors:Time-of-flight acoustic measurement suits large storage vessels with foam or vapor interference that corrupts optical signals.
- Magnetic Float Sensors:Mechanical reed-switch designs persist in legacy automotive and food processing installations requiring simple on-off level indication.
Optical sensors absorb the bulk of installed capacity in pharmaceutical and corrosive process environments; capacitive sensors are expanding most quickly into water treatment commoditization.
End User:
Customer procurement maturity separates specification-driven buyers from price-tender participants.
- Industrial Manufacturing:Chemical processing facilities deploy fiber optic sensors for electrical isolation in acid-handling operations where metallic probes corrode. ECHA REACH compliance requirements now govern wetted material selection across European installations.
- Automotive:Electric vehicle battery coolant monitoring demands infrared sensing with sub-second response times to prevent thermal runaway events. OEM thermal management system integrators in Stuttgart and Munich specify validated sensor modules.
- Water Treatment:Municipal and industrial water facilities source LED-based sensors through distribution channels, unbundling procurement from system integrator contracts.
- Food & Beverage:Hygienic design requirements under FDA 21 CFR and ISO 14159 constrain sensor housing materials and surface finish specifications.
Industrial manufacturing commands the highest specification density per installation; automotive represents the steepest expansion trajectory as EV thermal management scales.
Technology:
Cost tier stratification separates premium fiber optic validation from high-volume LED manufacturing.
- Fiber Optic:Silica-based light transmission with complete electrical isolation commands premium positioning in corrosive, high-temperature, and explosive atmospheres. Rare-earth doped fiber input costs tie pricing to semiconductor material cycles.
- Infrared:Solid-state emitters and photodetectors integrated into compact probe formats serve medical diagnostic instruments and battery thermal monitoring where rapid response matters.
- LED:Cost-optimized visible and near-infrared sources dominate bulk tank applications with standard refractive index media and minimal regulatory burden.
- Laser:Coherent light sources enable precision distance measurement in specialized process control applications requiring exact meniscus detection.
Fiber optic technology captures the highest value per unit; LED is gaining share fastest through distribution channel disintermediation.
Application:
Functional use case determines sensor specification intensity and replacement frequency.
- Level Monitoring:Continuous height measurement in storage vessels and process tanks constitutes the baseline deployment across all end-use sectors.
- Leak Detection:Point-level optical probes in containment sumps and secondary enclosures serve environmental compliance functions under EPA spill prevention regulations.
- Process Control:Real-time level feedback into PLC systems demands calibrated 4-20mA or digital outputs with documented measurement uncertainty.
- Inventory Management:Tank farm operators integrate level data into ERP systems for automated replenishment and custody transfer documentation.
Level monitoring accounts for the majority of unit shipments; leak detection is climbing the fastest as environmental liability frameworks tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European optical sensor demand through its dense concentration of automotive thermal management and pharmaceutical manufacturing clusters.
Germany
Automotive OEMs in Stuttgart and Munich specify infrared sensors for battery coolant monitoring in electric vehicle platforms. KBA type-approval processes govern thermal management component validation timelines. Bavarian pharmaceutical manufacturers under EU MDR extractables mandates drive fiber optic probe deployment in sterile fluid pathways.
United States
Cell therapy manufacturers in Greater Boston and the San Francisco Bay Area require disposable optical sensors for closed-system bioreactors. FDA 21 CFR Part 11 compliance shapes sensor firmware and data integrity specifications. South Carolina automotive suppliers integrate level monitoring into EV battery pack assembly lines.
China
Green hydrogen electrolyzer projects in the Yangtze River Delta and Shandong Peninsula demand corrosion-resistant level sensors for alkaline and PEM stack operations. MIIT industrial equipment standards accelerate domestic sensor certification requirements. Shenzhen automation distributors bundle LED-based sensors with machine vision systems for tank monitoring.
Japan
Precision medical device manufacturers in Osaka and Nagoya adopt compact infrared probes for point-of-care diagnostic instruments. METI carbon neutrality roadmaps push hydrogen infrastructure sensor deployment. Toyota City thermal management suppliers validate sub-second response sensors for next-generation battery platforms.
Switzerland
Swissmedic pharmaceutical regulations in Basel drive the strictest EU MDR material validation interpretations for sterile fluid handling. Rare-earth doped fiber supply chains concentrate around precision optics clusters. Geneva-area analytical instrumentation manufacturers specify pre-validated disposable sensor modules for high-throughput screening systems.
Optical Liquid Level Sensor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered certification grades. The market structures around three strategic archetypes: automation conglomerates bundling level sensing with vision systems, hazardous-area specialists anchoring European process industries, and compact probe manufacturers occupying medical instrumentation niches. Dominant competitive moves include distribution channel disintermediation in East Asian manufacturing hubs and MDR validation dossier accumulation for pharmaceutical market access.
Within the automation systems tier, Keyence leverages its East Asian channel dominance to bundle level sensing with machine vision platforms. Pepperl+Fuchs anchors European positioning through hazardous-area certifications and process industry relationships. SST Sensing Ltd exemplifies the compact probe specialist archetype, occupying a defensible niche in medical and analytical instrumentation against larger diversified competitors.
| Leading Market Players |
|---|
| Keyence |
| Pepperl+Fuchs |
| Banner Engineering |
| Honeywell |
| Baumer |
| IFM Electronic |
| Omron |
| SST Sensing Ltd |
| SICK AG |
| Others |
Value Network & Pricing Analysis
Captive fiber drawing operations in Germany and Switzerland anchor premium-tier positioning for EU MDR-validated probes, while outsourced LED assembly in East Asia locks commodity-tier suppliers into distributor-dictated pricing schedules. This integration split directly determines which manufacturers command specification premiums versus those competing on fulfillment speed.
Pricing Analysis
Outcome-based pricing tied to sterilization cycle validation anchors fiber optic premiums in pharmaceutical applications. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified probes from industrial-grade units and unbranded LED sensors. Price differentiation rests on certification grade and rare-earth fiber content. Cost compression in the LED tier is intensifying because East Asian distributors now stock generic sensors for same-day fulfillment. Water treatment buyers exhibit highest price sensitivity; cell therapy manufacturers show lowest.
Supply Chain Analysis
Freight costs for rare-earth doped fibers from China and specialty silica from the United States compound input volatility for precision-grade manufacturers. Supply concentration clusters in Germany, Switzerland, and Japan for fiber optic probes; China, South Korea, and Taiwan for LED emitter components. Raw material dependencies draw from germanium-doped silica, gallium arsenide substrates, and medical-grade polymer housings. Single-source vulnerability around EU Notified Body certification creates bottlenecks for pharmaceutical market entry. Distribution runs through industrial automation channels in East Asia and direct OEM relationships in European pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified Body validation capacity constraints prop pricing power for incumbent fiber optic suppliers, as EU MDR extractables testing backlogs extend material qualification timelines beyond standard product development cycles.
For Market Incumbents: Deepen vertical integration into rare-earth fiber drawing to insulate margin structures from semiconductor material cycles. Prioritize captive validation dossier accumulation at German and Dutch Notified Bodies to defend against emerging fiber optic specialists. Capacitive substitution in water treatment represents the primary displacement threat requiring tiered product line segmentation. For New Entrants and Emerging Players: The mid-tier price gap between MDR-validated fiber optics and commodity LED sensors offers entry space for ISO 13485-certified infrared probe manufacturers. Target green hydrogen electrolyzer projects in China's Yangtze River Delta where corrosion-resistant specifications outpace established supplier capacity. Go-to-market leverage rests on pre-validated disposable sensor formats for cell therapy bioreactors. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to automation conglomerates seeking pharmaceutical certification assets. Long-term viability favors suppliers with dual-use fiber optic platforms spanning medical and industrial hazardous-area applications. Acquisition target archetype: compact probe specialists with existing ISO 13485 infrastructure and Swissmedic relationship history. Watch EU MDR cybersecurity annex implementation as inflection signal for firmware-enabled sensor compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Validation Dossier Accumulation | EU Notified Body relationships in Germany and the Netherlands secure pharmaceutical market access against competitors. |
| Rare-Earth Fiber Backward Integration | In-house drawing of germanium-doped silica insulates margin structures from semiconductor material pricing cycles. |
| Disposable Sensor Format Development | Pre-validated single-use probes capture cell therapy manufacturing demand in Greater Boston and San Francisco Bay Area clusters. |
| Green Hydrogen Electrolyzer Partnership | Corrosion-resistant level monitoring for alkaline and PEM stacks addresses capacity gaps in China's Yangtze River Delta. |
| Sensor-Vision System Bundling | Integration with machine vision platforms leverages Keyence's East Asian channel dominance for tank monitoring solutions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical engineers, pharmaceutical manufacturing executives, GPO contracts managers, and aftermarket service heads combined with secondary validation from FDA 510(k) filings, EMA MDR submissions, EU Notified Body certification databases, and industrial automation distributor inventory records. Bottom-up sensor shipment estimates triangulated against top-down pharmaceutical capital expenditure patterns.
Data-stream reconciliation across product type, technology tier, end-use industry, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs were derived from segmented growth rate modeling throughout the forecast period. Industry-specific inputs included EU MDR extractables testing timeline data and electric vehicle thermal management system integration specifications.
Inputs from FDA and EMA filings were available through the study window; gaps in private-label distributor shipment data introduce uncertainty bands around LED sensor volume estimates. Forecasts reflect assumptions regarding Notified Body capacity expansion and semiconductor material pricing stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Advanced Optics Market
Optics
Fiber-Optic Couplers Market
Optics
Global Optical Lens Market
Optics
APAC Smart Glass Market
Optics
Optical Telescope Market
Optics
Smart Photochromic Lenses Market
Optics
Fiber Optic Development Tools Market
Optics
Collimating Lens Market
Optics
Smart Glass Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Glass Scintillator Market
Optics
Germanium Lens Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Optical Lens for Mobile Phone Market
Optics
Digital Holographic Microscopy Market
Optics
Photonics Sensor Market