
 Semiconductor Materials Market | 2026-2036
Semiconductor Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Materials Market Intelligence
The direct-to-foundry sales channel for bulk materials is narrowing the role of regional distributors, particularly for high-volume consumables. Shin-Etsu Chemical Co., Ltd. sustains its market leadership in silicon wafer production through massive manufacturing scale and R&D investment. Air Liquide SA specializes in supplying the ultra-high purity gases essential for advanced fabrication processes. DuPont de Nemours Inc. competes with a broad portfolio of photolithography, CMP, and advanced packaging materials for integrated device manufacturers.
Semiconductor materials are substances with specific electrical properties used to fabricate microelectronic devices. These materials, such as silicon, must achieve extreme purity levels, often exceeding 99.9999999%, to function correctly in integrated circuits. Their primary purpose is to create the patterned layers of conductive, insulating, and semiconducting pathways that form transistors. While silicon remains the foundational material type by volume for logic and memory devices, compound materials like Gallium Arsenide and Silicon Carbide are critical for optoelectronics and power devices.
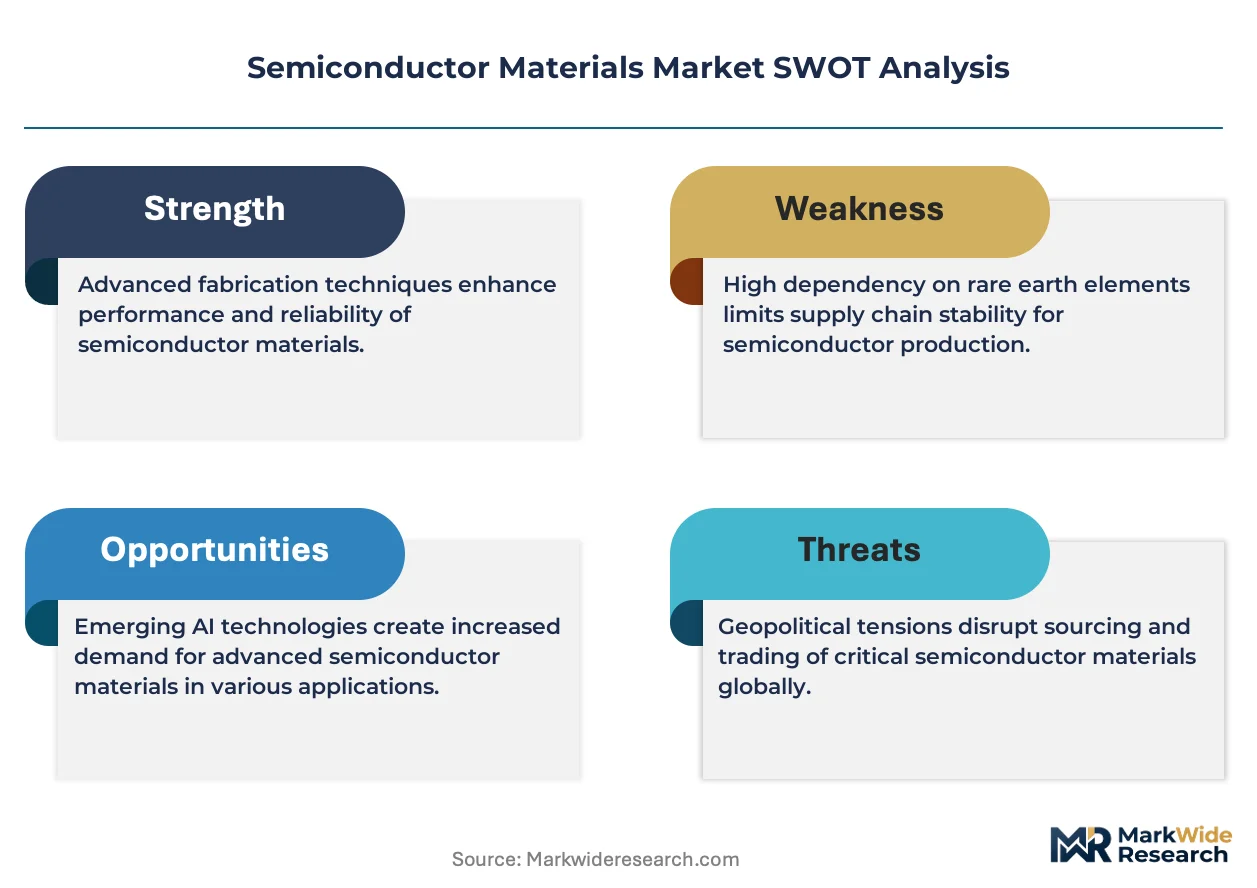
Environmental and safety regulations, including the EU's REACH and RoHS directives, govern the chemical composition and handling of many semiconductor materials. In the United States, the EPA sets standards for chemical production and waste, while China's MEE imposes strict environmental controls on manufacturing facilities. Navigating the complex web of national trade policies and securing resilient supply chains for critical raw materials remains a central strategic challenge for market participants.
Market Dynamics
The semiconductor materials market is fundamentally shaped by the dual pressures of Moore's Law and application diversification. This creates a constant demand for higher-purity substances for advanced logic nodes while simultaneously requiring novel compound materials for power and optoelectronic devices.
Growth Catalysts
- Advanced Logic Nodes:The push toward nodes below 5nm necessitates the use of new materials, such as cobalt and ruthenium for interconnects, and advanced photoresists for EUV lithography, driving demand for higher-value consumables.
- Power and RF Devices:Demand for wide-bandgap materials, especially Silicon Carbide (SiC) and Gallium Nitride (GaN), is accelerating due to their use in high-efficiency power electronics for electric vehicles and 5G radio frequency components.
- Industrial Policy:Government initiatives, including the US CHIPS Act and the European Chips Act, are stimulating investment in domestic semiconductor fabrication, which in turn creates localized demand for a complete ecosystem of material suppliers.
Market Restraints
- Extreme Capital Intensity:The construction of facilities capable of producing ultra-high purity materials and the associated metrology equipment requires massive upfront capital investment, creating high barriers to entry for new suppliers.
- Raw Material Concentration:The geographic concentration of critical raw minerals, such as specific rare earth elements used in dopants and polishing compounds, exposes the supply chain to geopolitical risks and price volatility.
- Technical Hurdles in Compound Semiconductors:Manufacturing large-diameter, defect-free wafers from compound materials like Gallium Arsenide (GaAs) or Indium Phosphide (InP) remains technically challenging and costly compared to silicon, limiting their scalability.
Strategic Opportunities
- Advanced Packaging Materials:The shift toward heterogeneous integration and 3D packaging creates significant opportunities for suppliers of dielectric films, underfills, and substrates that enable technologies like fan-out wafer-level packaging (FOWLP).
- Sustainable Materials and Circularity:Developing greener chemistries, reducing water and energy consumption in purification processes, and creating pathways for recycling materials like silicon wafers offers a competitive advantage amid growing ESG scrutiny.
- Geographic Diversification:As new fabrication clusters are established in the United States and Europe to enhance supply chain resilience, opportunities arise for material suppliers to co-locate facilities and secure long-term contracts.
Industry Challenges
- Specialized Talent Shortage:A critical deficit exists for materials scientists, chemical engineers, and process technicians with the specific expertise required for developing and scaling production of next-generation semiconductor materials.
- Regulatory Compliance Burden:Navigating the complex and divergent chemical regulations across major markets, such as the EU's REACH framework and the EPA's TSCA in the US, introduces significant administrative overhead and can delay product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Materials Market |
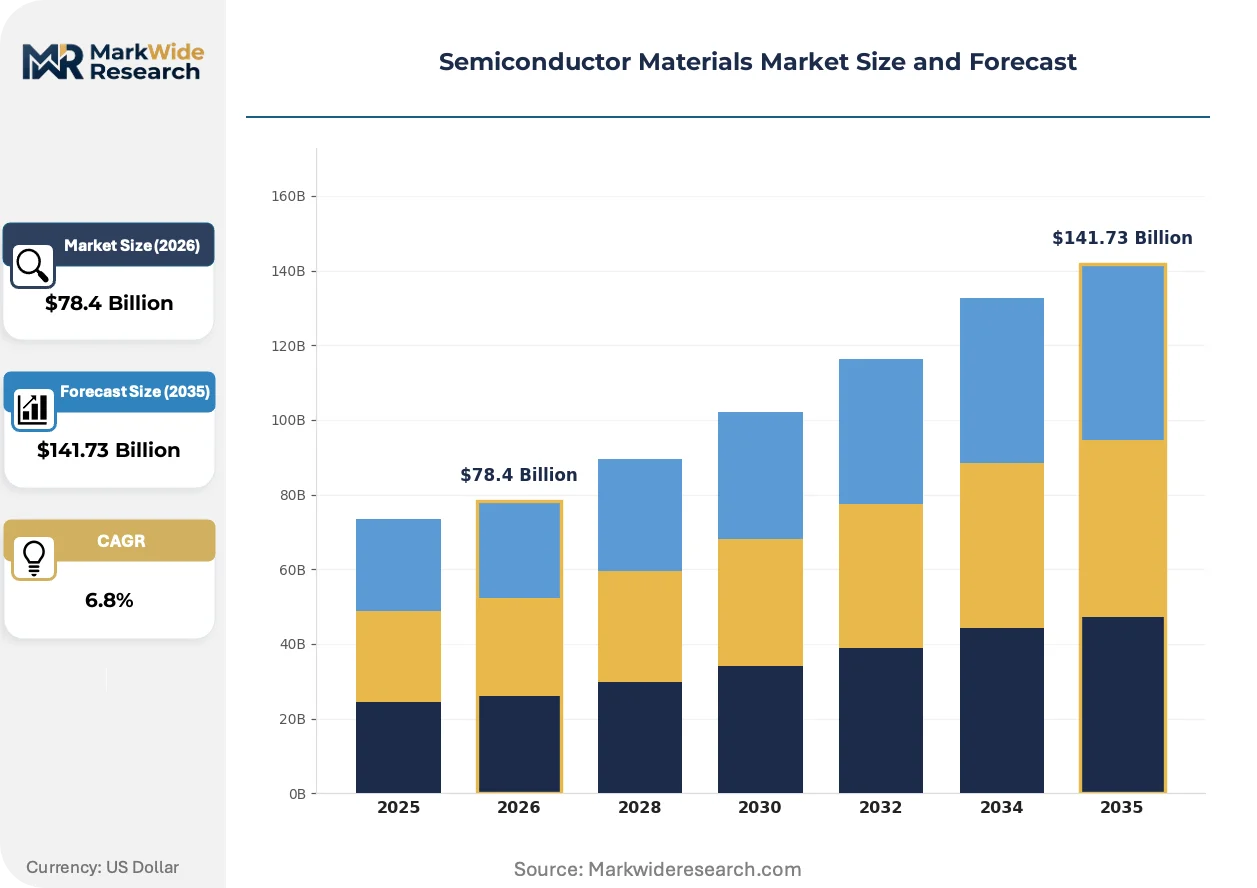
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silicon, Gallium Arsenide, Silicon Carbide, Indium Phosphide, Germanium Technology: Photolithography, Chemical Vapor Deposition, Molecular Beam Epitaxy, Atomic Layer Deposition, Diffusion Application: Consumer Electronics, Power Devices, Optoelectronics, Memory Devices, Sensors End User: Fabrication Units, Foundries, Integrated Device Manufacturers, Assembly & Packaging Firms |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., BASF SE, DuPont de Nemours Inc., Air Liquide SA, Sumco Corporation, Henkel AG, JSR Corporation, Tokyo Ohka Kogyo Co., Ltd., Cabot Microelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Materials Market Strategic Shifts & Innovations
The innovation trajectory in semiconductor materials is bifurcating. One path pursues atomic-level perfection and novel elements for next-generation logic, while the other focuses on engineering the unique properties of compound materials for specialized, high-growth applications beyond traditional computing.
Extreme Ultraviolet (EUV) lithography photoresists are critical materials that define circuit patterns at the most advanced nodes. Leading-edge foundries concentrated in Taiwan and South Korea are the primary consumers, driving rapid innovation cycles. The technology for patterning sub-3nm features is migrating from traditional chemically amplified resists (CARs) toward novel metal-oxide resists (MORs) to achieve superior resolution and lower defectivity.
Regulations like the EU's REACH and RoHS directives directly influence material composition and supply chain transparency. These rules require comprehensive registration for chemicals and restrict hazardous substances in electronic equipment, forcing reformulation of products like solders and packaging materials. Consequently, global material suppliers must invest heavily in compliance and documentation to maintain access to the European market, treating regulatory adherence as a core product attribute.
Direct-to-foundry sales models are altering the distribution landscape for high-volume consumables. This shift sees large semiconductor manufacturers bypassing regional distributors to engage directly with material producers for items like bulk gases and wafers. This trend is most visible in the concentrated fabrication ecosystems of Asia, where it allows for tighter supply chain integration and collaborative material development.
Semiconductor Materials Market Segmentation
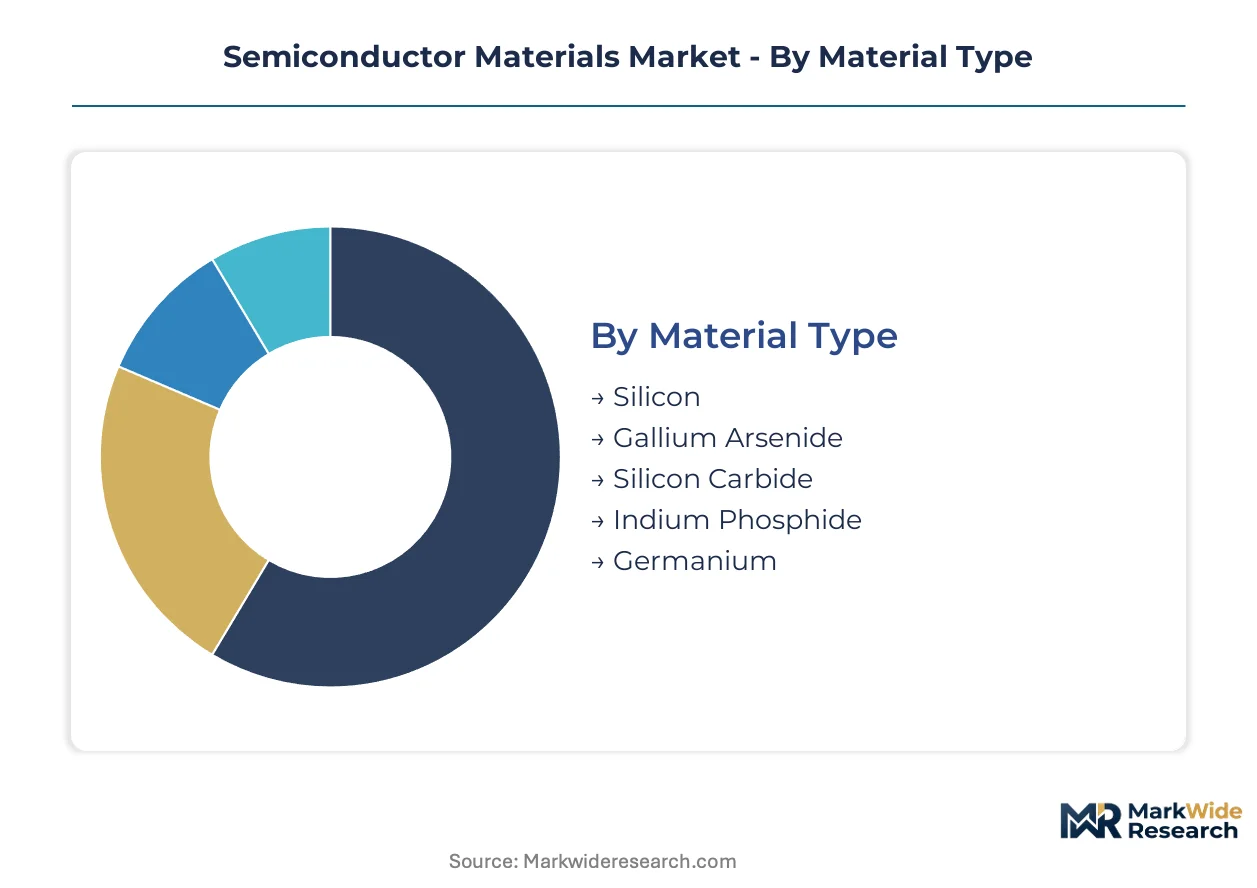
Understanding the segmentation within the semiconductor materials market provides crucial insights into demand drivers and technological shifts. Each category highlights distinct aspects of material composition, processing methods, end-use applications, and consumer types. This detailed breakdown helps identify where value is created and how supply chains are structured across different market verticals.
Material Type:
The composition of semiconductor materials directly influences device performance and manufacturing complexity.
- Silicon:This foundational material for logic and memory devices requires ultra-high purity levels, often exceeding 99.9999999%, for advanced nodes. Demand concentrates in Taiwan and South Korea's fabrication hubs for microprocessors and DRAM, driven by continuous scaling under Moore's Law.
- Silicon Carbide:A wide-bandgap compound semiconductor offering superior thermal conductivity and breakdown voltage compared to silicon. Demand accelerates in electric vehicle power electronics and renewable energy systems due to efficiency requirements.
- Gallium Arsenide:This compound material finds primary use in high-frequency radio frequency components and specialized optoelectronic devices.
- Indium Phosphide:Critical for high-speed fiber optic communications and advanced optoelectronic applications.
- Germanium:Utilized in high-frequency transistors and infrared optics, often as an alloy with silicon.
Silicon holds installed capacity. Silicon Carbide is rotating up the share rankings.
Technology:
The processing method employed dictates the precision and material requirements for creating intricate circuit patterns.
- Photolithography:This process uses light to transfer circuit patterns onto a substrate, with Extreme Ultraviolet (EUV) lithography enabling sub-5nm features. Demand concentrates in leading-edge foundries in Asia for high-volume logic and memory device manufacturing.
- Atomic Layer Deposition:A precise thin-film deposition technique creating conformal layers one atomic layer at a time, crucial for gate dielectrics and interconnects. Demand grows for advanced node devices requiring ultra-thin, uniform material layers for optimal performance.
- Chemical Vapor Deposition:This method involves chemical reactions to deposit thin films of materials onto substrates in a controlled environment.
- Molecular Beam Epitaxy:An ultra-high vacuum process for growing high-quality crystalline thin films, especially for compound semiconductors.
- Diffusion:A thermal process used to introduce dopants into semiconductor wafers, altering their electrical properties.
Photolithography processes represent the largest material consumption. Atomic Layer Deposition is experiencing the steepest expansion trajectory.
Application:
End-use scenarios define the specific material properties and performance characteristics required for device functionality.
- Power Devices:These components handle high voltages and currents efficiently, often leveraging wide-bandgap materials like Silicon Carbide and Gallium Nitride. Demand is driven by electric vehicles, industrial motor drives, and renewable energy systems for energy conversion.
- Memory Devices:Integrated circuits storing digital data, including DRAM and NAND flash, require ultra-pure silicon wafers and advanced dielectric materials. Demand is sustained by data centers, smartphones, and artificial intelligence applications requiring high-density storage.
- Consumer Electronics:This segment utilizes a broad range of semiconductor materials for microprocessors, displays, and sensors in devices like smartphones and laptops.
- Optoelectronics:This field integrates optics and electronics, relying on compound semiconductors for LEDs, lasers, and photodetectors.
- Sensors:Devices that detect physical inputs require specialized materials for converting stimuli into electrical signals.
Consumer Electronics drives broad material volume. Power Devices are gaining share fastest.
End User:
The type of manufacturing entity influences material procurement strategies and required purity specifications.
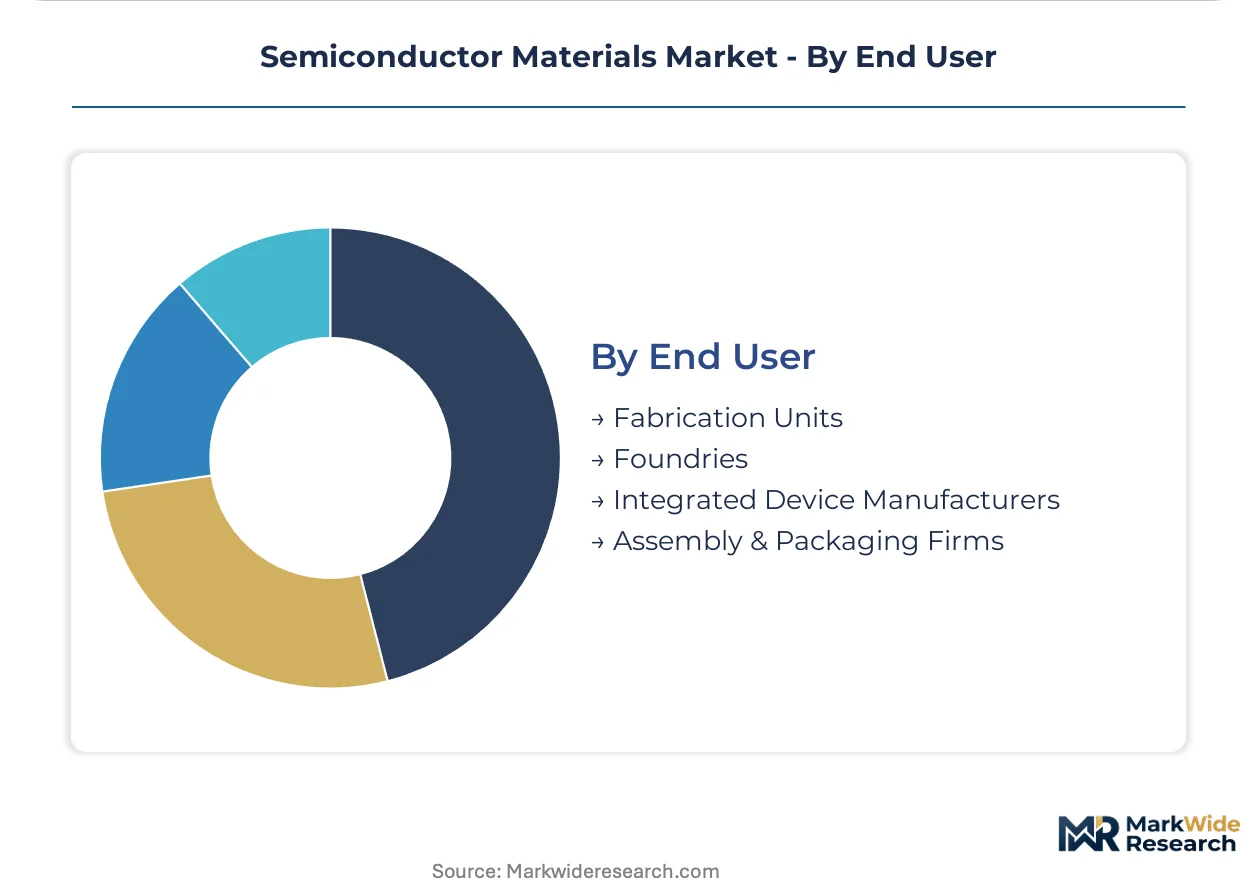
- Foundries:Companies specializing in semiconductor manufacturing for other firms require high volumes of standardized and advanced materials. Demand concentrates in Taiwan and South Korea, driving direct-to-foundry sales models for bulk consumables.
- Integrated Device Manufacturers:Firms that design, manufacture, and sell their own semiconductor devices maintain internal material specifications. Demand is influenced by a diverse product portfolio spanning logic, memory, and analog components, requiring a wide material range.
- Fabrication Units:This term broadly refers to facilities where semiconductor wafers are processed, consuming various materials for each manufacturing step.
- Assembly & Packaging Firms:These firms focus on the final stages of semiconductor production, utilizing materials like underfills, bonding wires, and encapsulants.
Foundries represent the largest material procurement volume. Assembly & Packaging Firms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global semiconductor fabrication infrastructure underpins regional demand for advanced materials. The market for semiconductor materials is geographically concentrated, driven by the presence of major foundries and integrated device manufacturers. This concentration necessitates robust supply chains and localized support for high-purity material delivery.
Taiwan
Taiwan's advanced foundry ecosystem drives substantial demand for EUV photoresists and ultra-high purity silicon wafers. The government's industrial policies support domestic material production and R&D for next-generation semiconductor technologies. The Hsinchu Science Park remains a critical hub, attracting extensive investment in advanced material synthesis and testing facilities.
South Korea
South Korea's leadership in memory and advanced packaging technologies creates a strong pull for specialized dielectric films and compound semiconductors. The K-Semiconductor Strategy promotes self-sufficiency in critical materials and equipment. Gyeonggi Province, with its dense concentration of fabrication plants, serves as a focal point for material suppliers and collaborative innovation.
United States
The United States' resurgent fabrication capacity, spurred by the US CHIPS Act, generates new demand for a wide range of materials, including those for advanced logic and power devices. The EPA sets stringent standards for chemical production and waste management, influencing material development. New manufacturing clusters in Arizona, New York, and Texas are attracting co-located material suppliers.
Germany
Germany's strong automotive and industrial sectors fuel demand for Silicon Carbide and Gallium Nitride materials for power electronics. The European Chips Act aims to bolster regional semiconductor manufacturing, including material supply chains. Dresden's "Silicon Saxony" cluster is expanding its material science capabilities to support local and European fabrication needs.
Japan
Japan's established base in semiconductor equipment and materials manufacturing sustains demand for high-purity gases and advanced chemical mechanical planarization (CMP) slurries. The Economic Security Promotion Act provides incentives for domestic semiconductor supply chain strengthening. Kumamoto, home to new foundry investments, is becoming a key area for material supply chain development.
Semiconductor Materials Market Key Industry Players
On the supply side, the industry is highly specialized, characterized by a tiered structure where a few large chemical and materials companies dominate foundational segments. Strategic archetypes include diversified chemical giants, specialized high-purity material providers, and niche compound semiconductor manufacturers. Dominant competitive moves involve massive R&D investment and continuous capacity expansion to meet stringent purity and volume demands.
Specialists in silicon wafer production, such as Shin-Etsu Chemical Co., Ltd., maintain market leadership through significant manufacturing scale. Air Liquide SA exemplifies a key supplier in ultra-high purity gases, essential for advanced fabrication processes. DuPont de Nemours Inc. occupies a position as a diversified materials provider, offering a broad portfolio spanning photolithography and advanced packaging solutions.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| BASF SE |
| DuPont de Nemours Inc. |
| Air Liquide SA |
| Sumco Corporation |
| Henkel AG |
| JSR Corporation |
| Tokyo Ohka Kogyo Co., Ltd. |
| Cabot Microelectronics |
| Others |
Cost & Logistics Intelligence
Taiwan and South Korea's concentrated advanced fabrication hubs create significant upstream pricing power for specialized material suppliers. This dynamic centralizes margin pools within a select group of high-purity chemical and wafer producers.
Pricing Analysis
Volume-based contract pricing dominates the semiconductor materials market, particularly for bulk consumables like silicon wafers and inert gases. Price differentiation stems from achieving ultra-high purity levels for advanced nodes and specific material certifications required for EUV lithography. Pricing softness stems from large foundries leveraging their procurement scale for high-volume consumables. Specialized materials for sub-5nm features exhibit lower price sensitivity due to their critical performance impact, while commodity-grade materials face intense competition.
Supply Chain Analysis
Export controls and national security regulations, such as those impacting advanced technology transfers, increasingly limit the free flow of critical semiconductor materials. Geographic concentration in Taiwan, South Korea, and Japan creates dependencies for critical raw materials like rare earth elements and specialized photoresist chemicals. This exposes the supply chain to geopolitical risks and single-source vulnerabilities. Direct-to-foundry sales models dominate for high-volume consumables, while specialized distributors handle niche compound materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor materials market functions as a defensive moat story, characterized by high switching costs for foundries due to extreme purity requirements and deep process integration. This creates significant barriers to entry and sustains incumbent market positions.
For Market Incumbents:Pre-empt emerging entrant archetypes by doubling down on massive R&D investments for sub-3nm materials and advanced packaging solutions. Expand capacity in strategic regions like the United States and Europe to secure long-term contracts and mitigate geopolitical supply chain risks. Invest heavily in next-generation material certification processes, ensuring regulatory compliance and maintaining high switching costs for integrated device manufacturers.
For New Entrants and Emerging Players:Establish a beachhead in underserved segments like advanced packaging materials or sustainable chemistries for purification processes. The most penetrable segment lies within specialized compound materials for power devices, where performance gains outweigh initial cost. Focus on collaborative R&D partnerships with smaller fabless design houses and niche foundries to co-develop application-specific solutions.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with highly specialized materials science firms possessing unique IP in advanced purification or synthesis. The market offers strong long-term viability, driven by continuous technological advancement and diversification into power and optoelectronics. Target niche players with proprietary processes for critical raw material refining or advanced photoresist formulation. A key signal to watch is the successful commercialization of novel metal-oxide resists for EUV lithography, indicating market readiness for next-generation materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Ensures material availability for growing demand in Taiwan and South Korea fabrication hubs. |
| R&D Investment | Develops novel photoresists and compound materials critical for sub-5nm nodes and power devices. |
| Green Manufacturing Transition | Reduces environmental impact, aligning with EU REACH and EPA regulations. |
| Long-term Supply Agreement | Secures material off-take for foundries, stabilizing revenue streams for suppliers. |
| Geographic Footprint Diversification | Supports new fabrication clusters in the US and Europe, enhancing supply chain resilience. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews, complemented by rigorous secondary validation. Stakeholders included materials scientists, chemical engineers, foundry procurement managers, and fab process technicians. Secondary data sources comprised scientific journals, government reports from EPA and MEE, corporate financial filings, and semiconductor trade association publications. This approach enabled comprehensive bottom-up and top-down triangulation of market data.
The analytical framework was calibrated through a multi-stage iterative process, integrating quantitative models with qualitative insights across the analysis window. Segmentation dimensions modeled included material type, processing technology, end-use application, end-user archetype, and regional fabrication intensity. Compound Annual Growth Rates were derived from historical data, expert consensus, and projected technological shifts. Key forecast inputs included advanced node roadmap adoption rates and electric vehicle production forecasts.
Stress conditions across geopolitical stability, raw material supply, and technological breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding advanced node progression and material innovation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
ITO Nanoparticles Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Tellurium Market