
 Global Gallium Nitride Market | 2026-2036
Global Gallium Nitride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gallium Nitride Market Foresight
A shortage of compound semiconductor process engineers is unwinding capacity expansion timelines across the gallium nitride supply chain. Wolfspeed, Inc. anchors North American substrate production through its silicon carbide and GaN-on-SiC platform investments. Infineon Technologies AG leverages its integrated manufacturing footprint to control costs across discrete devices and power integrated circuits. GaN Systems Inc. specializes in high-frequency transistor architectures for consumer electronics and telecommunications customers.
Gallium nitride is a wide-bandgap semiconductor with a 3.4 eV bandgap, manufactured primarily through metal organic chemical vapor deposition on silicon or silicon carbide substrates to achieve breakdown voltages exceeding 600V in power switching applications. Its primary commercial purpose is to replace silicon in power electronics and RF systems where efficiency, thermal performance, and switching speed determine system economics. Discrete devices dominate current revenue as the most mature product category, while integrated circuits capture expanding margin pools in RF front-end modules for 5G infrastructure. Metal organic chemical vapor deposition leads technology adoption due to throughput advantages, though hydride vapor phase epitaxy is gaining traction for thick GaN layers in power applications.
The U.S. Environmental Protection Agency and the Department of Energy impose efficiency benchmarks on data center power supplies and electric vehicle chargers that GaN technology satisfies more readily than incumbent silicon solutions. Europe's Ecodesign requirements under the F-Gas Regulation and REACH chemical restrictions shape material selection and product qualification pathways for GaN device manufacturers seeking EU market access. China's Ministry of Industry and Information Technology channels domestic capacity expansion through national semiconductor development frameworks. Stakeholders must monitor how evolving efficiency mandates across these jurisdictions alter qualification timelines and customer procurement criteria for wide-bandgap components.
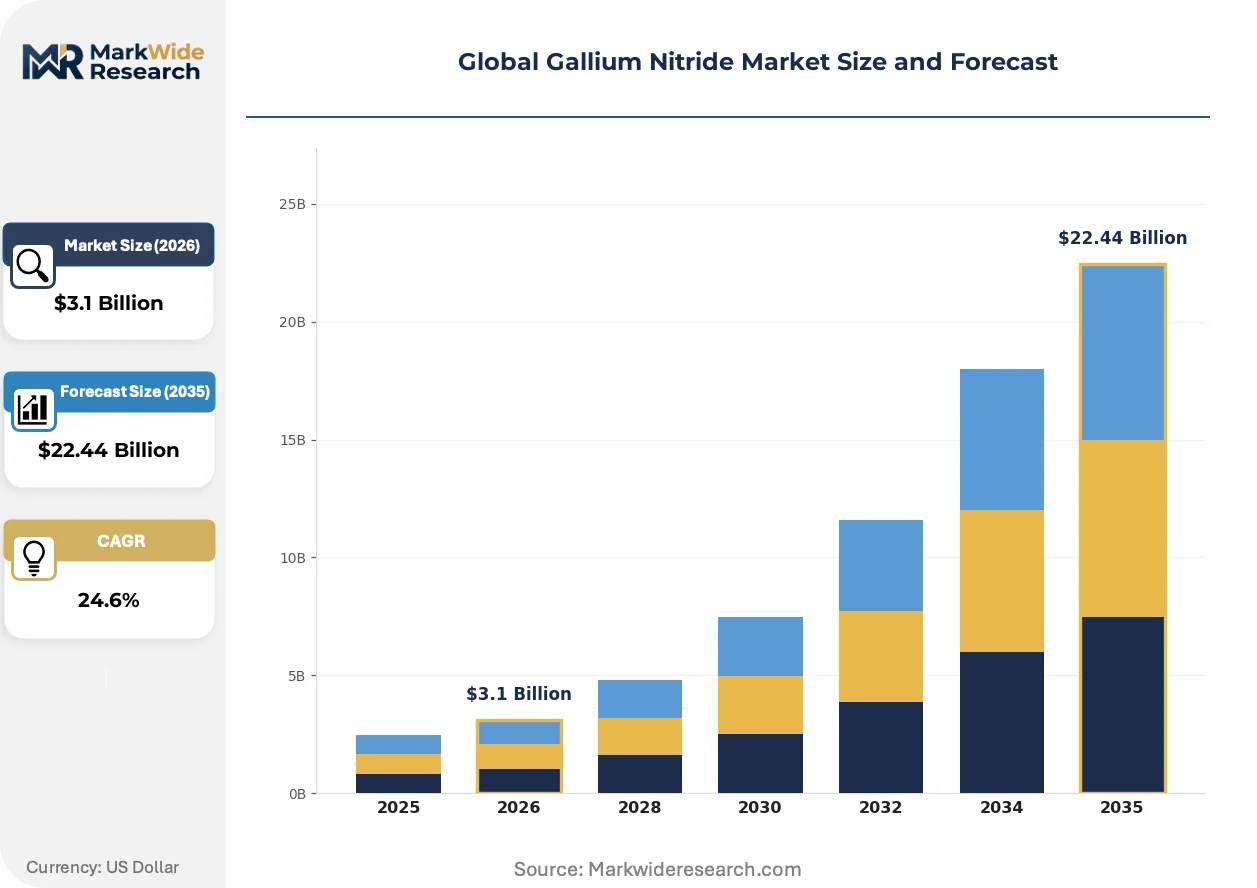
Market Dynamics
Efficiency mandates from regulators in the United States, Germany, and China are compressing qualification timelines and forcing power electronics buyers to abandon silicon for wide-bandgap alternatives faster than supply chains can adapt.
Growth Catalysts
- EPA efficiency benchmarks:The U.S. Environmental Protection Agency imposes power supply standards on data centers that GaN satisfies more readily than silicon, accelerating procurement in hyperscale facilities.
- 5G base station deployments:Wireless communication infrastructure expansion demands high-frequency transistors for massive MIMO arrays, pulling GaN-on-SiC devices into macro and small cell networks.
- China MIIT semiconductor frameworks:China's Ministry of Industry and Information Technology channels state investment into domestic GaN fabrication capacity for electric vehicle inverters and telecommunications.
Market Restraints
- Substrate cost volatility:Silicon carbide wafer prices fluctuate with raw material purity constraints and furnace capacity bottlenecks, compressing margins for GaN-on-SiC device manufacturers.
- Process engineer scarcity:Compound semiconductor fabrication requires specialized metal organic chemical vapor deposition expertise that universities and incumbent fabs cannot produce at scale.
- REACH chemical restrictions:Europe's Registration, Evaluation, Authorisation and Restriction of Chemicals regulation complicates precursor material sourcing for epitaxial growth operations.
Strategic Opportunities
- India PLI scheme:India's Production Linked Incentive program for semiconductors creates tariff advantages and capital subsidies for GaN device manufacturing serving domestic solar inverter and EV markets.
- GaN-on-silicon automotive inverters:Electric vehicle powertrain designers are evaluating cost-reduced GaN-on-silicon platforms for 400V architectures where silicon carbide remains over-specified.
- EU Green Deal industrial heat:The European Union's carbon neutrality targets mandate efficiency upgrades in industrial motor drives, opening qualification pathways for GaN power modules in pump and compressor applications.
Industry Challenges
- Compound semiconductor process engineering talent:Fabs report eighteen-month hiring cycles for metal organic chemical vapor deposition technicians, delaying equipment ramp schedules.
- Automotive AEC-Q101 certification timelines:Qualification for under-hood power switching devices requires extended temperature cycling and humidity testing that extends time-to-revenue by two to three years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gallium Nitride Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $22.44 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete Devices, Integrated Circuits, Power Amplifiers, Transistors Technology: Metal Organic Chemical Vapor Deposition, Hydride Vapor Phase Epitaxy, Molecular Beam Epitaxy, Ammonothermal Application: Wireless Communication, Radar Systems, RF and Microwave Transmitters, Optical Sensors, Aviation Electronics End User: Consumer Electronics Manufacturers, Telecommunications Providers, Defense Equipment Makers, Semiconductor Fabricators |
| Companies Covered | Navitas Semiconductor, Qorvo, Inc., Wolfspeed, Inc., Infineon Technologies AG, Sumitomo Electric Industries, Ltd., Efficient Power Conversion Corporation, GaN Systems Inc., Transphorm Inc., NXP Semiconductors N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gallium Nitride Market Shifts & Advancements
Wafer-scale integration and epitaxial growth advances are collapsing the cost gap between gallium nitride and legacy silicon power devices while regulatory pressure compresses buyer decision cycles.
GaN-on-silicon technology leverages existing 200mm and 300mm CMOS fabrication infrastructure to produce cost-competitive power transistors for sub-650V applications. Consumer electronics adapter manufacturers and data center power supply designers are adopting these platforms for volume production. The technology is supplanting superjunction MOSFETs in server power supplies and laptop chargers where efficiency and power density determine procurement awards.
The EU F-Gas Regulation tightens phase-down schedules for fluorinated greenhouse gases used in semiconductor etching and cleaning processes, forcing GaN manufacturers to qualify alternative chemistries. Equipment suppliers must redesign process chambers and exhaust handling systems to maintain throughput under constrained chemistries. German and French fabs face the most immediate compliance deadlines as their national environmental agencies enforce the strictest interpretation of allowable emissions thresholds.
Hyperscale data center operators now specify 80 PLUS Titanium efficiency standards in procurement tenders, eliminating silicon-based designs from shortlists. Power supply original design manufacturers are responding with GaN-based totem-pole PFC architectures that deliver the required conversion efficiency at higher switching frequencies. This specification-driven substitution is most visible in North American cloud regions where electricity costs and carbon accounting pressure concentrate procurement authority among three dominant buyers.
Global Gallium Nitride Market Segmentation
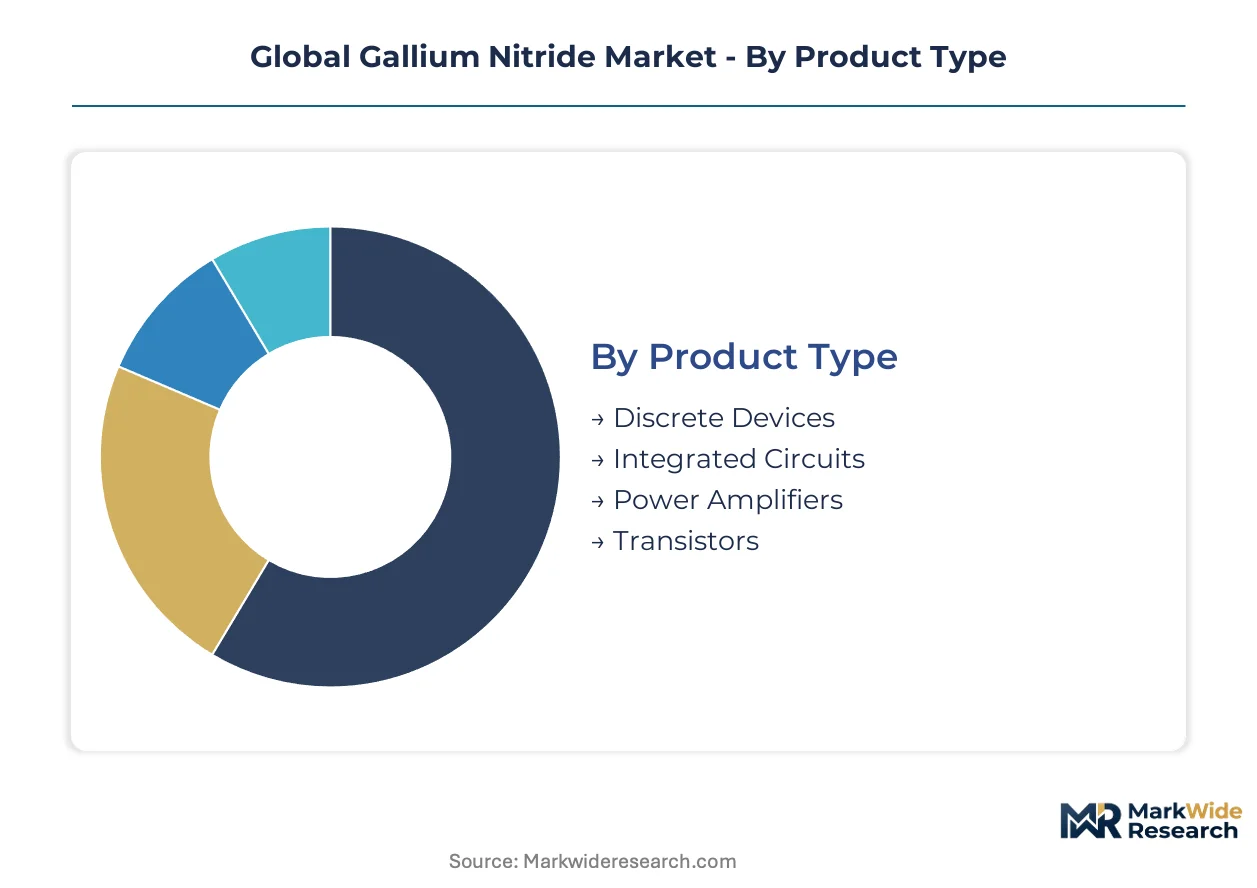
Segmentation in the gallium nitride market reveals how technology choices cascade through manufacturing economics and end-use qualification requirements. Product architecture and epitaxial growth methods determine which customer segments can be served profitably at scale.
Product Type:
Discrete devices flow through distributor channels serving high-volume adapter and lighting customers, while integrated circuits move through direct OEM relationships with telecommunications and automotive tier-1 suppliers.
- Discrete Devices:Individual power transistors and diodes packaged for drop-in replacement of silicon MOSFETs in sub-650V applications. Demand concentrates in China for consumer electronics adapters where cost sensitivity drives procurement decisions.
- Integrated Circuits:Monolithic GaN power stages combining gate drivers, protection logic, and power FETs on single die. Expansion concentrates in Germany and South Korea for 5G base station power amplifiers where integration reduces board area.
- Power Amplifiers:RF amplification modules for radar and telecommunications infrastructure.
- Transistors:High-electron-mobility transistors for switching and amplification functions.
Discrete devices dominate installed base. Integrated circuits are where expansion concentrates.
Technology:
Epitaxial growth method selection locks manufacturers into specific substrate supply chains and equipment vendor relationships that persist for decade-long depreciation cycles.
- Metal Organic Chemical Vapor Deposition:The dominant manufacturing platform using trimethylgallium and ammonia precursors to deposit crystalline GaN on silicon or silicon carbide wafers. Japanese and Taiwanese equipment suppliers anchor the installed tool base serving mass-market power electronics.
- Hydride Vapor Phase Epitaxy:Chloride-transport growth method achieving thicker GaN layers at higher deposition rates. Adoption concentrates in France and Germany for 1200V automotive inverter qualification where layer thickness determines breakdown voltage.
- Molecular Beam Epitaxy:Ultra-high-vacuum growth technique for precision heterostructure devices.
- Ammonothermal:High-pressure solution growth for native GaN substrates with lowest defect density.
Metal organic chemical vapor deposition commands production volume. Hydride vapor phase epitaxy is climbing the fastest for power applications.
Application:
Application segmentation maps directly to frequency and power handling requirements that dictate substrate choice and package thermal design.
- Wireless Communication:Base station power amplifiers and small cell transmitters operating at sub-6GHz and mmWave frequencies. Deployment concentrates in China and the United States for 5G macro infrastructure where massive MIMO array density drives transistor count.
- Radar Systems:Phased array transmit/receive modules for military and weather radar. Procurement concentrates in the United States and Israel for defense electronics where GaN-on-SiC reliability under thermal cycling outperforms gallium arsenide legacy.
- RF and Microwave Transmitters:Broadcast and satellite communication power stages.
- Optical Sensors:UV photodetectors and imaging arrays for sterilization and flame detection.
- Aviation Electronics:Radar altimeters and communication systems for commercial and military aircraft.
Wireless communication anchors revenue scale. Radar systems are gaining share fastest through defense procurement acceleration.
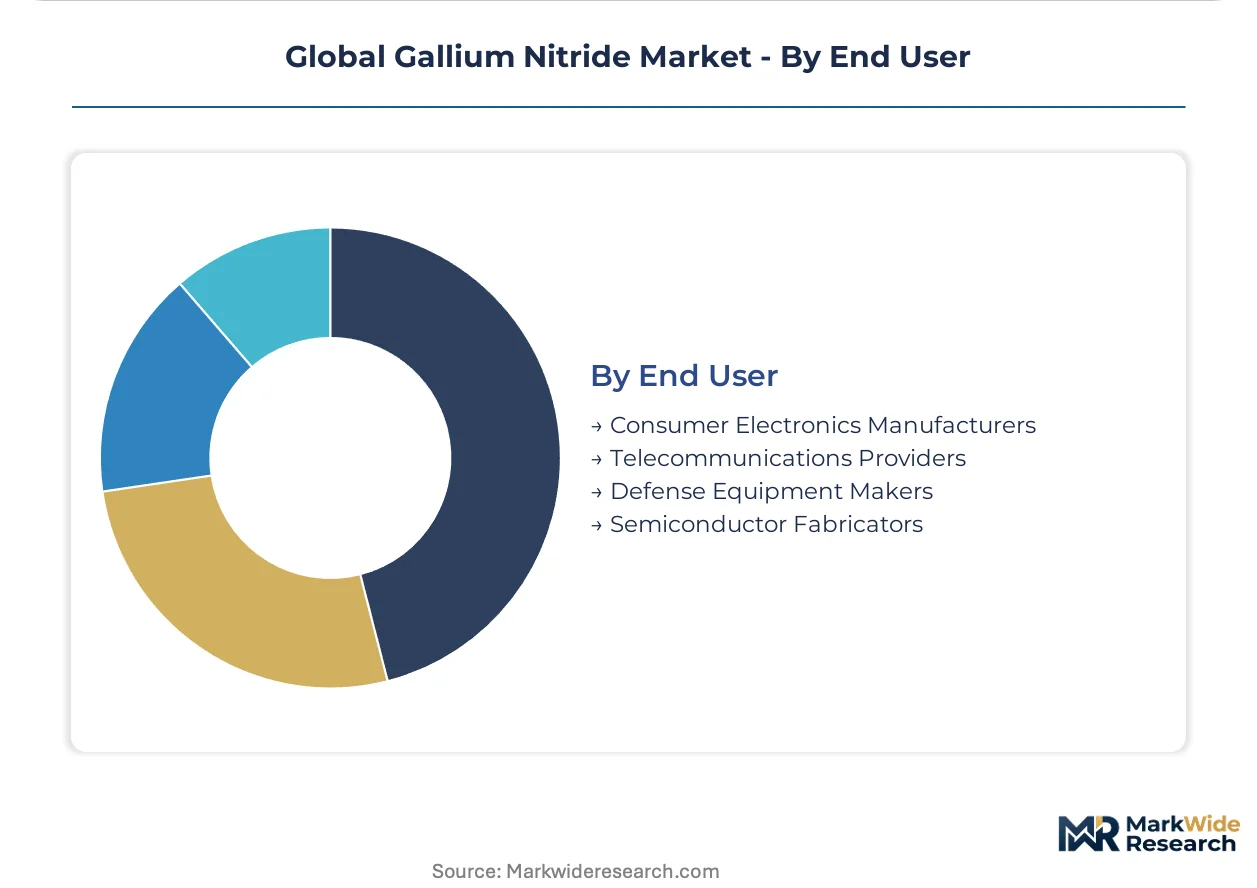
End User:
End user category determines qualification burden, with automotive and defense customers imposing multi-year testing protocols that consumer electronics bypass.
- Consumer Electronics Manufacturers:Adapter, charger, and lighting OEMs sourcing GaN transistors through Asian distributors. Procurement concentrates in Shenzhen and Dongguan manufacturing clusters where 65W-140W fast charger designs are standardizing on GaN-on-silicon platforms.
- Telecommunications Providers:Network equipment vendors and mobile operators specifying RF power devices. Demand concentrates in Ericsson's Swedish engineering centers and Huawei's Shenzhen procurement for macro base station massive MIMO deployments.
- Defense Equipment Makers:Prime contractors and subsystem suppliers for military radar and electronic warfare.
- Semiconductor Fabricators:Foundries and IDMs purchasing epitaxial wafers and process equipment.
Consumer electronics manufacturers represent the highest volume segment. Telecommunications providers are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes gallium nitride primarily for power electronics in consumer adapters and EV inverters, while the United States deploys the technology disproportionately in defense radar and hyperscale data centers. Germany concentrates on industrial motor drives and automotive qualification. This consumption-mix differential shapes regional supply chain investments and regulatory compliance priorities.
United States
Hyperscale data center operators in Northern Virginia and Oregon specify 80 PLUS Titanium efficiency standards that exclude silicon-based designs. The EPA imposes power supply benchmarks on cloud facilities that GaN satisfies more readily than legacy alternatives. Wolfspeed anchors substrate production through its North Carolina fabrication complex serving defense and telecommunications customers.
China
Domestic semiconductor fabricators scale GaN capacity for 5G base stations and electric vehicle inverters at unprecedented velocity. The Ministry of Industry and Information Technology channels state investment through national semiconductor development frameworks. Shenzhen and Dongguan manufacturing clusters standardize 65W-140W fast charger designs on GaN-on-silicon platforms for export markets.
Germany
Industrial motor drive manufacturers face EU Green Deal mandates for efficiency upgrades in pumps and compressors. The F-Gas Regulation tightens phase-down schedules for fluorinated gases used in semiconductor processing, forcing qualification of alternative chemistries. Bavarian fabs face immediate compliance deadlines as national environmental agencies enforce strict emissions thresholds.
Japan
Metal organic chemical vapor deposition equipment suppliers anchor the installed tool base serving mass-market power electronics across Asia. METI coordinates supply chain resilience initiatives for wide-bandgap semiconductor materials. Tokyo and Osaka engineering centers concentrate RF device design for 5G infrastructure and satellite communications.
South Korea
Telecommunications equipment vendors integrate monolithic GaN power stages for 5G base station deployments across domestic networks. National industrial policy prioritizes compound semiconductor fabrication capacity for export competitiveness. Seoul Capital Area foundries specialize in high-frequency transistor architectures for consumer electronics and telecommunications customers.
Global Gallium Nitride Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in substrate production and epitaxial wafer supply. The market structure rewards backward integration into silicon carbide materials and captive metal organic chemical vapor deposition capacity. Three archetypes dominate: diversified semiconductor conglomerates with power electronics divisions, pure-play GaN device specialists, and vertically integrated substrate-to-device manufacturers. Competitive dynamics center on capacity expansion timelines and strategic partnerships with automotive tier-1 suppliers.
Among North American fabricators, Wolfspeed, Inc. and Navitas Semiconductor occupy positions at opposite ends of the integration spectrum. Infineon Technologies AG represents the diversified conglomerate archetype with manufacturing footprint spanning discrete devices and power integrated circuits. GaN Systems Inc. exemplifies the pure-play specialist model focused on high-frequency transistor architectures.
| Leading Market Players |
|---|
| Navitas Semiconductor |
| Qorvo, Inc. |
| Wolfspeed, Inc. |
| Infineon Technologies AG |
| Sumitomo Electric Industries, Ltd. |
| Efficient Power Conversion Corporation |
| GaN Systems Inc. |
| Transphorm Inc. |
| NXP Semiconductors N.V. |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down schedules gate both chemical qualification for epitaxial growth and tiered pricing for GaN-on-SiC versus GaN-on-silicon platforms simultaneously. Buyers face extended certification timelines that compress procurement windows while manufacturers absorb reformulation costs that stratify end-product positioning.
Pricing Analysis
Long-term offtake contracts dominate substrate procurement between device manufacturers and silicon carbide wafer suppliers, insulating buyers from spot price volatility in furnace-limited production. Pricing stratifies across automotive-grade AEC-Q101 certified tiers, industrial-standard tiers, and consumer electronics economy tiers, with certification investment creating margin separation. Cost compression in consumer adapter segments is intensifying because Chinese fabs are scaling GaN-on-silicon capacity for export markets. Telecommunications providers exhibit lowest price sensitivity due to 5G deployment timelines, while consumer electronics manufacturers concentrate procurement authority in Shenzhen clusters where 65W adapter designs compete on fractional cost differentials.
Supply Chain Analysis
Silicon carbide substrate supply concentrates in the United States, Germany, and Japan, creating single-source vulnerability for GaN-on-SiC device manufacturers dependent on Wolfspeed and SiCrystal output. Metal organic chemical vapor deposition equipment draws from Japanese and Taiwanese tool suppliers, while trimethylgallium precursor sourcing rests on Chinese and German chemical processors. Tariff exposure runs through semiconductor manufacturing equipment imports into China under MIIT localization mandates. Distribution runs through direct OEM relationships for integrated circuits and Asian distributor networks for discrete devices serving adapter manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. AEC-Q101 automotive certification creates switching costs that lock tier-1 suppliers into qualified device relationships across multi-year platform lifecycles.
For Market Incumbents: Fortify backward integration into silicon carbide substrate production to defend margin position against GaN-on-silicon substitution in sub-650V applications. Expand captive metal organic chemical vapor deposition capacity in North Carolina or Bavaria to secure equipment allocation ahead of eighteen-month technician hiring cycles. Prioritize automotive qualification investment as the priority lever, as OEM powertrain platform decisions made today will lock in device suppliers through 2030 model generations. For New Entrants and Emerging Players: Lead with GaN-on-silicon automotive inverter designs for 400V electric vehicle architectures where silicon carbide remains over-specified and cost-disadvantaged. Target India's Production Linked Incentive scheme for semiconductor manufacturing, where tariff advantages and capital subsidies create white-space entry for solar inverter and domestic EV supply. Pursue direct qualification with Korean telecommunications equipment vendors as the go-to-market angle, bypassing saturated consumer adapter channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydride vapor phase epitaxy capacity for 1200V automotive applications, favoring late-stage private equity over venture deployment. Acquire pure-play GaN device specialists with captive epitaxial wafer supply and existing AEC-Q101 qualification timelines rather than de novo fabrication investments. Monitor compound semiconductor process engineering hiring velocity at Japanese equipment suppliers as the inflection indicator for supply chain expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Wolfspeed's North Carolina complex demonstrates how captive wafer supply secures allocation priority during furnace capacity constraints. |
| AEC-Q101 Automotive Certification | Qualification timelines extending thirty-six months create switching costs that lock tier-1 suppliers into validated device relationships. |
| GaN-on-Silicon Platform Development | Leveraging 300mm CMOS infrastructure collapses cost gaps against superjunction MOSFETs in server power supply applications. |
| India PLI Scheme Manufacturing Entry | Domestic solar inverter and EV market growth under India's semiconductor incentive program opens tariff-protected production capacity. |
| Alternative Chemistry Qualification | F-Gas Regulation compliance requires redesign of MOCVD process chambers to maintain throughput under constrained fluorinated gas availability. |
Research Methodology
The analysis maps discrete devices, integrated circuits, and epitaxial wafer supply tiers, each validated through procurement directors at telecommunications equipment vendors, power electronics design engineers at automotive tier-1 suppliers, and fab operations managers at compound semiconductor foundries. Primary interview findings triangulated against secondary sources including EPA efficiency benchmark filings, MIIT semiconductor framework disclosures, EU F-Gas Regulation implementation guidance, and SEC 10-K equipment capex disclosures from publicly traded substrate manufacturers. Bottom-up unit economics for GaN transistor production combined with top-down infrastructure deployment tracking across 5G base station and data center power supply installations.
Consistency checks validated volume and value outputs against hyperscaler power supply procurement disclosures and national electric vehicle inverter production forecasts. Segmentation modeling incorporated product architecture, epitaxial growth technology, application frequency requirements, and end-user qualification burden across the projection horizon. CAGRs derived from equipment installation timelines, automotive platform lifecycle commitments, and regulatory phase-in schedules rather than extrapolation. Forecast inputs included metal organic chemical vapor deposition tool delivery backlogs and silicon carbide wafer pricing indices from Japanese equipment suppliers.
Forecasts assume regulatory continuity in EPA data center efficiency mandates, EU F-Gas phase-down schedules, and China MIIT semiconductor localization frameworks; material policy shifts would require re-modeling qualification timelines and procurement criteria. Supply chain disruption risks from compound semiconductor engineering talent scarcity or silicon carbide furnace capacity constraints could compress expansion timelines. Practitioners should keep alternative scenarios live as automotive electrification adoption curves and telecommunications infrastructure deployment rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Graphene Oxide (GO) Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Gallium Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Indium Market