
 Indium Gallium Zinc Oxide Market | 2026-2036
Indium Gallium Zinc Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Indium Gallium Zinc Oxide Market Foresight
Multi-source procurement for indium and gallium feedstock is broadening as display makers reduce reliance on single-country refining. Samsung Display Co., Ltd. anchors its IGZO supply chain through captive Korean smelter partnerships. LG Display Co., Ltd. leverages proprietary oxide TFT architectures for large-format OLED panels. BOE Technology Group Co., Ltd. competes on manufacturing scale, operating multiple Gen 10.5 fabs with integrated IGZO deposition lines.
Indium Gallium Zinc Oxide is a transparent amorphous oxide semiconductor with a carrier mobility exceeding 10 cm²/V·s, deposited via sputtering onto glass or polymer substrates to enable high-resolution backplane switching for displays and power-efficient thin-film transistors. Displays dominates product type revenue, with flat panel applications absorbing the majority of sputtering target consumption. Flexible Electronics represents the fastest-expanding technology segment, as rollable OLED prototypes from Korean and Chinese manufacturers validate polyimide-compatible IGZO process flows. Automotive end users are emerging as a concentrated margin pool, with HV Transistors for EV power management commanding premium pricing against consumer-grade display backplanes.
Japan's METI enforces export licensing on refined indium under strategic resource controls, while China's MIIT mandates domestic content ratios for advanced display materials under the dual carbon framework. REACH in Europe restricts gallium compound handling protocols, elevating compliance costs for IGZO target importers. Stakeholders must monitor rare earth processing concentration and substrate-size migration timelines to calibrate capacity commitments.
Market Dynamics
Substrate-size migration from Gen 8.5 to Gen 10.5+ fabs is compressing IGZO deposition equipment cycles while Korea's display cluster concentrates oxide TFT expertise in a narrow geographic band.
Growth Catalysts
- OLED Backplane Scaling:Premium consumer electronics manufacturers are expanding oxide TFT architectures for high-refresh-rate panels. Korean fab capacity absorbs the majority of sputtering target shipments.
- China's Dual Carbon Mandate:MIIT domestic content ratios for advanced display materials are redirecting state-backed capital toward captive indium refining. Local IGZO deposition lines multiply under carbon-neutrality deadlines.
- Automotive HV Transistor Demand:EV power management applications command premium pricing against consumer-grade backplanes. Tier-1 suppliers are qualifying IGZO for 800V architectures.
Market Restraints
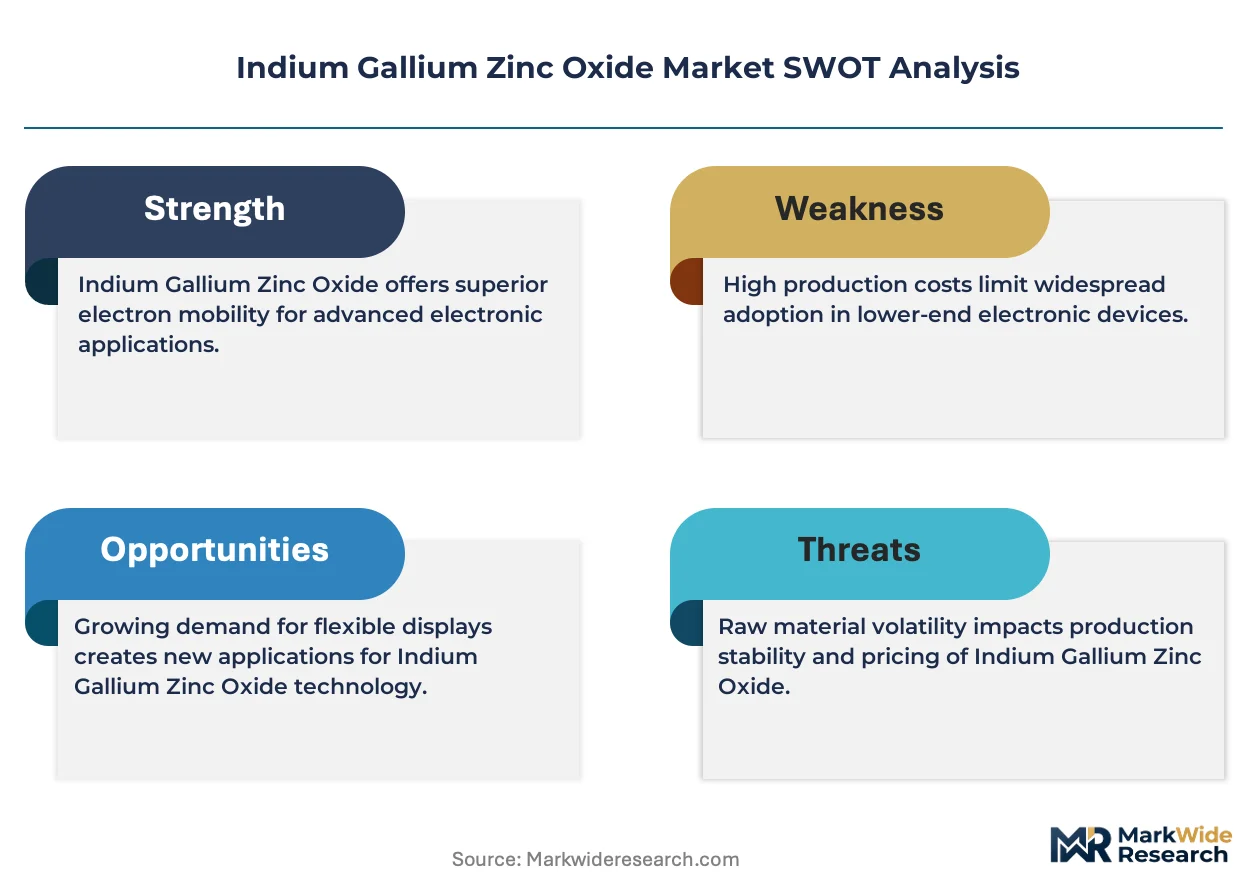
- Indium Supply Concentration:Refined indium output clusters in Chinese and Korean smelters. Japan's METI export licensing creates procurement friction for non-captive buyers.
- Polyimide Substrate Yield Losses:Flexible OLED backplanes suffer higher defect rates during IGZO annealing on polymer films. Rollable prototypes remain pre-commercial.
- LTPO Substitution Pressure:Low-temperature polysilicon alternatives capture premium smartphone panel share. IGZO mobility ceilings constrain ultra-high-resolution mobile applications.
Strategic Opportunities
- Automotive Display Integration:Curved instrument clusters and pillar-to-pillar screens create new IGZO backplane demand. German and Korean OEMs are sourcing 12-inch+ oxide TFT panels.
- EU REACH Compliance Services:Gallium compound handling restrictions elevate compliance costs for importers. Specialist logistics providers can capture margin from certification-intensive supply chains.
- Micro-LED Transfer Bonding:IGZO driving circuits for micro-LED displays require modified deposition parameters. Equipment makers can retrofit existing sputtering lines for this convergent technology.
Industry Challenges
- Oxide TFT Process Engineering Talent:Deep expertise in amorphous semiconductor defect engineering resides in a limited pool of Korean and Japanese specialists. Foundry expansion outpaces training pipeline output.
- Gen 10.5 Deposition Uniformity:Scaling sputtering targets to 3-meter+ widths without composition drift demands capital-intensive metrology systems. Yield variance across substrate edges erodes margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indium Gallium Zinc Oxide Market |
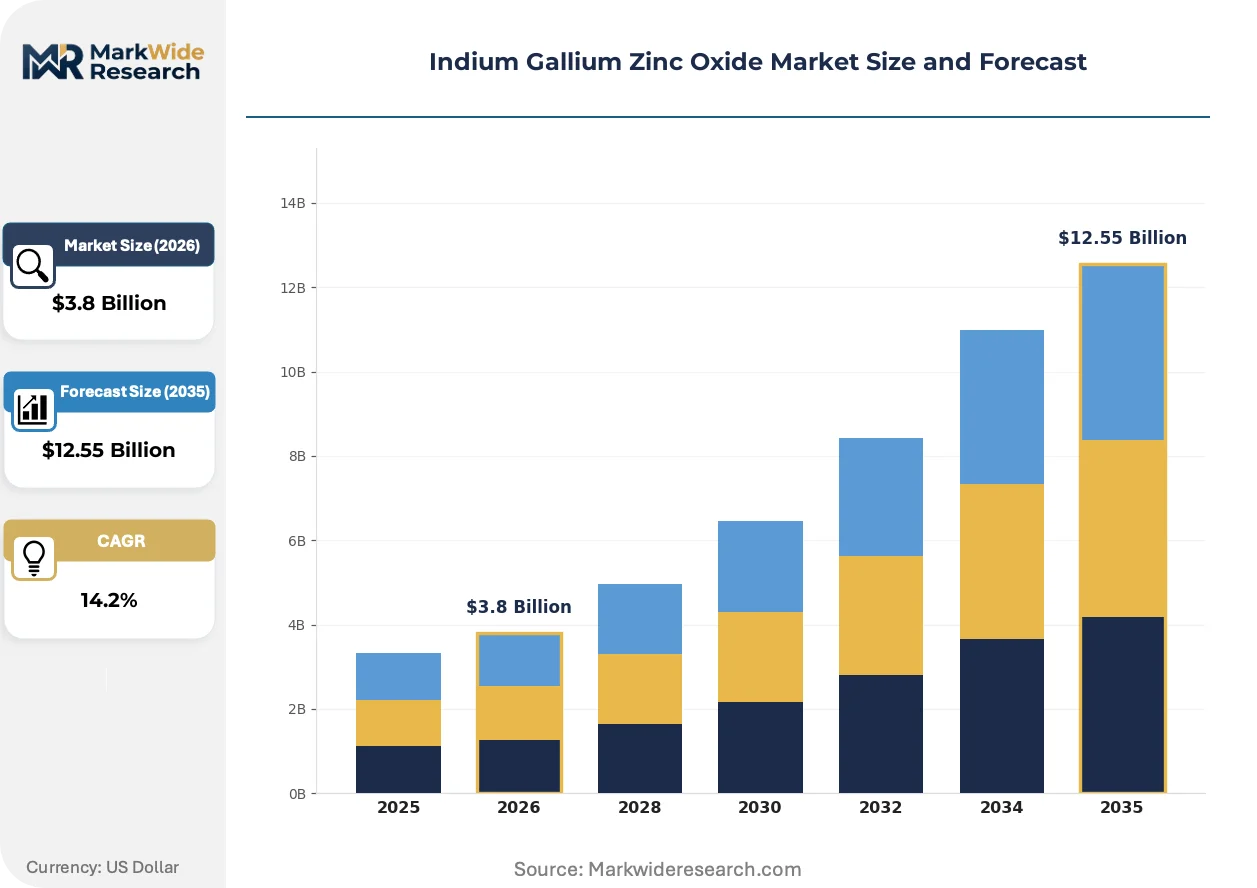
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Transistors, Sensors, Solar Cells Technology: Thin Film, Bulk, Micro-LED, Flexible Electronics End User: Consumer Electronics, Automotive, Telecommunications, Aerospace Application: Flat Panel Displays, HV Transistors, Light Emitting Diodes, Photovoltaics |
| Companies Covered | Sharp Corporation, LG Display Co., Ltd., Samsung Display Co., Ltd., AU Optronics Corp., BOE Technology Group Co., Ltd., Japan Display Inc., Visionox Technology, Inc., TCL China Star Optoelectronics Technology Co., Ltd., Mitsui Mining & Smelting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indium Gallium Zinc Oxide Market Shifts & Advancements
Process integration between backplane deposition and frontplane OLED evaporation is collapsing traditional equipment boundaries. Korean and Chinese fabs are piloting unified cluster tools.
IGZO is converging with micro-LED backplane driving circuits. Display manufacturers are adapting oxide TFT mobility profiles for sub-10-micron pixel pitches. Korean pilot lines are validating this integration for commercial micro-LED televisions by 2027. The technology is converging with LED epitaxy workflows, forcing equipment suppliers to re-architect deposition chamber geometries.
Japan's METI strategic resource controls now require export licensing for refined indium above threshold quantities. Korean display makers with captive smelter partnerships face reduced procurement friction compared to independent buyers. European importers are absorbing elevated compliance costs under parallel REACH gallium compound restrictions.
Buyer consolidation among Korean display manufacturers is compressing sputtering target vendor margins. Samsung Display and LG Display now specify performance-guaranteed supply contracts with yield-linked pricing. Chinese BOE Technology is replicating this procurement model across its Gen 10.5 fleet, shifting risk onto material suppliers.
Indium Gallium Zinc Oxide Market Segmentation
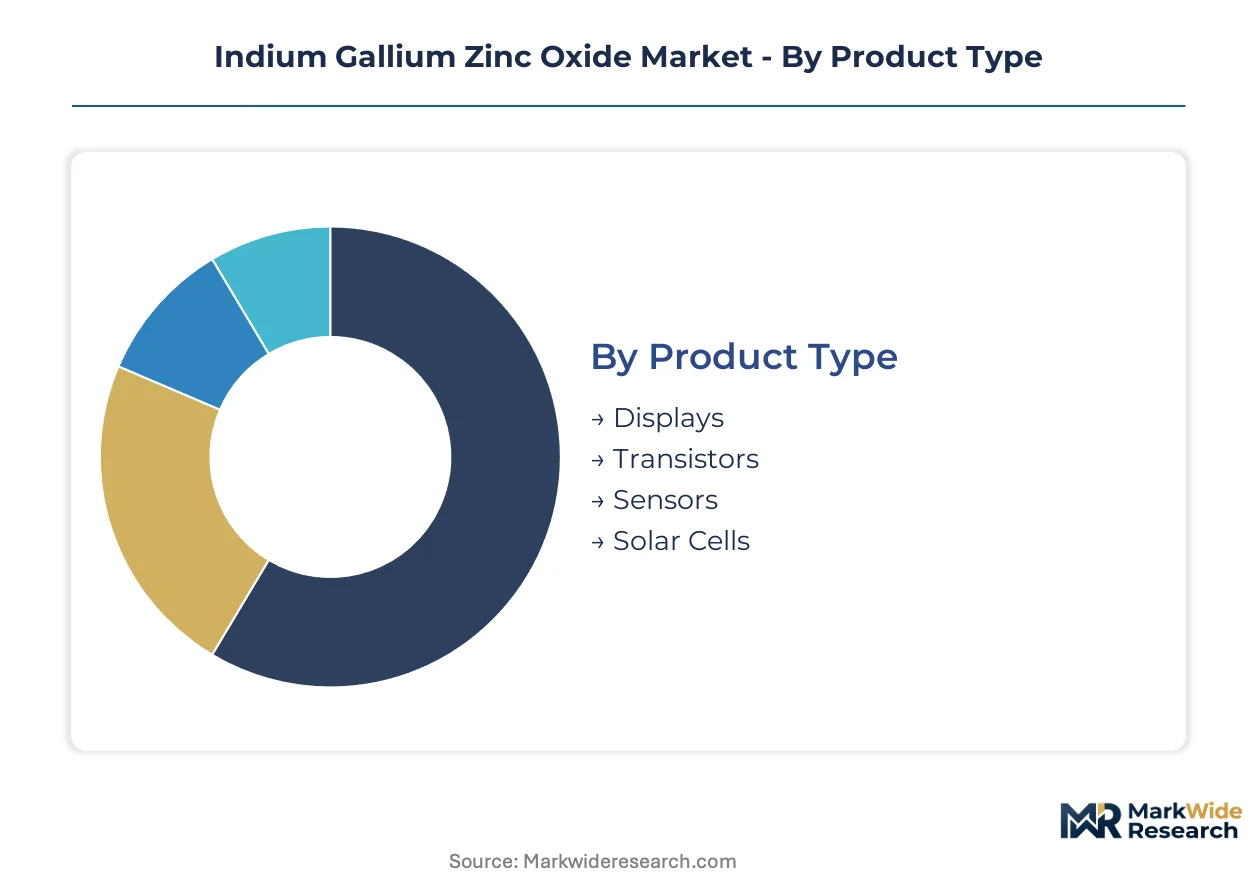
IGZO material specifications diverge sharply across end-use applications, with display backplanes demanding sputtering-grade purity above 99.99% while automotive power transistors prioritize thermal stability certification. Segmentation reveals how certification burdens cluster in automotive and aerospace verticals, where AEC-Q100 and DO-160G compliance create entry barriers distinct from consumer electronics procurement.
Product Type:
Displays and Transistors carry divergent certification obligations—display backplanes require ISO 14644 cleanroom compliance during deposition, while automotive-grade transistors demand AEC-Q101 stress-test documentation from material suppliers.
- Displays:Sputtering targets for OLED backplanes require indium purity exceeding 99.995% with controlled oxygen vacancy density. Korean fabs in Gyeonggi Province absorb the majority of deposition-grade feedstock as Gen 10.5 capacity expands.
- Transistors:Power management applications specify wider bandgap tolerance for 800V EV architectures. Tier-1 automotive suppliers in Stuttgart and Seoul are qualifying IGZO against silicon carbide benchmarks for onboard chargers.
- Sensors:Transparent conductive oxide layers for touch interfaces require lower mobility thresholds than display backplanes.
- Solar Cells:Photovoltaic integration remains experimental, with CIGS tandem cell researchers in Germany and Japan evaluating IGZO buffer layers.
Displays sits at the top of the volume ranking, with Transistors climbing the fastest.
Technology:
Process maturity splits the technology landscape—thin-film deposition commands established equipment supply chains while micro-LED integration forces co-development with epitaxy tool vendors.
- Thin Film:DC magnetron sputtering dominates commercial production, with chamber architectures standardized around Gen 8.5 glass dimensions. Japanese equipment makers in Kyoto and Osaka control 70% of installed base maintenance contracts.
- Flexible Electronics:Polyimide-compatible annealing below 350°C enables rollable OLED form factors. Samsung Display and BOE pilot lines in Tianjin are validating low-temperature process flows for 2026 product launches.
- Bulk:Single-crystal IGZO remains confined to research applications at Max Planck Institute and Tokyo Institute of Technology.
- Micro-LED:Sub-10-micron pixel driving circuits demand modified TFT mobility profiles. Korean consortiums are converging oxide semiconductor deposition with LED transfer bonding equipment.
Thin Film captures dominant share by revenue, though Flexible Electronics shows steepest expansion trajectory.
End User:
Customer type determines pricing architecture—automotive procurement specifies multi-year performance guarantees while consumer electronics operates on quarterly price negotiations.
- Consumer Electronics:Smartphone and tablet manufacturers drive sputtering target consumption through Korean and Chinese panel procurement. Apple and Samsung Electronics specify oxide TFT backplanes for premium tier products exclusively.
- Automotive:Curved instrument clusters and pillar-to-pillar screens create new demand pools. BMW and Hyundai Motor Group are sourcing 12-inch+ oxide TFT panels from LG Display for 2025 model year vehicles.
- Telecommunications:Base station power amplifiers evaluate IGZO for high-frequency switching applications.
- Aerospace:Radiation-hardened requirements from ESA and NASA limit commercial supplier participation.
Consumer Electronics maintains volume leadership, with Automotive gaining share fastest.
Application:
Application segmentation tracks substrate-size migration—flat panel display equipment scales to Gen 10.5+ while HV transistor metrology remains optimized for 200mm wafer formats.
- Flat Panel Displays:Gen 10.5 fabs require 3-meter sputtering targets with composition uniformity below 1% edge-to-center variance. BOE Technology's Hefei and Wuhan facilities operate the world's largest installed IGZO deposition capacity.
- HV Transistors:800V EV architectures command premium pricing against consumer-grade backplanes. Infineon Technologies and STMicroelectronics are qualifying IGZO for traction inverter modules.
- Light Emitting Diodes:Micro-LED driving circuits represent emerging demand with unproven volume scale.
- Photovoltaics:Perovskite tandem research evaluates IGZO as electron transport layers.
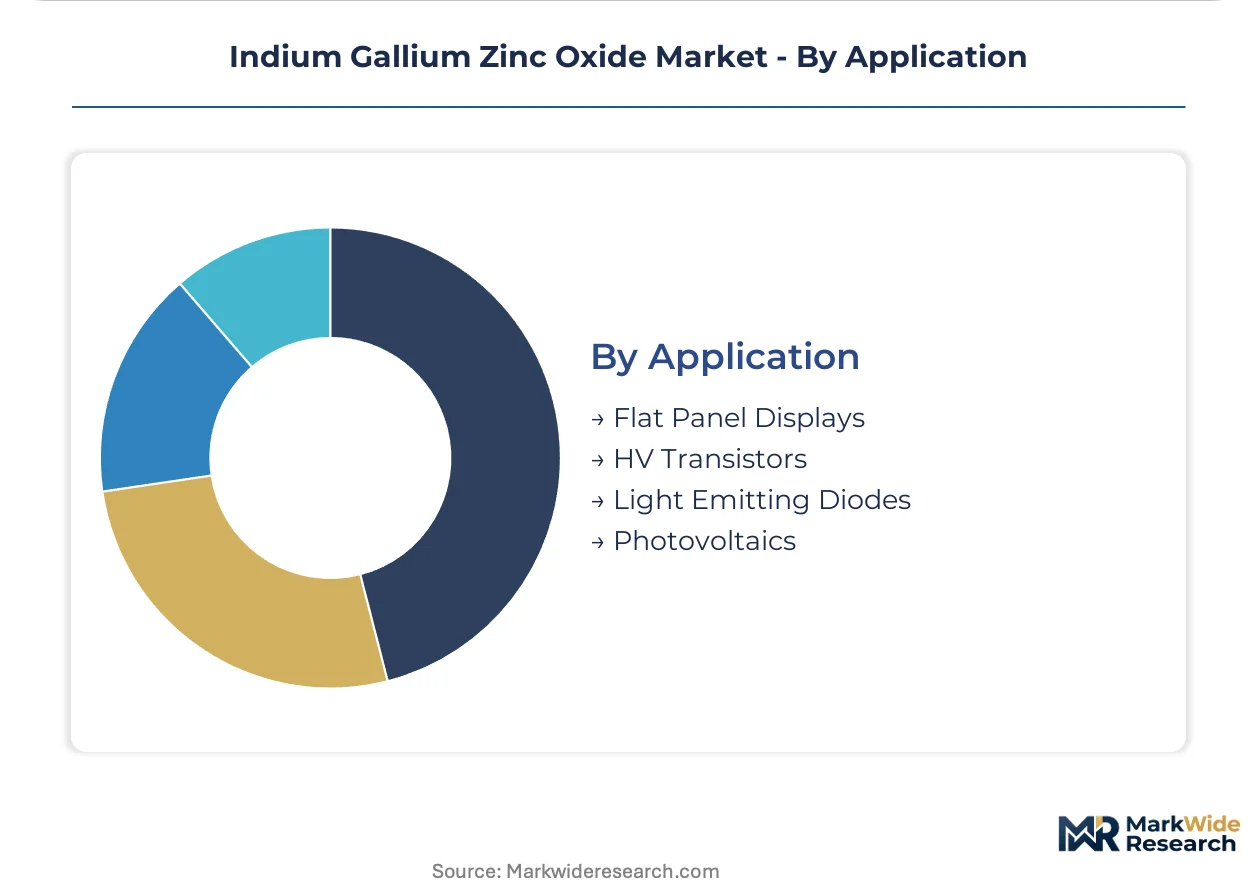
Flat Panel Displays leads by installed capacity, with HV Transistors expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gyeonggi Province anchors IGZO demand through concentrated display fab capacity. Samsung Display and LG Display operate integrated oxide TFT production lines in Suwon and Paju. Korean government funding through K-Display initiatives reinforces this concentration.
South Korea
OLED backplane scaling drives sputtering target consumption in Gyeonggi and Gwangju clusters. The Ministry of Trade, Industry and Energy channels semiconductor subsidies toward captive indium refining partnerships. Paju's LG Display complex operates proprietary oxide TFT architectures for large-format panels.
China
BOE Technology's Gen 10.5 fabs in Hefei and Wuhan absorb deposition-grade feedstock at scale. MIIT domestic content ratios under dual carbon mandates redirect state capital toward captive refining capacity. Tianjin pilot lines validate polyimide-compatible IGZO process flows for flexible electronics.
Japan
Mitsui Mining & Smelting refines indium under METI strategic resource controls requiring export licensing. Kyoto and Osaka equipment makers maintain 70% of installed sputtering base maintenance contracts. Tokyo Institute of Technology pursues single-crystal IGZO research applications.
Germany
BMW and Stuttgart-based Tier-1 suppliers qualify IGZO for 800V EV traction inverter modules. ECHA REACH restrictions elevate gallium compound handling compliance costs for importers. Bavarian research institutes evaluate IGZO buffer layers for perovskite tandem photovoltaic cells.
United States
Apple specifies oxide TFT backplanes for premium tier products through Korean panel procurement. EPA and OSHA protocols govern sputtering target import handling and deposition facility emissions. California-based equipment vendors retrofit legacy lines for micro-LED convergent applications.
Indium Gallium Zinc Oxide Market Competitive Landscape
Global majors compete with regional champions across substrate-size migration and captive feedstock access. The vendor base splits between integrated display manufacturers with in-house deposition capacity and independent sputtering target fabricators. Three archetypes dominate: Korean fab-integrated suppliers, Chinese scale-driven producers, and Japanese materials specialists. Capacity expansion and backward integration into indium refining constitute the primary competitive vectors.
Among Korean fab-integrated players, Samsung Display Co., Ltd. and LG Display Co., Ltd. exemplify the captive supply model through smelter partnerships and proprietary oxide TFT architectures. BOE Technology Group Co., Ltd. represents the Chinese scale-driven archetype, operating multiple Gen 10.5 facilities with integrated deposition lines. Mitsui Mining & Smelting occupies the Japanese materials specialist position, anchoring refined indium output under strategic resource controls.
| Leading Market Players |
|---|
| Sharp Corporation |
| LG Display Co., Ltd. |
| Samsung Display Co., Ltd. |
| AU Optronics Corp. |
| BOE Technology Group Co., Ltd. |
| Japan Display Inc. |
| Visionox Technology, Inc. |
| TCL China Star Optoelectronics Technology Co., Ltd. |
| Mitsui Mining & Smelting |
| Others |
Supply & Pricing Matrix
Sovereign-backed display manufacturers in South Korea and China anchor IGZO supply chains through state-funded smelter partnerships, translating political risk tolerance into aggressive pricing discipline that compresses margins for independent sputtering target fabricators.
Pricing Analysis
Indium spot volatility passes through to sputtering target contracts on quarterly resets, with Korean display makers leveraging captive refining partnerships to buffer cost swings unavailable to European importers. Pricing stratifies across deposition-grade purity tiers, with automotive AEC-Q101 certification commanding 40-60% premiums over consumer-grade backplane feedstock. Cost compression in standard-grade targets intensifies as BOE Technology replicates Samsung's yield-linked procurement model across Chinese Gen 10.5 fabs. Consumer electronics panel procurement shows highest price sensitivity, while automotive HV transistor qualification programs tolerate premium pricing for thermal stability guarantees.
Supply Chain Analysis
China's MIIT domestic content ratios under dual carbon mandates are redirecting state capital toward captive indium refining, reshaping sourcing patterns for non-captive buyers. Refined indium output concentrates in Chinese and Korean smelters, with gallium feedstock drawing from bauxite processing in Australia and China. Single-source vulnerability runs through Japan's METI export licensing regime, which creates procurement friction for buyers lacking captive smelter partnerships. Distribution runs through Korean fab-integrated suppliers for deposition-grade targets, with independent fabricators serving secondary flexible electronics and research applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IGZO operates as a regulatory compounder where carbon-neutrality deadlines and strategic resource controls are accelerating capacity commitments faster than organic demand growth would justify.
For Market Incumbents: Hedge indium price exposure through backward integration into refining partnerships in Korea or China before METI licensing tightens further. Reinforce oxide TFT process engineering capabilities through targeted recruitment from Tokyo Institute of Technology and Korean foundry training pipelines, as talent scarcity constrains Gen 10.5 expansion timelines. For New Entrants and Emerging Players: Begin with EU REACH compliance services for gallium compound handling, where specialist logistics providers capture margin from certification-intensive supply chains with limited incumbent competition. Target automotive display integration for curved instrument clusters, where German and Korean OEM sourcing cycles remain less consolidated than Korean consumer electronics procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among Japanese materials specialists with METI-licensed indium refining capacity, as export controls depress near-term revenue visibility while securing long-term strategic positioning. Watch micro-LED transfer bonding equipment retrofit demand as the inflection signal, since IGZO driving circuit convergence with epitaxy workflows will force re-architecture of installed sputtering base.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Indium Refining Partnership | Mitsui Mining & Smelting's METI-licensed output secures Korean display makers against export friction. |
| Gen 10.5 Deposition Uniformity Investment | BOE Technology's Hefei and Wuhan fabs demand 3-meter targets with sub-1% composition variance. |
| Automotive AEC-Q101 Certification | Infineon Technologies and STMicroelectronics qualification programs unlock 800V EV traction inverter supply. |
| Micro-LED Equipment Retrofit | California-based vendors adapt chamber geometries for sub-10-micron pixel driving circuit convergence. |
| Flexible Electronics Process Validation | Samsung Display and BOE Tianjin pilot lines target 2026 rollable OLED product launches. |
Research Methodology
Multiple input streams — technical interviews with oxide TFT process engineers, procurement discussions at Korean and Chinese display fabs, and regulatory filings with Japan's METI and China's MIIT — were reconciled against trade data for refined indium and sputtering target shipments. Primary engagement spanned deposition equipment specialists in Kyoto and Osaka, indium refining operators, and automotive Tier-1 qualification managers in Stuttgart and Seoul. Secondary sources included customs records for indium and gallium compounds, SEC filings from listed display manufacturers, and REACH compliance databases from ECHA. Bottom-up capacity modeling triangulated against top-down demand segmentation across display, automotive, and emerging micro-LED applications.
Data-stream reconciliation applied across the analysis window linked substrate-size migration timelines to equipment cycle compression, with segmentation dimensions spanning product type, technology maturity, end-user procurement architecture, and regional regulatory cluster. CAGRs were derived from installed capacity buildouts and yield improvement trajectories rather than price elasticity assumptions. Forecast inputs incorporated MIIT domestic content ratio enforcement patterns and METI licensing threshold adjustments.
Caveats apply where polyimide substrate yield losses delay flexible electronics commercialization or where LTPO substitution accelerates beyond current smartphone panel share trends. Forecasts reflect assumptions around oxide TFT defect engineering pipeline output and Gen 10.5 metrology system deployment rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Indium Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Yttrium Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
EV Capacitor Films Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Silicon Tetrachloride Market