
 Commercial Water Filter Market | 2026-2036
Commercial Water Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Water Filter Market Outlook
NSF/ANSI 53 certification for cyst and lead reduction is redrawing competitive boundaries in the commercial water filter landscape. Pentair PLC leverages its membrane engineering heritage to dominate high-volume reverse osmosis installations for industrial facilities. Culligan International sustains brand loyalty through captive dealer networks and service contracts across North American restaurants and hospitality chains. DuPont Water Solutions anchors its position with proprietary thin-film composite membranes that extend operational life in high-TDS environments.
A commercial water filter is a pressurized vessel assembly containing engineered media—activated carbon block, polymeric membranes, or ultraviolet lamps—designed to reduce particulates, chemical contaminants, and microbial load from municipal or well water supplies serving non-residential buildings. Membrane filtration systems utilizing spiral-wound polyamide elements achieve rejection rates above 99% for dissolved salts, making them indispensable for boiler feedwater and food processing lines. Reverse osmosis and activated carbon systems command the largest installed base, though UV filters are gaining share in hospital and pharmaceutical applications where chemical-free disinfection is mandated. Point-of-entry installations generate higher per-unit revenue but face longer replacement cycles than under-sink point-of-use units in restaurant kitchens.
The EPA Lead and Copper Rule Improvement provisions and NSF/ANSI standards collectively mandate third-party validation for health-claim filtration products sold in the United States. FDA Food Code requirements for foodservice establishments further compel routine filter maintenance and documented water quality monitoring. Stakeholders must monitor emerging state-level PFAS maximum contaminant limits, as these will force premature retirement of carbon-based systems lacking targeted adsorption capacity for short-chain fluorinated compounds.
Market Dynamics
NSF/ANSI 401 certification for emerging contaminant removal is compressing replacement cycles and forcing carbon block manufacturers to reformulate media formulations or exit the commercial segment entirely.
Growth Catalysts
- EPA Lead and Copper Rule Improvement:Revised federal mandates for lead service line replacement are accelerating point-of-entry system installations in schools, childcare facilities, and municipal buildings across the United States.
- Foodservice chain consolidation:Centralized procurement by multi-unit restaurant operators is standardizing filtration specifications and expanding recurring filter cartridge revenue streams.
- PFAS state-level action:Maximum contaminant limits enacted in Michigan, New Jersey, and California are compelling industrial facilities to upgrade from standard carbon to ion exchange or reverse osmosis systems.
Market Restraints
- Polyamide membrane supply concentration:Spiral-wound reverse osmosis element production clusters in East Asia, exposing North American system integrators to shipping volatility and tariff exposure.
- Activated carbon feedstock cost:Coconut shell charcoal prices fluctuate with Sri Lankan and Indonesian agricultural yields, compressing margins for carbon block fabricators.
- Technical limitation in short-chain PFAS:Conventional granular activated carbon demonstrates poor adsorption kinetics for PFAS compounds with carbon chains below six units.
Strategic Opportunities
- German industrial water reuse:The EU Green Deal's water efficiency targets are creating demand for closed-loop filtration systems in automotive paint shops and semiconductor fabs.
- UV-LED convergence:Mercury-free ultraviolet disinfection modules are penetrating pharmaceutical cleanrooms and hospital dialysis water loops where chemical-free validation is mandatory.
- Direct-to-operator e-commerce:Restaurant owners are bypassing dealer networks to purchase NSF-certified replacement cartridges through specialized industrial supply platforms.
Industry Challenges
- NSF/ANSI certification timeline:Third-party validation for new media formulations requires 12-18 months of challenge testing, delaying product launches behind regulatory deadlines.
- Retrofit integration complexity:Legacy plumbing configurations in pre-1990 commercial buildings often lack adequate pressure or space for modern multi-stage filtration skids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Water Filter Market |
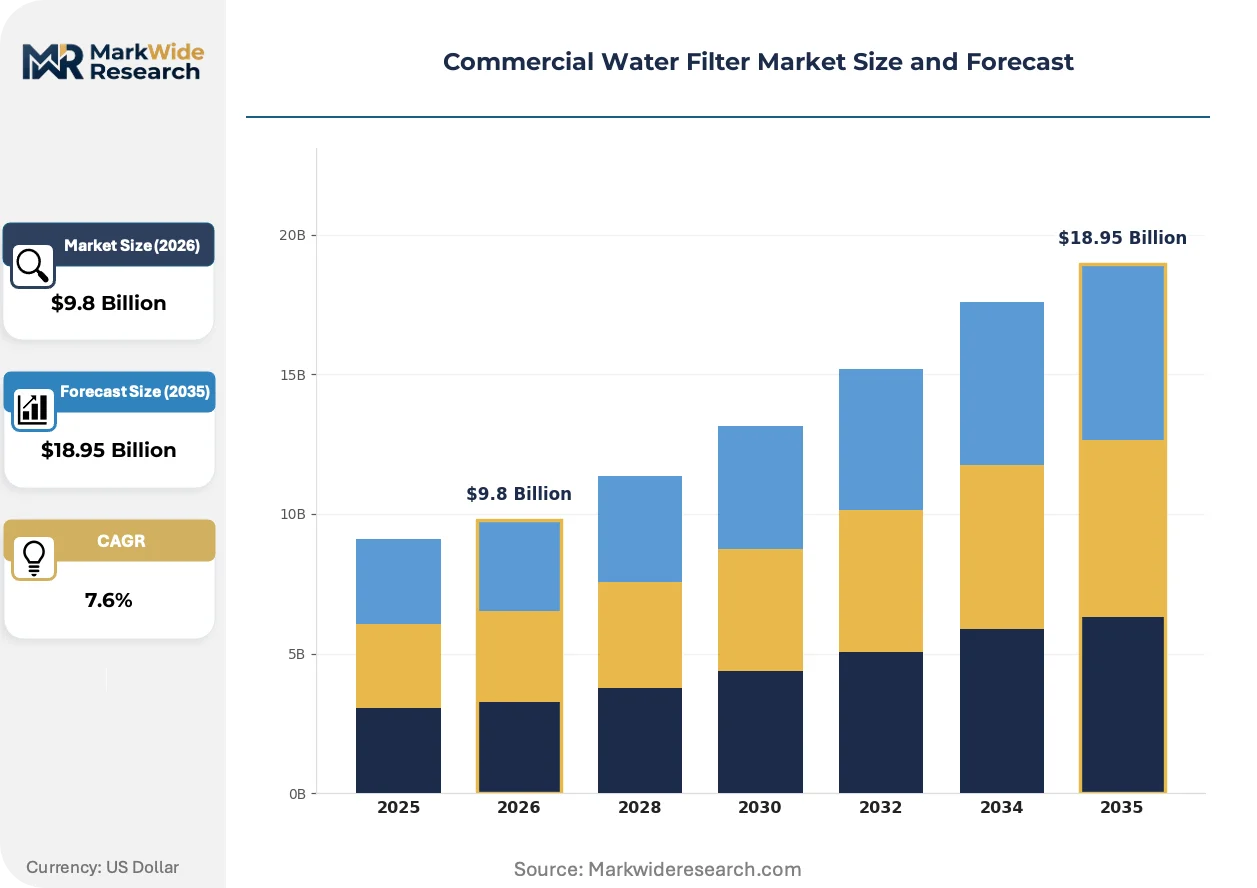
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Activated Carbon, UV Filters, Sediment Filters End User: Restaurants, Offices, Hospitals, Industrial Facilities Installation: Point of Use, Point of Entry, Under-Sink, Whole House Technology: Membrane Filtration, Ion Exchange, Filtration Media, Nanofiltration |
| Companies Covered | Pentair PLC, A. O. Smith Corporation, Culligan International, 3M Company, Evoqua Water Technologies, Eaton Corporation, Parker Hannifin, Toray Industries, DuPont Water Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Water Filter Market Strategic Shifts
Equipment manufacturers are pivoting from hardware-only sales toward bundled service models, embedding sensors and connectivity to capture recurring revenue and lock out aftermarket competitors.
Electrochemical advanced oxidation processes utilizing boron-doped diamond electrodes are displacing chemical biocide dosing in cooling tower and boiler feedwater applications. Data center operators and district energy utilities are adopting these systems to eliminate hazardous chemical handling and discharge permitting. The technology is displacing legacy halogen-based treatment programs and compressing the addressable market for traditional chemical suppliers.
The EPA's forthcoming PFAS National Primary Drinking Water Regulation is mandating detection limits below four parts per trillion for PFOA and PFOS. Municipal water authorities are responding with pilot programs evaluating nanofiltration and reverse osmosis for treatment plant upgrades. Food and beverage processors in affected watersheds are installing redundant filtration to ensure ingredient water compliance regardless of municipal infrastructure status.
Hospital and pharmaceutical buyers are unbundling equipment procurement from service contracts, selecting filtration skids through competitive tender while negotiating maintenance separately with third-party service providers. This pattern is most pronounced in the Northeastern United States where health system consolidation has centralized capital equipment decision-making. Independent service organizations are capturing margin previously retained by original equipment manufacturers through multi-vendor maintenance agreements.
Commercial Water Filter Market Segmentation
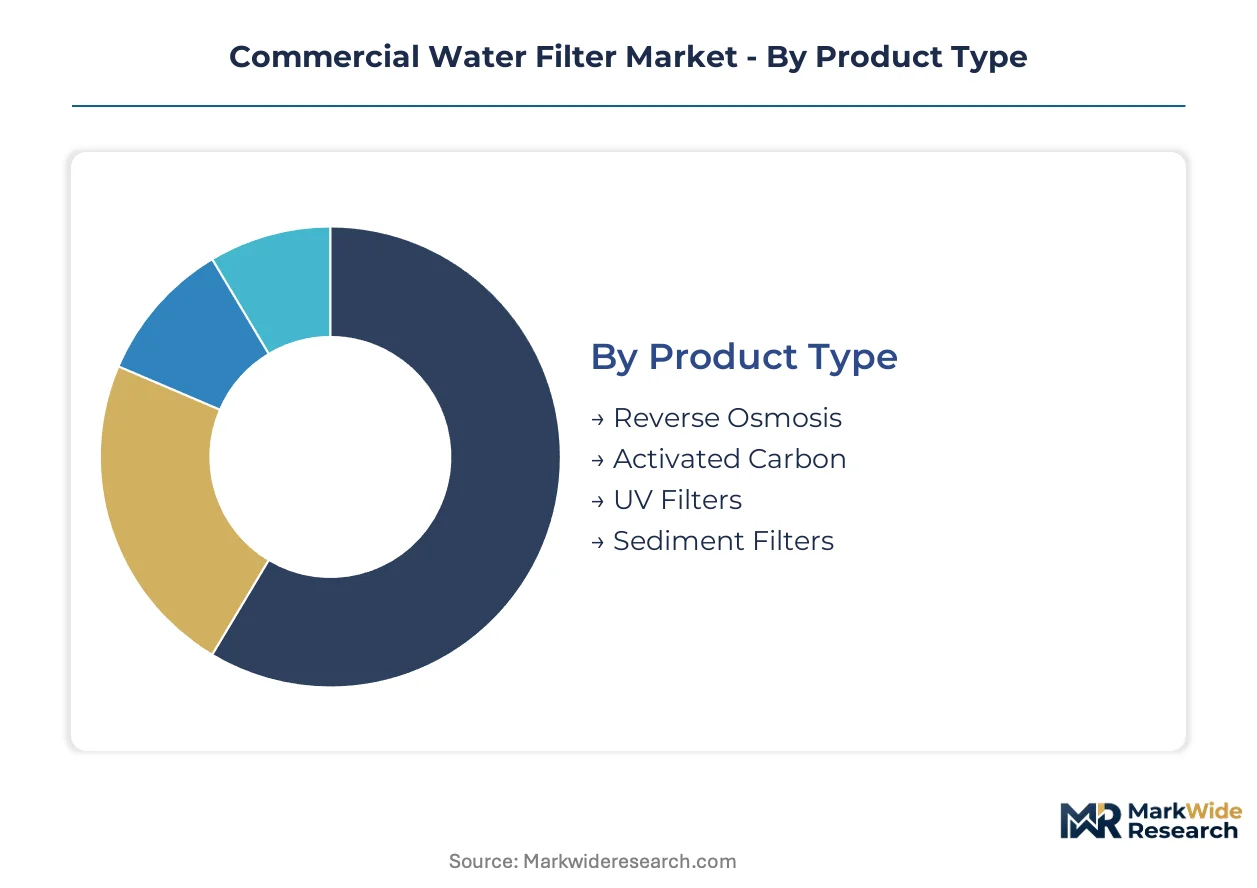
Segmentation in the commercial water filter market reveals how equipment specifications, installation complexity, and regulatory compliance requirements fragment purchasing decisions across end-use verticals. Understanding these divides exposes where manufacturers can capture premium pricing versus where commoditization pressures dominate.
Product Type:
Highest margin pools concentrate in systems requiring specialized media engineering and third-party certification for health claims.
- Reverse Osmosis:Spiral-wound polyamide membrane systems achieve dissolved salt rejection above 99%, serving boiler feedwater and food processing lines where mineral control is critical. Demand clusters in semiconductor fabrication facilities and bottled water plants across Michigan and California responding to state-level PFAS limits.
- Activated Carbon:Coconut shell charcoal block assemblies adsorb chlorine, volatile organic compounds, and certain PFAS variants, though short-chain fluorinated compounds exhibit poor kinetics. Restaurant chains in the United States specify NSF/ANSI 53-certified blocks for cyst and lead reduction, compressing replacement cycles to six-month intervals.
- UV Filters:Low-pressure mercury or UV-LED lamps deliver chemical-free disinfection for pharmaceutical cleanrooms and hospital dialysis loops.
- Sediment Filters:Polypropylene depth cartridges protect downstream membrane elements from particulate fouling in agricultural and industrial pre-treatment stages.
The dominant share belongs to Reverse Osmosis, while UV Filters are gaining share fastest as mercury-free LED modules penetrate regulated healthcare environments.
End User:
Volume concentration and procurement sophistication diverge sharply between fragmented small operators and centralized multi-unit chains.
- Restaurants:Foodservice establishments face FDA Food Code mandates for documented water quality monitoring and routine filter maintenance. Multi-unit operators leverage centralized procurement to standardize specifications, expanding recurring cartridge revenue for approved vendors.
- Hospitals:Healthcare systems in the Northeastern United States unbundle equipment procurement from service contracts, selecting filtration skids through competitive tender while negotiating maintenance separately with third-party providers.
- Industrial Facilities:Automotive paint shops and semiconductor fabs under EU Green Deal water efficiency targets drive demand for closed-loop filtration systems.
- Offices:Commercial buildings prioritize point-of-use installations for tenant amenity water dispensers with lower per-unit revenue but shorter replacement cycles.
Restaurants command the largest installed base by unit count, though Hospitals deliver the steepest expansion trajectory as health system consolidation centralizes capital equipment decision-making.
Installation:
Revenue recognition timing and customer lifetime value split between high upfront point-of-entry systems and recurring point-of-use cartridge replacement.
- Point of Entry:Whole-building pressurized vessels treating municipal or well water at building entry generate higher per-unit revenue but face 5-7 year replacement cycles. Schools and childcare facilities across the United States accelerate installations under EPA Lead and Copper Rule Improvement provisions.
- Point of Use:Under-sink and countertop units in restaurant kitchens and office breakrooms require quarterly to annual cartridge replacement, producing predictable recurring revenue streams.
- Under-Sink:Compact multi-stage assemblies fit legacy plumbing configurations where space constraints preclude larger skids.
- Whole House:Integrated treatment trains combine sediment, carbon, and UV stages for small commercial buildings with private well supplies.
Point of Entry captures the highest average transaction value, while Point of Use is expanding most quickly through direct-to-operator e-commerce channels bypassing traditional dealer networks.
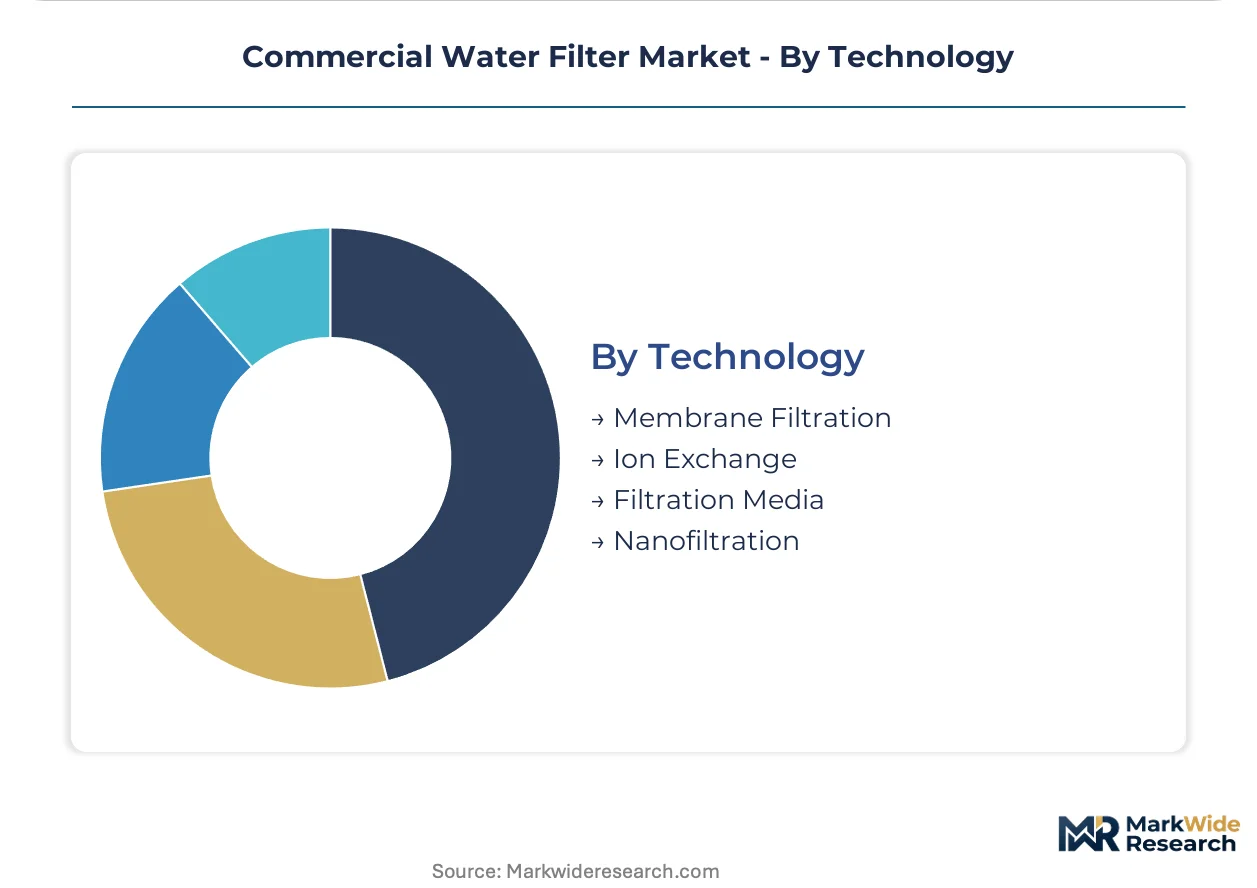
Technology:
Intellectual property concentration and barrier to entry vary from commoditized media to proprietary membrane chemistry.
- Membrane Filtration:Thin-film composite polyamide elements from concentrated East Asian production clusters expose North American integrators to shipping volatility and tariff exposure.
- Nanofiltration:Tighter pore structure than ultrafiltration enables divalent ion and small organic molecule rejection without full desalination energy costs. Municipal water authorities pilot these systems for PFAS treatment plant upgrades ahead of federal detection limits.
- Ion Exchange:Regenerable resin systems target perchlorate, nitrate, and short-chain PFAS where carbon adsorption fails.
- Filtration Media:Granular activated carbon, sand, and multimedia beds remain lowest-cost options for non-potable industrial process water.
Membrane Filtration retains the largest installed capacity, though Nanofiltration is climbing the fastest as utilities evaluate intermediate-rejection alternatives to full reverse osmosis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Lead and Copper Rule revisions and NSF/ANSI certification mandates are accelerating equipment replacement cycles across mature markets. State-level PFAS limits in industrialized regions are forcing upgrades from carbon-based systems to membrane technologies.
United States
Schools and childcare facilities accelerate point-of-entry installations under EPA Lead and Copper Rule Improvement provisions. FDA Food Code requirements compel documented water quality monitoring across foodservice chains. Michigan and California industrial clusters pilot nanofiltration for PFAS treatment ahead of federal detection limits.
Germany
EU Green Deal water efficiency targets create demand for closed-loop filtration in automotive paint shops and semiconductor fabrication. REACH compliance pressures manufacturers toward chemical-free disinvalidation methods. Bavarian industrial zones adopt electrochemical advanced oxidation for cooling tower applications.
China
Dual carbon goals and tightening discharge standards drive membrane filtration adoption in power generation and electronics manufacturing. MIIT industrial water reuse mandates compress payback periods for high-recovery reverse osmosis systems. Yangtze River Delta semiconductor fabs upgrade ultrapure water infrastructure.
Japan
METI energy efficiency standards favor low-pressure membrane systems in commercial building retrofits. Pharmaceutical cleanrooms mandate mercury-free UV-LED disinfection modules. Kansai region hospital networks unbundle equipment procurement from service contracts through competitive tender processes.
India
BIS drinking water quality standards expand certification requirements for commercial filtration products. Food processing hubs in Maharashtra and Gujarat install redundant treatment trains for ingredient water compliance. Central Pollution Control Board effluent norms drive adoption in textile and leather clusters.
Commercial Water Filter Market Competitive Environment
Listed leaders compete with private specialists across certification depth and service network density. The vendor base stratifies into three tiers: integrated water technology conglomerates, captive dealer network operators, and regional membrane fabricators. Two dominant competitive moves are reshaping positioning: strategic partnerships between membrane suppliers and system integrators, and backward integration into activated carbon feedstock sourcing.
Among diversified industrial conglomerates, 3M Company and Eaton Corporation exemplify the scale-driven archetype leveraging cross-divisional distribution channels. DuPont Water Solutions anchors the premium membrane tier through proprietary thin-film composite chemistry. Pentair PLC represents the integrated water platform model combining hardware manufacturing with recurring service revenue capture.
| Leading Market Players |
|---|
| Pentair PLC |
| A. O. Smith Corporation |
| Culligan International |
| 3M Company |
| Evoqua Water Technologies |
| Eaton Corporation |
| Parker Hannifin |
| Toray Industries |
| DuPont Water Solutions |
| Others |
Value Chain & Pricing Dynamics
NSF/ANSI certification timelines gate both supply qualification and price differentiation simultaneously, compressing margins for carbon block fabricators unable to absorb 12-18 month validation costs while allowing membrane specialists to command premium positioning.
Pricing Analysis
Certification level creates the primary spread between premium thin-film composite membrane systems and commodity granular activated carbon assemblies. Three-tier pricing structure across NSF/ANSI 53 health-claim systems, standard chlorine reduction units, and economy sediment pre-filters reflects validation depth and replacement frequency commitments. Cost compression in carbon block tiers is intensifying because coconut shell charcoal feedstock prices fluctuate with Sri Lankan and Indonesian agricultural yields. Restaurant chains with centralized procurement exhibit lowest price sensitivity, while independent foodservice operators and small commercial buildings drive hard bargaining on point-of-use cartridge contracts.
Supply Chain Analysis
East Asian membrane manufacturing clusters expose North American system integrators to shipping volatility and tariff exposure. Spiral-wound polyamide element production centers in China, South Korea, and Japan, while coconut shell activated carbon feedstock draws from Sri Lanka and Indonesia. Single-source vulnerability concentrates in thin-film composite chemistry patents held by a limited supplier set. Distribution runs through captive dealer networks for legacy brands and direct-to-operator e-commerce platforms for replacement cartridge fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
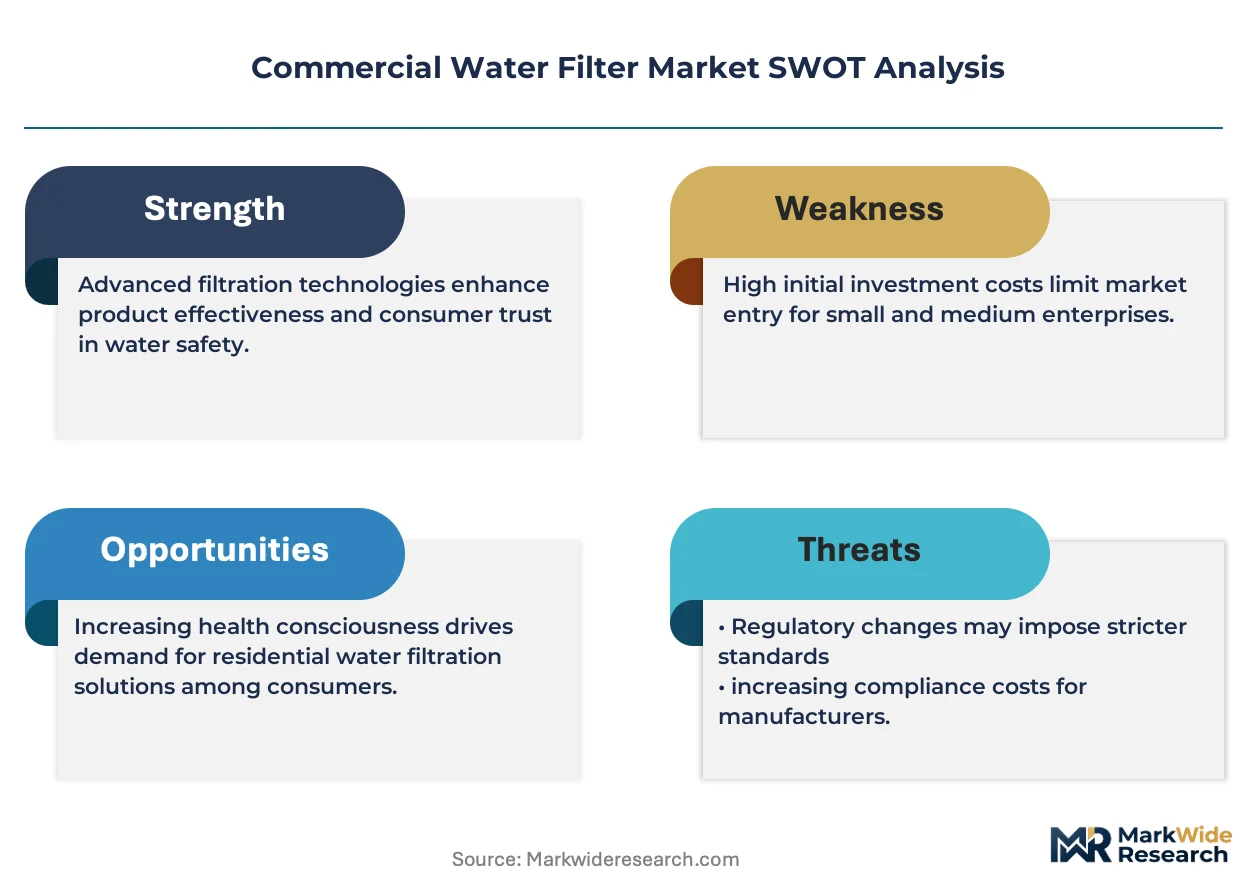
Fragmentation opportunity abounds as EPA PFAS regulations and state-level maximum contaminant limits splinter demand across specialized membrane technologies, creating niches for certified specialists to capture premium positioning.
For Market Incumbents: Shield recurring revenue streams by embedding IoT sensors and predictive maintenance algorithms into point-of-entry systems, locking out aftermarket competitors. Deepen backward integration into activated carbon feedstock sourcing to insulate margins from Sri Lankan and Indonesian agricultural volatility. Prioritize NSF/ANSI 401 certification investment ahead of federal PFAS rule finalization to capture replacement cycle acceleration. For New Entrants and Emerging Players: NSF/ANSI certification fast-tracks for ion exchange and nanofiltration media open immediate white-space in Michigan, New Jersey, and California industrial clusters confronting short-chain PFAS limits. Target hospital networks in the Northeastern United States where procurement unbundling creates entry points for third-party service providers. Lead with direct-to-operator e-commerce go-to-market angles bypassing established dealer networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core water treatment divisions with installed base but stagnant R&D investment. Long-term viability hinges on recurring revenue capture through sensor-enabled service contracts rather than transactional hardware sales. Monitor state-level PFAS maximum contaminant limit enactment velocity as the primary inflection signal for membrane technology demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NSF/ANSI 401 Certification Investment | Positions suppliers ahead of EPA PFAS rule finalization in United States industrial clusters. |
| Backward Integration into Carbon Feedstock | Insulates margins from Sri Lankan and Indonesian agricultural yield volatility. |
| Sensor-Enabled Service Contract Bundling | Captures recurring revenue and locks out aftermarket competitors in restaurant chains. |
| Direct-to-Operator E-Commerce Launch | Bypasses captive dealer networks for replacement cartridge fulfillment to independent foodservice. |
| UV-LED Module Manufacturing Scale-Up | Addresses pharmaceutical cleanroom and hospital dialysis demand for mercury-free validation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA enforcement actions, NSF certification databases, FDA Food Code guidance documents, and state-level PFAS regulatory filings. The research team conducted structured interviews with plant engineers at semiconductor fabrication facilities, procurement directors at multi-unit restaurant operators, biomedical engineers at Northeastern United States hospital systems, and aftermarket service heads at regional membrane distributors. Secondary validation drew from SEC 10-K filings of listed water technology conglomerates, customs trade data on activated carbon imports, and municipal water authority capital improvement plans. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, installation mode, and technology segments.
Segmentation dimensions modeled include product type (reverse osmosis, activated carbon, UV, sediment), end user vertical (restaurants, hospitals, industrial facilities, offices), installation configuration (point-of-entry, point-of-use), and technology platform (membrane filtration, nanofiltration, ion exchange, media filtration). CAGRs were derived from regression analysis of historical replacement cycle data and regulatory deadline acceleration effects. Industry-specific forecast inputs incorporated EPA Lead and Copper Rule implementation timelines and state-level PFAS maximum contaminant limit adoption curves.
Decision-makers should treat outputs as directional under assumptions of stable coconut shell charcoal feedstock availability and continued East Asian membrane manufacturing access; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EPA PFAS National Primary Drinking Water Regulation enforcement intensity and polyamide supply chain resilience evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
Home Water Softener System Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Water Desalination Equipment Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Global RO Water Purifier Market