
 Self-Cleaning Filters Market | 2026-2036
Self-Cleaning Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Cleaning Filters Market Outlook
The gap between electromechanical backwash control and AI-driven predictive maintenance is narrowing, forcing incumbent manufacturers to embed sensor arrays directly into filter housings. Eaton Corporation plc leverages its hydraulics heritage to integrate pressure-differential telemetry across industrial installations. Alfa Laval AG anchors its position in marine and offshore desalination through compact rotary designs that survive high-salinity cycling. HYDAC Filter System GmbH specializes in high-viscosity fluid recovery for steel rolling mills, a niche where manual cleaning remains prohibitively expensive.
Self-cleaning filters are pressure-vessel systems that remove suspended solids from process streams through automated regeneration cycles, typically employing stainless-steel wedge-wire screens with 10–3000 micron ratings and pneumatic or hydraulic backwash actuators. Their primary purpose is to maintain continuous throughput without production shutdowns in water-intensive operations. Automatic product types dominate capital deployment because they eliminate labor-intensive cartridge swaps in 24/7 process environments. Membrane technology segments command premium pricing due to their ability to achieve sub-micron separation without chemical pre-treatment, while backwash configurations retain volume leadership across agricultural irrigation and cooling tower applications.
The EPA enforces effluent limitation guidelines that mandate continuous particulate monitoring for heavy manufacturing dischargers, directly elevating replacement demand for legacy manual systems. REACH restrictions on hexavalent chromium plating compel European metal finishers to install closed-loop filtration with automated regeneration, tightening product certification requirements. India's Central Pollution Control Board enforcement of zero-liquid-discharge mandates for textile clusters in Gujarat and Tamil Nadu forces dye houses to adopt onsite backwash units rather than relying on municipal treatment. Stakeholders must weigh capital intensity against regulatory penalty exposure when selecting between hybrid and fully automatic architectures.
Market Dynamics
Automated backwash systems are displacing manual cartridge filters as zero-liquid-discharge mandates and continuous-process uptime requirements harden across water-intensive industries. This substitution wave concentrates procurement authority in engineering-procurement-construction firms and multinational plant operators with standardized specifications.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Continuous particulate monitoring mandates for heavy manufacturing dischargers in the United States force replacement of legacy manual systems with automated regeneration units.
- Zero-liquid-discharge enforcement:India's Central Pollution Control Board mandates for textile clusters in Gujarat and Tamil Nadu compel dye houses to install onsite backwash filtration rather than relying on municipal treatment.
- Stainless-steel wedge-wire screens:Advances in 10–3000 micron rating precision enable sub-micron separation without chemical pre-treatment, expanding addressable applications in food processing and pharmaceutical water loops.
Market Restraints
- High-grade stainless steel input costs:Nickel and molybdenum price volatility squeezes margin structures for filter housing manufacturers dependent on 316L and duplex alloys.
- Specialized actuator supply concentration:Pneumatic and hydraulic backwash valve assemblies concentrate among German and Japanese precision component suppliers, creating single-source vulnerability.
- Membrane fouling limitations:Organic and biological fouling in high-salinity environments degrades membrane-based self-cleaning performance, restricting deployment in certain desalination pre-treatment stages.
Strategic Opportunities
- AI-driven predictive maintenance convergence:Embedding pressure-differential sensor arrays with machine-learning analytics creates recurring revenue streams through condition-monitoring subscriptions.
- EU Drinking Water Directive revisions:Tightened microbiological standards across municipal treatment facilities in Germany, France, and Italy accelerate procurement of membrane-based systems with automated regeneration.
- Steel rolling mill fluid recovery:High-viscosity lubricant filtration in metalworking clusters represents an underpenetrated niche where manual cleaning remains prohibitively expensive.
Industry Challenges
- Integration complexity with legacy DCS architectures:Plant operators face protocol mismatches when retrofitting automated backwash controllers into decades-old distributed control systems without full line shutdowns.
- Certification timeline compression:REACH restrictions on hexavalent chromium plating compel European metal finishers to secure closed-loop filtration certifications under accelerated compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Cleaning Filters Market |
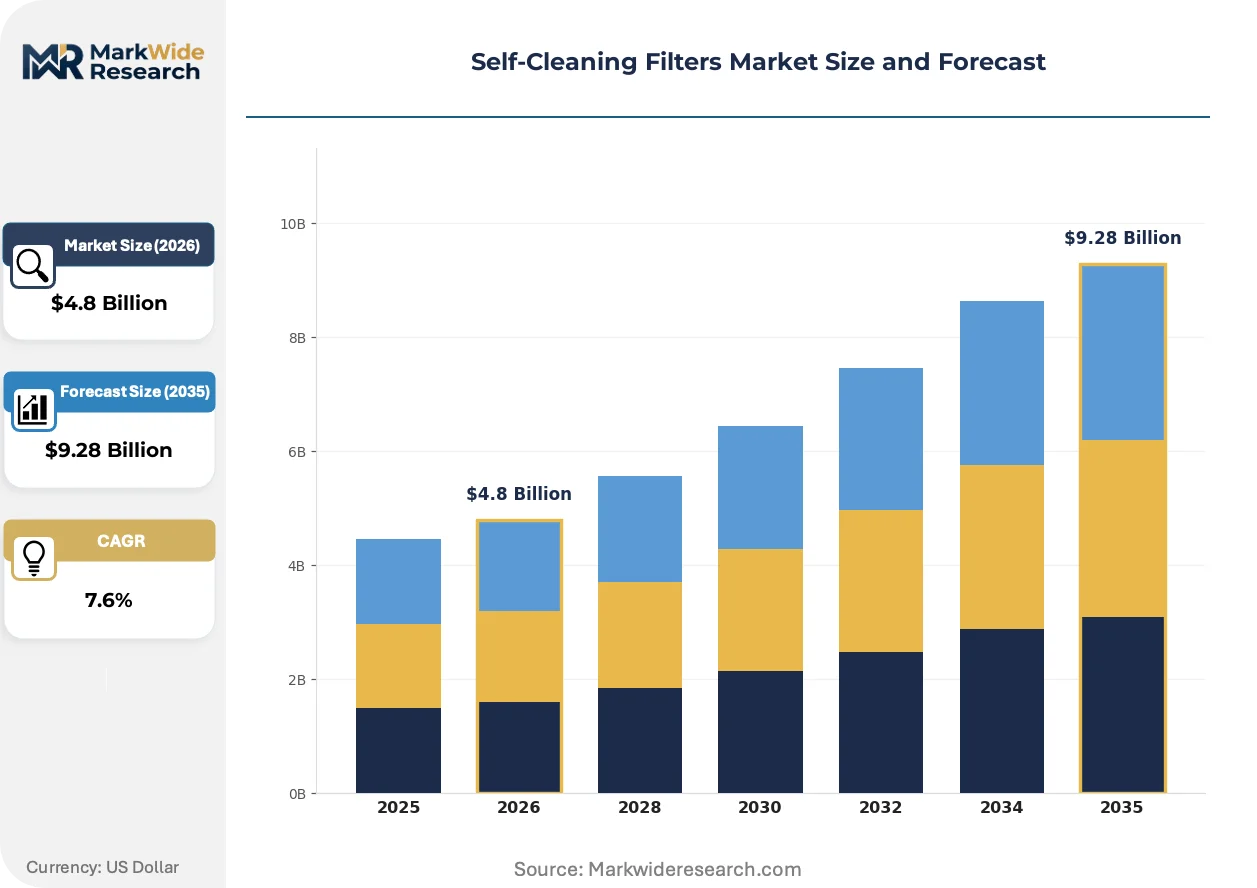
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Hybrid, Rotary Technology: Backwash, Reverse Flow, Pulsing, Membrane End User: Industrial, Residential, Commercial, Agricultural Installation Type: Onsite, Offsite, Fixed, Portable |
| Companies Covered | Amiad Water Systems Ltd, 3M Company, Eaton Corporation plc, HYDAC Filter System GmbH, The Dow Chemical Company, Alfa Laval AG, Baleen Filters Pty Ltd, Pall Corporation, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Cleaning Filters Market Strategic Shifts
Sensor-embedded filter housings are rewriting competitive boundaries between electromechanical specialists and industrial software providers. Convergence of hardware durability with predictive analytics is compressing maintenance cycles and reshaping supplier value propositions.
Wedge-wire screen technology is hybridizing with membrane pre-layer configurations to bridge the gap between coarse backwash systems and fine filtration. Food processing clusters in the Netherlands and dairy cooperatives in New Zealand are piloting these hybrid units for CIP-recovery loops. The technology is hybridizing capital equipment and consumables business models, forcing incumbent manufacturers to develop recurring revenue streams alongside unit sales.
REACH restrictions on hexavalent chromium plating compel European metal finishers to install closed-loop filtration with automated regeneration. The regulation tightens product certification requirements and elevates documentation burdens for filter suppliers serving surface-treatment applications. German automotive component suppliers and Italian aerospace finishers are consolidating procurement specifications to reduce vendor qualification overhead.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into discrete sensor-data subscriptions and on-demand technical support tiers. Municipal water authorities in Australia and Singapore are separating capital purchase decisions from long-term service agreements, enabling specialized analytics firms to insert themselves between filter OEMs and end-users. This disintermediation concentrates pricing pressure on hardware margins while shifting profitability toward software-enabled monitoring platforms.
Self-Cleaning Filters Market Segmentation
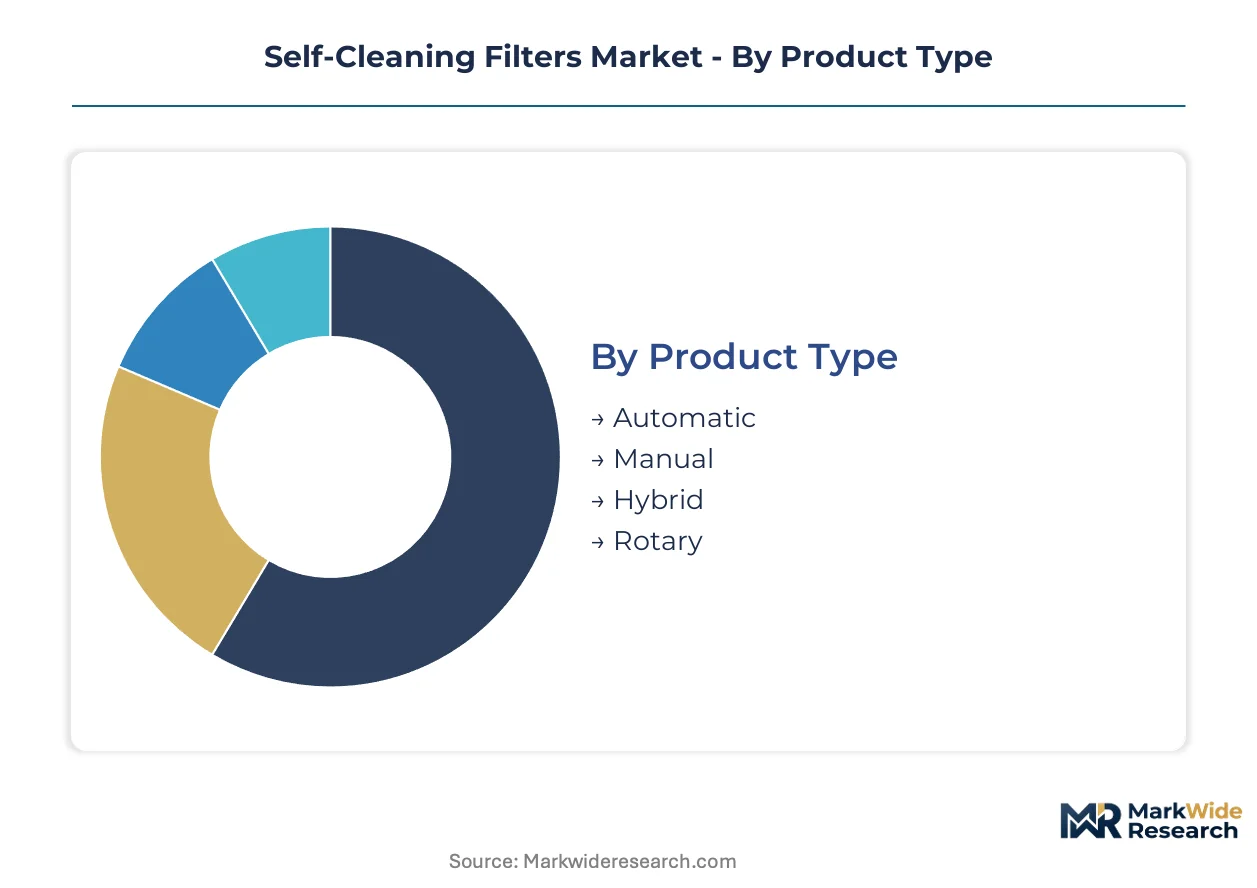
Self-cleaning filter procurement patterns diverge sharply across operational contexts, with continuous-process industries prioritizing automation while intermittent-use applications tolerate manual intervention. Understanding these segment boundaries clarifies where technology premiums command justified pricing.
Product Type:
Mature automatic architectures dominate capital deployment, while hybrid configurations emerge at the boundary of cost-sensitive and performance-critical applications.
- Automatic:Stainless-steel wedge-wire screen systems with pneumatic or hydraulic actuators eliminate production shutdowns in 24/7 process environments. Municipal water treatment facilities in Germany and textile dye houses in Gujarat under India's zero-liquid-discharge mandates drive replacement of legacy manual units.
- Manual:Cartridge-based units requiring operator intervention persist where labor costs undercut automation premiums and batch processes allow scheduled downtime. Small-scale agricultural irrigation in India's Punjab region and rural commercial facilities in Vietnam's Mekong Delta retain these systems despite tightening maintenance labor availability.
- Hybrid:Semi-automated configurations blending manual oversight with partial actuation serve mid-scale food processing clusters in the Netherlands piloting CIP-recovery loops.
- Rotary:Compact drum designs engineered for high-salinity cycling anchor marine and offshore desalination pre-treatment stages.
Automatic configurations retain volume leadership; hybrid designs hold the steepest expansion curve as cost-performance trade-offs tighten.
Technology:
Cost tier stratification separates commodity backwash systems from membrane premiums requiring minimal chemical pre-treatment.
- Backwash:Pressure-differential triggered reversal through wedge-wire screens achieves 10–3000 micron separation across cooling tower applications and agricultural irrigation networks. Cooling tower operators in Texas and Arizona under EPA effluent guidelines deploy these for continuous particulate control without chemical augmentation.
- Membrane:Sub-micron separation layers integrated with automated regeneration cycles command pricing premiums in pharmaceutical water loops and dairy processing. EU Drinking Water Directive revisions across France and Italy accelerate municipal procurement of membrane-based systems with microbiological compliance guarantees.
- Reverse Flow:Bidirectional fluid dynamics for high-viscosity applications concentrate in steel rolling mill lubricant recovery where manual cleaning costs prove prohibitive.
- Pulsing:Pneumatic shock-wave cleaning for fragile filtration media serves specialized pharmaceutical and biotechnology process streams.
Backwash technology anchors installed base economics; membrane systems are climbing the fastest as regulatory thresholds tighten.
End User:
Application context determines automation tolerance, with industrial process continuity commanding the highest specification tiers.
- Industrial:Heavy manufacturing dischargers under EPA continuous monitoring mandates and European metal finishers facing REACH hexavalent chromium restrictions drive specification intensity. Steel rolling mills, automotive component suppliers, and surface-treatment facilities require closed-loop filtration with automated regeneration and certification documentation.
- Agricultural:Irrigation network operators prioritize capital efficiency over automation sophistication, though water scarcity regulations in California and Australia's Murray-Darling Basin shift procurement toward backwash configurations with remote monitoring capability.
- Commercial:Building-scale HVAC and process water systems balance maintenance labor costs against automation premiums in Singapore's commercial districts and Dubai's hospitality sector.
- Residential:Point-of-entry systems for private wells and municipal backup concentrate in rural Germany and suburban Australian markets with variable source water quality.
Industrial end-use commands specification leadership; agricultural deployment is expanding most quickly as water stress intensifies irrigation efficiency mandates.
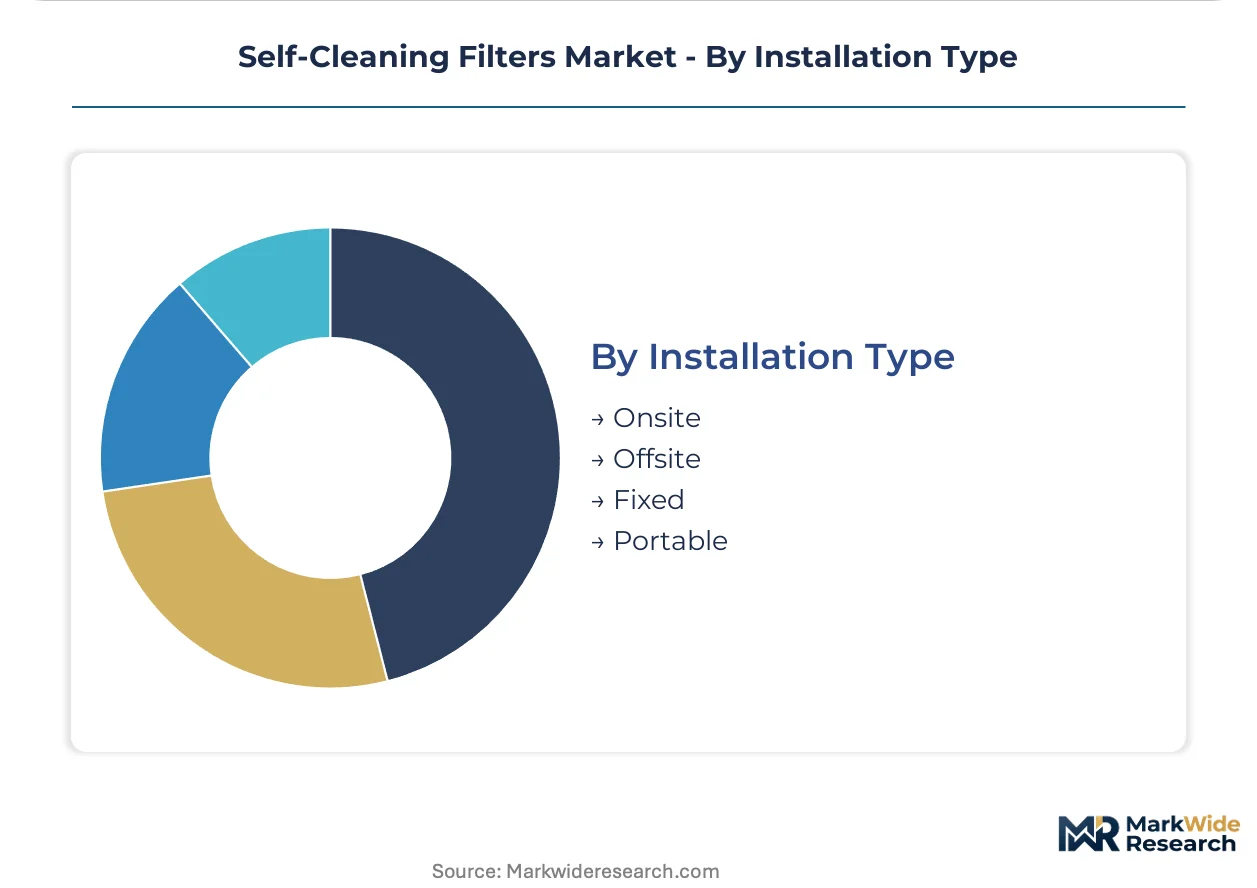
Installation Type:
Customer type segmentation separates permanent infrastructure investments from mobile or outsourced service models.
- Fixed:Permanent pressure-vessel installations integrated with distributed control systems dominate municipal treatment and industrial process water loops. Retrofit complexity with legacy DCS architectures in decades-old US manufacturing plants creates protocol mismatch challenges during specification.
- Portable:Skid-mounted rental units serve temporary construction dewatering, emergency response, and seasonal agricultural peaks. Australian mining operations and Canadian oil sands projects deploy these for rapid deployment without permanent infrastructure commitment.
- Onsite:Capital ownership with direct operator control prevails where process continuity risk exceeds service outsourcing appetite.
- Offsite:Third-party operated filtration-as-a-service models emerge in Singapore and Australian municipal markets separating hardware purchase from long-term service agreements.
Fixed installation retains capital deployment dominance; portable configurations are gaining share fastest in resource extraction and emergency response verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Self-cleaning filter trade flows reflect divergent industrial water stress and regulatory enforcement intensity. Import dependence concentrates in economies with limited domestic precision manufacturing capacity, while export leadership clusters where stainless-steel fabrication and actuator engineering co-locate.
United States
EPA effluent limitation guidelines drive continuous particulate monitoring mandates across heavy manufacturing dischargers. Cooling tower operators in Texas and Arizona deploy backwash configurations for regulatory compliance without chemical augmentation. Automotive component suppliers in Michigan and Ohio face replacement deadlines for legacy manual cartridge systems.
Germany
Municipal water treatment facilities expand procurement of membrane-based systems with automated regeneration cycles. REACH restrictions on hexavalent chromium plating compel metal finishers in Baden-Württemberg to install closed-loop filtration with accelerated certification timelines. Stuttgart-area automotive suppliers consolidate vendor specifications to reduce qualification overhead.
China
Textile and food processing clusters face mounting compliance deadlines under tightening discharge standards. Municipal water treatment facilities in the Yangtze River Delta region scale procurement of backwash and membrane-based systems. Shanghai and Jiangsu province dye houses adopt onsite filtration rather than relying on municipal treatment capacity.
India
Central Pollution Control Board zero-liquid-discharge mandates for textile clusters in Gujarat and Tamil Nadu force dye houses to adopt onsite backwash units. Industrial process water segments concentrate procurement authority in engineering-procurement-construction firms with standardized specifications. Ahmedabad and Surat processing facilities face compressed compliance timelines.
Australia
Municipal water authorities separate capital purchase decisions from long-term service agreements, enabling analytics firms to insert themselves between filter OEMs and end-users. Mining operations in Western Australia deploy portable skid-mounted units for rapid deployment without permanent infrastructure commitment. Murray-Darling Basin irrigation efficiency mandates shift procurement toward backwash configurations with remote monitoring.
Self-Cleaning Filters Market Competitive Environment
On the supply side, the industry is consolidating around electromechanical specialists with embedded sensor capabilities and diversified industrial conglomerates with filtration divisions. Three strategic archetypes dominate: precision actuator manufacturers extending into filter housings, membrane technology licensors pursuing system integration, and regional stainless-steel fabricators serving cost-sensitive agricultural segments. Competitive moves concentrate on M&A for sensor technology access and geographic expansion through localized assembly partnerships.
Among diversified industrial conglomerates, Eaton Corporation plc and Alfa Laval AG occupy positions spanning hydraulics heritage and marine desalination specialization respectively. HYDAC Filter System GmbH exemplifies the precision actuator-to-system integration archetype. These three anchors illustrate how competitive positioning diverges between hardware durability emphasis and predictive analytics convergence.
| Leading Market Players |
|---|
| Amiad Water Systems Ltd |
| 3M Company |
| Eaton Corporation plc |
| HYDAC Filter System GmbH |
| The Dow Chemical Company |
| Alfa Laval AG |
| Baleen Filters Pty Ltd |
| Pall Corporation |
| Parker Hannifin Corporation |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's precision actuator cluster transmits cost volatility directly into filter system pricing, with nickel and molybdenum fluctuations in 316L stainless steel feedstock amplifying margin pressure across German and Chinese manufacturing bases. Buyers in water-stressed regions absorb these input costs unevenly, creating divergent pricing power between membrane technology licensors and commodity backwash fabricators.
Pricing Analysis
Second-generation electromechanical backwash systems trade at 40-60% premiums over first-generation pneumatic configurations, while third-generation AI-embedded predictive maintenance platforms command subscription-tier recurring revenue models. Pricing stratifies across premium membrane systems with sub-micron certification, standard automatic wedge-wire units for industrial process loops, and economy-grade manual cartridges retained in agricultural irrigation. Price differentiation hinges on EPA effluent compliance certification tier and stainless-steel alloy grade specification. Cost compression in economy tiers intensifies because Indian textile clusters and Vietnamese commercial facilities prioritize capital efficiency over automation sophistication. Municipal water authorities in Germany and Australia demonstrate lowest price sensitivity, while dye houses in Gujarat under zero-liquid-discharge mandates face acute budget constraints.
Supply Chain Analysis
High-grade stainless steel feedstock draws from German, Chinese, and Japanese metallurgical complexes, with 316L and duplex alloy production concentrating in Ruhr Valley and Jiangsu province facilities. Pneumatic and hydraulic actuator assemblies rest on German and Japanese precision component suppliers, creating single-source vulnerability for backwash valve mechanisms. Wedge-wire screen fabrication sources from Italian and Indian metalworking clusters. Supply chain risk centers on nickel price volatility transmitted through specialty alloy contracts. Distribution runs through engineering-procurement-construction firms in industrial segments and specialized water treatment distributors in municipal and agricultural channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as EPA effluent guidelines and EU Drinking Water Directive revisions embed incumbent filtration systems with multi-year certification timelines that new entrants cannot shortcut.
For Market Incumbents: Insulate installed base relationships by embedding pressure-differential sensor arrays with predictive analytics subscriptions, converting one-time hardware sales into recurring revenue streams. Deepen backward integration into stainless-steel wedge-wire screen production to offset nickel and molybdenum cost volatility. Secure accelerated REACH certification for closed-loop filtration systems serving European metal finishers before compliance deadlines harden. For New Entrants and Emerging Players: Pursue portable skid-mounted rental configurations for Australian mining operations and Canadian oil sands projects, where rapid deployment without permanent infrastructure commitment creates service-model white space. Target steel rolling mill lubricant recovery in Baden-Württemberg and Michigan metalworking clusters, an underpenetrated niche where manual cleaning costs prove prohibitive. Lead with filtration-as-a-service offerings that separate hardware purchase from long-term monitoring agreements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision actuator manufacturers extending into sensor-embedded filter housings, as AI-driven predictive maintenance convergence rewrites competitive boundaries between electromechanical specialists and industrial software providers. Long-term viability hinges on recurring revenue attachment rates and regulatory certification breadth. Acquisition targets should demonstrate embedded sensor integration capabilities and municipal procurement relationships in Germany or Australia. The signal to watch is unbundling velocity in after-sales service contracts, as Singapore and Australian water authorities separate capital purchases from long-term agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Hardware Integration | Eaton Corporation plc and HYDAC Filter System GmbH embed pressure-differential telemetry to enable predictive maintenance subscriptions. |
| REACH Certification Acceleration | European metal finishers in Stuttgart and Milan require closed-loop filtration documentation under compressed hexavalent chromium compliance timelines. |
| Portable Rental Unit Expansion | Australian mining operations in Western Australia deploy skid-mounted systems for rapid dewatering without permanent infrastructure commitment. |
| Membrane-Backwash Hybrid Development | Dutch food processing clusters pilot CIP-recovery loops bridging coarse and fine filtration capabilities. |
| Filtration-as-a-Service Launch | Singapore municipal authorities separate hardware procurement from long-term monitoring agreements, enabling analytics firm insertion. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers at textile dye houses, municipal water treatment facility managers, EPC procurement leads, and aftermarket service directors, then refined through secondary validation against EPA effluent guideline filings, EU Drinking Water Directive implementation reports, and Central Pollution Control Board enforcement records. Bottom-up triangulation across equipment shipment data and top-down reconciliation with industrial water treatment capex disclosures anchored volume estimates. Trade flow analysis of stainless-steel wedge-wire screen exports and pneumatic actuator import dependencies informed supply-side constraints.
Demand-supply balance modeling across the analysis window segmented procurement by automation level, technology generation, end-use intensity, and installation permanence. CAGRs were derived from regression analysis of replacement cycle acceleration under tightening regulatory mandates, cross-referenced with engineering-procurement-construction firm specification standardization trends. Industry-specific forecast inputs incorporated zero-liquid-discharge enforcement timelines in Gujarat and Tamil Nadu, plus EU membrane system adoption curves under revised microbiological standards.
Sensitivities concentrate around nickel price volatility in 316L alloy contracts, REACH certification timeline compression for European metal finishers, and protocol mismatch risks in legacy DCS retrofit specifications. Forecasts reflect assumptions about regulatory enforcement continuity and actuator supply chain stability. Cross-checking against customs records of German and Japanese precision component shipments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Plant Based Water Filter Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Zero Liquid Discharge Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Water Purification Tablets Market