
 Water Quality Monitoring Equipment Market | 2026-2036
Water Quality Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Water Quality Monitoring Equipment Market Outlook
The transition from periodic manual sampling to continuous automated monitoring is shifting procurement patterns across municipal and industrial water operators. Xylem leverages its vertical integration across sensors, telemetry, and analytics software to capture bundled utility contracts. Hach sustains dominance in standardized colorimetric testing protocols for regulatory compliance workflows. Danaher Corporation anchors its position through specialized electrochemical sensor platforms deployed in North American treatment facilities.
Water quality monitoring equipment comprises instruments and sensor systems that measure chemical, physical, and biological parameters in water matrices, typically detecting contaminants at parts-per-billion sensitivity through optical absorbance, ion-selective electrode response, or acoustic signal propagation. These systems serve to ensure potable water safety, optimize wastewater treatment efficiency, and enforce discharge permits under environmental law. Optical sensors lead in growth velocity as photonic detection methods displace wet-chemistry approaches for online turbidity and dissolved organic carbon measurement. Electrochemical sensors occupy the largest installed base due to lower unit cost and proven reliability for pH and conductivity monitoring in continuous deployment configurations. Portable testing remains the margin-dense segment, commanding premium pricing from emergency response teams and field audit specialists who prioritize rapid deployment over laboratory precision.
The EPA enforces Safe Drinking Water Act amendments that mandate real-time distribution system monitoring, directly stimulating capital expenditure on networked sensor arrays. ISO 7027 and ASTM D1889 standards govern turbidity measurement protocols, creating compliance barriers for non-certified equipment suppliers seeking utility market access. China's MEE implements increasingly stringent surface water quality classifications that require provincial authorities to expand automated monitoring station density along major river basins. Stakeholders must weigh interoperability standards against proprietary data architectures as utilities consolidate multi-parameter platforms into unified SCADA environments.
Market Dynamics
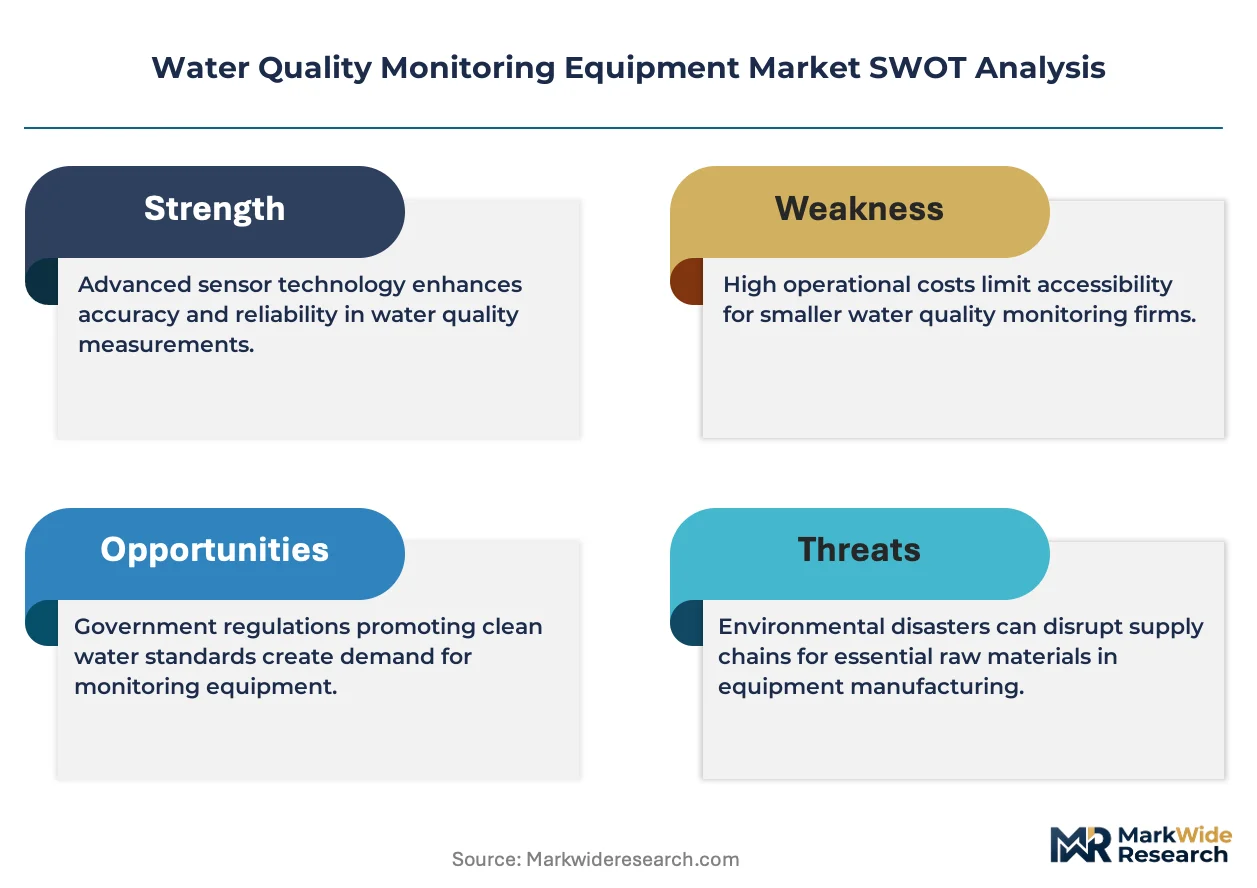
Real-time contaminant detection mandates from the EPA are forcing wholesale replacement of legacy grab-sampling infrastructure with networked sensor arrays, compressing procurement cycles and elevating interoperability requirements for municipal water utilities.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Mandated real-time distribution system monitoring accelerates capital deployment on continuous analyzers across US municipal networks.
- Photonic detection methods:Optical absorbance sensors for dissolved organic carbon measurement displace wet-chemistry approaches in turbidity monitoring applications.
- Federal infrastructure funding:Aging water infrastructure in the United States drives wholesale modernization programs at state and municipal levels.
Market Restraints
- Sensor calibration complexity:Ion-selective electrodes require frequent recalibration protocols that increase total cost of ownership for continuous deployment configurations.
- Proprietary data architectures:Vendor-specific communication protocols create integration friction as utilities consolidate multi-parameter platforms into unified SCADA environments.
- Skilled technician scarcity:Electrochemical sensor maintenance demands specialized expertise that concentrates in regional service hubs, extending response times for rural utilities.
Strategic Opportunities
- China's MEE surface water classifications:Provincial authorities must expand automated monitoring station density along major river basins under tightening national standards.
- Portable testing premiumization:Emergency response teams and field audit specialists prioritize rapid deployment capabilities over laboratory precision, supporting margin-dense handheld device segments.
- AI-driven predictive analytics:Machine learning integration with acoustic signal propagation sensors enables anomaly detection before contaminant thresholds breach regulatory limits.
Industry Challenges
- ISO 7027 certification timelines:Turbidity measurement protocol compliance creates market access barriers for non-certified equipment suppliers seeking utility contracts.
- Interoperability standardization delays:Competing industry consortiums advance divergent open-architecture specifications, complicating multi-vendor procurement decisions for treatment facility operators.
- Legacy analog infrastructure:Decades-old telemetry systems in North American treatment plants require parallel investment in gateway technologies to support digital sensor feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Quality Monitoring Equipment Market |
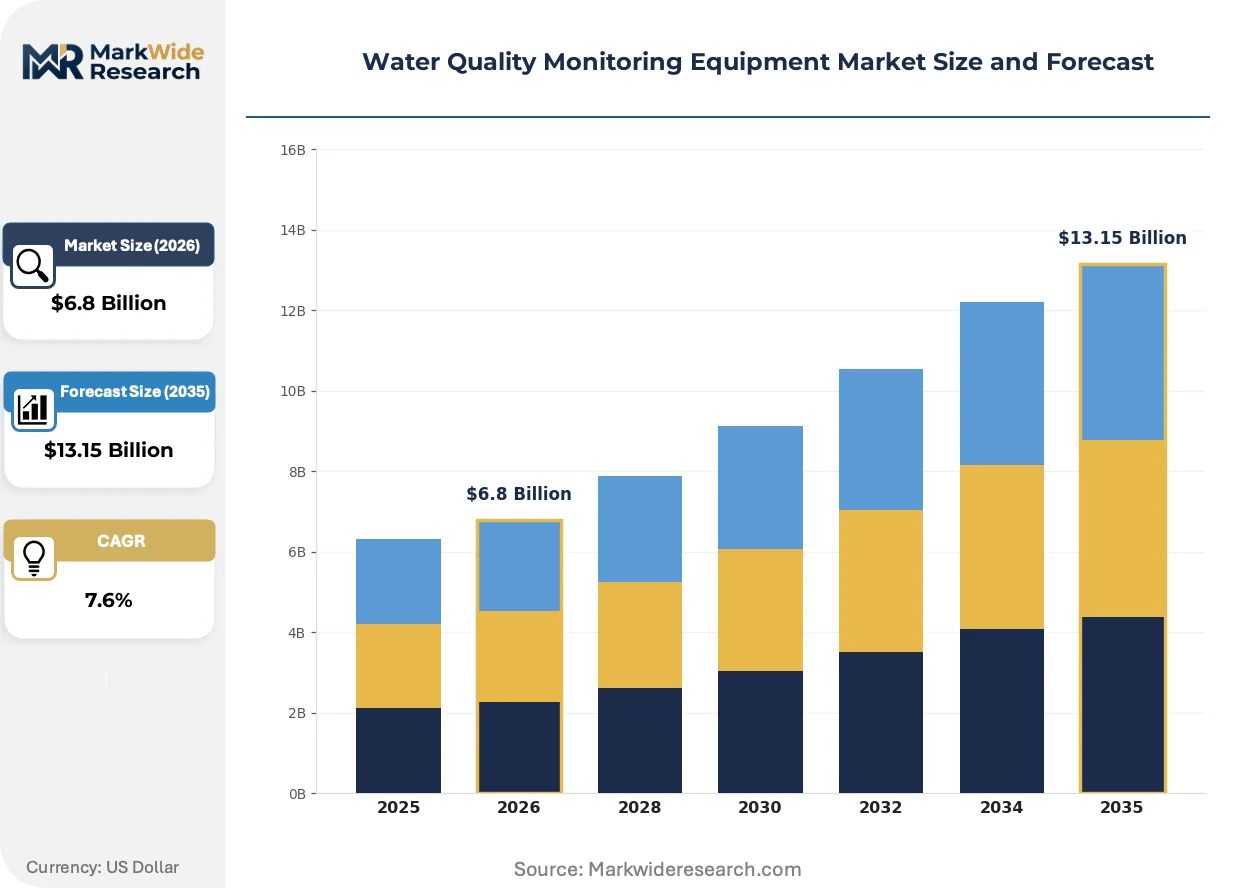
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: pH Meters, Turbidity Meters, Dissolved Oxygen Meters, Conductivity Meters Technology: Optical Sensors, Electrochemical Sensors, Colorimetric Analysis, Ultrasonic Sensors End User: Agricultural Sector, Environmental Agencies, Industrial Sector, Research Laboratories Deployment: In-Situ Monitoring, Laboratory Analysis, Portable Testing, Continuous Monitoring |
| Companies Covered | Xylem, Hach, Thermo Fisher Scientific, Danaher Corporation, ABB, Emerson, Horiba, Endress+Hauser, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Quality Monitoring Equipment Market Strategic Shifts
Photonic sensing architectures and predictive analytics integration are compressing the gap between contaminant detection and system response, enabling autonomous treatment adjustments that reduce human-in-the-loop dependencies for water quality management.
Solid-state optical sensors leveraging UV-LED excitation and photodiode arrays for dissolved organic carbon quantification are electrifying the transition from laboratory-based chromatography to inline monitoring. Metropolitan water authorities in California and Texas deploy these systems at intake points to trigger coagulant dosing adjustments within minutes rather than hours. The technology is electrifying competitive positioning around total analyzer footprint and reagent-free operation as primary procurement criteria.
REACH authorization requirements for mercury-containing reagents in analytical instruments are accelerating substitution with electrochemical and optical alternatives across European treatment facilities. The European Chemicals Agency's restriction roadmap forces manufacturers to redesign legacy colorimetric protocols around non-toxic indicator chemistries. German and French utilities now specify mercury-free certification as a mandatory tender precondition, compressing supplier qualification timelines.
Service unbundling from hardware procurement is fragmenting traditional bundled contracts as municipal finance departments favor operational expenditure models. Equipment lessors and third-party calibration specialists capture recurring revenue streams previously retained by original manufacturers. This pattern concentrates in the United States, where municipal bond constraints and infrastructure funding volatility drive preference for subscription-based sensor network deployments over capital purchases.
Water Quality Monitoring Equipment Market Segmentation
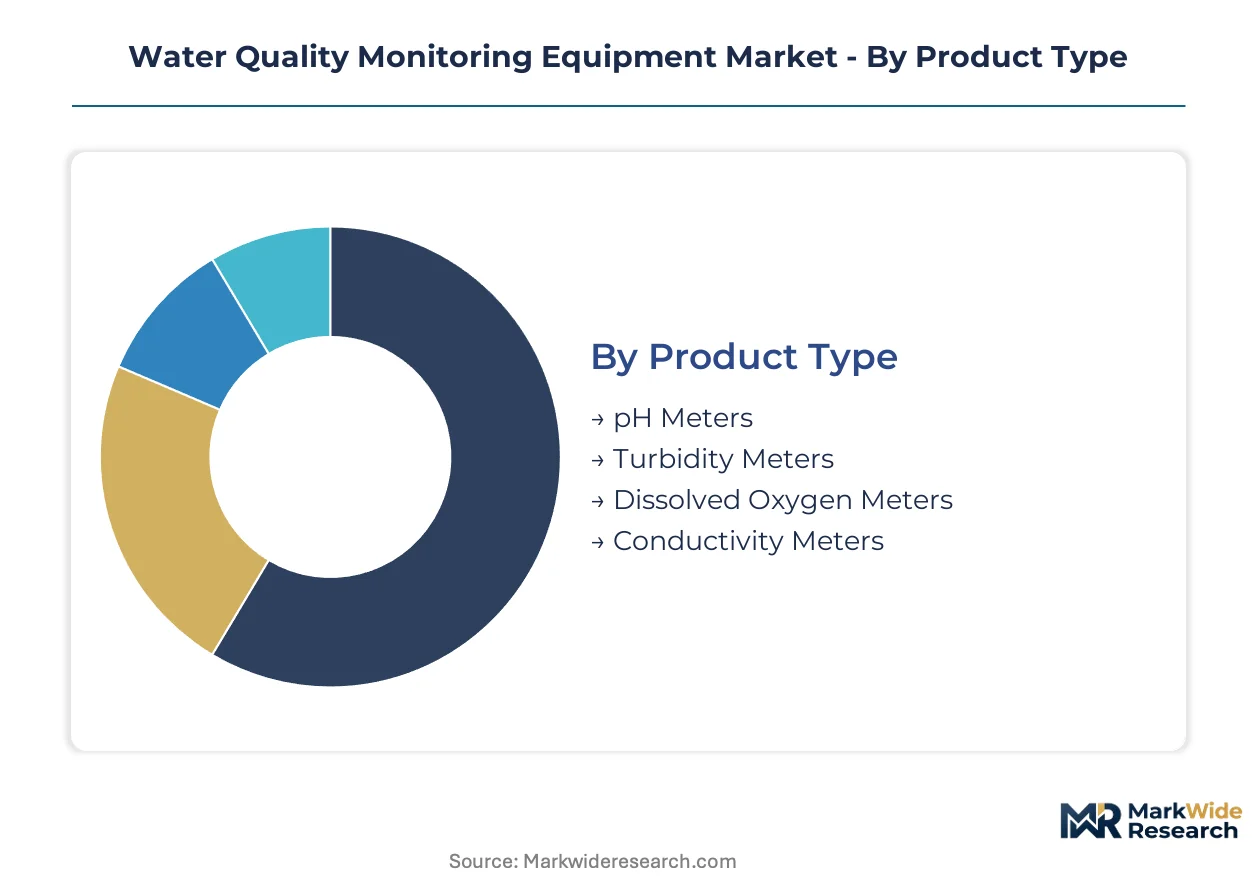
Water quality monitoring equipment segments by measurement parameter, sensing architecture, deployment environment, and operational workflow. Procurement patterns diverge sharply between regulatory compliance mandates and operational optimization priorities across end-use verticals.
Product Type:
Measurement parameter specialization dictates sensor design complexity and calibration protocols.
- pH Meters:Glass membrane or ISFET-based hydrogen ion activity measurement with temperature compensation circuits. Municipal utilities in the United States deploy these for distribution system compliance under EPA Lead and Copper Rule revisions, driving networked electrode arrays with automatic buffer recognition.
- Turbidity Meters:Nephelometric or attenuation-based suspended particle detection governed by ISO 7027 and ASTM D1889 standards. Metropolitan water authorities prioritize these for intake protection and coagulation control, with photonic architectures displacing legacy wet-chemistry approaches.
- Dissolved Oxygen Meters:Optical luminescence or Clark-type electrochemical sensors for biological process monitoring. Wastewater treatment facilities specify these for activated sludge optimization.
- Conductivity Meters:Four-electrode or toroidal induction cells for ionic strength quantification. Industrial discharge permit enforcement drives demand for these in manufacturing corridors.
pH meters lead on scale; turbidity meters lead on momentum.
Technology:
Detection physics determines reagent dependency, maintenance intervals, and integration complexity with SCADA environments.
- Optical Sensors:UV-LED excitation and photodiode arrays for dissolved organic carbon and turbidity quantification. California and Texas metropolitan authorities deploy solid-state photonic systems at raw water intakes to trigger coagulant dosing adjustments within minutes.
- Electrochemical Sensors:Ion-selective electrodes and amperometric cells for pH, conductivity, and specific ion measurement. These occupy the largest installed base due to proven reliability in continuous deployment configurations despite frequent recalibration requirements.
- Colorimetric Analysis:Wet-chemistry automated analyzers using indicator reactions for regulated parameter compliance. REACH authorization pressures for mercury-containing reagents are forcing redesign around non-toxic chemistries in European facilities.
- Ultrasonic Sensors:Acoustic signal propagation for flow-coupled concentration measurement and anomaly detection. AI-driven predictive analytics integration with these sensors enables pre-threshold contaminant identification.
Electrochemical sensors dominate installed base; optical sensors are expanding most quickly.
End User:
Regulatory pressure intensity and capital availability shape procurement sophistication across verticals.
- Agricultural Sector:Irrigation water quality and nutrient runoff monitoring for discharge permit compliance. Nutrient management plans in intensive farming regions drive demand for portable nitrate and phosphate testing.
- Environmental Agencies:Surface water classification enforcement and watershed protection mandates. China's MEE tightening of river basin standards requires provincial authorities to expand automated station density.
- Industrial Sector:Process water optimization and effluent permit adherence. Manufacturing facilities prioritize multi-parameter platforms with unified data architectures for SCADA integration.
- Research Laboratories:Method development and reference-grade analytical protocols. Academic and government labs sustain demand for laboratory-precision chromatography and spectrometry systems.
Environmental agencies lead on scale; industrial sector leads on momentum.
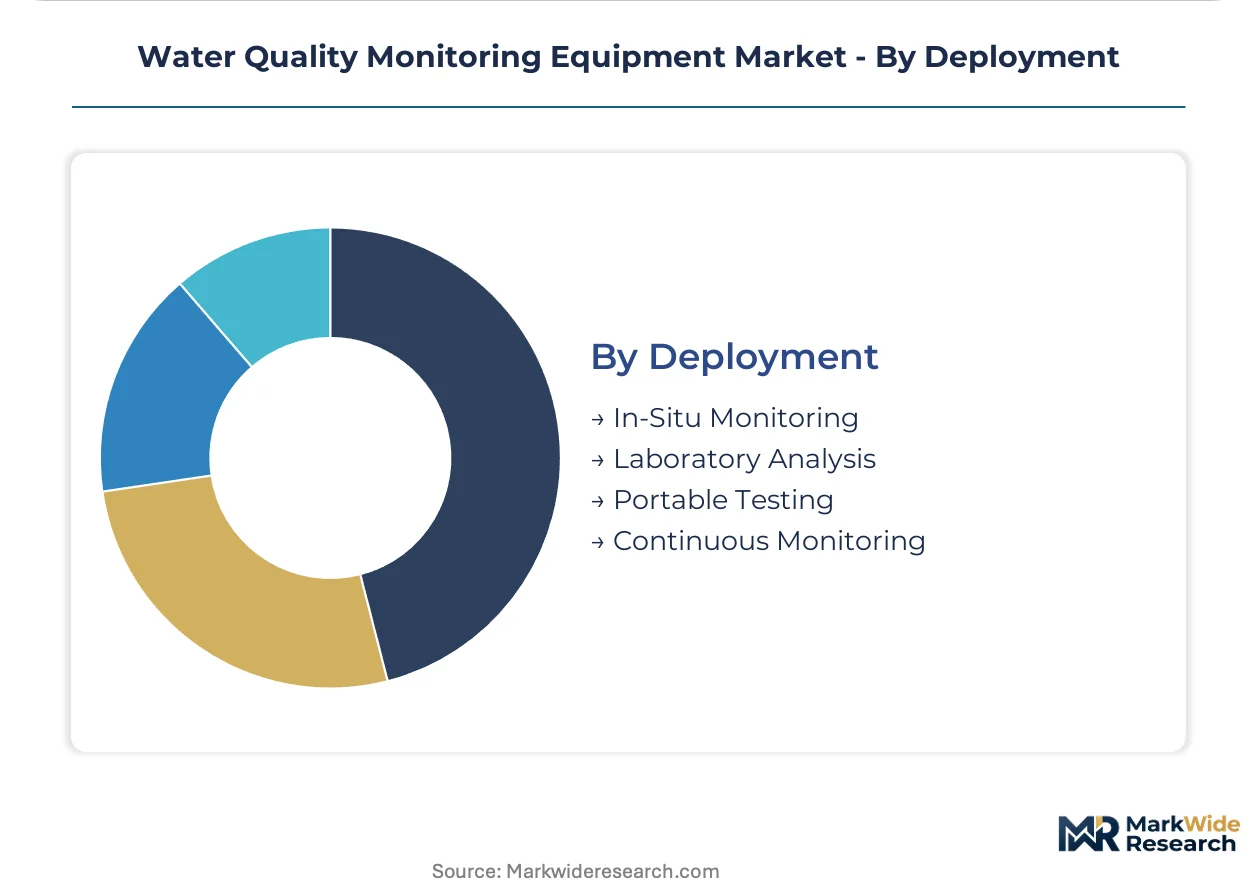
Deployment:
Operational expenditure preferences are fragmenting traditional capital procurement models across configuration types.
- In-Situ Monitoring:Submersible probe arrays for direct water body measurement without sample extraction. Lake and reservoir managers deploy these for stratification and algal bloom tracking.
- Laboratory Analysis:Benchtop instrumentation with reference-grade precision for regulatory confirmatory testing. Certified laboratories maintain these for dispute resolution and enforcement support.
- Portable Testing:Handheld devices prioritizing rapid deployment over laboratory precision. Emergency response teams and field audit specialists pay premium pricing for battery-operated multi-parameter units.
- Continuous Monitoring:Permanent installation with telemetry for real-time data transmission and automated alerts. Municipal finance departments increasingly favor subscription-based sensor network deployments over capital purchases.
Continuous monitoring leads on scale; portable testing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal water utilities in the United States anchor procurement volume for networked sensor arrays as federal infrastructure funding accelerates wholesale modernization of aging treatment and distribution systems.
United States
Metropolitan water authorities in California and Texas deploy solid-state optical sensors at raw water intakes to trigger coagulant dosing adjustments within minutes. EPA Lead and Copper Rule revisions mandate real-time distribution system monitoring, compressing procurement cycles for continuous analyzers. State-level infrastructure grants concentrate deployment in the Great Lakes region and Southwest corridor.
China
Provincial authorities along the Yangtze and Yellow River basins expand automated monitoring station density under tightening surface water quality classifications. MEE implements increasingly stringent national standards that require real-time data transmission from watershed monitoring networks. Industrial clusters in the Pearl River Delta retrofit manufacturing facilities with multi-parameter platforms for discharge permit enforcement.
Germany
REACH authorization requirements for mercury-containing reagents force redesign of legacy colorimetric protocols around non-toxic indicator chemistries. Municipal utilities in the Rhine-Ruhr and Bavarian regions specify mercury-free certification as mandatory tender preconditions. German treatment facilities lead European adoption of electrochemical alternatives to wet-chemistry approaches.
India
Central Pollution Control Board mandates expand automated monitoring along the Ganges and Yamuna river systems under the Namami Gange program. State water boards in Maharashtra and Gujarat deploy portable testing units for field audit specialists prioritizing rapid deployment capabilities. Industrial discharge enforcement drives demand for conductivity and pH monitoring in the chemical manufacturing corridors of Gujarat.
Japan
Metropolitan waterworks bureaus in Tokyo and Osaka integrate AI-driven predictive analytics with acoustic signal propagation sensors for pre-threshold contaminant identification. METI promotes standardization of open-architecture specifications to reduce integration friction in multi-vendor procurement. Advanced treatment facilities in the Kansai region deploy photonic detection methods for dissolved organic carbon measurement.
Water Quality Monitoring Equipment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent analytics software and service unbundling opportunities. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with captive water divisions, specialized instrumentation pure-plays with deep regulatory compliance expertise, and precision sensor technology developers. Competitive dynamics center on bundled utility contract capture versus modular component supply, with backward integration into sensor manufacturing and telemetry systems representing the dominant capability-building pattern.
Within the diversified industrial tier, Xylem and Danaher Corporation exemplify vertical integration strategies spanning sensors, telemetry, and analytics platforms. Hach occupies a position as the compliance workflow specialist with standardized colorimetric testing protocols. These three anchors represent contrasting approaches to municipal utility procurement: full-stack system integration, electrochemical sensor specialization, and regulatory-certified analytical methods respectively.
| Leading Market Players |
|---|
| Xylem |
| Hach |
| Thermo Fisher Scientific |
| Danaher Corporation |
| ABB |
| Emerson |
| Horiba |
| Endress+Hauser |
| Shimadzu Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH authorization timelines for mercury-containing reagents gate qualified supply access for European utilities and compress premium-tier pricing power for compliant equipment manufacturers. German and French tender specifications now embed mercury-free certification as mandatory preconditions, forcing suppliers to absorb redesign costs or surrender high-margin regional contracts.
Pricing Analysis
Input-cost pass-through from UV-LED photodiode arrays and ion-selective electrode membranes runs through equipment bill-of-materials with limited buffering capacity. A three-tier pricing structure across premium, standard, and economy levels separates ISO 7027-certified continuous analyzers from portable field units and uncertified component sales. Pricing pressure stems from municipal finance departments favoring subscription-based sensor network deployments over capital purchases. Agricultural irrigation operators exhibit highest price sensitivity; metropolitan water authorities in California and Texas demonstrate lowest sensitivity due to federal infrastructure grant absorption.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale utility demand for multi-parameter platforms while specialized distributors serve fragmented agricultural and industrial end-users. Manufacturing concentration in Germany, Japan, and the United States draws from precision glass membrane foundries, rare-earth phosphor deposits, and semiconductor-grade photodiode wafer supply. Single-source vulnerability sits with toroidal induction cell cores sourced from Japanese specialty metalworkers. Distribution runs through regional service hubs that concentrate electrochemical sensor calibration expertise, extending lead times for rural North American utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA-mandated real-time monitoring infrastructure investments in the United States outpace European municipal bond constraints, creating divergent procurement cycle velocities and margin capture opportunities.
For Market Incumbents: Lock in bundled utility contract renewal terms before service unbundling fragments traditional hardware-software-procurement packages. Xylem's vertical integration model faces erosion from third-party calibration specialists capturing recurring revenue streams; backward integration into sensor manufacturing and captive telemetry development represents the priority defensive lever. Certification investment in mercury-free colorimetric protocols preserves European market access against REACH authorization deadlines. For New Entrants and Emerging Players: The price-point gap between premium photonic detection systems and economy-grade electrochemical electrodes creates white-space opportunity for mid-tier solid-state optical sensors with reduced reagent dependency. China's MEE surface water classification enforcement represents the most penetrable geography; provincial authorities along the Yangtze and Yellow River basins expand automated station density under tightening national standards. A calibration-as-a-service go-to-market angle bypasses capital purchase barriers among municipal finance departments. For Investors and Strategic Acquirers: Roll-up economics work for specialized instrumentation pure-plays because regulatory compliance expertise concentrates in fragmented regional service hubs with limited scalability. Long-term viability over a multi-year window hinges on AI-driven predictive analytics integration capabilities. The signal to watch is municipal procurement language shifting from capital expenditure line items to operational expenditure subscription terms.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Sensor Platform Integration | UV-LED excitation systems displace wet-chemistry approaches in California and Texas metropolitan deployments. |
| Mercury-Free Certification Program | REACH compliance unlocks German and French utility tender access against authorization deadline pressures. |
| Calibration-as-a-Service Launch | Subscription revenue models capture municipal finance department preference over capital purchases. |
| AI-Driven Predictive Analytics Development | Machine learning integration with acoustic sensors enables pre-threshold contaminant identification for Japanese utilities. |
| Provincial Monitoring Station Expansion | China's MEE tightening drives automated density increases along Yangtze and Yellow River basins. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal utility procurement officers, water treatment plant engineers, environmental regulatory compliance leads, and aftermarket calibration service specialists with secondary validation. EPA enforcement databases, ISO certification registries, MEE surface water quality disclosures, and municipal bond filing documents anchored supply-side and demand-side sizing. Bottom-up equipment shipment tallies and top-down infrastructure spending allocations were cross-referenced for triangulation.
Comparable-period anchoring linked historical sensor deployment patterns to projected procurement cycle compression under EPA Lead and Copper Rule revisions across the modeling period. Segmentation dimensions included measurement parameter specialization, sensing architecture physics, deployment environment configuration, and end-use vertical regulatory pressure intensity. CAGRs were derived from installed base turnover rates and replacement cycle acceleration factors. Forecast inputs incorporated federal infrastructure funding allocation trajectories and REACH authorization timeline impacts on European equipment redesign requirements.
Caveats apply where EPA enforcement delay, REACH authorization extension, or municipal bond market volatility could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory implementation schedules and infrastructure grant disbursement velocities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
India Cloud Seeding Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Global Water Quality Monitoring Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Asia-Pacific Food and Environment Manual Testing Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Europe Air Quality Monitoring Market
Environmental Monitoring
Water Pipeline Leak Detection System Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Water Quality Monitoring Systems Market