
 Global Water Quality Monitoring Market | 2026-2036
Global Water Quality Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water Quality Monitoring Market Outlook
Continuous monitoring-grade instrumentation is redrawing procurement standards across utilities and industrial operators. Xylem Inc. leverages its vertical integration across sensor manufacturing and digital platforms to control deployment costs in North American municipal accounts. Danaher Corporation anchors its position through specialized electrochemical probe lines that dominate laboratory calibration workflows. Bureau Veritas SA competes on geographic breadth, extending third-party validation services across European and Asia-Pacific industrial clients.
Water quality monitoring encompasses the systematic measurement of physical, chemical, and biological parameters—turbidity, dissolved oxygen, heavy metals, and microbial loads—using electrochemical or spectrophotometric methods to ensure regulatory compliance and process control. The primary purpose spans safeguarding drinking water distribution, optimizing wastewater treatment throughput, and certifying industrial effluent before environmental discharge. Sensor product lines lead in volume terms due to their integration into IoT-enabled networks, while analyzer systems command premium positioning through multi-parameter chromatography configurations that environmental testing laboratories prefer. Electrochemical technology sustains the largest installed base for dissolved oxygen and pH measurement, though fluorometry is displacing legacy methods in algal bloom and emerging contaminant detection.
The United States EPA enforces Clean Water Act monitoring mandates that drive municipal capital expenditure on automated sampling stations. The European Union's Drinking Water Directive and REACH framework shape product certification requirements for equipment sold across member states. China's MEE implements surface water quality standards that compel industrial facilities to install real-time discharge monitoring. Stakeholders must weigh regulatory trajectory against sensor lifecycle economics when allocating capital between retrofit upgrades and greenfield deployments.
Market Dynamics
Real-time sensor networks are compressing replacement cycles for legacy electrochemical probes as utilities face dual pressure from tightening contaminant thresholds and operational efficiency mandates. Capital allocation now tilts toward IoT-integrated systems that merge measurement with predictive analytics.
Growth Catalysts
- EU Drinking Water Directive revision:The tightened thresholds for PFAS and microplastics are forcing municipal utilities across Germany, France, and the Netherlands to upgrade distribution network monitoring density.
- Industrial corridor enforcement in China:Provincial environmental bureaus in Jiangsu and Zhejiang provinces now mandate real-time discharge monitoring for chemical and textile facilities, pulling continuous analyzer installations.
- Fluorometry advancement:Algal bloom detection capabilities are expanding addressable applications for surface water management beyond traditional dissolved oxygen and pH measurement.
Market Restraints
- Reference electrode supply concentration:Silver-silver chloride sensor components rely heavily on processing facilities concentrated in East Asian supply chains, creating input cost volatility.
- Laboratory calibration dependency:Electrochemical probe accuracy requires periodic recalibration against certified reference materials, locking in recurring service costs that resist automation.
- Interference complexity:Spectrophotometric methods face matrix interference in high-turbidity industrial effluents, limiting deployment in mining and pulp processing applications.
Strategic Opportunities
- India smart city instrumentation:The AMRUT 2.0 urban infrastructure scheme creates procurement channels for distributed sensor networks in water-stressed municipalities across Maharashtra and Tamil Nadu.
- Blockchain-secured data verification:Integration of distributed ledger technology with monitoring outputs addresses emerging requirements for tamper-proof compliance documentation in cross-border supply chains.
- Per- and polyfluoroalkyl substance detection:Emerging contaminant monitoring represents a greenfield application segment where specialized fluorometry systems command premium positioning ahead of standardized methods.
Industry Challenges
- Field calibration expertise scarcity:The intersection of electrochemistry, firmware diagnostics, and regulatory documentation requirements creates talent gaps that extend deployment timelines for complex multi-parameter stations.
- Legacy SCADA integration friction:Brownfield utilities face protocol mismatches between new IoT-enabled sensors and existing control architectures, forcing middleware investments that erode project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water Quality Monitoring Market |
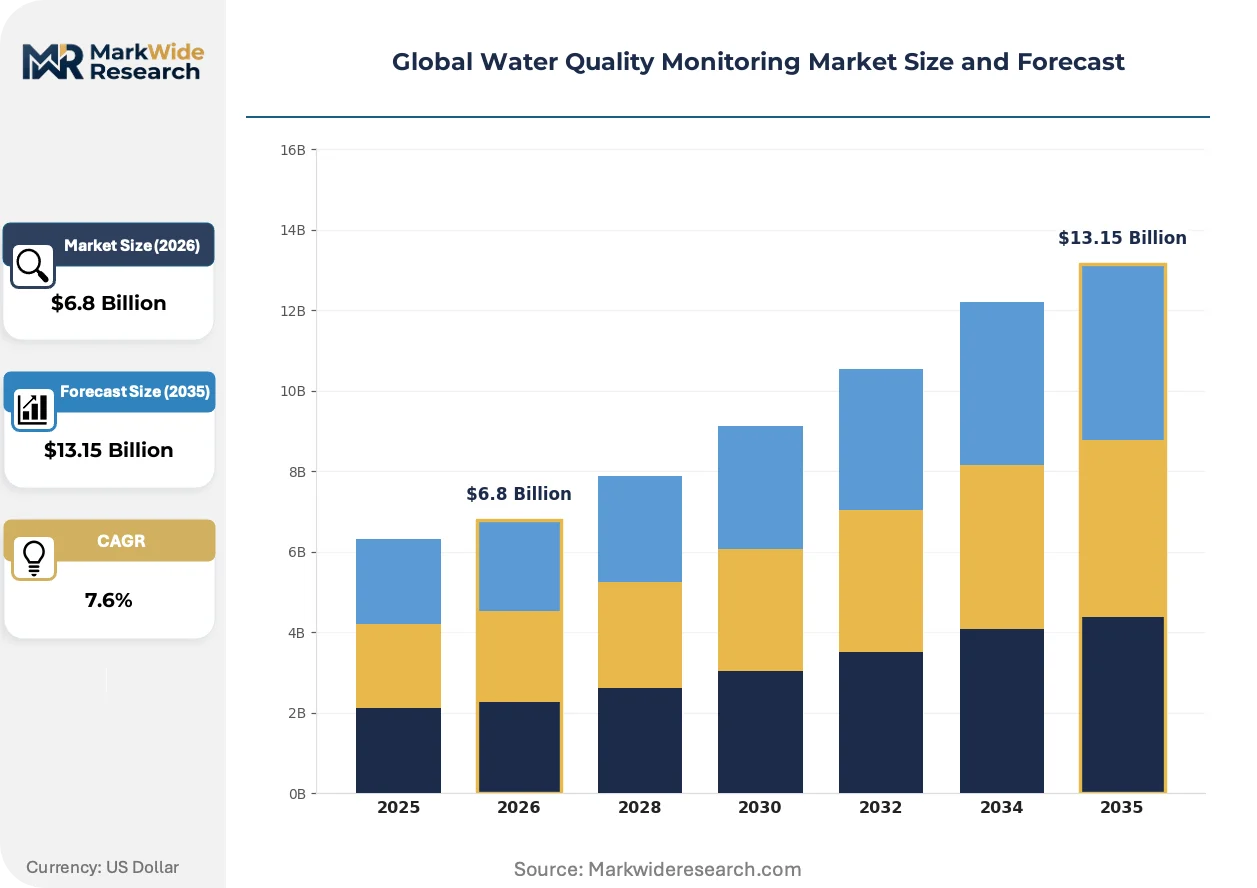
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor, Detector, Probe, Analyzer Application: Wastewater Treatment, Drinking Water, Industrial Processes, Aquaculture Technology: Electrochemical, Spectrophotometry, Fluorometry, Chromatography End User: Government, Agriculture, Environmental Testing, Research Institutes |
| Companies Covered | Intertek Group plc, Xylem Inc., Eurofins Scientific SE, Thermo Fisher Scientific Inc., Danaher Corporation, SGS SA, ALS Limited, HORIBA, Ltd., Bureau Veritas SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water Quality Monitoring Market Strategic Shifts
Sensor architecture is converging with edge computing and low-power wide-area networking, collapsing the distinction between measurement hardware and data infrastructure. This fusion is rewriting procurement criteria and vendor competitive positioning.
Microfluidic sample handling is miniaturizing multi-parameter analyzer footprints from benchtop to portable configurations. Environmental consultants and emergency response teams are adopting handheld units for rapid field screening. The technology is compressing the addressable market gap between laboratory-grade precision and single-parameter probe simplicity.
REACH framework amendments are extending substance monitoring obligations to industrial effluent dischargers previously exempt from continuous measurement. Chemical manufacturers in Belgium and the Netherlands face expanded parameter lists including heavy metals and persistent organic pollutants. Analyzer suppliers are responding with modular optical detection platforms that accommodate evolving regulatory schedules without hardware replacement.
Utility procurement committees now unbundle hardware acquisition from decade-long service contracts, forcing equipment vendors to compete on capital cost transparency rather than bundled lifecycle pricing. This disintermediation is most pronounced in United States municipal accounts where GSA schedule purchasing and cooperative buying organizations aggregate demand across state lines. Third-party calibration laboratories are capturing service revenue that previously flowed to original equipment manufacturers.
Global Water Quality Monitoring Market Segmentation
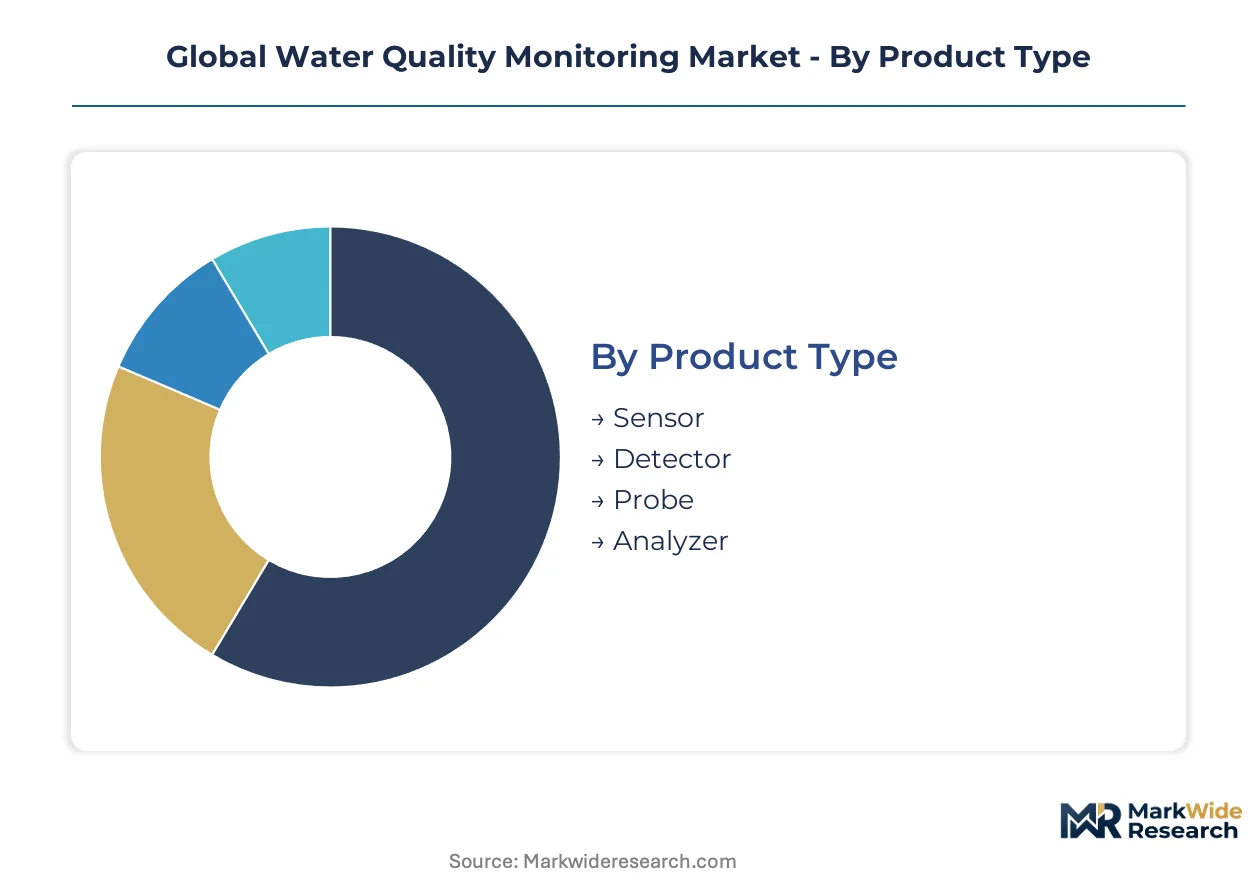
Water quality monitoring procurement splits across hardware configurations, deployment contexts, and measurement principles. Each segmentation axis carries distinct margin profiles and vendor specialization patterns that shape competitive entry strategies.
Product Type:
Margin pools concentrate in analyzer systems where multi-parameter configurations and software integration sustain premium positioning against commoditized single-point sensors.
- Sensor:Solid-state electrochemical and optical sensors form the volume foundation of IoT-enabled distribution networks. Municipal utilities across Germany and the United States are deploying dissolved oxygen and turbidity sensors at density levels that compress unit economics while expanding addressable parameter coverage.
- Analyzer:Benchtop and portable multi-parameter systems command pricing multiples through chromatography and spectrophotometry modules that environmental testing laboratories require for regulatory certification workflows. The integration burden of sample handling, detection, and data management sustains vendor stickiness.
- Detector:Single-purpose units for specific contaminant classes—heavy metals, microbial indicators—serve niche compliance applications where parameter specificity outweighs flexibility requirements.
- Probe:Replacement-grade electrochemical probes for pH and dissolved oxygen constitute recurring revenue streams with predictable refresh cycles tied to reference electrode degradation.
Sensor hardware holds installed capacity. Analyzer systems are rotating up the share rankings.
Application:
Deployment contexts vary in measurement frequency, regulatory stringency, and integration complexity—factors that reshape pricing power across the application map.
- Wastewater Treatment:Continuous discharge monitoring mandates from China's MEE and the United States EPA drive real-time analyzer installations at municipal and industrial facilities. Biological nutrient removal optimization adds dissolved oxygen and nitrate sensor density beyond compliance minimums.
- Drinking Water:Distribution network monitoring for disinfectant residuals, turbidity, and emerging contaminants requires sensor redundancy that multiplies hardware counts per treatment plant. The EU Drinking Water Directive revision tightens thresholds for PFAS and microplastics in Germany, France, and the Netherlands.
- Industrial Processes:Boiler water, cooling tower, and ultrapure water applications in semiconductor and pharmaceutical manufacturing demand resistivity and silica analyzers with calibration traceability to pharmacopeia standards.
- Aquaculture:Dissolved oxygen and pH monitoring in intensive farming operations across Norway and Chile deploys wireless sensor networks with alarm thresholds tied to stock mortality risk.
Wastewater treatment absorbs the largest hardware volumes. Drinking water applications are climbing the fastest.
Technology:
Measurement principles diverge in capital intensity, operational expertise requirements, and susceptibility to interference—variables that segment vendor capabilities and customer switching costs.
- Electrochemical:Potentiometric and amperometric methods for pH, dissolved oxygen, and conductivity sustain the largest installed base through probe simplicity and field replaceability. Silver-silver chloride reference electrode supply concentration in East Asian processing facilities creates input cost volatility.
- Fluorometry:Excitation-emission detection for chlorophyll-a, phycocyanin, and emerging contaminant markers is displacing legacy methods in algal bloom and per- and polyfluoroalkyl substance applications. Surface water management agencies in the United States and China are expanding fluorometer procurement.
- Spectrophotometry:UV-Vis absorbance and colorimetric methods for nitrate, phosphate, and organic carbon face matrix interference limits in high-turbidity mining and pulp processing effluents.
- Chromatography:Ion chromatography and liquid chromatography-mass spectrometry configurations serve laboratory validation workflows where regulatory defensibility demands separation resolution beyond field-deployable methods.
Electrochemical technology holds installed capacity. Fluorometry is rotating up the share rankings.
End User:
Customer types differ in procurement authority, technical staffing, and compliance documentation requirements—factors that reshape sales channel economics and service contract structures.
- Government:Municipal utilities and environmental agencies in the United States, Germany, and China aggregate demand through cooperative purchasing and framework agreements that prioritize capital cost transparency over bundled lifecycle pricing.
- Environmental Testing:Commercial laboratories serving industrial discharge certification and drinking water compliance require analyzer throughput and multi-parameter flexibility that sustains premium equipment positioning.
- Agriculture:Irrigation water quality and nutrient runoff monitoring in water-stressed regions deploys lower-cost sensor networks with simplified calibration protocols suited to seasonal deployment patterns.
- Research Institutes:Academic and government research facilities drive early adoption of emerging detection methods including microfluidic sample handling and blockchain-secured data verification.
Government accounts hold installed capacity. Environmental testing laboratories are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in water quality monitoring hardware tilt toward net importing in emerging markets while Germany, the United States, and Japan maintain trade surpluses in high-specification analyzers. Equipment flows concentrate through Rotterdam, Singapore, and Shanghai as regional redistribution hubs for sensor networks and calibration standards.
United States
Municipal utilities in Texas and California are deploying dissolved oxygen sensor networks at wastewater treatment plants to meet biological nutrient removal mandates. The EPA enforces Clean Water Act monitoring requirements that drive capital expenditure on automated sampling stations. Industrial facilities along the Gulf Coast are installing real-time discharge monitoring to satisfy NPDES permit conditions.
Germany
Water utilities in North Rhine-Westphalia and Bavaria are upgrading distribution network monitoring density to comply with tightened EU Drinking Water Directive thresholds for PFAS and microplastics. The Federal Environment Agency certifies equipment under the DIN standard framework. Chemical manufacturers in Ludwigshafen and Leverkusen face expanded REACH monitoring obligations for industrial effluent.
China
Provincial environmental bureaus in Jiangsu and Zhejiang provinces mandate real-time discharge monitoring for chemical and textile facilities. The Ministry of Ecology and Environment implements surface water quality standards that compel continuous analyzer installations. Municipal governments in the Yangtze River Delta are expanding sensor procurement under smart city infrastructure programs.
India
The AMRUT 2.0 urban infrastructure scheme creates procurement channels for distributed sensor networks in water-stressed municipalities across Maharashtra and Tamil Nadu. The Central Pollution Control Board enforces effluent discharge standards that pull continuous monitoring adoption. Industrial clusters in Gujarat and Karnataka are installing multi-parameter analyzers to satisfy state pollution control board consent conditions.
Japan
Semiconductor and pharmaceutical manufacturers in Kansai and Chubu regions demand resistivity and silica analyzers with calibration traceability to pharmacopeia standards. METI promotes IoT integration in water infrastructure through subsidy programs for municipal utilities. Aquaculture operations in Kyushu deploy wireless dissolved oxygen sensor networks with alarm thresholds tied to stock mortality risk.
Global Water Quality Monitoring Market Competitive Environment
Listed leaders compete with private specialists across certification breadth and service contract structures. The vendor base stratifies into three tiers: diversified instrumentation conglomerates with captive sensor manufacturing, specialized electrochemical probe fabricators, and third-party validation laboratories with geographic coverage advantages. Consolidation pressure operates through vertical acquisition of calibration service providers and technology licensing agreements for fluorometry detection methods.
Within the diversified instrumentation tier, Xylem Inc. and Danaher Corporation exemplify contrasting strategic positions—Xylem through backward integration into sensor manufacturing and digital platforms, Danaher through specialized electrochemical probe lines that anchor laboratory calibration workflows. Bureau Veritas SA occupies a position in the third-party validation segment, extending certification services across European and Asia-Pacific industrial clients. Thermo Fisher Scientific Inc. represents the laboratory-grade analyzer archetype with chromatography and mass spectrometry configurations.
| Leading Market Players |
|---|
| Intertek Group plc |
| Xylem Inc. |
| Eurofins Scientific SE |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| SGS SA |
| ALS Limited |
| HORIBA, Ltd. |
| Bureau Veritas SA |
| Others |
Value Chain & Pricing Dynamics
EPA Clean Water Act certification requirements and EU Drinking Water Directive compliance tiers simultaneously gate supplier qualification and stratify price positioning across sensor and analyzer procurement. Municipal utilities in Germany and the United States face dual pressure from tightening contaminant thresholds and reference electrode supply volatility, compressing margin structures while elevating premium-tier positioning for multi-parameter systems with embedded predictive analytics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium positioning commands multiples through chromatography modules and blockchain-secured data verification that environmental testing laboratories require for regulatory defensibility. Price differentiation hinges on ISO/IEC 17025 calibration certification and software integration depth. Cost compression in economy-tier single-parameter probes is intensifying because silver-silver chloride component volatility feeds through East Asian supply chains. Municipal government accounts exhibit highest price sensitivity through GSA schedule purchasing and cooperative buying organizations, while semiconductor manufacturers in Japan and pharmaceutical facilities in Germany demonstrate lowest sensitivity due to pharmacopeia traceability mandates.
Supply Chain Analysis
Port congestion on Rotterdam-Singapore trade lanes elevates inbound logistics costs for analyzer systems requiring climate-controlled transport of optical detection modules. Manufacturing concentrates in Germany for high-specification electrochemical probes, in Japan for precision fluorometry components, and in China for solid-state sensor volume production. Silver-silver chloride reference electrodes and specialized optical gratings draw from concentrated East Asian processing facilities. Single-source vulnerability in rare-earth-doped optical fiber supply creates exposure to export restriction shocks. Distribution runs through environmental testing laboratories and municipal procurement frameworks that unbundle hardware from decade-long service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-to-cloud platform economics are compressing the addressable gap between field-deployable probes and laboratory-grade analyzers, with IoT-integrated systems rewriting procurement criteria through predictive analytics bundling.
For Market Incumbents: Shield installed base erosion by embedding edge computing capabilities into legacy probe architectures before brownfield utilities face SCADA protocol mismatches. Deepen backward integration into silver-silver chloride reference electrode production to offset East Asian supply volatility. Prioritize certification investment for PFAS fluorometry detection ahead of standardized method adoption. For New Entrants and Emerging Players: Lead with blockchain-secured data verification modules that address emerging tamper-proof compliance documentation requirements in cross-border supply chains. Target India's AMRUT 2.0 urban infrastructure scheme for distributed sensor network deployment across Maharashtra and Tamil Nadu municipalities. Pursue direct procurement relationships with provincial environmental bureaus in China's Jiangsu and Zhejiang industrial corridors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable microfluidic analyzer configurations as miniaturization collapses benchtop-to-handheld cost structures. Acquisition candidates include specialized electrochemical probe fabricators with DIN standard certification and third-party validation laboratories with Asia-Pacific geographic coverage. Monitor fluorometry patent filing velocity as inflection indicator for emerging contaminant detection platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Xylem's captive production of electrochemical probes controls deployment costs for North American municipal accounts. |
| Blockchain-Secured Data Verification | Distributed ledger integration addresses tamper-proof compliance requirements in REACH-regulated European supply chains. |
| Fluorometry Platform Expansion | Specialized excitation-emission detection systems command premium positioning in PFAS and algal bloom monitoring applications. |
| Third-Party Validation Laboratory Acquisition | Bureau Veritas extends certification services across Asia-Pacific industrial clients through geographic coverage expansion. |
| Microfluidic Sample Handling Miniaturization | Portable multi-parameter configurations compress the market gap between laboratory precision and single-parameter probe simplicity. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal utility procurement directors, environmental testing laboratory managers, industrial facility compliance officers, and sensor manufacturing plant engineers. Secondary validation drew from EPA enforcement databases, ECHA REACH substance registrations, China's MEE surface water quality standard filings, and DIN equipment certification records. Bottom-up unit economics across sensor, analyzer, and detector product lines were triangulated against top-down market sizing derived from municipal capital expenditure disclosures and industrial discharge permit monitoring mandates.
Across the analysis window, volume and value outputs reflect segmentation modeling by product type, application context, measurement technology, and end-user procurement authority. CAGRs were derived from regression analysis against regulatory enforcement intensity indices and sensor network deployment density metrics. Industry-specific forecast inputs include provincial environmental bureau permit issuance rates in China and cooperative purchasing organization aggregation patterns across United States state lines.
Forecasts assume regulatory continuity in EPA Clean Water Act enforcement, EU Drinking Water Directive threshold schedules, and China's MEE surface water quality standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Europe Air Quality Monitoring Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
India Cloud Seeding Market
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
Water Quality Monitoring Systems Market