
 Municipal Water Market | 2026-2036
Municipal Water Market Size, Share, and Industry Trends Forecast 2026-2036
Municipal Water Market Analysis
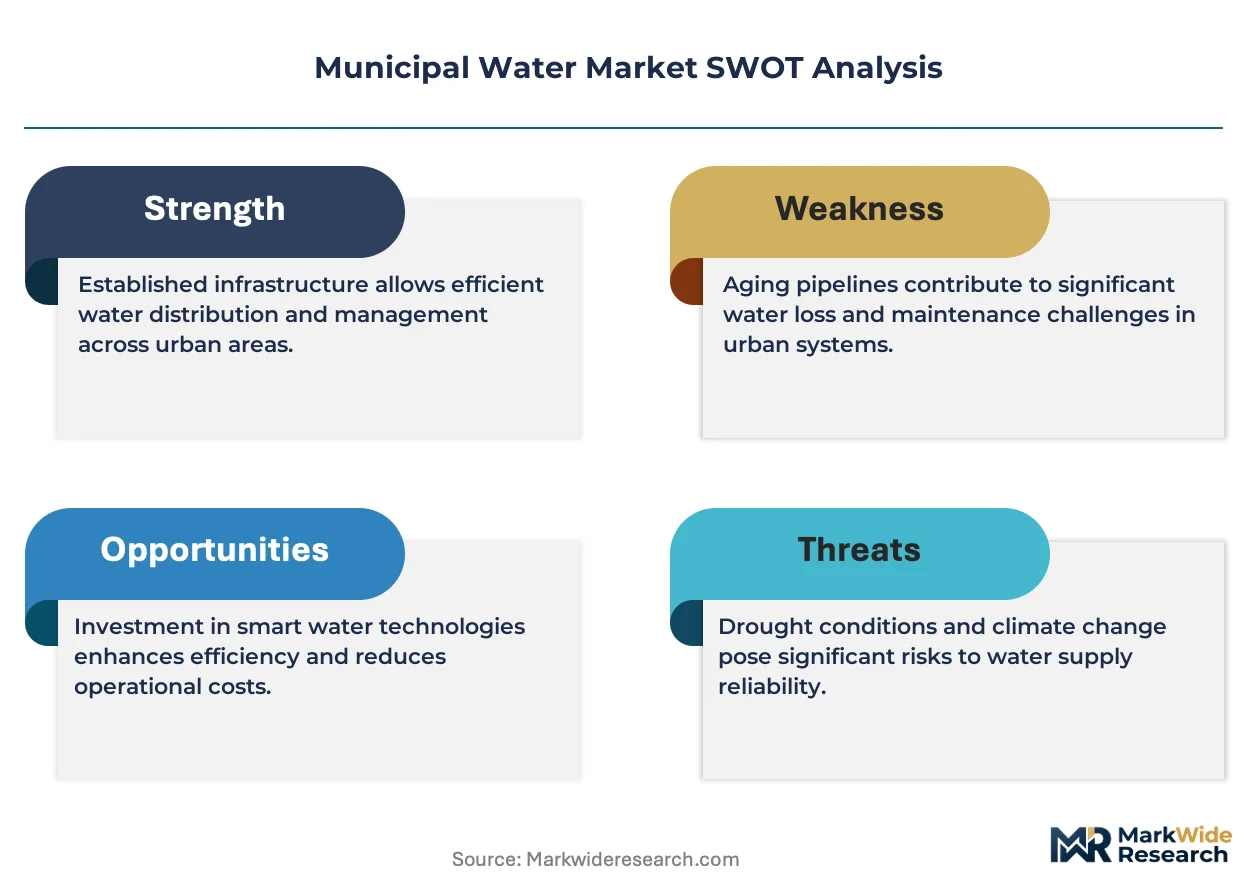
Concession-based project finance is tilting competitive dynamics toward operators with balance-sheet capacity for long-dated infrastructure assets. American Water Works Company leverages its scale across regulated jurisdictions to sustain capital deployment advantages. Essential Utilities anchors multi-state water and wastewater platforms through disciplined rate-base growth. SJW Group competes in California's constrained regulatory environment with focused operational excellence.
Municipal water encompasses the collection, treatment, storage, and distribution of potable water to urban populations through networked infrastructure operating at pressures typically between 30 and 80 psi. The primary purpose is safeguarding public health while delivering reliable volumes for residential, commercial, and fire-suppression demand. Water Treatment commands the largest share of service-type revenue as aging plants require upgrade cycles. Reverse Osmosis leads technology deployment for brackish and seawater desalination applications where conventional filtration proves insufficient. Distribution networks represent the most capital-intensive segment with buried pipe replacement cycles spanning 75 to 100 years.
EPA enforces Maximum Contaminant Levels under the Safe Drinking Water Act, compelling utilities to invest in advanced treatment and monitoring infrastructure. State public utility commissions set allowed returns on rate base, directly shaping investor-owned utility profitability and reinvestment capacity. ISO water management standards and AWWA guidelines influence procurement specifications for treatment equipment and pipeline materials. Stakeholders must track how emerging PFAS regulations reshape treatment technology selection and capital planning horizons.
Market Dynamics
EPA Lead and Copper Rule revisions are compelling utilities to accelerate buried pipe replacement cycles and deploy continuous monitoring infrastructure across aging distribution networks.
Growth Catalysts
- Smart Meter Mandates:Utilities in California and Texas are deploying AMI infrastructure to reduce non-revenue water losses. Real-time pressure management systems cut burst frequency by enabling predictive maintenance scheduling.
- PFAS Treatment Requirements:The EPA's proposed Maximum Contaminant Levels for per- and polyfluoroalkyl substances force activated carbon and ion exchange upgrades. Municipalities in Michigan and New Jersey front-load capital for compliance deadlines.
- Seawater Desalination Expansion:Reverse osmosis membrane improvements reduce energy intensity for coastal utilities. Plants in San Diego County and Tampa Bay demonstrate bankable project economics for inland brackish applications.
Market Restraints
- Polymer Supply Concentration:Specialty membrane polymers depend on petrochemical feedstocks concentrated in Gulf Coast refineries. Price volatility in propylene derivatives compresses equipment margins.
- Rate Case Friction:State public utility commissions in New York and Illinois impose multi-year rate freeze conditions. Allowed return compression limits reinvestment capacity for investor-owned utilities.
- Technical Limitation:Conventional coagulation fails for trace contaminant removal at low temperatures. Cold-climate utilities face seasonal treatment performance gaps requiring backup oxidation capacity.
Strategic Opportunities
- India Urban Sanitation:The Jal Jeevan Mission and AMRUT 2.0 schemes fund wastewater treatment plants for tier-2 cities. Build-operate-transfer structures attract private capital to underpenetrated state markets.
- Digital Twin Convergence:Hydraulic modeling software integrates with SCADA sensor networks. Singapore's PUB demonstrates operational optimization through virtual network replication.
- Green Bond Financing:Certified climate-aligned instruments reduce cost of capital for efficiency retrofits. European Investment Bank frameworks validate sustainability credentials for institutional investors.
Industry Challenges
- Certified Operator Scarcity:State licensing boards report 30% vacancy rates for Class A treatment plant operators. Retirement waves in the Midwest and Northeast outpace apprenticeship pipeline capacity.
- Legacy SCADA Integration:Proprietary protocols from 1990s-era control systems obstruct cloud analytics deployment. Cybersecurity hardening requires parallel infrastructure investment without operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Municipal Water Market |
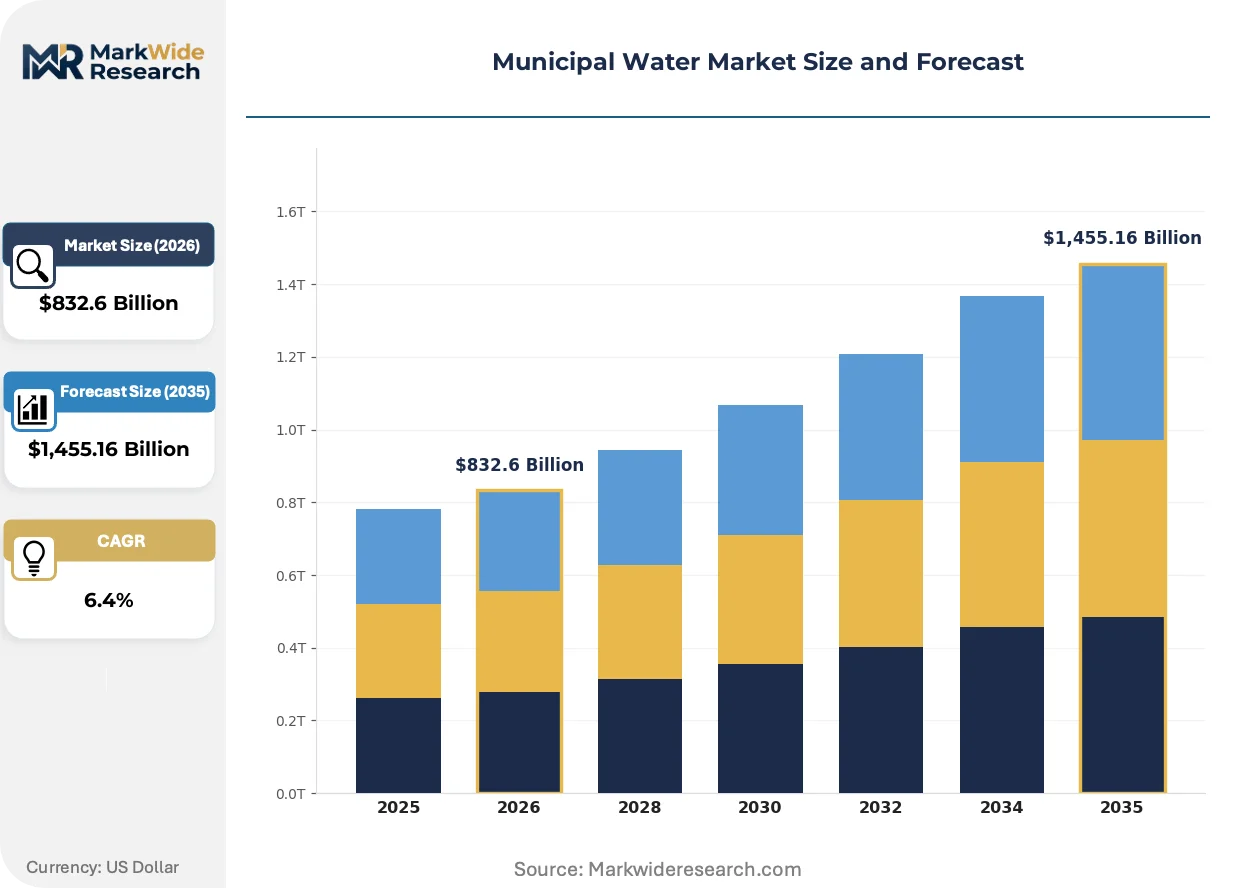
| Market Size in 2026 | $832.6 Billion |
| Market Size in 2035 | $1,455.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Water Treatment, Wastewater Management, Distribution, Monitoring Systems Technology: Reverse Osmosis, Filtration, UV Treatment, Chlorination Application: Residential Supply, Industrial Supply, Agricultural Irrigation, Recreational Use End User: Municipalities, Utility Companies, Government Agencies, Water Boards |
| Companies Covered | California Water Service Group, Middlesex Water Company, American Water Works Company, Artesian Resources Corporation, York Water Company, Essential Utilities, SJW Group, Consolidated Water Co, American States Water Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Municipal Water Market Emerging Trajectories
Digital infrastructure is compressing operational response times while regulatory stringency redefines treatment technology selection criteria across utility procurement cycles.
Digital twin platforms are virtualizing hydraulic network management by creating real-time simulation replicas of distribution infrastructure. Metropolitan utilities in Copenhagen and Melbourne deploy these systems to model pressure transients and optimize pump scheduling. The technology is virtualizing capital planning by reducing physical pilot project requirements.
REACH restrictions on perfluorinated substances are accelerating membrane material substitution in European treatment equipment procurement. Manufacturers reformulate polymer chemistry to maintain performance without restricted compounds. German and Dutch utilities now specify PFAS-free certification in tender documentation.
Performance-based service contracts are displacing equipment-only procurement for municipal treatment plants. French and British water companies bundle chemical supply with guaranteed output quality metrics. This model concentrates vendor risk while transferring operational expertise to specialized service providers.
Municipal Water Market Segmentation
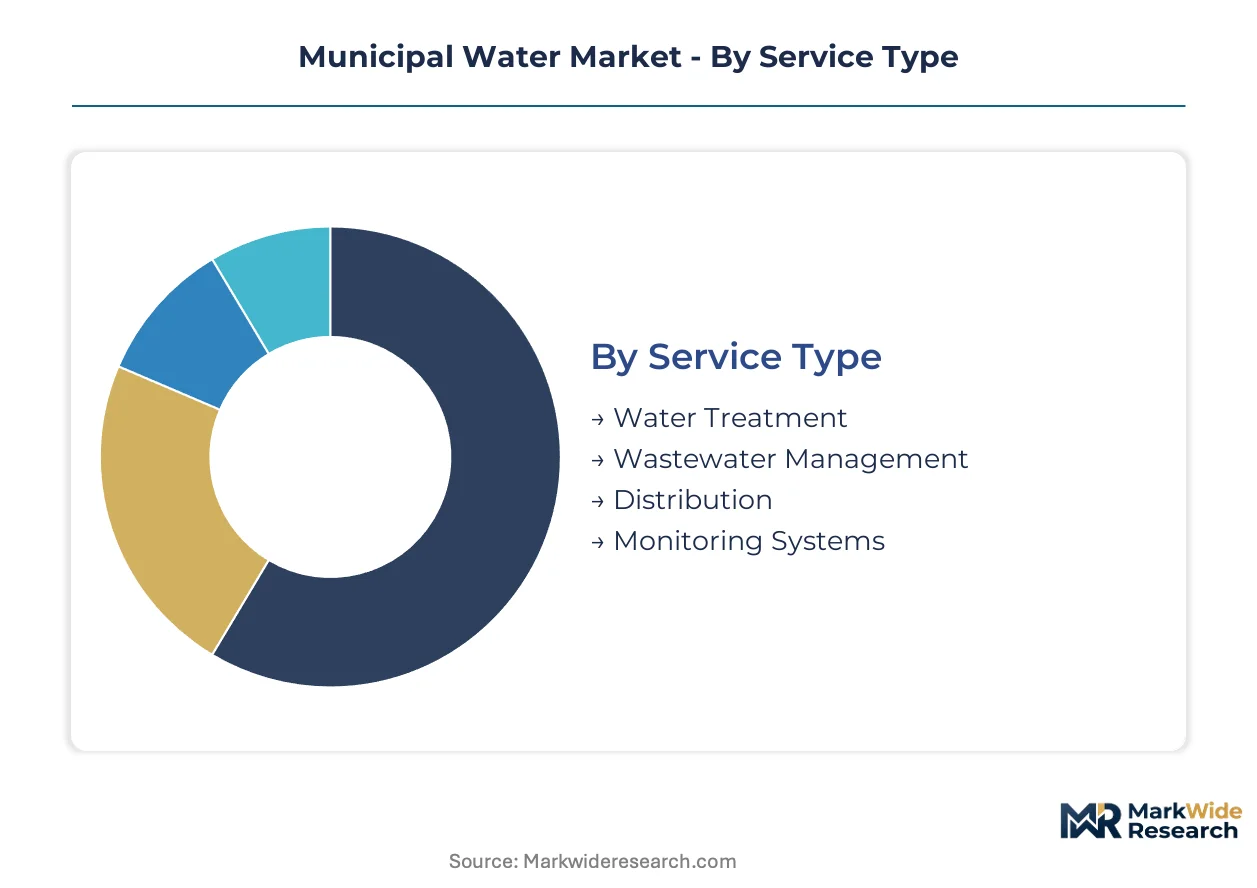
Municipal water infrastructure investment flows through distinct procurement channels shaped by regulatory mandates, technology maturity, and balance-sheet capacity. Understanding segment boundaries clarifies where capital deployment concentrates and which service models capture rate-base growth.
Service Type:
Utilities deploy capital across the full operational spectrum from source to tap, with spending priorities shifting between treatment upgrades and network renewal cycles.
- Water Treatment:Physical and chemical processes remove contaminants to meet EPA Maximum Contaminant Levels. Plants in Michigan and New Jersey front-load activated carbon and ion exchange upgrades for emerging PFAS compliance deadlines.
- Wastewater Management:Collection, biological processing, and effluent discharge systems serve urban sanitation requirements. India's Jal Jeevan Mission and AMRUT 2.0 schemes fund build-operate-transfer structures for tier-2 cities with underpenetrated sewer networks.
- Distribution:Pressurized pipe networks deliver potable water at 30-80 psi across buried infrastructure with 75-100 year replacement cycles. California and Texas utilities accelerate AMI deployment to cut non-revenue losses.
- Monitoring Systems:SCADA networks, pressure sensors, and quality probes enable real-time network visibility. Legacy proprietary protocols from 1990s-era installations obstruct cloud analytics deployment without parallel cybersecurity hardening.
The dominant share belongs to Water Treatment, while Wastewater Management is closing the gap fastest.
Technology:
Process selection hinges on source water chemistry, energy economics, and contaminant target profiles.
- Reverse Osmosis:Semi-permeable membranes force water against osmotic pressure to desalinate brackish and seawater sources. San Diego County and Tampa Bay demonstrate bankable project economics that extend membrane applications inland.
- Filtration:Granular media and membrane configurations remove suspended solids across conventional treatment trains. REACH restrictions on perfluorinated substances accelerate polymer reformulation for European procurement.
- UV Treatment:Germicidal irradiation inactivates pathogens without chemical residuals. Cold-climate utilities pair UV with backup oxidation capacity where low temperatures degrade coagulation performance.
- Chlorination:Disinfection chemistry maintains distribution system residuals against bacterial regrowth. Legacy dosing infrastructure requires automation upgrades to meet continuous monitoring mandates.
Reverse Osmosis commands the premium technology tier, though UV Treatment is expanding most quickly as secondary disinfection requirements tighten.
Application:
Demand intensity varies by user category, with residential volumes anchoring base load and industrial quality specifications driving treatment complexity.
- Residential Supply:Potable water delivery for household consumption and fire protection dominates volume throughput. EPA Lead and Copper Rule revisions compel utilities to accelerate buried service line replacement.
- Industrial Supply:Process water with customized purity grades serves manufacturing and power generation. Semiconductor fabrication and pharmaceutical production impose ultrapure specifications that cascade treatment train requirements.
- Agricultural Irrigation:Non-potable water for crop production tolerates higher salinity and suspended solids. Reclaimed wastewater discharge permits expand source availability in water-stressed regions.
- Recreational Use:Golf course irrigation and aesthetic water features consume treated supplies with lower stringency than potable standards. Seasonal demand patterns strain distribution capacity during peak summer months.
Residential Supply absorbs the majority of capital deployment, yet Industrial Supply generates the steepest margin expansion for advanced treatment providers.
End User:
Procurement authority fragments across governance structures with divergent financing constraints and regulatory oversight.
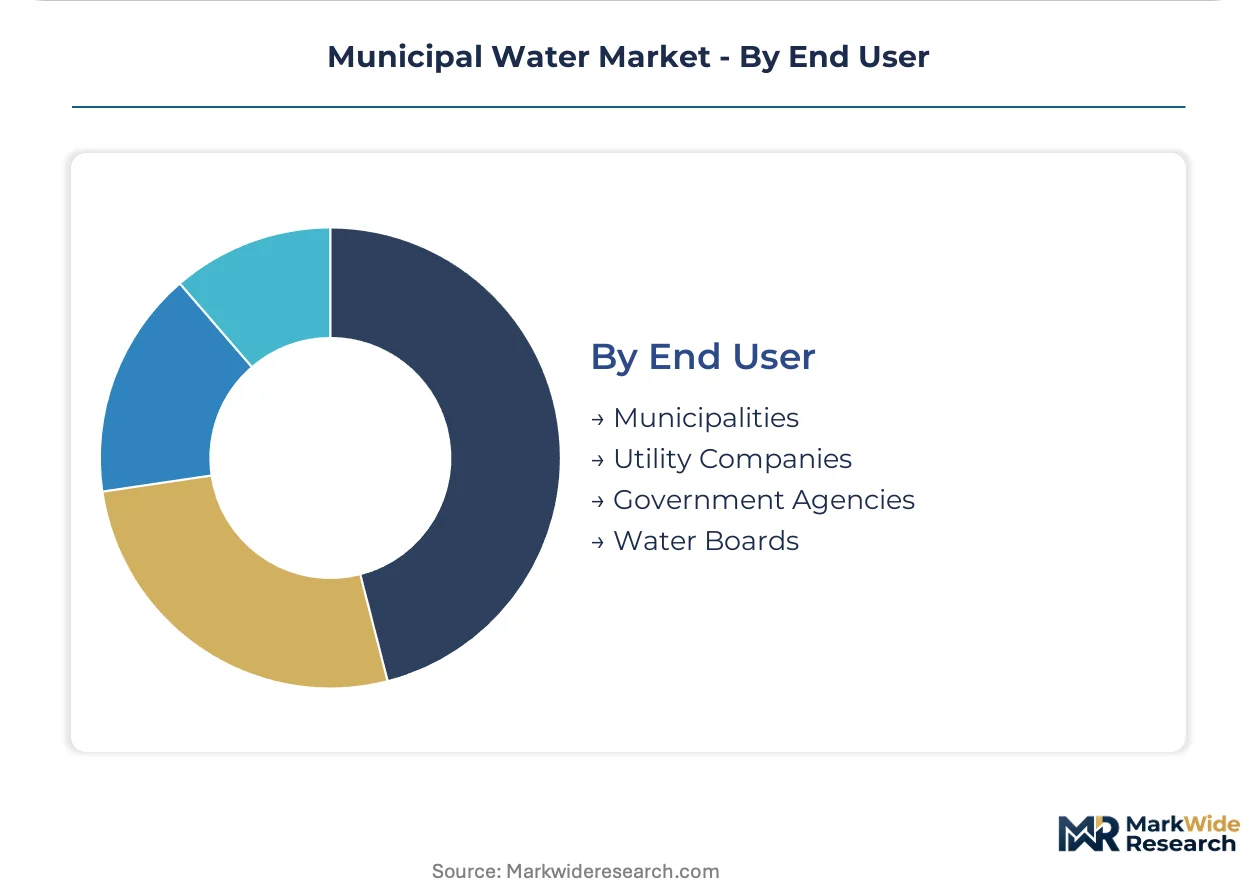
- Municipalities:City and county governments own infrastructure assets and set retail rate structures. State public utility commissions in New York and Illinois impose multi-year rate freezes that compress reinvestment capacity.
- Utility Companies:Investor-owned operators deploy capital across regulated jurisdictions with allowed returns on rate base. American Water Works and Essential Utilities leverage multi-state scale for procurement advantages.
- Government Agencies:Federal and state environmental departments fund grants and administer compliance deadlines. EPA enforcement of Safe Drinking Water Act standards shapes capital planning horizons.
- Water Boards:Special-purpose districts manage regional systems with dedicated tax or rate authority. California's constrained regulatory environment rewards focused operational excellence for specialized operators.
Municipalities retain the largest installed asset base, while Utility Companies are gaining share fastest through consolidation and concession-based project finance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States utilities capture pricing premiums through rate-base mechanisms while Indian municipalities absorb cost compression under federal subsidy programs. This asymmetry reshapes capital deployment patterns across treatment technology procurement cycles.
United States
EPA Lead and Copper Rule revisions drive buried pipe replacement cycles exceeding 75-year historical norms. State public utility commissions in California and Texas authorize AMI infrastructure deployment through rate-case mechanisms. Metropolitan utilities in San Diego County and Tampa Bay demonstrate bankable reverse osmosis economics for inland brackish applications.
China
Urbanization intensifies demand for wastewater treatment services in tier-2 cities across the Yangtze River Delta. MEE enforcement of dual carbon goals compels membrane technology upgrades at municipal plants. Shanghai and Beijing municipal water bureaus pilot digital twin platforms for hydraulic network optimization.
India
Jal Jeevan Mission and AMRUT 2.0 schemes fund build-operate-transfer structures for underpenetrated state markets. Central government subsidy programs compress capital recovery timelines for private operators. Tier-2 cities in Maharashtra and Gujarat attract concession-based project finance for treatment plant expansion.
Germany
REACH restrictions on perfluorinated substances accelerate membrane material substitution in treatment equipment procurement. ECHA compliance deadlines force polymer reformulation without restricted compounds. Utilities in the Ruhr industrial cluster specify PFAS-free certification in tender documentation for plant retrofits.
Singapore
PUB's digital twin deployment demonstrates operational optimization through virtual network replication. National water agency mandates integrate SCADA sensor networks with hydraulic modeling software. The city-state's NEWater facilities anchor membrane technology advancement for municipal reuse applications.
Municipal Water Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying membranes, sensors, and chemical feed systems to treatment plant operators. The vendor base organizes around three strategic archetypes: multi-state regulated utilities with rate-base scale, regional water boards with dedicated tax authority, and specialized technology providers bundling equipment with performance guarantees. Consolidation activity concentrates in concession-based project finance structures. Technology licensing agreements proliferate as European membrane manufacturers seek distribution channels in Asian growth markets.
Within the multi-state utility tier, American Water Works Company and Essential Utilities occupy positions defined by regulated jurisdiction scale. California Water Service Group exemplifies the regional specialist archetype operating within constrained state regulatory environments. SJW Group anchors operational excellence positioning in markets where rate-case friction limits reinvestment flexibility. These named entities represent competitive positioning patterns rather than definitive market share claims.
| Leading Market Players |
|---|
| California Water Service Group |
| Middlesex Water Company |
| American Water Works Company |
| Artesian Resources Corporation |
| York Water Company |
| Essential Utilities |
| SJW Group |
| Consolidated Water Co |
| American States Water Company |
| Others |
Supply Flow & Price Mechanics
Gulf Coast petrochemical clusters anchor specialty polymer supply for membrane manufacturing, concentrating upstream pricing power among propylene derivative producers while downstream utilities face cost pass-through pressure on treatment equipment procurement.
Pricing Analysis
The customization-premium spread separates configured-to-order membrane systems from standard filtration skids by 40-60 percent, with project-based contracting dominating municipal procurement. Price differentiation hinges on certification tier—NSF/ANSI 61 compliance commands premiums over basic AWWA specifications—and geographic delivery cost to inland utilities far from coastal manufacturing hubs. Pricing pressure stems from rate-case friction in New York and Illinois, where multi-year freezes compress allowed returns and limit capital recovery flexibility. Municipalities exhibit highest price sensitivity due to tax-backed financing constraints, while investor-owned utilities absorb premiums for operational reliability guarantees.
Supply Chain Analysis
Export-control regimes on advanced ceramic membrane substrates limit technology flows from German and Japanese specialty materials producers to Chinese equipment assemblers, fragmenting procurement channels. Manufacturing concentrates in China for commodity polymer housings, Germany for precision-engineered membrane elements, and the United States for SCADA-integrated control systems. Raw material dependencies center on high-purity alumina feedstocks, fluoropolymer resins, and rare-earth catalysts for oxidation processes. Single-source vulnerability pervades the ion exchange resin tier, where two producers control 80 percent of specialty capacity. Distribution runs through engineer-procure-construct contractors who bundle equipment with installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal water infrastructure is approaching a platform-economics inflection where digital twin interoperability—exemplified by Singapore PUB's SCADA-hydraulic model convergence—reshapes vendor competitive boundaries from equipment sales to outcome-based service ecosystems.
For Market Incumbents: Harden rate-base positions by accelerating AMI deployment in Texas and California before regulatory mandates crystallize, while securing backward integration into membrane polymer supply through offtake agreements with Gulf Coast refiners. Threat substitution looms from digital-native entrants bundling predictive analytics with hardware; certification investment in NSF/ANSI 61 and emerging PFAS compliance tiers provides defensive moats. For New Entrants and Emerging Players: Pursue tier-2 Indian cities under Jal Jeevan Mission subsidy windows where build-operate-transfer structures lower capital barriers and state-level competition remains fragmented. The most penetrable white space sits in Maharashtra and Gujarat wastewater treatment expansion, where European membrane technology licensing agreements enable rapid capability assembly without proprietary R&D. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded water technology divisions lacking scale for platform economics. Long-term viability over the coming decade favors operators with concession-based project finance expertise and digital infrastructure deployment capabilities. The signal to watch is EPA enforcement acceleration on PFAS Maximum Contaminant Levels, which would force accelerated capital cycles and consolidate procurement toward integrated service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Concession-Based Project Finance | Transfers construction risk to operators while municipalities retain asset ownership under EPA compliance deadlines. |
| Digital Twin Platform Integration | Virtual network replication reduces physical pilot requirements for hydraulic optimization in Copenhagen and Melbourne deployments. |
| Membrane Material Substitution | REACH-compliant polymer reformulation opens European procurement channels previously blocked by perfluorinated restrictions. |
| AMI Infrastructure Deployment | Real-time pressure management cuts burst frequency for California and Texas utilities facing non-revenue water mandates. |
| Green Bond Financing Certification | European Investment Bank frameworks reduce cost of capital for efficiency retrofits through climate-aligned instruments. |
Methodological Framework
Cross-validation between utility capital planning disclosures and equipment manufacturer order backlogs anchors the qualitative findings, combining primary interviews with municipal procurement officers, treatment plant operators, membrane technology R&D directors, and state public utility commission staff with secondary validation through EPA enforcement records, AWWA guideline documentation, and SEC 10-K filings from regulated water utilities. Bottom-up segmentation triangulation across service type, technology, application, and end-user dimensions converges with top-down macroeconomic drivers including urbanization rates and regulatory compliance timelines.
Calibration against historical capital expenditure patterns from American Water Works and Essential Utilities informs the projection framework, with segment-level modeling spanning water treatment, wastewater management, distribution networks, and monitoring systems across the analysis window. CAGRs derive from regression against population growth, pipe replacement cycle acceleration, and technology substitution curves for reverse osmosis versus conventional filtration. Industry-specific inputs include EPA Lead and Copper Rule revision implementation schedules and state-level rate-case approval velocities.
Sensitivities concentrate around PFAS regulatory finalization timing, polymer feedstock price volatility, and municipal bond market conditions affecting infrastructure finance availability. Forecasts reflect documented assumptions on compliance deadline adherence and technology cost curves. Material shifts in EPA enforcement posture or membrane energy economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
Middle East and Africa Water Sink Market
Water Management
NRW Smart Leak Management Market
Water Management
Global Water Market
Water Management
Water Free Urinals Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
North America Water Sink Market
Water Management
Water Utility Services Market
Water Management
Smart Water Network Market
Water Management
Water Filters Market
Water Management
Mexico Water Consumption Market
Water Management
Smart Water Management Market
Water Management
Water Trading Market
Water Management
Chile Water Consumption Market
Water Management
Asia-Pacific Water Sink Market
Water Management
Spain Water Consumption Market