
 Shower Water Filters Market | 2026-2036
Shower Water Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Shower Water Filters Market Insights
Consolidation among hospitality chains and health club operators is restructuring procurement patterns for shower water filtration systems. Aquasana leverages its direct-to-consumer channel strength to sustain recurring filter replacement revenue. Kohler anchors its position through built-in integration with premium fixture lines. Sprite Industries competes on specialized KDF media formulations for chlorine reduction.
Shower water filters are point-of-use treatment devices installed at shower outlets, typically employing activated carbon, KDF alloy, or calcium sulfite media to reduce chlorine, heavy metals, and scale-forming minerals through adsorption and redox reactions. Their primary purpose is to protect skin and respiratory health by removing disinfectant byproducts before water contact. Showerhead filters dominate residential installations due to minimal retrofit complexity, while inline systems capture commercial retrofits where plumbing access permits. Kinetic Degradation Fluxion technology leads in chlorine-specific applications, though activated carbon variants occupy broader contaminant removal. Reverse osmosis remains marginal in shower applications given flow rate constraints and wastewater ratios.
EPA Safe Drinking Water Act amendments and NSF/ANSI 177 certification requirements shape product legitimacy and channel access in the United States. The EU Drinking Water Directive and REACH chemical compliance frameworks govern material safety for European imports. Stakeholders must monitor evolving state-level PFAS maximum contaminant levels, as these emerging standards will force media formulation changes and testing protocol investments across manufacturing footprints.
Market Dynamics
Multi-stage filtration technology is rewriting procurement priorities as residential buyers in hard-water zones demand chlorine-specific performance validated by third-party certification. EPA amendments to shower water quality standards and tightening NSF/ANSI 177 requirements are forcing media formulation investments across manufacturing footprints.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:Tightening federal standards for disinfectant byproducts in municipal supplies push homeowners toward point-of-use filtration with certified chlorine reduction capabilities.
- Hospitality procurement consolidation:Merged hotel chains and health club operators are standardizing shower filtration specifications across property portfolios, creating volume contracts for inline system suppliers.
- Kinetic Degradation Fluxion media:Advanced KDF alloy formulations deliver superior redox reaction efficiency for chlorine removal, differentiating premium product tiers in competitive retail channels.
Market Restraints
- Activated carbon input volatility:Coconut shell carbon supply concentrates in Southeast Asian processing hubs, exposing filter manufacturers to freight cost swings and raw material availability constraints.
- Reverse osmosis flow limitations:Wastewater ratios and pressure requirements render RO technology structurally incompatible with residential shower applications, capping performance ceilings for high-purity demand segments.
- REACH compliance friction:ECHA chemical safety frameworks impose material testing burdens on European imports, extending product registration timelines and freezing channel access for non-compliant suppliers.
Strategic Opportunities
- PFAS MCL expansion:State-level maximum contaminant level rollouts for per- and polyfluoroalkyl substances will mandate media formulation upgrades, creating first-mover advantages for certified filter suppliers.
- Direct-to-consumer subscription channels:Recurring filter replacement revenue models bypass traditional retail markups, capturing lifetime value from digitally native residential buyers.
- Built-in fixture integration:Premium bathroom renovation cycles create openings for showerhead-filter combinations specified by architects and interior designers in upscale residential construction.
Industry Challenges
- NSF/ANSI 177 certification timelines:Third-party validation protocols for chlorine reduction claims require 6-12 month testing cycles, delaying product launches and compressing innovation-to-revenue windows.
- Retrofit installation skill gaps:Inline system deployment demands basic plumbing competence that many residential end-users lack, creating customer support burdens and return-rate risk for direct-sale channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shower Water Filters Market |
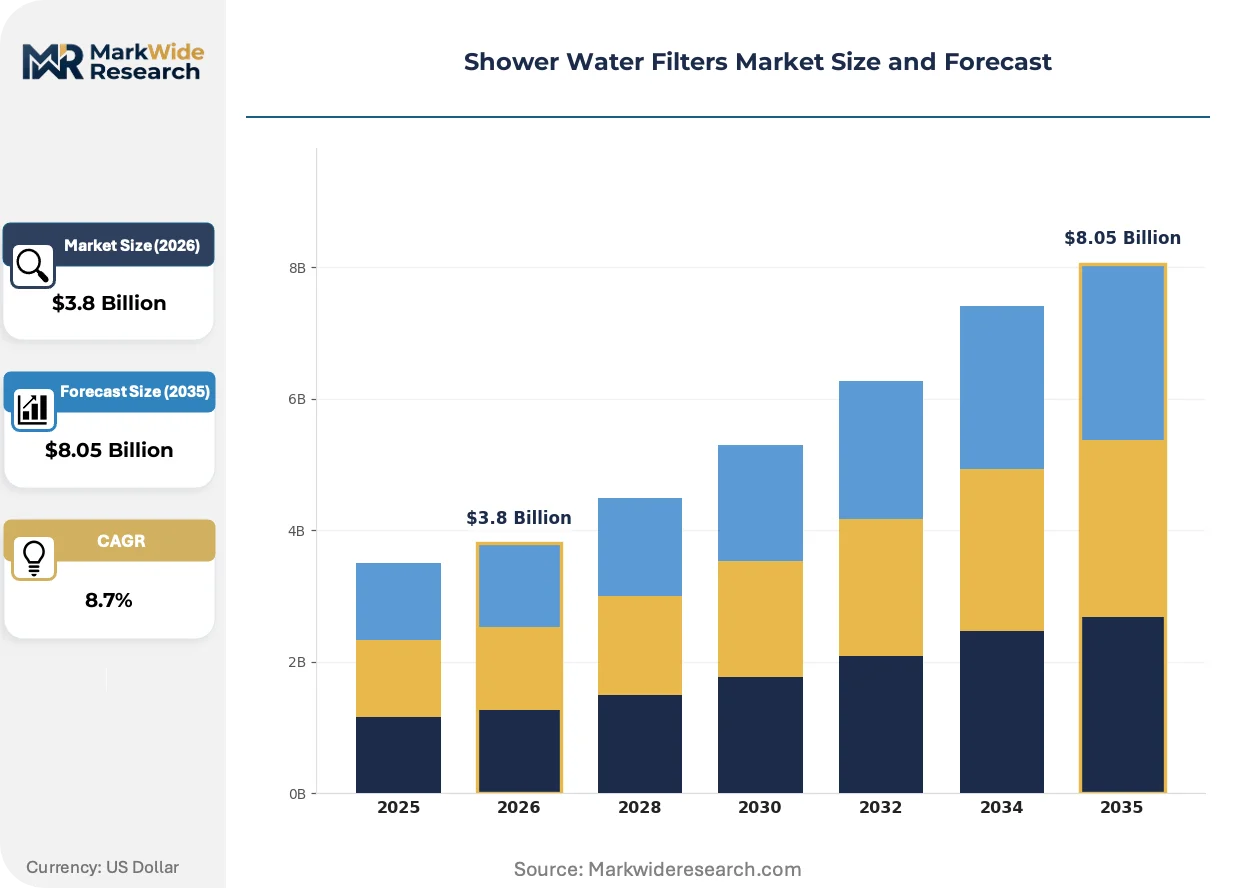
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Showerhead Filters, Inline Filters, Faucet Filters, System Filters Technology: Activated Carbon, Ion Exchange, Kinetic Degradation Fluxion, Reverse Osmosis Installation Type: Wall-Mounted, Portable, Countertop, Built-in End User: Residential, Commercial, Hospitality, Health Clubs |
| Companies Covered | Aquasana, Weddell, Jolie, Delta, Kohler, Sprite Industries, Multipure, Crystal Quest, AquaBliss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shower Water Filters Market Trends and Innovations
Calcium sulfite and ceramic ball media combinations are displacing single-stage carbon filters in performance-oriented residential segments. Manufacturers are embedding smart replacement indicators and consolidating control over recurring consumables revenue.
Calcium sulfite beads integrated with vitamin C infusion layers are rewriting performance expectations for skin-sensitive consumer segments. Dermatology clinics and wellness-focused hospitality operators are specifying these formulations for guest experience differentiation. The technology is compressing price premiums previously commanded by imported Japanese ceramic filters.
REACH and EU Drinking Water Directive amendments are tightening material safety documentation requirements for shower filter imports into European markets. Manufacturers must now submit full supply chain chemical inventories to ECHA portals before customs clearance. German and French distributors are demanding pre-certified product lines to avoid liability exposure.
After-sales service unbundling is fragmenting traditional wholesale relationships as residential buyers purchase filters through manufacturer websites and source replacements via subscription. Big-box home improvement retailers are responding with private-label filter lines to recapture attach revenue. This pattern is most visible in United States coastal metros where municipal water quality variability drives repeat purchase frequency.
Shower Water Filters Market Segmentation
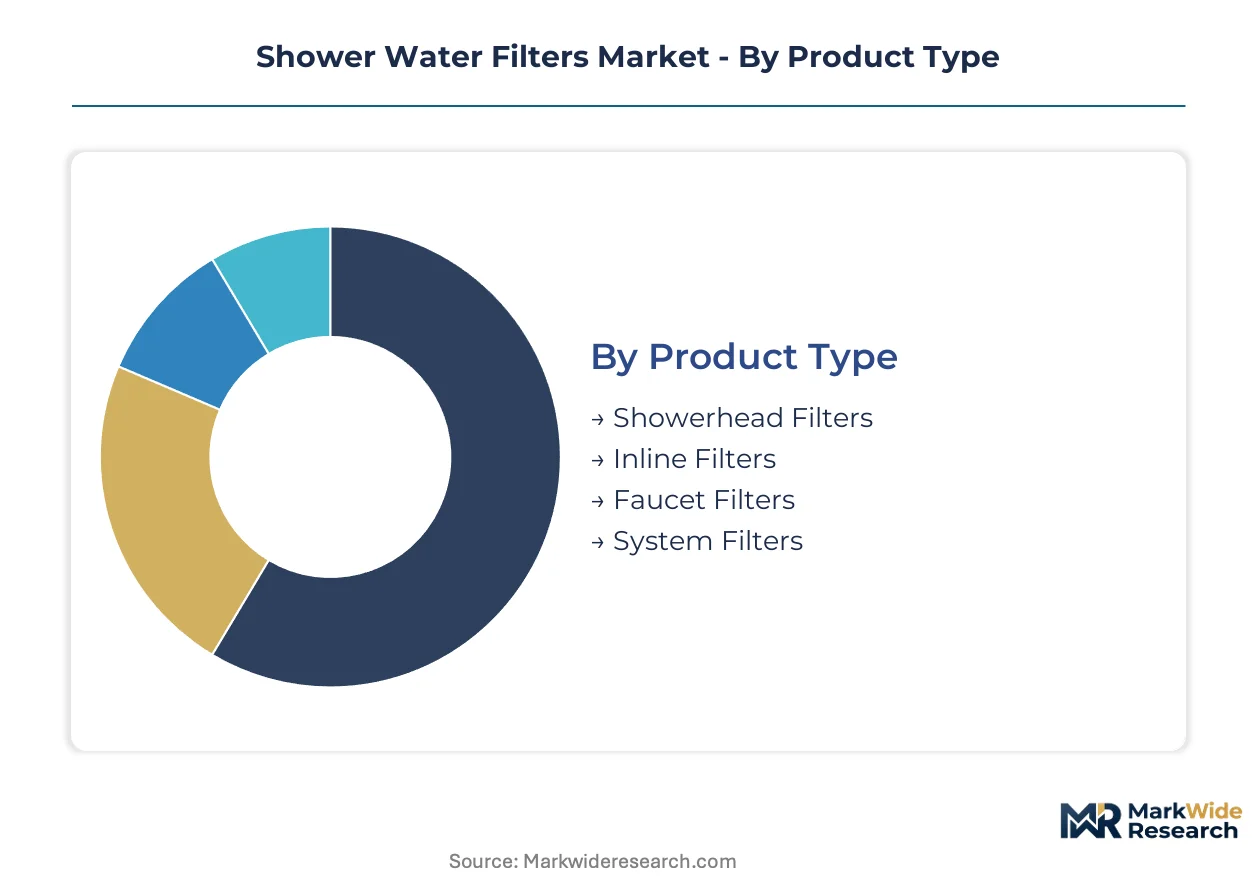
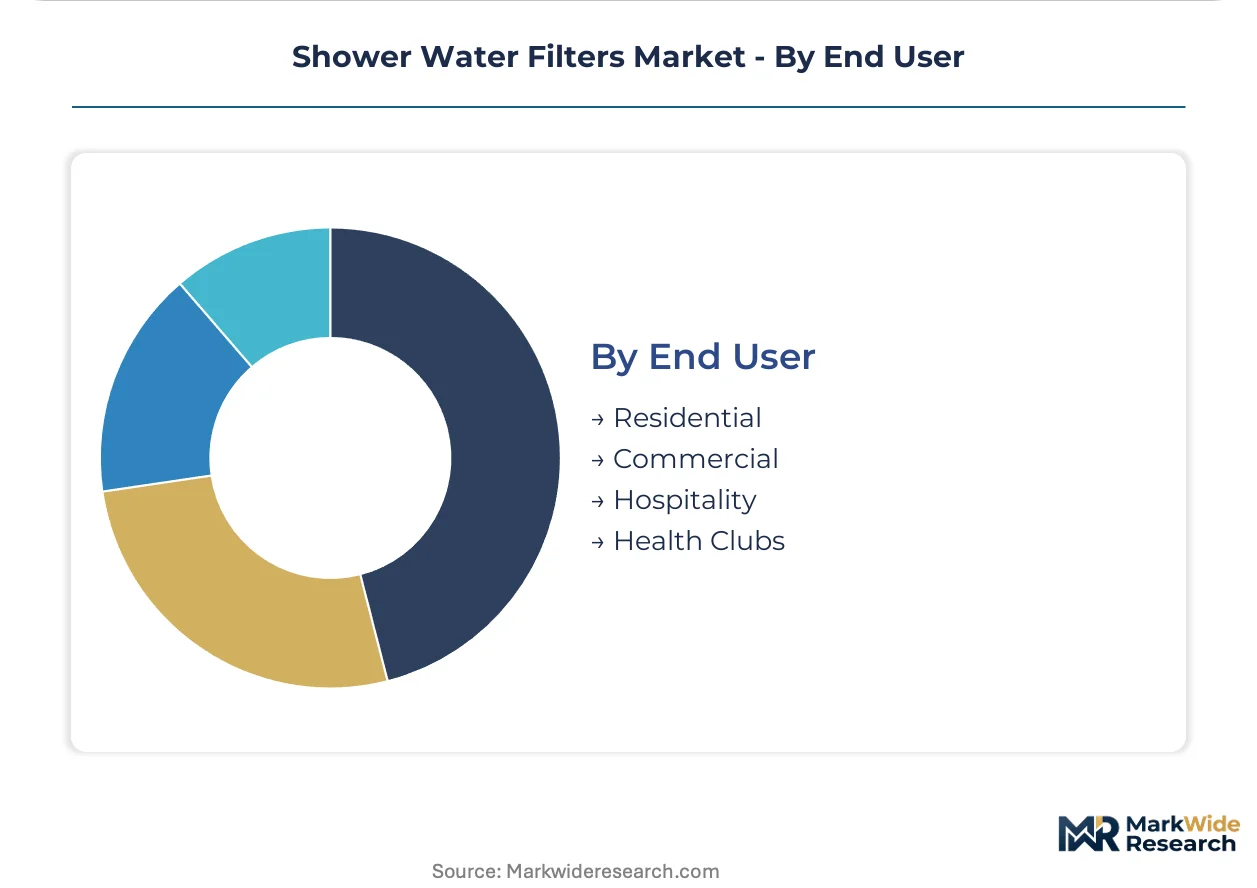
Shower water filter procurement patterns diverge sharply across technical specifications and installation contexts. Buyers prioritize chlorine reduction certification in hard-water municipalities while commercial operators negotiate volume contracts for inline retrofit systems.
Product Type:
Cost tier separates residential impulse purchases from engineered commercial installations requiring plumbing access.
- Showerhead Filters:These screw-on units integrate KDF alloy or calcium sulfite media directly into the showerhead housing, delivering 2.5 GPM flow rates without pressure loss. Demand clusters in United States suburban markets where EPA disinfectant byproduct concerns drive NSF/ANSI 177-certified purchases among homeowners avoiding plumbing modifications.
- Inline Filters:Cylindrical canister units install between shower arm and existing head, enabling multi-stage media stacks with replaceable cartridges. Hospitality chains and health club operators specify these for property-wide standardization, leveraging bulk procurement to reduce per-unit filter replacement costs across portfolio properties.
- Faucet Filters:Compact diverters attach to standard bathroom sink spouts for facial washing and oral care applications, typically employing activated carbon blocks rated for 100-gallon service life.
- System Filters:Whole-bathroom point-of-entry units treat all fixtures simultaneously, requiring professional installation and pressure tank integration in premium residential renovations.
Showerhead filters lead volumes today; inline systems are gaining share fastest among commercial retrofit projects.
Technology:
Application context determines media selection, with dermatological sensitivity and municipal water chemistry driving specification divergence.
- Activated Carbon:Coconut shell-derived carbon blocks adsorb chlorine, volatile organic compounds, and sediment through microporous surface area exceeding 1,000 square meters per gram. Residential buyers in chlorinated municipal systems favor this technology for its broad-spectrum contaminant removal and established third-party certification protocols.
- Kinetic Degradation Fluxion:Copper-zinc alloy media trigger redox reactions converting free chlorine to chloride ions while inhibiting bacterial growth within the filter bed. Wellness-focused hospitality operators specify KDF formulations for guest experience differentiation in competitive urban markets.
- Ion Exchange:Resin beads swap calcium and magnesium ions for sodium or potassium, softening water without salt-based whole-house systems.
- Reverse Osmosis:Semipermeable membrane technology remains structurally incompatible with shower applications due to 3:1 wastewater ratios and pressure requirements below typical residential line pressure.
KDF technology commands premium pricing today; activated carbon variants are expanding most quickly through mass retail channels.
Installation Type:
Customer plumbing competence and renovation cycle timing create distinct purchase moments across the category.
- Wall-Mounted:Fixed shower arm installations dominate residential replacement cycles, requiring only thread seal tape and hand-tightening for deployment.
- Portable:Handheld shower wands with integrated filtration suit rental properties and travel applications where permanent modification is prohibited.
- Countertop:Auxiliary units for bathtub filling and pet washing occupy niche positioning in multi-pet households.
- Built-in:Architect-specified filtration integrated during rough-in construction captures premium residential new-build and hospitality ground-up development, locking in proprietary cartridge formats for recurring revenue capture.
Wall-mounted units lead volumes today; built-in specifications are climbing the fastest among luxury bathroom renovation projects.
End User:
Volume scale and replacement frequency separate fragmented residential demand from consolidated commercial procurement.
- Residential:Individual homeowners purchase through direct-to-consumer channels and big-box retailers, generating recurring filter replacement revenue at 6-12 month intervals depending on household size and water hardness.
- Commercial:Property management firms and facility operators negotiate service contracts covering multiple units, prioritizing bulk cartridge pricing and standardized maintenance protocols across building portfolios.
- Hospitality:Hotel chains specify filtration as brand-standard amenities in wellness-focused property tiers, with procurement centralization at corporate level displacing individual property purchasing authority.
- Health Clubs:Fitness operators install filtration in high-traffic shower facilities to differentiate member experience and reduce dermatological complaints in chlorinated water markets.
Residential segments lead volumes today; hospitality procurement is gaining share fastest through chain consolidation and brand standardization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States homeowners purchase shower water filters at triple the per-capita rate of German consumers, though both markets prioritize NSF-certified chlorine reduction. Municipal water chemistry variability and dermatological health awareness create divergent adoption patterns across developed economies.
United States
EPA Safe Drinking Water Act amendments targeting disinfectant byproducts accelerate point-of-use filtration adoption in chlorinated municipal systems. The agency's tightening standards for trihalomethanes push manufacturers toward third-party NSF/ANSI 177 certification. Los Angeles and Phoenix metropolitan clusters concentrate demand where hard water and high chlorine residuals coincide.
Germany
REACH compliance requirements and ECHA chemical safety documentation burden filter imports from non-EU suppliers. The country's national plumbing regulator, DVGW, certifies products for potable water contact. Berlin and Munich renovation markets specify built-in filtration during premium bathroom retrofits.
Japan
Meti's energy efficiency guidelines and JIS standards for water quality appliances shape product specifications for domestic manufacturers. Tokyo and Osaka metropolitan areas drive demand for compact showerhead units in high-density residential construction. Vitamin C infusion technology commands price premiums in dermatology-adjacent retail channels.
China
GB standards for household water treatment devices and MEE environmental quality targets create compliance frameworks for domestic producers. Shanghai and Shenzhen manufacturing clusters supply activated carbon media to global filter assemblers. E-commerce platforms dominate distribution, bypassing traditional retail markups.
Australia
TGA therapeutic claims regulations and state-level plumbing codes govern filter installation permissions. Sydney and Melbourne coastal markets exhibit elevated sensitivity to chlorine exposure in shower environments. Wellness-focused hospitality operators specify KDF media formulations for guest experience differentiation.
Shower Water Filters Market Competitive Landscape
United States producers anchor one tier; German and Japanese specialists hold certification-advantaged positions in premium segments. The vendor base splits between mass-market showerhead assemblers and engineered inline system fabricators serving commercial property portfolios. Three archetypes dominate: direct-to-consumer subscription operators, built-in fixture integrators, and specialized media formulators. Consolidation among hospitality procurement departments and health club chains drives volume contracting, while residential channels fragment across big-box retail and manufacturer-direct e-commerce.
Among North American incumbents, Aquasana exemplifies the direct-to-consumer subscription archetype through recurring filter replacement revenue capture. Kohler occupies a position as the built-in fixture integrator, leveraging premium bathroom renovation cycles. Sprite Industries represents the specialized media formulation tier, with KDF alloy expertise differentiating chlorine-specific applications. These three anchors illustrate how competitive positioning stratifies across channel strategy rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Aquasana |
| Weddell |
| Jolie |
| Delta |
| Kohler |
| Sprite Industries |
| Multipure |
| Crystal Quest |
| AquaBliss |
| Others |
Pricing and Supply Chain Analysis
Hospitality procurement consolidation toward NSF/ANSI 177-certified inline systems forces manufacturers to absorb media formulation testing costs or cede volume contracts to certified rivals, compressing margins at the standard tier while premium KDF formulations retain pricing power.
Pricing Analysis
Capacity additions in China and Vietnam are reshaping price floors for activated carbon media, enabling mass-market showerhead assemblers to undercut legacy suppliers. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified KDF systems from uncertified carbon blocks and private-label imports. Pricing pressure stems from coconut shell carbon freight cost volatility and REACH compliance testing burdens on European-bound shipments. Residential direct-to-consumer buyers exhibit lowest price sensitivity for dermatologist-recommended formulations, while big-box retail channels drive cost compression through private-label sourcing.
Supply Chain Analysis
Direct-to-OEM channels handle hospitality chain volume demand, while manufacturer-direct e-commerce captures residential replacement cartridge revenue. Coconut shell carbon processing concentrates in Indonesia, Malaysia, and the Philippines, with copper-zinc KDF alloy production anchored in United States and German specialty foundries. Raw material dependencies include Southeast Asian carbon feedstock, copper-zinc alloy ingots, and calcium sulfite beads from Chinese chemical processors. Single-source vulnerability runs through Indonesian carbon processing hubs exposed to monsoon logistics disruptions. Distribution runs through big-box home improvement retailers, plumbing wholesalers, and subscription-direct channels in coastal United States metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as residential buyers in hard-water municipalities migrate toward multi-stage filtration with third-party chlorine reduction certification.
For Market Incumbents: Anticipate margin compression from private-label entrants by deepening backward integration into KDF alloy production and locking in hospitality volume contracts before procurement centralization completes. Certify next-generation media formulations against emerging state-level PFAS standards to defend channel access. Prioritize subscription platform investments to capture lifetime replacement revenue from digitally native homeowners. For New Entrants and Emerging Players: Begin with portable shower wand filtration for rental property segments where permanent installation is prohibited, leveraging minimal regulatory burden and impulse purchase dynamics. Target wellness-focused health club operators in chlorinated water markets with calcium sulfite and vitamin C infusion formulations. Pursue direct-to-consumer launch through dermatology clinic partnerships to bypass retail markup requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized media formulators holding KDF alloy expertise and pre-certified European product lines. Long-term viability hinges on regulatory compliance capabilities rather than manufacturing scale alone. Monitor state-level PFAS maximum contaminant level announcements as inflection signals for media formulation upgrade cycles and testing protocol investments.| Strategic Initiative | Industry Significance |
|---|---|
| NSF/ANSI 177 Certification Investment | Unlocks hospitality procurement contracts and validates chlorine reduction claims for liability-sensitive buyers. |
| Direct-to-Consumer Subscription Launch | Captures recurring filter replacement revenue and bypasses retail margin extraction in United States coastal metros. |
| Backward Integration into KDF Alloy Production | Secures copper-zinc media supply and differentiates premium tiers against carbon-only competitors. |
| PFAS-Compliant Media Formulation Development | Positions first-mover advantage as state-level maximum contaminant levels expand across United States jurisdictions. |
| Built-in Fixture Partnership with Premium Brands | Locks in proprietary cartridge formats during luxury bathroom renovation cycles for recurring revenue capture. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and Australia, with primary inputs from each market. The research combines structured interviews with shower filter brand managers, plumbing wholesale distributors, hospitality procurement directors, and dermatology clinic administrators with secondary validation from EPA regulatory filings, NSF certification databases, ECHA REACH registrations, and customs trade records. Bottom-up demand modeling triangulates against top-down market sizing across residential, commercial, hospitality, and health club end-use segments.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon. The analytical framework models showerhead, inline, faucet, and system filter product types; activated carbon, KDF, ion exchange, and reverse osmosis technologies; and wall-mounted, portable, countertop, and built-in installation configurations. CAGRs derive from segment-level growth rate blending adjusted for technology substitution effects and regulatory compliance timeline impacts. Industry-specific inputs include municipal water chemistry variability indices and hospitality chain consolidation tracking.
Several conditions sit outside the modeled scope, including catastrophic supply chain disruptions, abrupt tariff regime changes on Southeast Asian carbon imports, and technological breakthroughs enabling reverse osmosis feasibility in shower applications. Forecasts reflect documented assumptions regarding EPA amendment timelines and state-level PFAS standard adoption patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Zero Liquid Discharge Market