
 Asia-Pacific Water Purifier Market | 2026-2036
Asia-Pacific Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Water Purifier Market Outlook
The capability gap between membrane-in-house producers and outsourced assemblers is collapsing as Chinese contract manufacturers scale thin-film composite production. A.O. Smith Water Technologies sustains premium positioning through captive reverse osmosis membrane lines in Nanjing. Xiaomi Corporation leverages its IoT ecosystem to bundle purifiers with smart home dashboards, competing on data integration rather than filtration specs alone. Kent RO Systems anchors its India dominance through a dense direct-sales network spanning 500-plus district towns.
Asia-Pacific water purifiers are electromechanical appliances engineered to reduce total dissolved solids, microbial load, and chemical contaminants through pressure-driven membrane separation, UV photolysis, or adsorptive media, typically achieving potable water standards below 500 ppm TDS for household and commercial use. Reverse osmosis systems occupy the largest value share due to high replacement frequency of spiral-wound membranes and consumer willingness to pay for mineral-retention variants. Ultraviolet purifiers lead unit volumes in Southeast Asian markets where municipal chlorination leaves biological gaps, while activated carbon segments compete on taste improvement in Australia's chlorine-heavy reticulated supply.
India's BIS IS 10500 standards and China's GB/T 30307 national purifier specifications create divergent compliance burdens that fragment regional product portfolios. South Korea's MFDS drinking-water safety alerts and Japan's JIS S 3201 household appliance codes further tighten material-contact requirements for plastic housings and tubing. Stakeholders must monitor regulatory divergence between national certification regimes when configuring pan-Asia supply chains and service architectures.
Market Dynamics
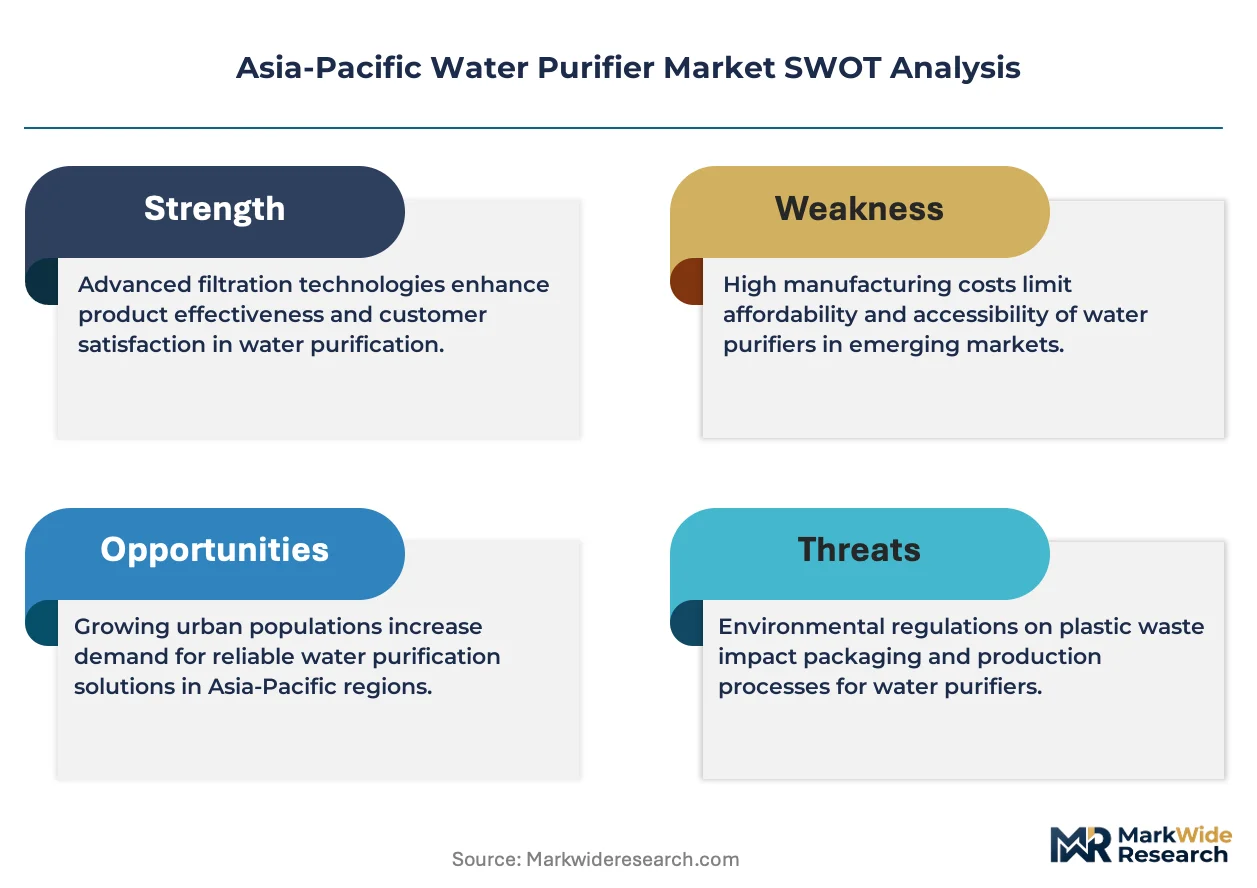
Thin-film composite membrane production is concentrating in Chinese contract manufacturing clusters, collapsing the capability gap that once separated integrated producers from outsourced assemblers and compressing margin structures across the value chain.
Growth Catalysts
- Groundwater contamination in tier-two Indian cities:Residential households in secondary urban centers face intensifying arsenic and fluoride pollution, accelerating RO system penetration where municipal infrastructure remains inadequate.
- China's GB/T 30307 national purifier specifications:Mandatory performance testing and material-contact requirements are forcing technology upgrades that expand the addressable market for certified systems.
- Municipal retrofit programs in the Yangtze River Delta:Shanghai and surrounding megacities are replacing aging distribution infrastructure, creating parallel demand for point-of-use protection during transition periods.
Market Restraints
- Spiral-wound membrane import dependency:High-performance thin-film composites rely on concentrated supply from Japanese and Korean substrate manufacturers, exposing assemblers to currency and logistics volatility.
- BIS IS 10500 compliance fragmentation:India's state-level enforcement variance creates product configuration complexity that raises inventory carrying costs for national distributors.
- Ultraviolet lamp mercury content regulations:South Korea's MFDS and Japan's METI are tightening restrictions on amalgam lamps, forcing costly LED-UV redesigns before economies of scale mature.
Strategic Opportunities
- Vietnam and Indonesia household penetration gaps:Under-15% installed base rates in Southeast Asian emerging markets offer first-mover positioning before municipal water quality improvements reduce urgency.
- IoT-enabled predictive maintenance bundles:Smart membrane life monitoring and automated filter reordering create recurring revenue streams that decouple profitability from hardware margins.
- India's PLI scheme for white goods components:Domestic manufacturing incentives for compressors and pumps support backward integration strategies that reduce landed cost disadvantages against Chinese imports.
Industry Challenges
- Thin-film composite polymer chemistry expertise scarcity:Interfacial polymerization process engineering requires specialized talent concentrated in Korean and Japanese materials science programs, constraining local R&D scale-up.
- Multi-jurisdiction certification pipeline congestion:Parallel BIS, GB, and JIS testing protocols extend product launch timelines by 8-14 months for pan-Asia portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Water Purifier Market |
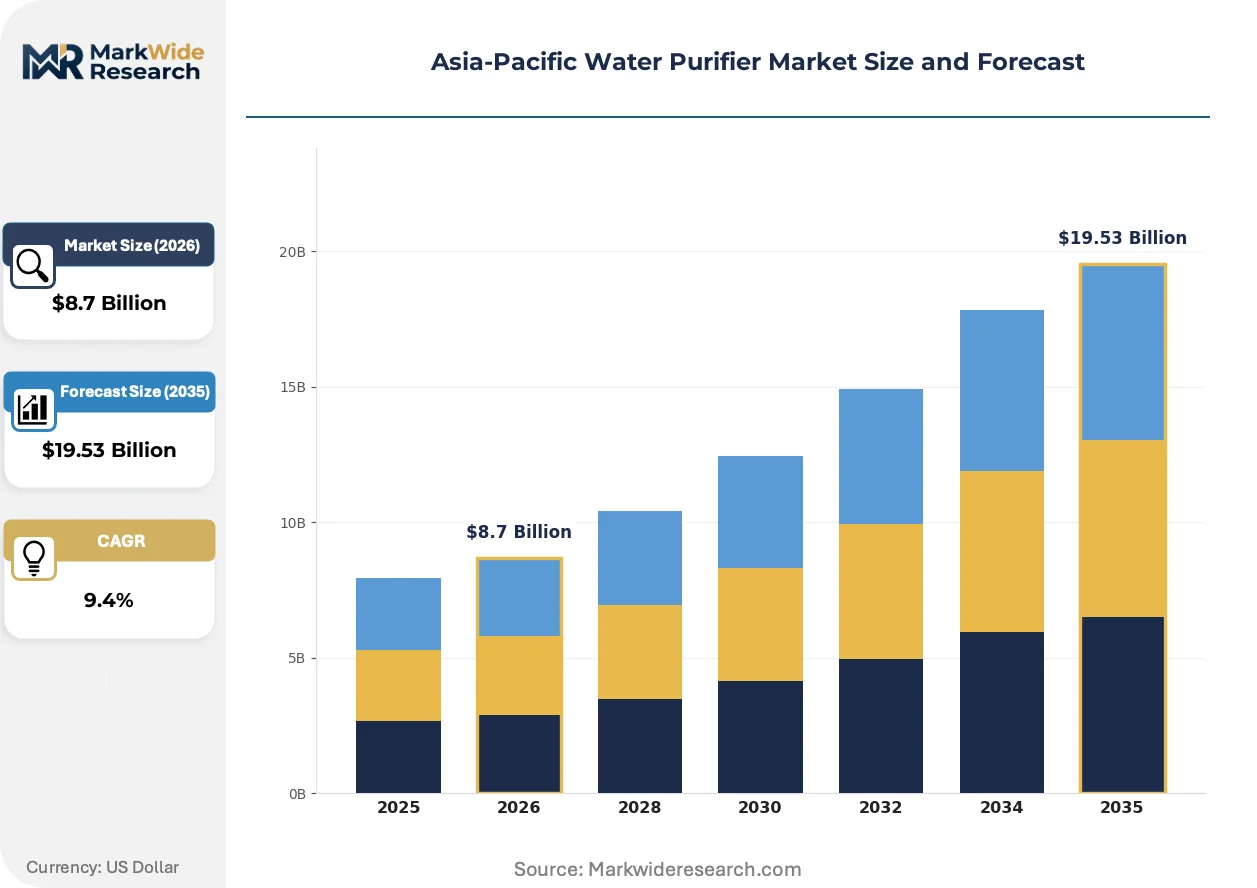
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Ultraviolet, Activated Carbon, Gravity-Based End User: Residential, Commercial, Industrial, Municipal Distribution Channel: Online, Retail, Direct Sales, Distributors Technology: Membrane Filtration, Chemical Treatment, Biological Treatment, Others |
| Companies Covered | A.O. Smith Water Technologies, 3M, Coway, Xiaomi Corporation, Livpure Smart Homes Private Limited, Kent RO Systems, Eureka Forbes, Membrane Solutions, LG Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Water Purifier Market Strategic Shifts
Membrane chemistry advances and connected hardware architectures are redrawing competitive boundaries, while regulatory divergence between national certification regimes forces modular product platform strategies.
Mineral-retention reverse osmosis technology is fragmenting the premium segment by addressing consumer resistance to zero-TDS output. Urban households in China's first-tier cities are adopting TDS-adjustable systems at twice the rate of conventional RO. This capability expansion is fragmenting what was previously a binary choice between purification thoroughness and taste preference.
Japan's JIS S 3201 household appliance safety codes are tightening plastic housing and tubing material-contact requirements for all products sold domestically. Manufacturers serving the Japanese market must now validate migration testing for bisphenol-A alternatives and specialized PPSU resins. The compliance burden falls heaviest on economy-tier producers lacking in-house polymer characterization laboratories.
Direct-to-consumer filter subscription models are displacing traditional distributor-led replacement cycles in India's metropolitan markets. Kent RO Systems and emerging competitors are unbundling hardware sales from consumable revenue, capturing lifetime value through app-managed auto-replenishment. This behavioral shift is most visible in Bangalore and Hyderabad, where smartphone penetration and payment infrastructure support seamless recurring transactions.
Asia-Pacific Water Purifier Market Segmentation
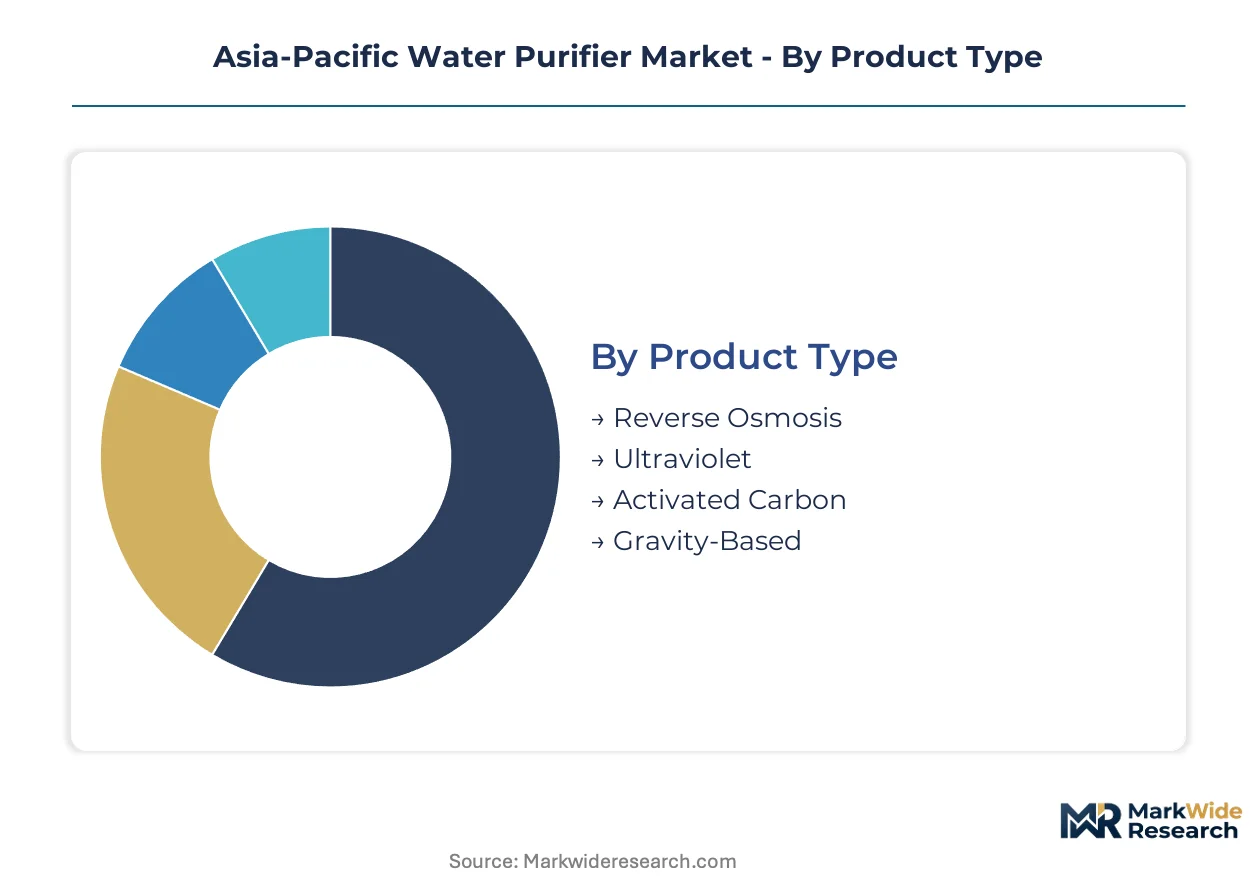
Segmentation in the Asia-Pacific water purifier market reveals divergent technology preferences between groundwater-dependent inland cities and chlorinated coastal metros. Product configuration, channel strategy, and compliance architecture all vary sharply across these divides.
Product Type:
Reverse osmosis systems dominate domestic manufacturing in India and China, while ultraviolet and gravity-based units retain stronger export orientation toward Southeast Asian price-sensitive markets.
- Reverse Osmosis:Pressure-driven membrane separation reduces TDS below 50 ppm through spiral-wound thin-film composites. Demand concentrates in Indian tier-two cities where BIS IS 10500 compliance mandates drive municipal-adjacent household upgrades.
- Ultraviolet:UV-C photolysis at 254 nm disrupts microbial DNA without chemical residuals. Penetration runs deepest in Vietnam and Indonesia where municipal chlorination gaps persist and electricity access enables point-of-use installation.
- Activated Carbon:Adsorptive media target chlorine, VOCs, and taste compounds in reticulated supply zones.
- Gravity-Based:Ceramic and activated carbon candles operate without electricity for off-grid rural deployment.
Reverse osmosis holds the largest share; momentum sits with mineral-retention RO variants.
End User:
Residential volumes outpace commercial and industrial segments, though municipal procurement in China's Yangtze River Delta generates concentrated project-scale revenue.
- Residential:Point-of-use systems serve individual households through countertop, under-sink, and wall-mounted configurations. China's first-tier cities are adopting TDS-adjustable RO at twice the rate of conventional systems.
- Commercial:Restaurants, hotels, and healthcare facilities require higher-capacity centralized units with redundant filtration stages. India's hospitality sector drives demand for certified systems meeting FSSAI drinking water protocols.
- Industrial:Boiler feedwater and process rinsing applications demand pre-treatment trains with softening and deionization.
- Municipal:District-scale installations and community water purification plants serve peri-urban transition zones.
Residential commands absolute volume; commercial applications are expanding most quickly.
Distribution Channel:
Channel structure reflects urban-rural digital divides, with direct sales penetrating India's district towns while online platforms capture China's metropolitan smartphone users.
- Online:E-commerce platforms and brand-owned apps enable filter subscription bundling and predictive reordering. Xiaomi's IoT ecosystem integration exemplifies this channel's data-capture potential.
- Retail:Electronics chains and home improvement stores provide tactile evaluation for first-time buyers. Penetration remains highest in South Korea's organized retail environment.
- Direct Sales:Territory-exclusive representatives demonstrate filtration efficacy through TDS meter comparisons. Kent RO's 500-plus district coverage anchors India market leadership.
- Distributors:Regional wholesalers stock inventory for tier-three cities and service-dependent replacement cycles.
Direct sales retain the deepest rural reach; online channels are gaining share fastest.
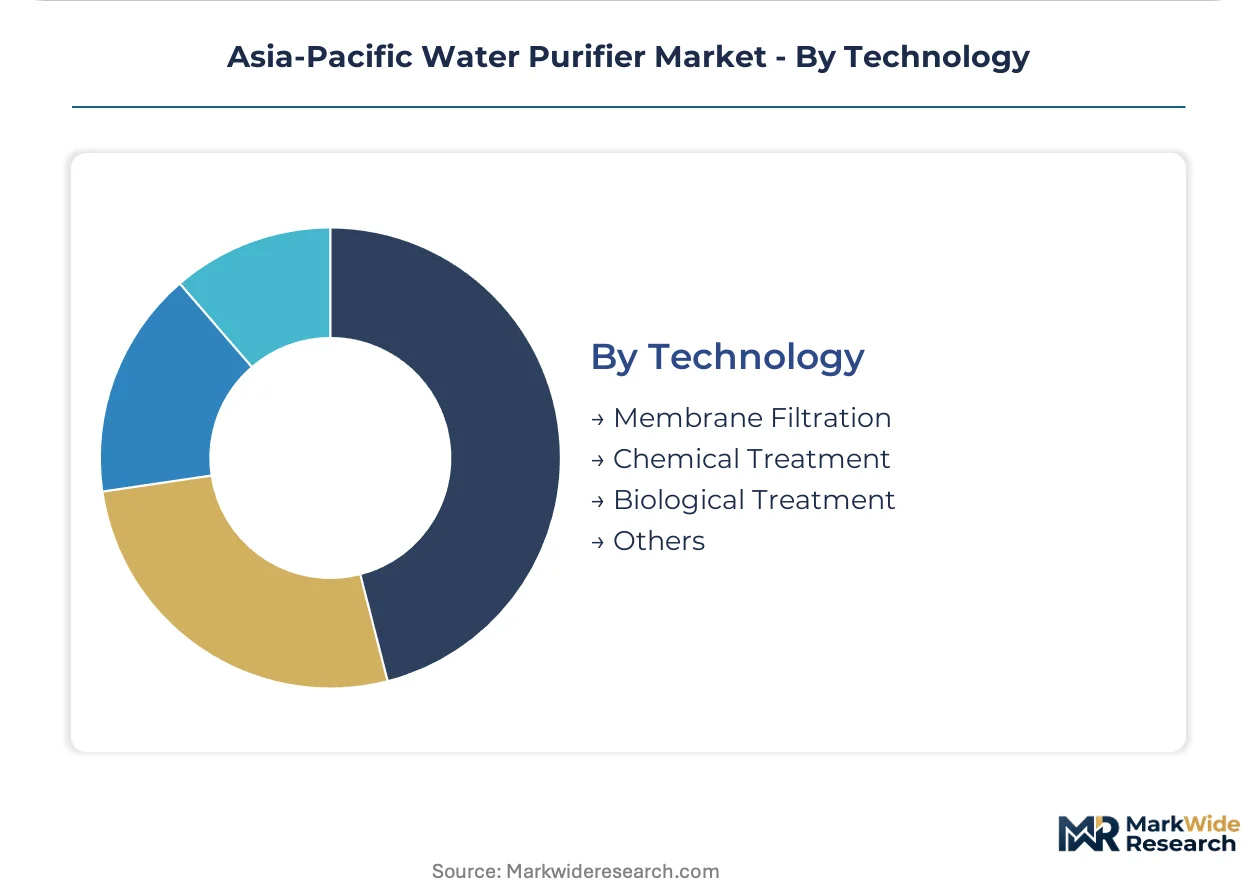
Technology:
Membrane filtration attracts capital investment in Chinese contract manufacturing clusters, while chemical and biological treatments remain fragmented across application-specific niches.
- Membrane Filtration:Microfiltration, ultrafiltration, nanofiltration, and reverse osmosis pressure-driven separations. Thin-film composite production is concentrating in Nanjing and Suzhou manufacturing corridors.
- Chemical Treatment:Coagulation, flocculation, and disinfection through chlorine, ozone, or potassium permanganate dosing. Industrial pre-treatment applications dominate in Australia's mining and food processing sectors.
- Biological Treatment:Biofilm reactors and constructed wetlands for organic load reduction. Deployment concentrates in decentralized rural systems with land availability.
- Others:Electrodialysis, distillation, and hybrid oxidation processes for specialized industrial effluent.
Membrane filtration holds the largest share; biological treatment shows the steepest expansion trajectory in off-grid applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and South Korean metropolitan markets where JIS S 3201 and MFDS compliance create certification premiums, while Indian tier-two cities compete on landed cost and direct-sales density. This asymmetry shapes divergent investment returns across the region.
China
Shanghai and the Yangtze River Delta megacity cluster drive demand through municipal retrofit programs that create parallel point-of-use protection needs. GB/T 30307 national purifier specifications mandate performance testing and material-contact upgrades that expand the certified-system addressable market. Nanjing and Suzhou manufacturing corridors concentrate thin-film composite membrane production, collapsing the capability gap between integrated and outsourced producers.
India
Residential households across tier-two cities face intensifying arsenic and fluoride groundwater contamination, accelerating RO system penetration where municipal infrastructure remains inadequate. BIS IS 10500 standards and state-level enforcement variance create product configuration complexity that raises inventory carrying costs. Bangalore and Hyderabad lead adoption of direct-to-consumer filter subscription models through app-managed auto-replenishment.
Japan
Urban households in Tokyo and Osaka metropolitan areas command premium positioning for TDS-adjustable and mineral-retention RO variants. METI and JIS S 3201 household appliance safety codes tighten plastic housing and tubing material-contact requirements, forcing migration testing for bisphenol-A alternatives. Compliance burdens fall heaviest on economy-tier producers lacking in-house polymer characterization laboratories.
South Korea
Seoul Capital Area consumers exhibit strong preference for IoT-enabled predictive maintenance bundles and smart home dashboard integration. MFDS drinking-water safety alerts and tightening mercury-content restrictions on amalgam UV lamps force costly LED-UV redesigns before economies of scale mature. Organized retail environments sustain tactile evaluation channels for first-time buyers.
Vietnam
Ho Chi Minh City and Hanoi household penetration remains under 15%, offering first-mover positioning before municipal water quality improvements reduce urgency. UV-C photolysis systems lead unit volumes where municipal chlorination gaps persist and electricity access enables point-of-use installation. Distribution runs through electronics chains and emerging e-commerce platforms targeting smartphone-enabled metropolitan consumers.
Asia-Pacific Water Purifier Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where membrane chemistry expertise and manufacturing scale rarely coincide. The vendor base spans captive membrane producers, IoT-integrated ecosystem players, direct-sales network operators, and contract manufacturing assemblers. Three archetypes dominate: vertically integrated specialists with in-house thin-film composite lines; platform-integrated consumer electronics firms bundling purification with smart home ecosystems; and dense direct-sales organizations penetrating district-level distribution. Competitive moves concentrate on backward integration into membrane substrate production and subscription-based recurring revenue models that decouple profitability from hardware margins.
Among Asia-Pacific-based operators, Kent RO Systems and Livpure Smart Homes Private Limited occupy positions within the direct-sales archetype, while Xiaomi Corporation exemplifies the ecosystem-integrated approach. A.O. Smith Water Technologies represents the vertically integrated specialist tier with captive production capabilities. These three anchors illustrate the strategic divergence between hardware-margin dependence and recurring-revenue architectures that defines competitive positioning across the region.
| Leading Market Players |
|---|
| A.O. Smith Water Technologies |
| 3M |
| Coway |
| Xiaomi Corporation |
| Livpure Smart Homes Private Limited |
| Kent RO Systems |
| Eureka Forbes |
| Membrane Solutions |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
China's GB/T 30307 national purifier specifications and India's BIS IS 10500 standards operate as simultaneous gating mechanisms for supply qualification and price differentiation, forcing manufacturers to absorb certification costs that stratify market access while creating compliance premiums for certified systems.
Pricing Analysis
The customization-premium spread separates configured-to-order membrane systems from standard SKUs by 40-60% at wholesale, with mineral-retention RO variants and TDS-adjustable units commanding the widest spreads. Price differentiation hinges on certification tier—GB/T 30307 Grade A versus baseline compliance—and after-sales service bundling that locks in recurring filter revenue. Cost compression in economy-tier segments is intensifying because Chinese contract manufacturers have collapsed thin-film composite production costs. Municipal procurement offices in China's Yangtze River Delta exhibit lowest price sensitivity, while Vietnam's household segment remains most exposed to landed cost fluctuations.
Supply Chain Analysis
Inventory cycles for spiral-wound membranes now stretch 14-20 weeks as Japanese and Korean substrate manufacturers throttle capacity expansion, exposing assemblers to lead-time volatility that forces buffer stock accumulation. Geographic supply concentration centers on China for thin-film composite fabrication, Japan for high-performance substrate polymers, and South Korea for interfacial polymerization equipment. Raw material dependencies include polyamide chemistry, polysulfone support layers, and specialized PPSU resins for JIS S 3201 compliance. Single-source vulnerability in Japanese substrate supply creates tariff-agnostic risk. Distribution runs through direct-sales networks in India's district towns and IoT-integrated e-commerce platforms in China's first-tier cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward organized retail and municipal procurement offices as channel consolidation concentrates volume allocation decisions among fewer actors with certified-system mandates.
For Market Incumbents: Shield premium positioning by securing captive thin-film composite production lines before Chinese contract manufacturers complete backward integration into substrate supply. Accelerate BIS IS 10500 and GB/T 30307 certification pipeline throughput to outpace compliance bottlenecks that delay product launches. Channel control through direct-sales territory exclusivity remains the priority defensive lever against Xiaomi's IoT ecosystem bundling. For New Entrants and Emerging Players: BIS fast-track certification for mineral-retention RO variants opens immediate access to India's arsenic-contaminated tier-two cities where Kent RO's network coverage remains incomplete. Vietnam's under-15% household penetration offers white-space positioning before municipal chlorination infrastructure matures. A subscription-first go-to-market angle—hardware subsidization with filter auto-replenishment—bypasses upfront price resistance in Bangalore and Hyderabad. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across contract membrane manufacturing as Chinese producers achieve scale economies in Nanjing and Suzhou corridors. Long-term viability favors acquirers targeting vertically integrated specialists with in-house polymer chemistry labs rather than pure-play assemblers. The signal to watch is thin-film composite substrate localization announcements from Korean and Japanese materials suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Substrate Production | Captive polyamide supply from Korean and Japanese polymer producers insulates against logistics volatility. |
| IoT-Enabled Predictive Maintenance Launch | Xiaomi's smart home dashboard integration demonstrates recurring revenue decoupling from hardware margins. |
| BIS IS 10500 Certification Fast-Track | Accelerated compliance timelines capture India's tier-two city groundwater contamination upgrade cycle. |
| Direct-to-Consumer Filter Subscription Model | Kent RO's app-managed auto-replenishment in Bangalore locks lifetime value through behavioral habit formation. |
| LED-UV Redesign for Mercury Compliance | MFDS and METI amalgam lamp restrictions force technology transition before LED-UV scale economies mature. |
Study Parameters
Operator-level perspectives from membrane production engineers, BIS certification laboratory directors, direct-sales territory managers, and municipal procurement officers in the Yangtze River Delta anchored the qualitative base. Primary interviews combined with secondary validation from GB standards documentation, BIS IS 10500 test protocols, JIS S 3201 migration studies, and customs trade data for thin-film composite imports. Bottom-up unit economics triangulated against top-down addressable market sizing across technology, end-use, and distribution channel dimensions.
Sensitivity analysis tested forecast robustness against membrane substrate localization timelines and regulatory enforcement variance across Indian states. Segmentation dimensions modeled include product type, end-user category, distribution channel, and technology platform across the projection horizon. CAGRs derived from installed base penetration curves and replacement cycle frequency, with mineral-retention RO adoption rates and IoT bundle attach rates as industry-specific forecast inputs.
Underlying assumptions cover sustained groundwater contamination severity in Indian tier-two cities and Chinese municipal retrofit program continuity, with deviation risk concentrated in BIS state-level enforcement harmonization and LED-UV cost curve acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Home Water Filtration Unit Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Portable Water Purifier Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Water Treatment Ozone Generator Market