
 Water Purifier/Filter Market | 2026-2036
Water Purifier/Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Water Purifier/Filter Market Analytics
EPA Lead and Copper Rule revisions are decoupling low-cost filtration from municipal compliance, forcing manufacturers to certify at stricter contaminant-removal thresholds. Pentair PLC leverages its industrial membrane portfolio to anchor premium residential lines with proven reverse-osmosis performance. A.O. Smith Corporation sustains channel dominance in North America through captive distribution and contractor relationships. Coway Co., Ltd. differentiates via subscription-based filter-replacement models that lock in recurring revenue across Asian urban markets.
Water purifiers and filters are engineered systems that remove particulates, dissolved solids, biological contaminants, and chemical impurities from water supplies through physical barriers, chemical adsorption, or electromagnetic radiation, typically achieving removal efficiencies of 90-99% for targeted contaminants depending on technology configuration. Their primary purpose spans potable water preparation for households, process-water conditioning for manufacturing, and compliance-grade treatment for municipal distribution. Reverse osmosis systems command the highest installed value per unit due to membrane replacement economics and energy requirements, while UV purifier segments are expanding fastest in commercial applications where chemical-free disinfection is preferred. Activated carbon gravity filters occupy the mass-market tier with thin margins but dominant unit volumes across price-sensitive geographies.
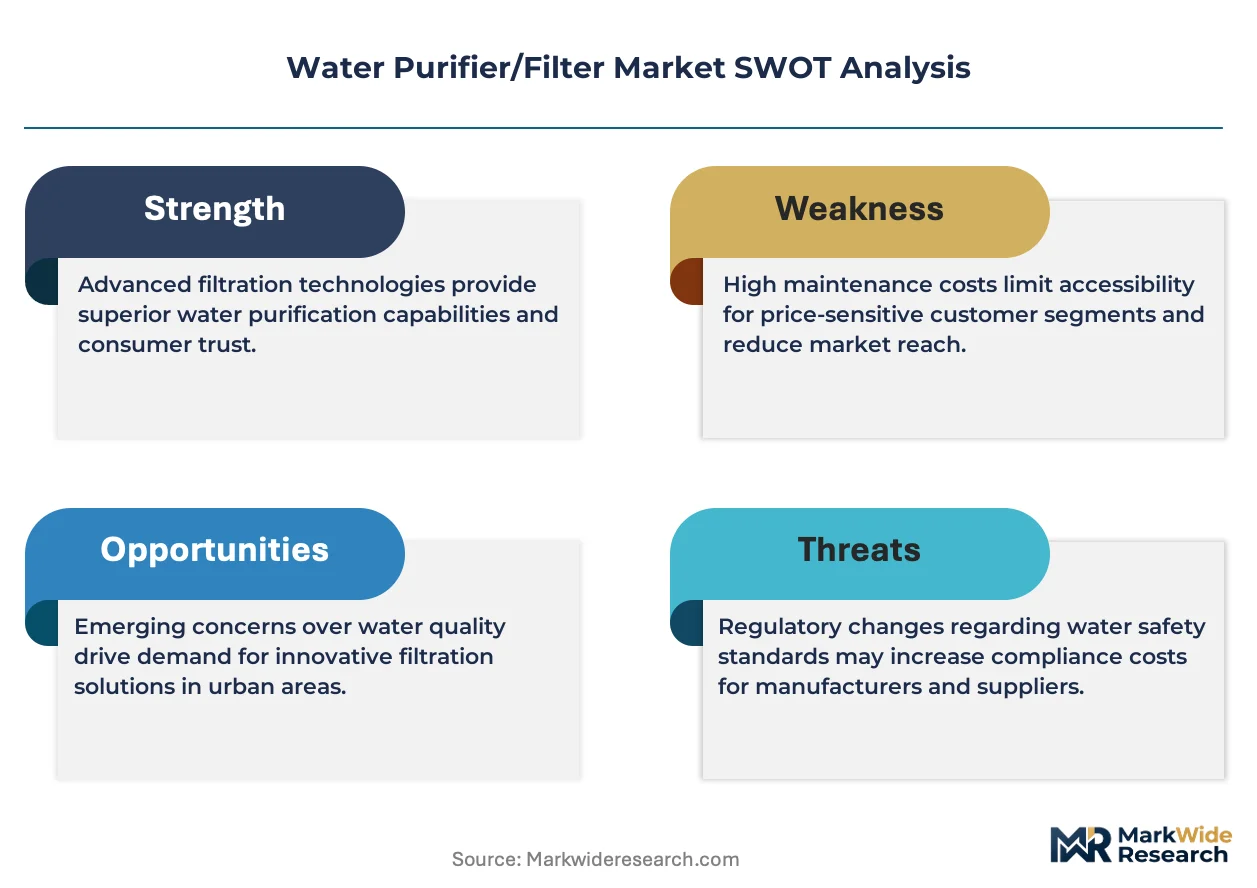
The EPA enforces Safe Drinking Water Act standards that directly dictate NSF/ANSI certification requirements for point-of-use devices sold in the United States. The EU Drinking Water Directive and REACH chemical restrictions similarly shape product material specifications and contaminant-claim substantiation across European markets. China's SAMR and GB standards for household water treatment equipment impose additional testing protocols that foreign entrants must navigate for market access. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation is raising R&D duplication costs and favoring multi-certification platforms over single-market specialists.
Market Dynamics
Point-of-use filtration is fragmenting municipal water infrastructure authority, as households bypass centralized treatment through countertop reverse-osmosis and UV systems that deliver certified potable water without utility dependence.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Municipal utilities face stricter corrosion control mandates, accelerating residential point-of-use adoption as households seek certified lead-removal independent of pipe replacement timelines.
- India's municipal supply gaps:Intermittent piped water delivery and documented bacterial contamination in cities like Delhi and Mumbai drive penetration of gravity-fed ceramic filters and UV purifiers among middle-class apartments.
- Membrane miniaturization:Spiral-wound reverse-osmosis elements now fit under-sink footprints previously occupied by carbon blocks, enabling retrofit installation without plumbing reconstruction.
Market Restraints
- Polymer resin cost volatility:Activated carbon block housings and RO membrane substrates depend on petroleum-derived polymers whose price swings compress assembler margins unpredictably.
- Certification fragmentation:NSF/ANSI 42/53/58 protocols in the United States diverge from China's GB/T 30307 and India's BIS IS 16240, forcing parallel testing runs for multi-market entrants.
- Filter cartridge substitution:Third-party aftermarket cartridges undercut OEM replacement revenue, eroding the subscription economics that sustain installed-base profitability.
Strategic Opportunities
- Vietnam's emerging middle class:Ho Chi Minh City and Hanoi exhibit underpenetrated point-of-use adoption despite documented groundwater arsenic, creating first-mover positioning for certified RO distributors.
- Commercial foodservice mandates:California's AB 1200 disclosure requirements for perfluoroalkyl substances are forcing restaurant chains to install certified pre-filtration for ice machines and beverage dispensers.
- IoT-enabled predictive maintenance:Connected flow sensors and TDS monitors allow manufacturers to trigger filter shipments before performance degradation, converting transactional hardware sales into recurring revenue platforms.
Industry Challenges
- Membrane fouling expertise scarcity:Field technicians capable of diagnosing biofilm accumulation versus scaling in RO systems remain concentrated in industrial water treatment, leaving residential service networks undertrained.
- NSF certification timeline compression:Expedited contaminant-claim validation for emerging threats like PFAS requires protocol development that outpaces standard 12-18 month certification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Purifier/Filter Market |
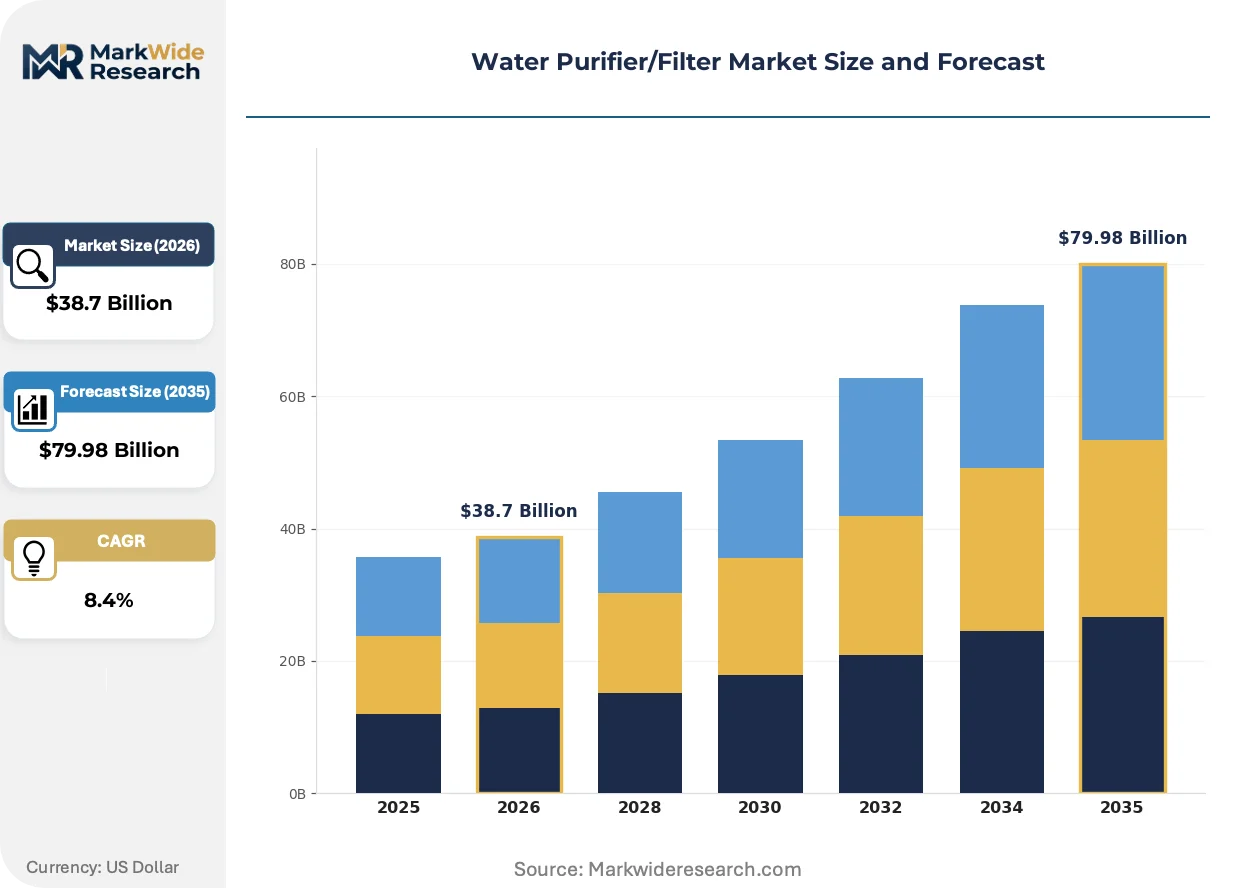
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Activated Carbon, UV Purifier, Gravity Filter End User: Residential, Commercial, Industrial, Municipal Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales Technology: Filtration, Ultraviolet, Ion Exchange, Distillation |
| Companies Covered | Pentair PLC, A.O. Smith Corporation, Culligan International, Coway Co., Ltd., Panasonic Corporation, 3M Company, Brita GmbH, LG Electronics, Eureka Forbes Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Purifier/Filter Market Evolving Landscape
Water purification hardware is converging with connected infrastructure and predictive service models, compressing replacement cycles while shifting buyer relationships from transactional to continuous.
Tankless direct-flow reverse osmosis is decentralizing under-sink installation economics by eliminating the 3-4 gallon storage vessel that previously dictated cabinet space requirements. Urban apartment dwellers in Seoul and Shanghai are adopting these systems at accelerating rates. The technology is compressing distributor inventory requirements while enabling same-day installation without plumbing modification.
REACH restrictions on per- and polyfluoroalkyl substances are forcing membrane manufacturers to reformulate hydrophobic coatings and gasket materials. Industrial consequence includes accelerated R&D spend on fluorine-free alternatives. European residential RO lines face 2025 compliance deadlines that Asian exporters must meet to maintain market access.
Subscription filter replacement is displacing retail cartridge purchases among Asian urban households, with locked-in replenishment schedules reducing price comparison behavior. Direct-to-consumer platforms and appliance-rental channels are capturing this shift. South Korea's apartment-dense Seoul metropolitan area exhibits the most visible concentration of this model.
Water Purifier/Filter Market Segmentation
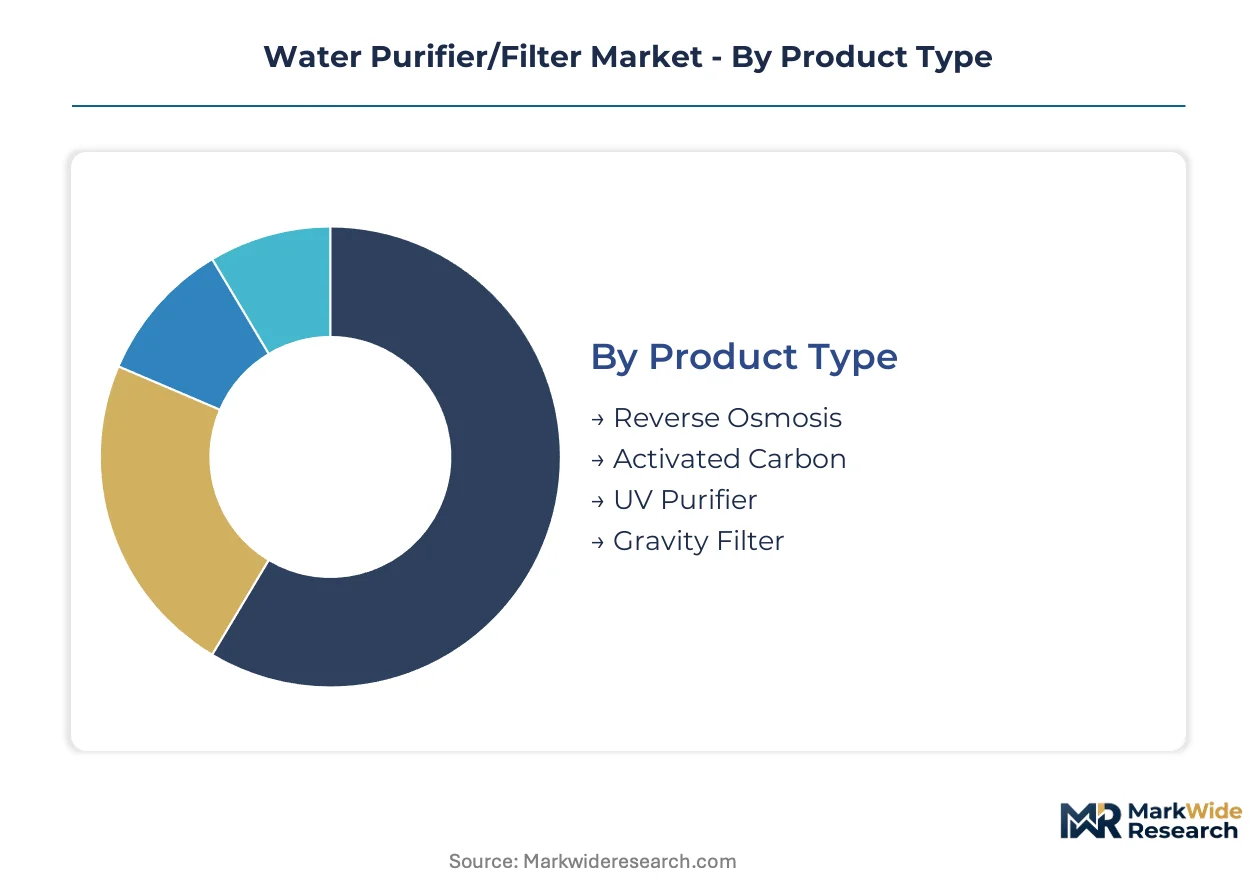
Water purification markets fragment sharply across buyer sophistication, infrastructure maturity, and regulatory exposure. Segment boundaries determine pricing architecture, certification burden, and channel economics for manufacturers navigating divergent compliance regimes.
Product Type:
Purchase decisions in this category hinge on contaminant threat profiles and installation feasibility rather than price alone.
- Reverse Osmosis:Multi-stage membrane systems force water through semi-permeable barriers under pressure, achieving dissolved solids rejection exceeding 95%. Demand concentrates in Indian metropolitan apartments and Vietnamese urban households confronting groundwater arsenic, where municipal supply gaps eliminate cheaper alternatives.
- Activated Carbon:Porous carbon blocks adsorb chlorine, volatile organic compounds, and taste-odor compounds through surface binding. North American suburban retrofit installations dominate volume, driven by EPA Lead and Copper Rule anxiety among homeowners seeking certified lead reduction without pipe replacement delays.
- UV Purifier:Germicidal ultraviolet lamps inactivate bacterial and viral pathogens without chemical residuals. Commercial foodservice applications in California restaurant chains are expanding under AB 1200 disclosure mandates for perfluoroalkyl substances.
- Gravity Filter:Unpowered ceramic-carbon composite elements rely on hydrostatic head for flow. Rural Indian households and price-sensitive Southeast Asian markets sustain dominant unit volumes despite thin margins.
Volume sits with Gravity Filter; growth tilts toward Reverse Osmosis.
End User:
Scale economics and replacement frequency separate buyer classes more than initial hardware specifications.
- Residential:Point-of-use countertop and under-sink systems serving individual households. Middle-class apartment penetration in Delhi, Mumbai, and Ho Chi Minh City is climbing fastest amid documented municipal supply contamination.
- Commercial:Foodservice, hospitality, and office installations requiring certified output for liability protection. California restaurant chains are retrofitting ice machines and beverage dispensers under PFAS disclosure rules.
- Industrial:Process-water conditioning for manufacturing with customized pretreatment trains. Semiconductor fabrication and pharmaceutical production sustain premium membrane replacement economics.
- Municipal:Centralized treatment infrastructure and distributed point-of-entry systems for small communities. EPA corrosion control mandates are accelerating decentralized adoption where pipe replacement timelines exceed compliance deadlines.
Replacement revenue concentrates in Commercial; steepest expansion trajectory belongs to Residential.
Distribution Channel:
Channel selection determines margin capture and customer data ownership for manufacturers.
- Online Retail:Direct-to-consumer platforms and marketplace listings enabling subscription lock-in. Seoul apartment households exhibit highest subscription conversion rates for filter replenishment.
- Offline Retail:Big-box home improvement and appliance specialty stores. North American contractor relationships through captive distribution sustain A.O. Smith's channel dominance.
- Wholesale:Distributor networks serving regional installers and service technicians. Inventory compression from tankless direct-flow systems is reducing distributor capital requirements.
- Direct Sales:Manufacturer-owned service arms and rental platforms. Coway's locked-in replenishment schedules across Asian urban markets exemplify this model's recurring revenue architecture.
Margin capture favors Direct Sales; volume throughput remains with Offline Retail.
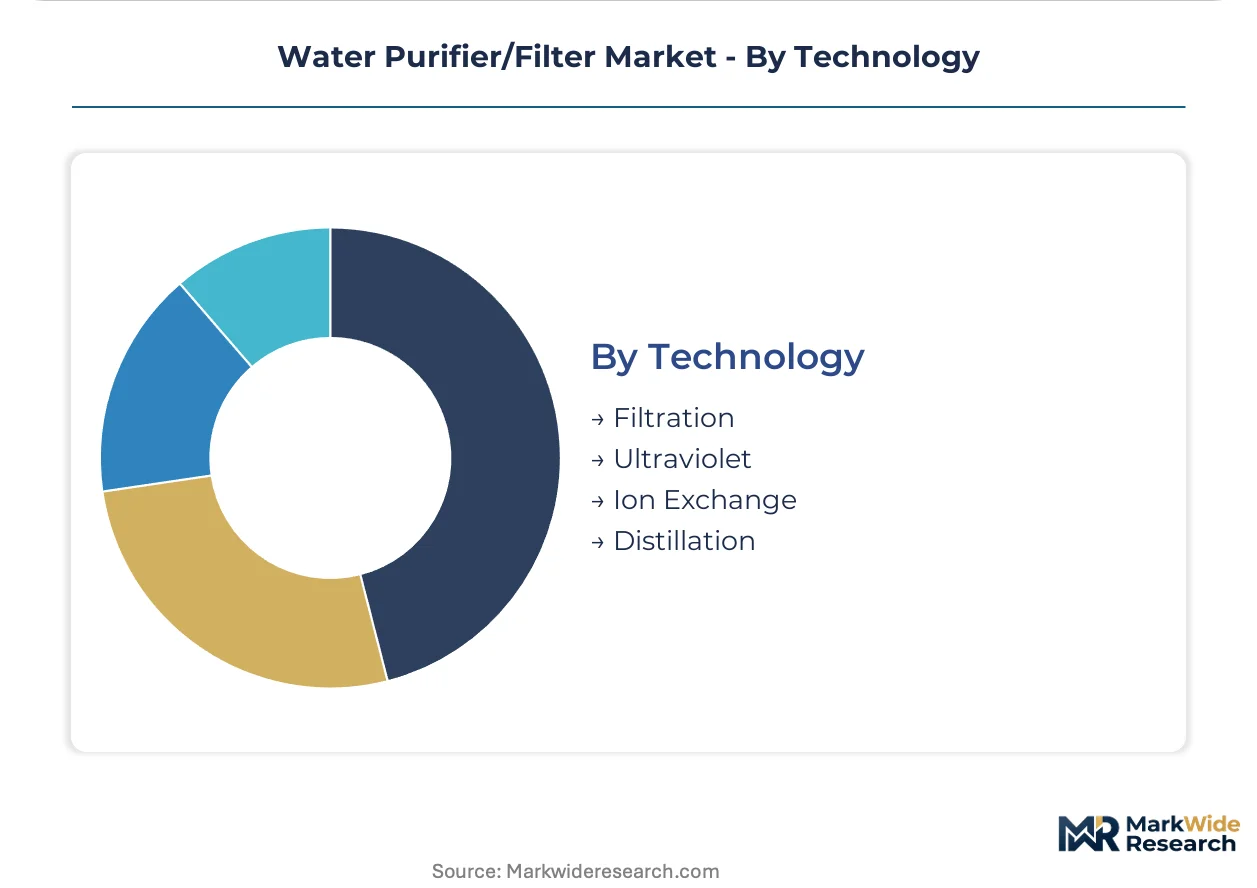
Technology:
Underlying mechanism determines energy intensity, waste generation, and certification complexity.
- Filtration:Physical barrier separation through porous media including membranes, ceramics, and compressed carbon. Spiral-wound reverse-osmosis miniaturization is enabling under-sink retrofit without plumbing reconstruction.
- Ultraviolet:Electromagnetic disinfection at 254 nanometers wavelength. Chemical-free operation drives preference in commercial foodservice where residual taste is unacceptable.
- Ion Exchange:Resin-based cation and anion substitution for hardness and specific contaminant removal. Industrial boiler feedwater pretreatment sustains specialized demand.
- Distillation:Phase-change purification through evaporation and condensation. Energy intensity limits application to laboratory and medical settings requiring highest purity grades.
Installed base concentrates in Filtration; regulatory tailwinds favor Ultraviolet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential point-of-use adoption concentrates in emerging economies where municipal infrastructure gaps intersect with rising health consciousness. India anchors absolute volume expansion, while Vietnam and Indonesia represent underpenetrated frontier markets. Regulatory divergence across EPA, REACH, and BIS frameworks shapes certification burdens for multi-market entrants.
United States
Suburban homeowners confronting aging lead service lines drive under-sink reverse-osmosis retrofit demand. EPA Lead and Copper Rule revisions accelerate point-of-use adoption timelines independent of municipal pipe replacement schedules. California's AB 1200 disclosure mandates for perfluoroalkyl substances force restaurant chains to install certified pre-filtration for commercial foodservice equipment.
India
Middle-class apartment dwellers in Delhi and Mumbai respond to documented bacterial contamination in intermittent municipal supplies. BIS IS 16240 certification requirements tighten product entry standards for domestic and foreign manufacturers alike. Gravity-fed ceramic filters dominate rural penetration while UV-RO combinations capture urban unit growth.
China
Seoul and Shanghai apartment households adopt tankless direct-flow systems at accelerating rates as membrane miniaturization eliminates storage vessel requirements. SAMR and GB/T 30307 standards impose testing protocols that foreign entrants must navigate for market access. Yangtze River Delta manufacturing clusters supply spiral-wound membrane elements for regional assembly.
Vietnam
Ho Chi Minh City and Hanoi exhibit documented groundwater arsenic contamination without commensurate point-of-use penetration. Emerging middle-class households create first-mover positioning opportunities for certified RO distributors. National technical regulations on drinking water quality are tightening import certification requirements.
Germany
REACH restrictions on per- and polyfluoroalkyl substances force membrane manufacturers to reformulate hydrophobic coatings and gasket materials. Industrial R&D spend on fluorine-free alternatives accelerates ahead of 2025 compliance deadlines. Bavaria-based precision engineering clusters support high-purity process-water systems for pharmaceutical and semiconductor fabrication.
Water Purifier/Filter Market Competitive Landscape
North American producers anchor one tier through captive distribution networks and contractor relationships; Asian specialists hold another through subscription-based filter replacement models and appliance-rental channels. The vendor base stratifies across industrial membrane conglomerates, diversified appliance manufacturers, and pure-play residential filtration brands. Three archetypes dominate: membrane technology licensors, direct-to-consumer subscription platforms, and diversified industrial conglomerates with residential line extensions. Competitive moves concentrate on vertical integration into membrane substrate production and geographic licensing partnerships to bypass certification fragmentation.
Among diversified industrial conglomerates, 3M Company and Panasonic Corporation exemplify technology-platform leverage across filtration-adjacent materials science and electronics divisions. Pentair PLC occupies a position within the membrane-specialist tier, anchoring premium residential lines through industrial reverse-osmosis performance heritage. A.O. Smith Corporation sits within the captive-distribution archetype, sustaining North American channel dominance through contractor relationships and wholesale network control. Coway Co., Ltd. represents the subscription-model specialist, locking in recurring revenue through locked-in replenishment schedules across Seoul and other dense Asian urban markets.
| Leading Market Players |
|---|
| Pentair PLC |
| A.O. Smith Corporation |
| Culligan International |
| Coway Co., Ltd. |
| Panasonic Corporation |
| 3M Company |
| Brita GmbH |
| LG Electronics |
| Eureka Forbes Ltd. |
| Others |
Value Network & Pricing Analysis
REACH restrictions on per- and polyfluoroalkyl substances gate qualified membrane supply and premium-tier pricing access, as fluorine-free coating reformulation raises qualified supplier counts and separates certified European product lines from uncertified competitors.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement decisions, with short-lead-time membrane elements commanding premiums while spot inventory of activated carbon blocks trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 58-certified RO systems from BIS-compliant Indian market variants and unbranded gravity filters. Price differentiation hinges on certification grade and geographic delivery cost. Pricing pressure stems from third-party cartridge substitution eroding OEM replacement economics. Price-sensitive buyers cluster in rural Indian households selecting gravity filters; least sensitive buyers occupy California commercial foodservice chains facing AB 1200 liability exposure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale membrane demand from diversified appliance manufacturers, while distributor networks serve regional installer bases with compressed inventory requirements from tankless direct-flow systems. Manufacturing concentrates in China, South Korea, and Germany. Raw material flows draw from petroleum-derived polymers for carbon block housings, polyamide thin-film composites for RO membranes, and rare-earth phosphors for UV lamps. Single-source vulnerability sits with spiral-wound element production concentrated in Yangtze River Delta clusters. Distribution runs through captive wholesale networks in North America and subscription-direct platforms in Seoul and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane substrate production represents the upstream lever incumbents are racing to control, as backward integration into polyamide casting and polymer resin compounding separates cost-competitive scale players from assembler-margin-dependent competitors.
For Market Incumbents: Deepen captive membrane substrate production to offset polymer resin cost volatility and defend against third-party cartridge erosion. Lock in NSF/ANSI certification pipelines for emerging PFAS contaminant claims before protocol standardization accelerates. Channel control through contractor relationships remains defensible in North American suburban retrofit segments where installation complexity sustains service bundling. For New Entrants and Emerging Players: Capture Vietnam's certified RO distribution whitespace in Ho Chi Minh City and Hanoi, where groundwater arsenic documentation meets underpenetrated point-of-use adoption. Target subscription-based filter replacement models in dense Asian urban apartments, converting transactional hardware sales into recurring revenue platforms through IoT-enabled predictive maintenance triggers. For Investors and Strategic Acquirers: EPA Lead and Copper Rule revision acceleration is the leading indicator that residential point-of-use retrofit demand will sustain premium pricing tiers independent of municipal infrastructure timelines. Acquisition targets should concentrate on multi-certification platform specialists with parallel NSF/ANSI, GB/T 30307, and BIS IS 16240 testing capabilities. Watch for expedited PFAS protocol development as the signal that regulatory divergence costs are favoring integrated compliance platforms over single-market specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Substrate Backward Integration | In-house polyamide casting reduces polymer resin cost exposure and secures supply continuity for RO system assemblers. |
| Multi-Certification Platform Investment | Parallel NSF/ANSI, GB/T 30307, and BIS testing capabilities lower R&D duplication costs for geographic expansion. |
| IoT-Enabled Predictive Maintenance Launch | Connected TDS monitors trigger filter shipments before degradation, converting hardware sales into recurring revenue. |
| Fluorine-Free Coating Reformulation | REACH-compliant membrane alternatives maintain European market access ahead of 2025 compliance deadlines. |
| Direct-to-Consumer Subscription Platform | Locked-in replenishment schedules reduce price comparison behavior among Seoul apartment households. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with membrane manufacturing executives, water treatment contractor network heads, BIS certification laboratory directors, and municipal utility corrosion control officers. Secondary sources included EPA Safe Drinking Water Act enforcement records, SAMR GB standard publications, India BIS IS 16240 test protocols, and REACH substance restriction updates. Bottom-up unit shipment estimates by product type and geography triangulated against top-down market value reconstructions.
Data-stream reconciliation across shipment volumes, average selling price trajectories, and replacement frequency assumptions generated segment-level value estimates across the projection horizon. Modeled dimensions spanned product type, end-user category, distribution channel, and underlying technology mechanism, with additional granularity on certification tier and geographic regulatory cluster. CAGRs derived from fitted growth curves incorporating membrane miniaturization adoption rates, municipal supply gap documentation, and subscription model penetration patterns in dense Asian urban markets.
The model holds under stable polymer resin pricing and certification timeline assumptions; deviation in EPA enforcement acceleration or REACH substance list expansion would shift replacement cycle and compliance cost trajectories. Forecasts reflect documented assumptions on membrane replacement economics and regulatory divergence costs. Periodic stress-testing of base assumptions against customs records and certification database updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Plant Based Water Filter Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Home Water Filtration Unit Market
Water Treatment Systems
Home Water Softener System Market
Water Treatment Systems
Portable Water Purifier Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Water Desalination Equipment Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Commercial Water Filter Market