
 Global Water Recycle and Reuse Market | 2026-2036
Global Water Recycle and Reuse Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water Recycle and Reuse Market Outlook
Performance-based service contracts for membrane maintenance and remote monitoring is repositioning how water reuse systems are sold, shifting capital expenditure into operational contracts. Veolia leverages its integrated service platform across municipal and industrial accounts. Xylem sustains technology leadership in smart pumping and digital water analytics. Siemens anchors large-scale automation and control systems for industrial water loops.
Water recycle and reuse encompasses the collection, treatment, and redistribution of wastewater to substitute fresh water in industrial, agricultural, or potable applications, typically achieving total dissolved solids below 500 mg/L for process water and meeting microbial standards through UV or ozone disinfection. Membrane bioreactor systems dominate municipal installations where footprint constraints and effluent quality requirements are strict, while reverse osmosis occupies the highest-value segment in semiconductor and pharmaceutical process water preparation. Industrial facilities represent the fastest-growing end-user category as energy and manufacturing sectors face intensifying withdrawal limits.
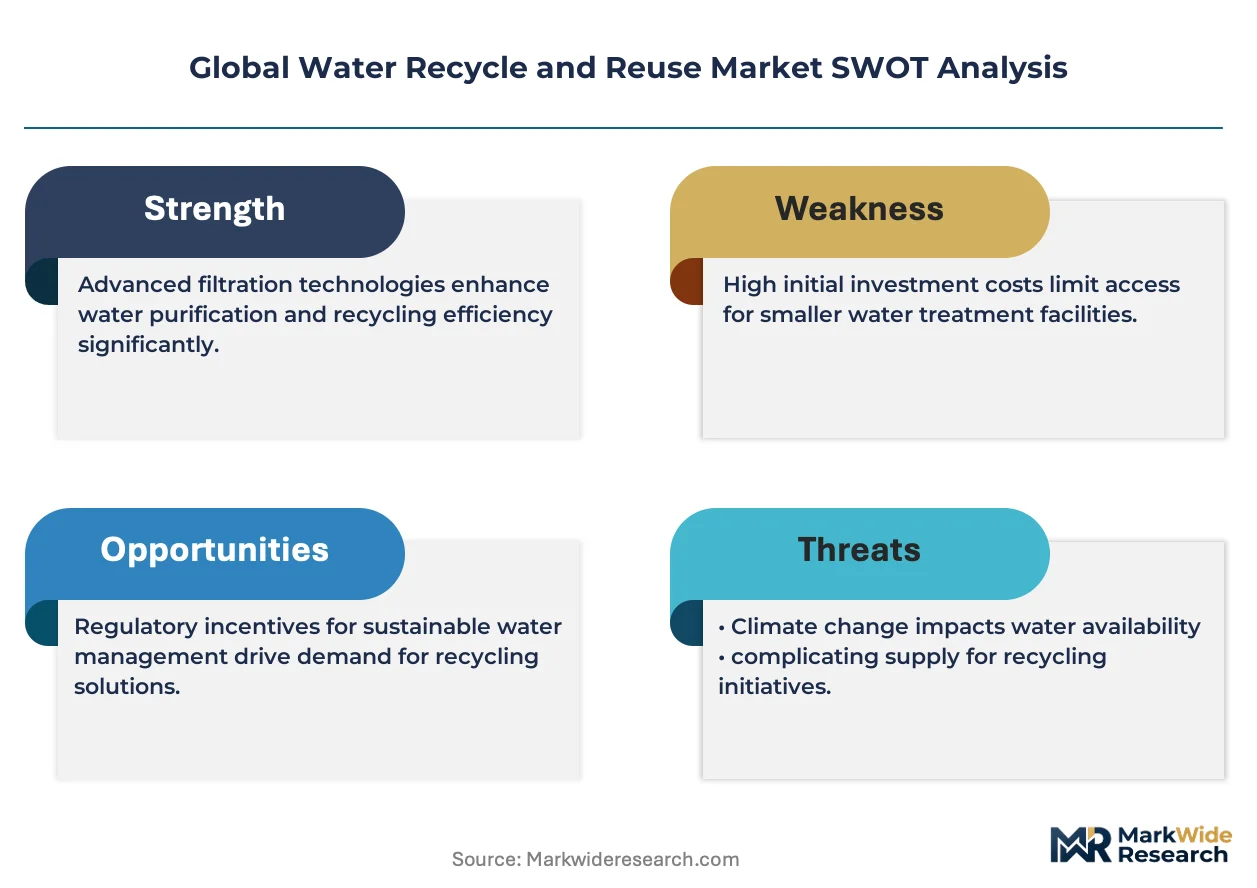
The US EPA enforces Clean Water Act discharge standards that push facilities toward zero-liquid-discharge configurations, while the EU Urban Wastewater Treatment Directive mandates nutrient removal thresholds that expand tertiary treatment demand. China's MEE enforces stricter industrial wastewater reuse quotas under dual carbon goals, tightening market access for non-compliant equipment suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to align certification investments with the geographies offering the steepest compliance-driven replacement cycles.
Market Dynamics
Performance-based service contracts for membrane maintenance and remote monitoring are repositioning how water reuse systems are sold, shifting capital expenditure into operational contracts and compressing traditional equipment-only sales cycles.
Growth Catalysts
- Semiconductor fab expansion:Taiwan and South Korea fabs are expanding on-site water recycling capacity to meet ultra-pure water specifications for advanced node production.
- California's Title 22 regulations:Tightening discharge requirements are pushing municipal utilities toward tertiary treatment upgrades and indirect potable reuse infrastructure.
- Singapore's NEWater standards:Stringent microbial and chemical benchmarks are creating certification-driven replacement demand for UV and ozone disinfection systems.
Market Restraints
- Membrane replacement cost volatility:Polymer feedstock price swings and specialized ceramic supply concentration in Japan create input cost uncertainty for MBR operators.
- High capex intensity for ZLD systems:Thermal evaporators and crystallizers require substantial upfront investment, limiting adoption outside heavily regulated industrial clusters.
- Permitting timeline friction:US EPA Clean Water Act discharge variances and state-level environmental review processes extend project commissioning by 18-36 months.
Strategic Opportunities
- Saudi Arabia's megaproject mandates:Qiddiya and NEOM developments mandate closed-loop water systems, creating demand for integrated treatment and brine management.
- Digital twin convergence:Integration of real-time sensors with predictive analytics is expanding into municipal networks, enabling condition-based membrane replacement.
- EU Urban Wastewater Treatment Directive:Nutrient removal thresholds are expanding tertiary treatment demand across Germany, France, and the Netherlands.
Industry Challenges
- Process control specialist scarcity:Automation engineers with expertise in PLC programming for water treatment loops command premium compensation, constraining system integrator capacity.
- Legacy SCADA integration complexity:Brownfield industrial facilities face protocol incompatibility when retrofitting smart monitoring onto 1990s-era distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water Recycle and Reuse Market |
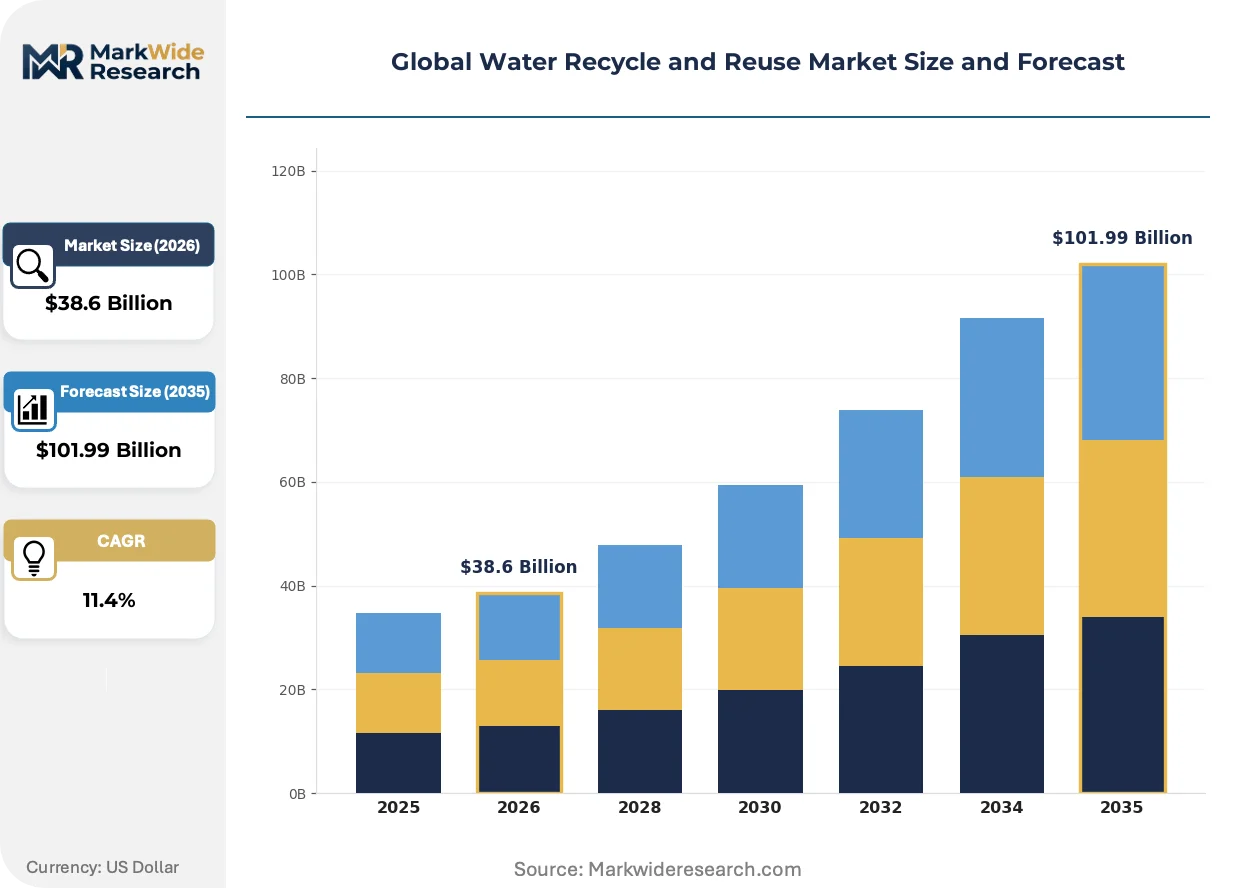
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Bioreactor, Reverse Osmosis, UV Disinfection, Advanced Oxidation Application: Agricultural Irrigation, Industrial Process Water, Potable Reuse, Recreational Water End User: Municipalities, Industrial Facilities, Agricultural Sector, Commercial Buildings Distribution Channel: Direct Sales, Online Sales, Distributors, Contractors |
| Companies Covered | Veolia, Xylem, Ecolab, DuPont, Pentair, Siemens, Hitachi, Aquatech, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water Recycle and Reuse Market Strategic Shifts
Membrane technology evolution, regulatory tightening in water-stressed jurisdictions, and service model restructuring are converging to reshape competitive positioning and value capture mechanisms.
Forward osmosis draw solute regeneration systems are expanding into high-salinity industrial wastewater treatment. Oil and gas operators in the Permian Basin are piloting these configurations for produced water management. The technology is expanding into markets previously dominated by thermal desalination, compressing energy intensity benchmarks for zero-liquid-discharge applications.
China's MEE industrial wastewater reuse quotas under dual carbon goals are tightening market access for non-compliant equipment suppliers. Facilities in the Yangtze River Economic Belt must achieve 85% reuse rates or face production curtailments. Semiconductor and pharmaceutical manufacturers are responding by retrofitting reverse osmosis trains with advanced oxidation process post-treatment.
After-sales service unbundling is accelerating as end-users separate membrane element supply from technical support contracts. Large municipal utilities in Australia and Singapore are negotiating direct procurement with membrane manufacturers while retaining third-party specialists for optimization services. This bifurcation is most visible in Asia-Pacific, where public-sector procurement rules favor multi-vendor sourcing strategies.
Global Water Recycle and Reuse Market Segmentation
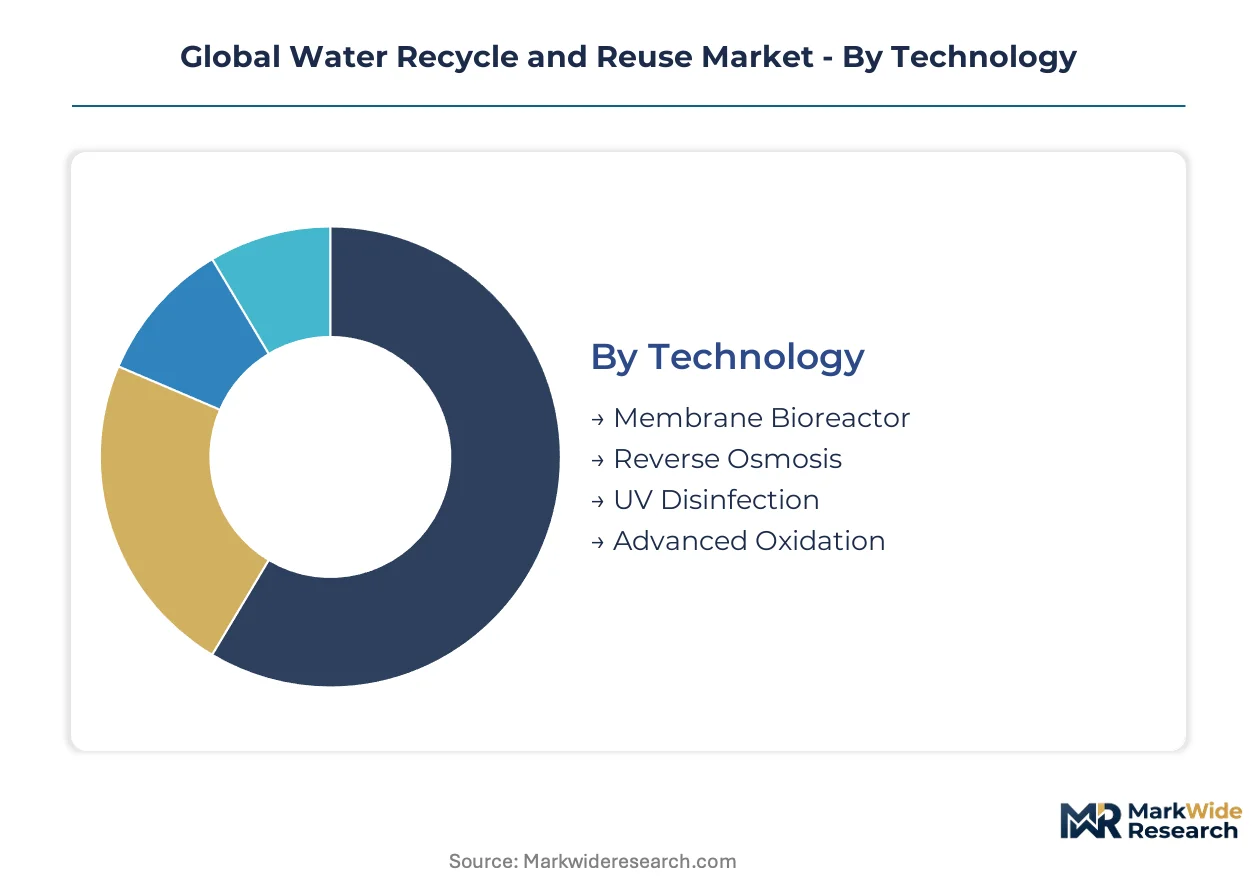
Technology selection in water recycle and reuse systems determines capital intensity, operational complexity, and regulatory compliance pathways. Application context dictates whether systems operate as standalone installations or integrate into broader industrial or municipal infrastructure. Understanding these segment boundaries clarifies where equipment suppliers capture value versus where service providers dominate recurring revenue streams.
Technology:
Integration depth varies sharply across technologies, with some functioning as embedded process steps and others operating as complete standalone treatment trains.
- Membrane Bioreactor:Combines biological degradation with membrane filtration in a single tank, achieving suspended solids below 5 mg/L without secondary clarifiers. Municipal utilities in Singapore and California deploy MBRs where footprint constraints and Title 22 compliance converge, though polymer membrane replacement cycles compress operating margins when feedstock prices spike.
- Reverse Osmosis:Applies hydraulic pressure across semi-permeable thin-film composite membranes to reject dissolved salts and organics, producing conductivity below 10 µS/cm for semiconductor process water. Taiwan and South Korea fabs are expanding RO capacity for advanced node production, driving demand for specialized antiscalant chemistries and energy-recovery devices.
- UV Disinfection:Inactivates pathogens through 254 nm irradiation without chemical residuals, typically deployed as a polishing step post-filtration.
- Advanced Oxidation:Generates hydroxyl radicals through ozone/UV or photocatalytic processes to mineralize recalcitrant organics in pharmaceutical and chemical manufacturing effluent.
Reverse osmosis leads volumes today; advanced oxidation is gaining share fastest.
Application:
Cost tier segmentation separates high-purity process water commanding premium treatment from bulk irrigation applications where tertiary standards suffice.
- Industrial Process Water:Requires multi-barrier treatment achieving resistivity above 10 MΩ·cm for electronics manufacturing and boiler feed applications. Semiconductor fabs in the Yangtze River Economic Belt face China's MEE 85% reuse mandates, forcing retrofit investments in RO-UV-Ozone treatment trains.
- Potable Reuse:Demands the most stringent multi-barrier approach including reverse osmosis, advanced oxidation, and engineered storage buffers before distribution. California's indirect potable reuse projects and Singapore's NEWater facilities represent the regulatory frontier, with microbial and chemical benchmarks exceeding conventional drinking water standards.
- Agricultural Irrigation:Tolerates higher salinity and nutrient loads, favoring lower-cost biological treatment with minimal post-processing.
- Recreational Water:Balances aesthetic clarity with disinfection requirements for golf courses, artificial lakes, and urban water features.
Industrial process water leads volumes today; potable reuse is climbing the fastest.
End User:
Customer type determines procurement sophistication, with industrial buyers favoring performance contracts and municipalities bound by public tender regulations.
- Industrial Facilities:Energy, pharmaceutical, and electronics manufacturers face intensifying withdrawal limits under US EPA Clean Water Act discharge standards. Zero-liquid-disclosure configurations are concentrating in heavily regulated clusters where thermal evaporators and crystallizers justify their capital intensity through avoided discharge penalties.
- Municipalities:Public utilities manage large-scale infrastructure with 20-30 year asset lifecycles, prioritizing operational reliability over technology novelty. Australia's major utilities are unbundling membrane procurement from technical service contracts, favoring multi-vendor sourcing strategies that fragment supplier relationships.
- Agricultural Sector:Operates at lower treatment sophistication, typically reusing lagoon-treated effluent for non-food crop irrigation.
- Commercial Buildings:Deploys packaged systems for greywater recycling in high-rise developments, particularly in water-stressed Middle Eastern cities.
Municipalities lead volumes today; industrial facilities are expanding most quickly.
Distribution Channel:
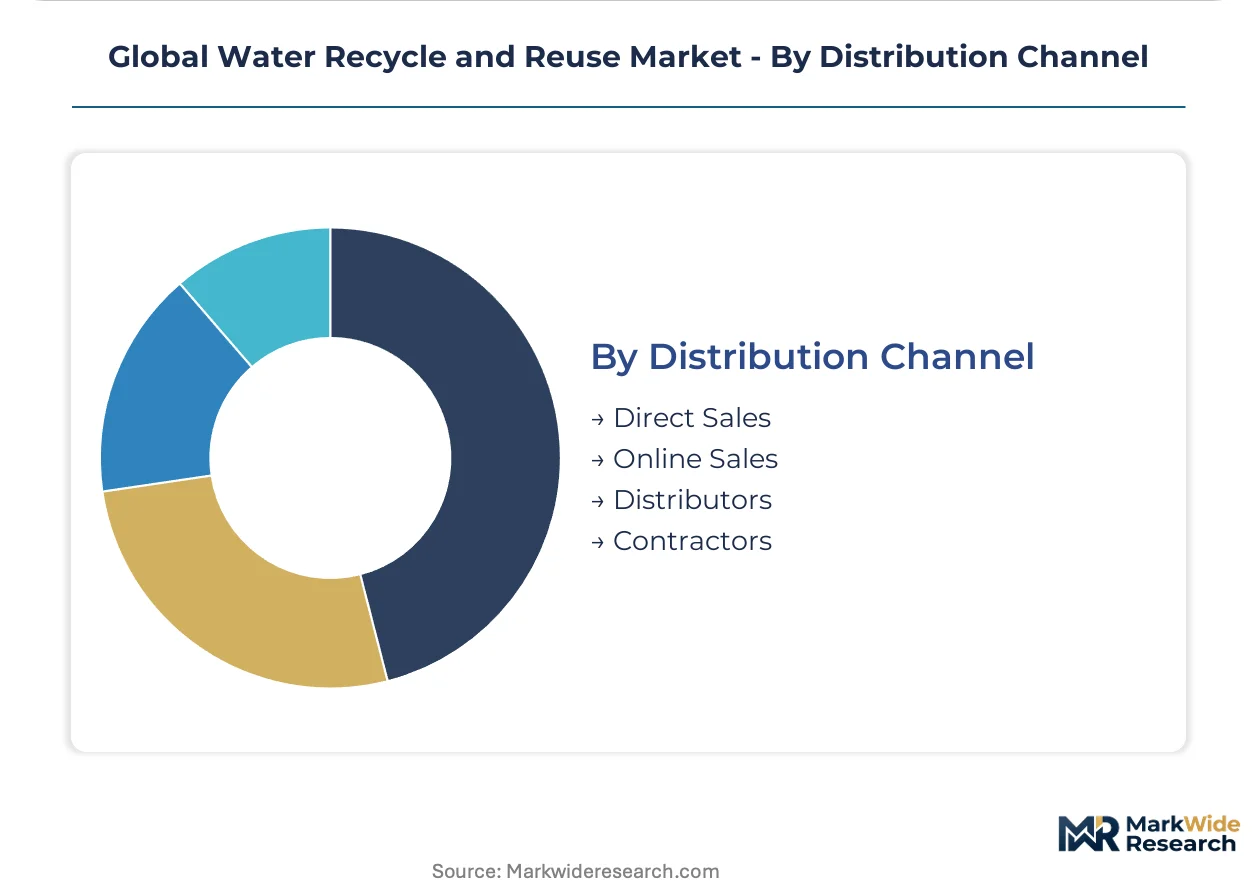
Supply concentration shapes how equipment reaches end-users, with direct relationships dominating complex industrial sales and intermediaries handling standardized municipal products.
- Direct Sales:Engineering teams configure custom treatment trains for large industrial and municipal accounts, embedding themselves in front-end engineering design phases. Veolia and Xylem leverage direct channels to attach long-term service contracts to initial equipment supply.
- Distributors:Maintain regional inventory of standardized membrane elements, pumps, and instrumentation for maintenance and expansion projects. Japanese ceramic membrane manufacturers rely on distributor networks to reach MBR operators across Southeast Asia.
- Contractors:Specify equipment during design-build and EPC project delivery, influencing technology selection without holding inventory risk.
- Online Sales:Handles consumables and replacement components for small-scale commercial and agricultural systems.
Direct sales leads volumes today; distributors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia mandates closed-loop systems for desert megaprojects while Singapore's NEWater facilities set microbial benchmarks that exceed conventional drinking water standards. These contrasting approaches illustrate how arid regions prioritize conservation while dense city-states emphasize potable reuse certification.
United States
California's Title 22 regulations drive municipal utilities toward tertiary treatment upgrades and indirect potable reuse infrastructure. The US EPA enforces Clean Water Act discharge standards that push industrial facilities toward zero-liquid-discharge configurations. Semiconductor fabs in Arizona and Texas face intensifying withdrawal limits, expanding on-site membrane bioreactor capacity.
Singapore
NEWater standards create certification-driven replacement demand for UV and ozone disinfection systems. The national water agency mandates multi-barrier treatment including reverse osmosis and advanced oxidation for indirect potable reuse. Jurong Island's chemical cluster operates integrated water loops that recover process water for industrial cooling.
Saudi Arabia
Qiddiya and NEOM developments mandate closed-loop water systems, creating demand for integrated treatment and brine management. The national regulator enforces discharge standards that concentrate zero-liquid-disclosure adoption in industrial cities. Red Sea coastal projects deploy membrane distillation for high-salinity wastewater recovery.
China
MEE industrial wastewater reuse quotas under dual carbon goals tighten market access for non-compliant equipment suppliers. Facilities in the Yangtze River Economic Belt must achieve mandated reuse rates or face production curtailments. Semiconductor manufacturers in Shanghai and Wuxi retrofit reverse osmosis trains with advanced oxidation post-treatment.
Germany
The EU Urban Wastewater Treatment Directive mandates nutrient removal thresholds that expand tertiary treatment demand across industrial clusters. Chemical manufacturers in the Rhine-Ruhr region invest in membrane bioreactor systems to meet discharge limits. Bavaria's automotive plants recover process water for paint shop operations through closed-loop configurations.
Global Water Recycle and Reuse Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated service platforms capturing recurring revenue while equipment-only vendors face compressed sales cycles. The vendor base organizes around three archetypes: multinational environmental conglomerates with bundled service offerings, pure-play technology specialists focused on membrane or digital systems, and regional engineering contractors delivering design-build projects. Competitive moves concentrate on attaching long-term service contracts to initial equipment supply and unbundling aftermarket membrane procurement from technical support.
Within the integrated service tier, Veolia and Xylem occupy positions that exemplify platform-based competition, leveraging direct sales channels to embed themselves in front-end engineering design phases. Siemens anchors the automation and control systems segment for industrial water loops, representing the capital-equipment archetype that supplies large-scale distributed control architectures.
| Leading Market Players |
|---|
| Veolia |
| Xylem |
| Ecolab |
| DuPont |
| Pentair |
| Siemens |
| Hitachi |
| Aquatech |
| Alfa Laval |
| Others |
Value Chain & Pricing Dynamics
Polymer membrane feedstock costs originating from petrochemical complexes in the Middle East and East Asia cascade through three distinct pricing tiers for water reuse systems, with ceramic membrane alternatives commanding premiums that reflect Japan's specialized manufacturing concentration and California's Title 22 compliance mandates.
Pricing Analysis
Capacity additions in China are reshaping price floors for standardized membrane bioreactor systems while specialized reverse osmosis trains for semiconductor fabs retain pricing power. Project-based contracting dominates municipal procurement, with price differentiation hinging on certification tier—NEWater-grade UV disinfection systems versus agricultural irrigation baselines—and after-sales service bundling. Pricing pressure stems from unbundling trends in Australia and Singapore, where utilities separate membrane procurement from technical support. Industrial facilities show lowest price sensitivity due to avoided discharge penalty economics, while agricultural buyers prioritize capital minimization over performance guarantees.
Supply Chain Analysis
Freight costs for ceramic membrane elements from Japan and polymer modules from Germany compress margins for Southeast Asian project developers serving Saudi Arabia's NEOM and Qiddiya mandates. Supply concentration rests on Japan for specialized ceramic substrates, the United States for advanced oxidation catalysts, and Germany for automation control systems. Single-source vulnerability runs through Japanese ceramic manufacturers serving the high-salinity industrial segment. Distribution runs through direct sales channels for large industrial accounts, with regional distributors handling standardized municipal maintenance inventory across the Middle East and Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Saudi Arabia's closed-loop mandates and California's Title 22 discharge limits create compliance-driven replacement cycles that offset pricing softness in less regulated jurisdictions.
For Market Incumbents: Hedge membrane replacement revenue erosion by attaching predictive maintenance subscriptions to initial equipment supply, countering the unbundling threat from Australian and Singaporean utilities. Deepen backward integration into antiscalant chemistry production to capture value that currently flows to third-party suppliers serving Taiwan's semiconductor fabs. For New Entrants and Emerging Players: The premium-to-economy price gap in commercial building greywater systems offers entry points for packaged MBR units in water-stressed Middle Eastern cities. Target agricultural irrigation retrofit opportunities in India's industrial corridors, where lower treatment sophistication tolerates standardized biological systems. Pursue channel partnerships with regional EPC contractors to bypass entrenched direct sales relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where automation engineering talent scarcity constrains system integrator capacity expansion. Long-term viability favors platforms combining hardware supply with recurring service revenue over pure equipment vendors facing compressed sales cycles. Monitor China's MEE enforcement intensity as the signal indicating whether Yangtze River Economic Belt retrofit demand sustains or contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contract Expansion | Veolia and Xylem attach long-term membrane maintenance to initial equipment supply, shifting municipal procurement from capex to opex. |
| Digital Twin Platform Integration | Real-time sensor networks with predictive analytics enable condition-based replacement for Singapore's NEWater facilities. |
| Backward Integration into Antiscalant Chemistry | RO system suppliers capture value currently flowing to third-party chemical suppliers serving Taiwan semiconductor fabs. |
| Geographic Manufacturing Footprint Expansion | Regional production in Saudi Arabia reduces freight exposure for megaproject developers serving Qiddiya and NEOM. |
| Certification-Driven Product Tiering | UV and ozone systems segmented by California Title 22 versus agricultural irrigation standards capture compliance premiums. |
Study Parameters
Bottom-up industrial facility and municipal utility modeling reconciled against top-down equipment shipment tracking forms the analytical core. Primary interviews with membrane system procurement managers, water treatment plant engineers, EPC project developers, and aftermarket service directors were validated against secondary sources including US EPA discharge permit databases, China's MEE enforcement bulletins, Singapore PUB technical standards, and EU Urban Wastewater Treatment Directive implementation reports. Triangulation across these sources calibrated installation base estimates and replacement cycle assumptions.
Input-output matrices map technology adoption rates across membrane bioreactor, reverse osmosis, UV disinfection, and advanced oxidation segments against end-use applications and geographic regulatory clusters. CAGRs were derived from fitted adoption curves incorporating enforcement intensity variables for China's dual carbon goals and Saudi Arabia's megaproject mandates. Forecast inputs include semiconductor fab capacity expansion timelines in Taiwan and South Korea, and California municipal bond issuance for indirect potable reuse infrastructure.
The model assumes a particular technology adoption path; alternative pathways for forward osmosis draw solute regeneration would alter the outlook if Permian Basin pilots achieve cost parity with thermal desalination. Forecasts reflect assumptions about regulatory enforcement consistency and polymer feedstock price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market