
 US Water Purifier Market | 2026-2036
US Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
US Water Purifier Market Intelligence
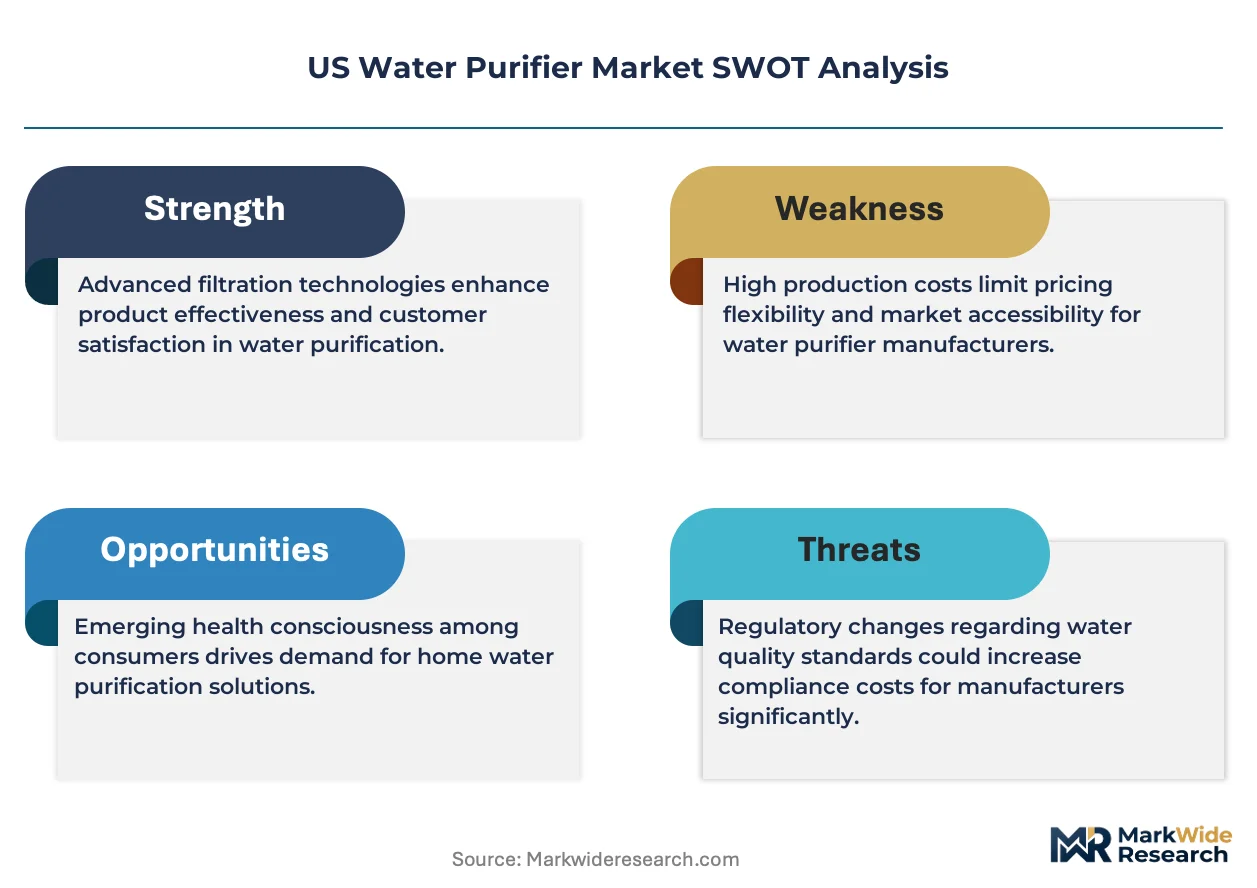
NSF/ANSI Standard 53 certification for cyst and lead reduction is unwinding the competitive landscape for entry-level purifier brands. Culligan International Company leverages its dealer network and commercial service contracts to dominate the institutional segment. A.O. Smith Corporation anchors its position through captive manufacturing of reverse osmosis membranes and tank components. Pentair PLC competes on system integration, bundling filtration with smart-home monitoring platforms for residential installers.
A water purifier is a treatment device engineered to remove particulates, chemical contaminants, and microbial pathogens from potable water through physical barriers, adsorption media, or semipermeable membranes, typically achieving total dissolved solids reduction below 500 ppm for residential compliance. Its primary commercial purpose is to deliver contaminant-free water that meets or exceeds EPA Safe Drinking Water Act standards at the point of use or point of entry. Reverse osmosis systems command the deepest margin pools due to membrane replacement cycles and proprietary cartridge lock-in, while activated carbon units remain the volume leader in countertop and pitcher formats. Ultraviolet purifiers represent the fastest-growing installation type for under-sink configurations in regions with documented Cryptosporidium outbreaks.
EPA enforcement of PFAS maximum contaminant levels, FDA oversight of bottled water equivalency claims, and state-level lead service line replacement mandates in Michigan, Illinois, and New Jersey collectively expand the addressable market for certified point-of-use systems. NSF International testing protocols and WaterSense labeling criteria function as de facto gatekeepers for retail shelf access and municipal procurement eligibility. Stakeholders must monitor emerging state legislation on microplastics filtration requirements and position cartridge compatibility strategies before patchwork standards harden into federal rulemaking.
Market Dynamics
EPA enforcement of PFAS maximum contaminant levels is forcing wholesale replacement schedules across municipal and residential filtration infrastructure, compressing replacement cycles from ten-year horizons to immediate procurement timelines.
Growth Catalysts
- PFAS Rulemaking:EPA finalized maximum contaminant levels for six per- and polyfluoroalkyl substances in drinking water, compelling utilities and homeowners to deploy certified reverse osmosis and activated carbon systems.
- Aquifer Stress:Depletion of the Ogallala Aquifer and Central Valley groundwater basins concentrates demand for point-of-use treatment in Texas, California, and agricultural corridor households.
- Lead Service Line Mandates:Michigan, Illinois, and New Jersey state legislation mandates lead pipe replacement, accelerating point-of-entry filtration installation during infrastructure transitions.
Market Restraints
- Membrane Supply Concentration:Thin-film composite reverse osmosis membrane production clusters among East Asian specialty chemical manufacturers, exposing US system assemblers to input volatility.
- NSF Certification Friction:NSF/ANSI Standard 53 and 58 testing protocols require six-to-twelve month validation timelines, freezing out smaller entrants lacking capital for extended compliance runway.
- Bottled Water Substitution:Bulk bottled water delivery retains cost advantage in rental housing and transient populations, capping household penetration in lower-income census tracts.
Strategic Opportunities
- Smart-Home Integration:WiFi-enabled filter monitoring and cartridge auto-replenishment converges with residential IoT platforms, opening recurring revenue streams for installer networks.
- Rural Well Water:Unregulated private well systems serving fifteen percent of US households lack treatment infrastructure, creating white space for packaged ultraviolet and sediment filtration units.
- IRA Tax Credits:Inflation Reduction Act residential clean energy credits extend to water efficiency improvements, subsidizing point-of-entry system adoption in qualified census tracts.
Industry Challenges
- Certification Bottleneck:EPA's new PFAS testing requirements and state-level microplastics legislation fragment compliance standards, forcing manufacturers to maintain multiple cartridge SKUs.
- Installer Capacity Constraints:Residential plumbing contractors face skilled technician shortages, elongating installation backlogs for under-sink and whole-house configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Water Purifier Market |
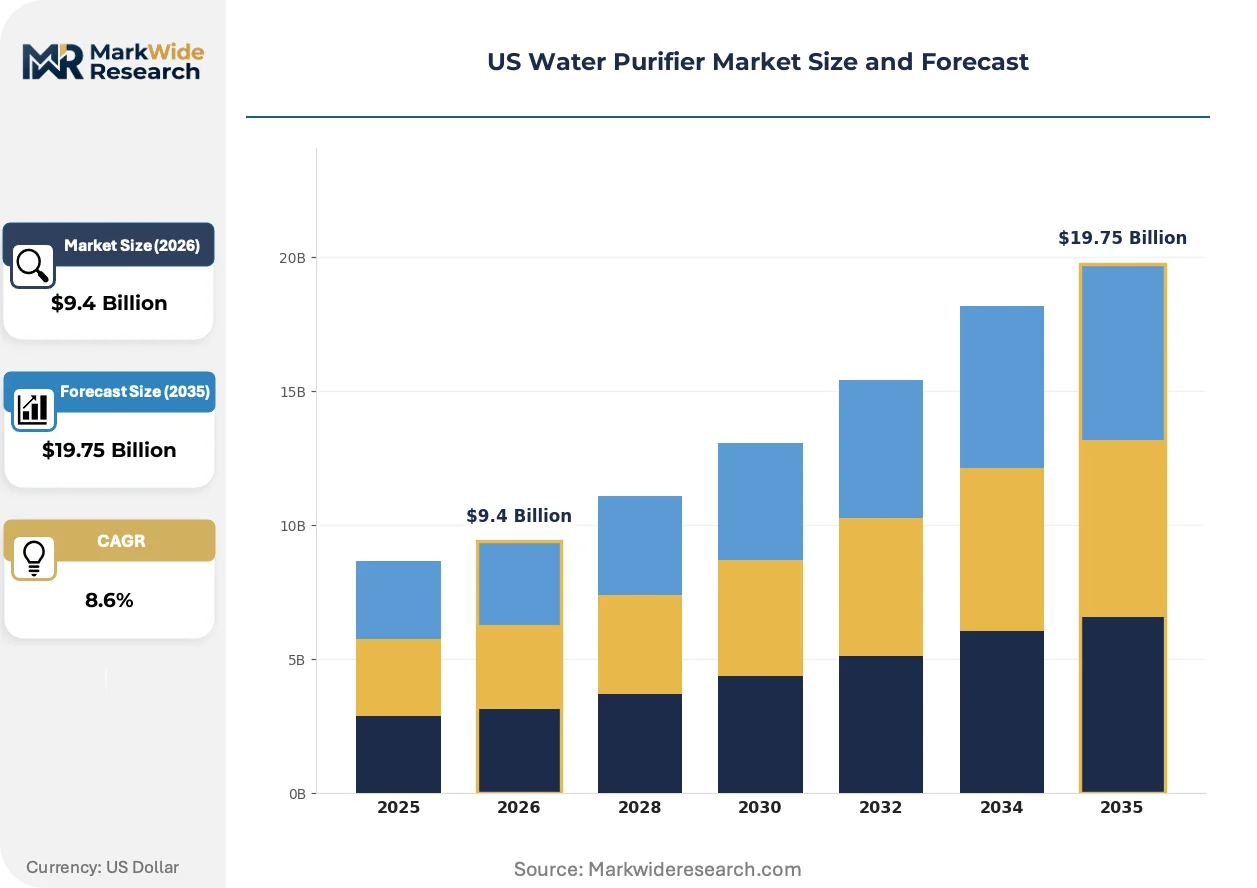
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $19.75 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Ultraviolet, Activated Carbon, Ceramic, Ion Exchange Application: Residential, Commercial, Institutional, Hospitality, Food & Beverage Installation Type: Under Sink, Countertop, Wall Mounted, Faucet Mounted, Portable Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Direct Sales, Wholesale Suppliers |
| Companies Covered | Culligan International Company, A.O. Smith Corporation, 3M Purification Inc., Pentair PLC, Brita GmbH, Aquasana Inc., Helen of Troy Limited, The Clorox Company, Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Water Purifier Market Strategic Shifts & Innovations
Tankless reverse osmosis systems are compressing form factors and eliminating storage contamination risks. Smart monitoring platforms now predict cartridge exhaustion. Certification requirements are hardening into procurement gatekeepers.
Ultraviolet-C LED disinfection is fragmenting the under-sink category by eliminating mercury lamp disposal burdens and enabling instant-on operation without warm-up latency. California and Florida installers report rapid specification shifts toward LED-based units for residential kitchen retrofits. Mercury-free certification is fragmenting competitive positioning between incumbent lamp manufacturers and semiconductor entrants.
EPA's finalized PFAS National Primary Drinking Water Regulation imposes strict monitoring and treatment obligations on public water systems serving over one hundred million Americans. Municipal procurement now mandates NSF/ANSI 53-certified systems for compliance demonstration. Water utilities in contaminated groundwater zones are accelerating point-of-entry filtration deployment ahead of enforcement deadlines.
Subscription cartridge replenishment is displacing retail replacement purchases among reverse osmosis owners, locking households into proprietary filter formats. Amazon and direct-to-consumer channels capture growing share of replacement revenue, squeezing big-box retail margins. Texas and Arizona metropolitan markets show highest subscription attach rates due to hard water accelerating cartridge consumption.
US Water Purifier Market Segmentation
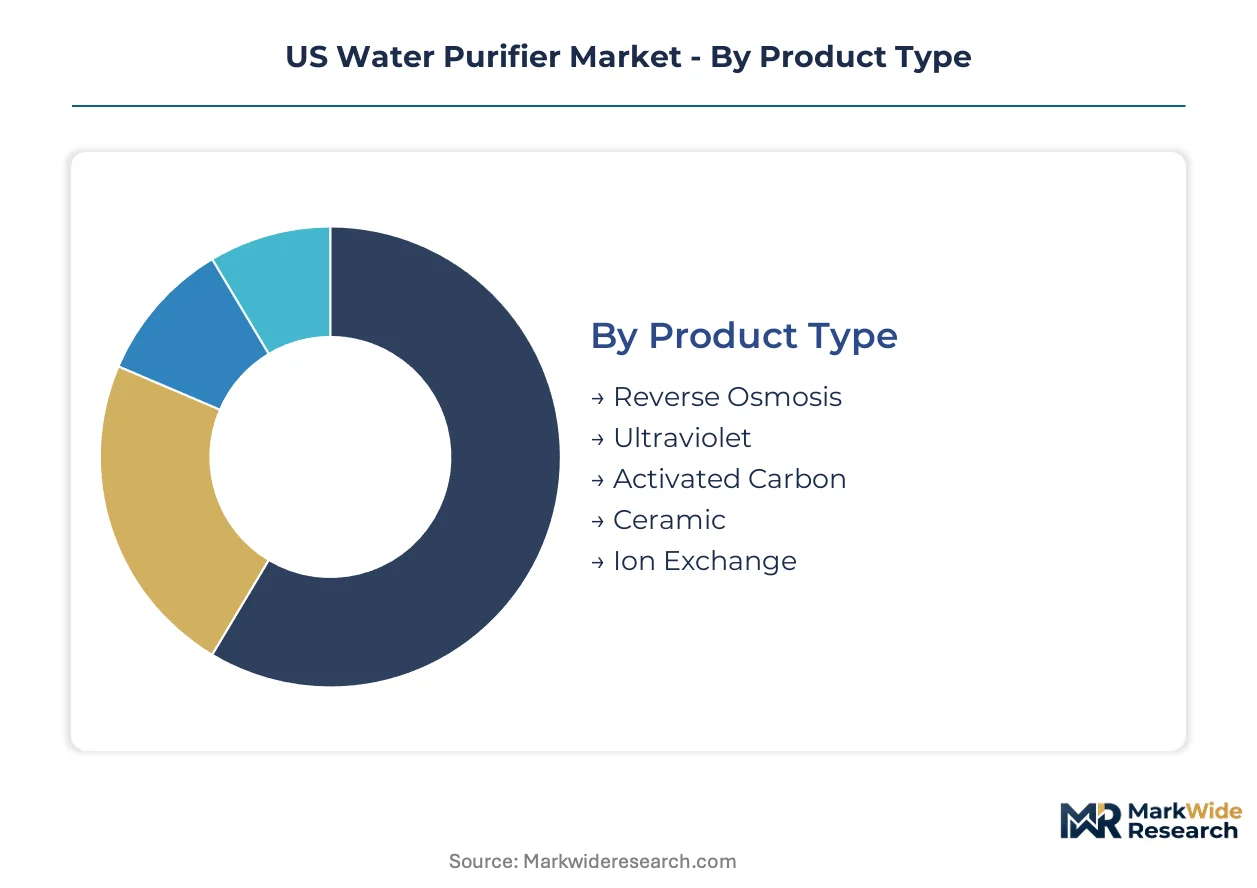
Segmentation in the US water purifier market reveals distinct procurement patterns across residential, commercial, and institutional buyers. Product specifications, installation constraints, and distribution access vary sharply by end-use context. Understanding these divides exposes where margin pools concentrate and where volume expansion faces structural barriers.
Product Type:
Domestic manufacturing capacity concentrates on activated carbon and ceramic housings, while thin-film composite membranes for reverse osmosis systems remain import-dependent from East Asian suppliers.
- Reverse Osmosis:Semi-permeable membranes force water through microscopic pores under pressure, stripping dissolved solids including PFAS compounds below EPA maximum contaminant levels. Demand clusters in California, Texas, and Florida households facing agricultural runoff and aquifer depletion where municipal treatment proves insufficient. Membrane replacement cycles generate recurring revenue streams that deepen customer lock-in for installer networks.
- Ultraviolet:UV-C LED and mercury-vapor lamp systems neutralize Cryptosporidium, Giardia, and bacterial pathogens without chemical additives. Installers in outbreak-documented regions specify under-sink UV configurations for private well owners lacking centralized disinfrastructure. The shift toward mercury-free LED formats accelerates specification changes in California and Florida residential retrofits.
- Activated Carbon:Adsorptive media removes chlorine, volatile organic compounds, and taste-odor contaminants through porous carbon block or granular configurations. Pitcher and countertop formats dominate volume sales through mass retail channels.
- Ceramic:Sintered diatomaceous earth or clay filters provide mechanical filtration for sediment and cyst reduction without electricity dependency. Rural well-water households in unregulated groundwater zones favor gravity-fed ceramic systems for off-grid reliability.
- Ion Exchange:Resin beads swap calcium and magnesium ions for sodium or hydrogen equivalents, softening hard water and reducing scale accumulation. Texas and Arizona metropolitan markets show elevated specification rates due to extreme groundwater hardness accelerating resin exhaustion cycles.
Reverse Osmosis commands the established base. The steepest expansion runs through Ultraviolet.
Application:
Cost tier stratification separates premium whole-house systems for affluent homeowners from economy pitcher formats in rental housing and transient populations.
- Residential:Point-of-use and point-of-entry installations serve single-family homes, condominiums, and multi-unit dwellings with NSF-certified contaminant reduction. Southwest households replacing aging systems drive specification shifts toward tankless reverse osmosis and smart-monitored configurations. IRA tax credits for residential clean energy improvements subsidize point-of-entry adoption in qualified census tracts.
- Commercial:Offices, retail spaces, and light industrial facilities deploy bottle-filling stations and breakroom filtration to displace bulk bottled water contracts. Leasing arrangements and service-inclusive procurement dominate this segment, favoring vendors with captive technician networks.
- Institutional:Schools, healthcare facilities, and government buildings mandate NSF/ANSI 53 or 58 certification for compliance demonstration. Culligan International leverages its dealer network and service contracts to dominate municipal and institutional procurement cycles.
- Hospitality:Hotels, resorts, and restaurants require aesthetic and safety filtration for guest-facing water service and food preparation. Brand standards at national chains drive centralized specification decisions with limited installer discretion.
- Food & Beverage:Breweries, coffee roasters, and packaged food processors demand mineral-controlled water profiles for product consistency. FDA oversight of bottled water equivalency claims compels certified treatment infrastructure for in-house filling operations.
Residential absorbs the volume concentration. Institutional procurement carries the premium pricing power.
Installation Type:
Maturity gradients separate established under-sink configurations from emerging portable formats targeting rental and travel use cases.
- Under Sink:Concealed plumbed systems deliver filtered water through dedicated faucets or refrigerator lines, requiring professional installation and permanent cabinetry modification. Skilled technician shortages elongate installation backlogs in major metropolitan markets, constraining near-term volume expansion.
- Countertop:Free-standing electric or gravity-fed units require no plumbing modifications, appealing to renters and temporary residents. Lower initial cost and mobility trade off against reduced flow rates and aesthetic intrusion.
- Wall Mounted:Commercial and institutional bottle-filling stations mount at ergonomic heights for high-traffic corridors and fitness facilities. Specification concentrates in LEED-certified building projects seeking WaterSense-labeled efficiency credits.
- Faucet Mounted:Diverter valves attach directly to existing tap spouts, offering entry-level filtration without under-sink complexity. Quick installation appeals to cost-conscious households in lower-income census tracts where bottled water substitution remains prevalent.
- Portable:Battery-powered or manual-pump units serve recreational vehicles, emergency preparedness kits, and international travel. Emerging demand from climate-driven disaster response planning expands addressable use cases beyond traditional residential markets.
Under Sink retains the revenue depth. Portable formats are climbing the fastest.
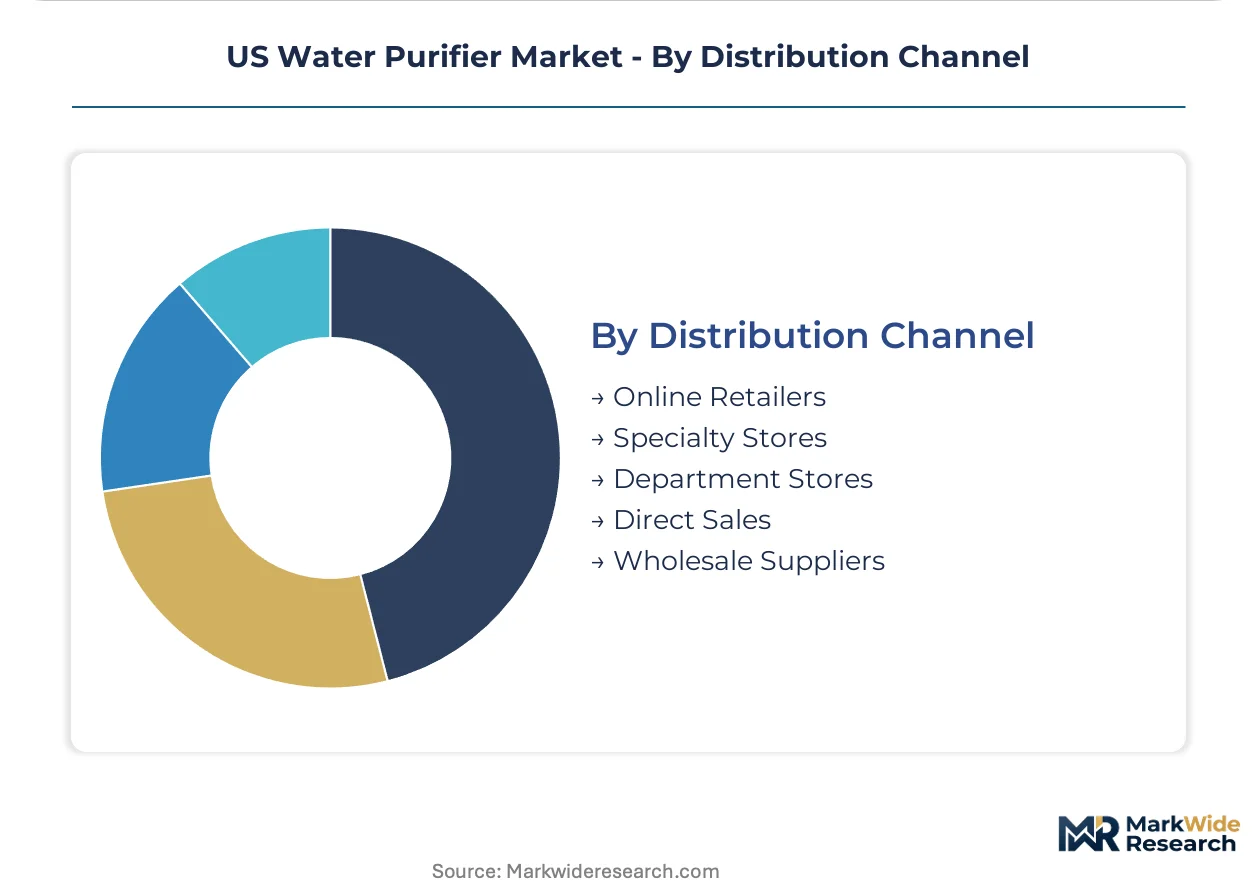
Distribution Channel:
Supply concentration in membrane manufacturing shapes channel power, with direct sales and wholesale suppliers capturing specification-intensive commercial and institutional volumes.
- Online Retailers:Amazon and direct-to-consumer platforms capture replacement cartridge revenue through subscription auto-replenishment, squeezing big-box retail margins. Texas and Arizona show highest subscription attach rates due to hard water accelerating consumption cycles.
- Specialty Stores:Kitchen and bath showrooms, plumbing supply houses, and water treatment dealers provide specification guidance and installation referrals. NSF certification visibility and hands-on product comparison drive premium segment conversion.
- Department Stores:Mass merchants move volume in pitcher and countertop formats with lower price points and minimal service attachment. Seasonal promotional cycles and co-op marketing funds determine shelf placement economics.
- Direct Sales:Manufacturer-employed or contracted sales forces target institutional and commercial accounts with customized proposal development and service bundling. Pentair PLC competes on system integration, bundling filtration with smart-home monitoring platforms for residential installer networks.
- Wholesale Suppliers:Plumbing and HVAC distributors stock point-of-entry systems, components, and replacement cartridges for contractor resale. Inventory concentration in membrane and housing SKUs reflects lead time exposure from East Asian supply sources.
Online Retailers are gaining share fastest. Direct Sales defends the high-value institutional base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in the Southwest and agricultural corridors drive replacement demand, while municipal procurement concentrates in Great Lakes and Northeast states confronting legacy contamination.
California
Central Valley agricultural runoff and aquifer depletion strain municipal treatment capacity. EPA PFAS maximum contaminant levels compel utilities in Fresno and Bakersfield to deploy certified point-of-entry systems. Los Angeles and San Diego metropolitan installers report rapid specification shifts toward tankless reverse osmosis configurations.
Texas
Ogallala Aquifer depletion and extreme groundwater hardness accelerate residential point-of-use adoption. State-level water infrastructure grants subsidize filtration deployment in rural counties. Houston and Dallas-Fort Worth contractor networks face skilled technician shortages elongating installation backlogs.
Florida
Documented Cryptosporidium outbreaks and saltwater intrusion into coastal aquifers drive ultraviolet and reverse osmosis demand. Department of Environmental Protection enforcement of revised treatment standards pressures utilities in Tampa and Miami-Dade. Orlando metropolitan installers specify mercury-free UV-C LED systems for residential kitchen retrofits.
Michigan
Lead service line replacement mandates and legacy PFAS contamination in industrial corridors create dual procurement pressure. State legislation accelerates point-of-entry filtration installation during infrastructure transitions. Detroit and Grand Rapids municipal procurement cycles favor vendors with captive service technician networks.
New Jersey
Industrial corridor PFAS plumes and combined sewer overflow infrastructure strain existing treatment capacity. State Department of Environmental Protection mandates drive specification toward NSF/ANSI 53-certified systems. Newark and Camden utility districts accelerate point-of-entry deployment ahead of federal enforcement deadlines.
US Water Purifier Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive component manufacturing and specialized water treatment dealers with service-contract depth. Consolidation pressure concentrates among membrane-dependent system assemblers exposed to East Asian supply volatility. Three archetypes dominate: integrated membrane manufacturers, dealer-network service specialists, and smart-home platform bundlers. Competitive moves center on backward integration into cartridge production and subscription-based filter replenishment models.
Among diversified industrial conglomerates, 3M Purification Inc. and A.O. Smith Corporation exemplify the captive-manufacturing archetype through in-house membrane and tank component production. Pentair PLC occupies a position within the system-integration tier, bundling filtration hardware with monitoring platforms for installer networks. Culligan International Company anchors the dealer-network specialist category, leveraging commercial service contracts to dominate institutional procurement cycles.
| Leading Market Players |
|---|
| Culligan International Company |
| A.O. Smith Corporation |
| 3M Purification Inc. |
| Pentair PLC |
| Brita GmbH |
| Aquasana Inc. |
| Helen of Troy Limited |
| The Clorox Company |
| Whirlpool Corporation |
| Others |
Cost & Logistics Intelligence
Thin-film composite membrane substitution for ceramic and carbon block media simultaneously shifts procurement geography toward East Asian specialty chemical manufacturers and compresses margin pools for US system assemblers exposed to import volatility. This input transition forces pricing models to absorb currency fluctuation and tariff exposure while cartridge replenishment subscriptions attempt to lock in recurring revenue streams.
Pricing Analysis
Cost-plus contracts with East Asian membrane suppliers indexed to petrochemical feedstock benchmarks dominate procurement for reverse osmosis system assemblers. Price differentiation separates NSF/ANSI 58-certified premium tiers from uncertified economy units, with certification investment and smart-home integration bundling commanding installer premiums. Pricing pressure stems from Amazon and direct-to-consumer channels capturing replacement cartridge share, squeezing big-box retail margins. Municipal and institutional buyers show lowest price sensitivity due to compliance mandates, while rental housing households in lower-income census tracts remain highly sensitive to upfront system costs.
Supply Chain Analysis
Strait of Malacca transit underwrites thin-film composite membrane delivery schedules for US system assemblers, exposing lead times to regional port congestion and geopolitical friction. Manufacturing concentration clusters in South Korea, Japan, and China for membrane production, while domestic capacity concentrates on activated carbon block extrusion and polypropylene housing injection molding. Raw material dependencies include polyamide thin-film chemistry, coconut shell activated carbon, and UV-C LED semiconductor substrates. Single-source vulnerability concentrates in specialty membrane chemistry where patent-protected formulations limit supplier alternatives. Distribution runs through plumbing and HVAC wholesale distributors stocking components for contractor resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA PFAS maximum contaminant level enforcement constitutes a regulatory inflection disrupting ten-year replacement cycles into immediate procurement timelines, creating compressed demand windows for certified system providers. This enforcement architecture positions the market for sustained expansion as municipal and residential infrastructure undergoes wholesale filtration upgrades.
For Market Incumbents: Fortify captive membrane manufacturing capabilities or secure long-term supply agreements with East Asian specialty chemical producers to defend against input volatility threatening margin stability. Accelerate NSF/ANSI 53 and 58 certification pipelines to maintain procurement eligibility as state-level microplastics legislation fragments compliance standards. Deepen installer network relationships to capture point-of-entry system deployment during lead service line replacement mandates in Michigan, Illinois, and New Jersey.
For New Entrants and Emerging Players: Lead with mercury-free UV-C LED configurations targeting California and Florida residential retrofit markets where specification shifts favor semiconductor-based disinfection over legacy lamp formats. Target rural well-water households in unregulated groundwater zones with packaged ultraviolet and sediment filtration units, exploiting white space where fifteen percent of US households lack treatment infrastructure. Deploy direct-to-consumer subscription cartridge replenishment models to bypass wholesale distributor gatekeepers and capture recurring revenue attach.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed dealer-network specialists holding commercial service contracts in institutional procurement channels. Long-term viability over a five-to-ten year horizon rests on positioning for federal microplastics rulemaking convergence and smart-home integration platform consolidation. Acquisition targets should demonstrate captive technician networks in Texas and California metropolitan markets where skilled installer scarcity elongates installation backlogs. Watch state-level lead service line replacement acceleration as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive polyamide thin-film production insulates A.O. Smith and 3M Purification from East Asian supply volatility. |
| Smart-Home Platform Integration | Pentair PLC bundles WiFi-enabled filter monitoring with residential IoT platforms to deepen installer network lock-in. |
| Subscription Cartridge Replenishment | Amazon and direct-to-consumer channels capture replacement revenue through auto-replenishment, squeezing retail margins. |
| NSF/ANSI Certification Acceleration | State-level microplastics legislation fragments standards, forcing multiple cartridge SKU maintenance for compliance coverage. |
| Rural Well-Water Market Entry | Unregulated private well systems serving fifteen percent of US households create white space for packaged UV filtration units. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with residential plumbing contractors, municipal water utility procurement officers, NSF International certification engineers, and wholesale distributor inventory managers. Secondary validation drew from EPA enforcement filings, state-level lead service line replacement mandate documentation, SEC 10-K disclosures from diversified industrial conglomerates, and WaterSense labeling criteria databases. Bottom-up triangulation across point-of-use and point-of-entry installation volumes converged with top-down market sizing derived from membrane import customs data and activated carbon block manufacturing capacity surveys.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, application context, installation configuration, and distribution channel access. CAGRs were derived from regression analysis against EPA compliance deadline schedules, IRA tax credit eligibility expansion, and smart-home IoT platform penetration curves. Industry-specific inputs incorporated Ogallala Aquifer depletion rates, Cryptosporidium outbreak documentation, and hard water geography indices affecting cartridge consumption velocity.
Underlying assumptions cover continued EPA PFAS enforcement trajectory, IRA tax credit program stability, and absence of catastrophic membrane supply disruption, with deviation risk concentrated in tariff escalation, state-level microplastics rulemaking timing, and installer technician labor market tightness. Practitioners should keep alternative scenarios live as federal microplastics legislation convergence and East Asian supply chain reconfiguration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Home Water Softener System Market
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Home Water Filtration Unit Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Plant Based Water Filter Market