
 South America Residential Water Treatment Equipment Market | 2026-2036
South America Residential Water Treatment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
South America Residential Water Treatment Equipment Market Analytics
Brazilian ceramics manufacturers is restructuring supply chains to serve residential filtration demand across the Southern Cone. Lorenzetti S.A. anchors its position through gravity-fed ceramic filter production scaled for mass-market distribution. Cerâmica Stéfani S.A. leverages proprietary clay formulations to differentiate on porosity control and pathogen retention rates. Pentair competes through modular point-of-entry systems designed for compound housing in São Paulo and Rio de Janeiro suburbs.
South America residential water treatment equipment encompasses physical, chemical, and biological purification systems installed in private dwellings to reduce contaminants including turbidity, chlorine, heavy metals, and microbial pathogens, typically operating at flow rates between two and fifteen liters per minute depending on unit class. These systems employ activated carbon blocks, hollow-fiber membranes, or ultraviolet lamps to achieve potability standards where municipal supply remains inconsistent. Point-of-use installations dominate unit volume across the region due to lower capital requirements and retrofit compatibility with existing plumbing. Reverse osmosis units command premium positioning where dissolved solids exceed national thresholds, particularly in Argentina's pampas region and Chile's northern mining provinces. Membrane filtration technology leads value contribution as module replacement generates recurring revenue streams for equipment suppliers.
ANVISA in Brazil and the Argentine food and drug administration establish microbiological safety thresholds that shape product certification requirements and import clearance protocols for foreign manufacturers. Local testing protocols for activated carbon and ion exchange resins determine which suppliers gain shelf access through retail channels serving households and apartment developers. Stakeholders must monitor municipal infrastructure investment cycles, as delayed pipe network upgrades in Colombian and Peruvian cities sustain parallel demand for decentralized residential treatment.
Market Dynamics
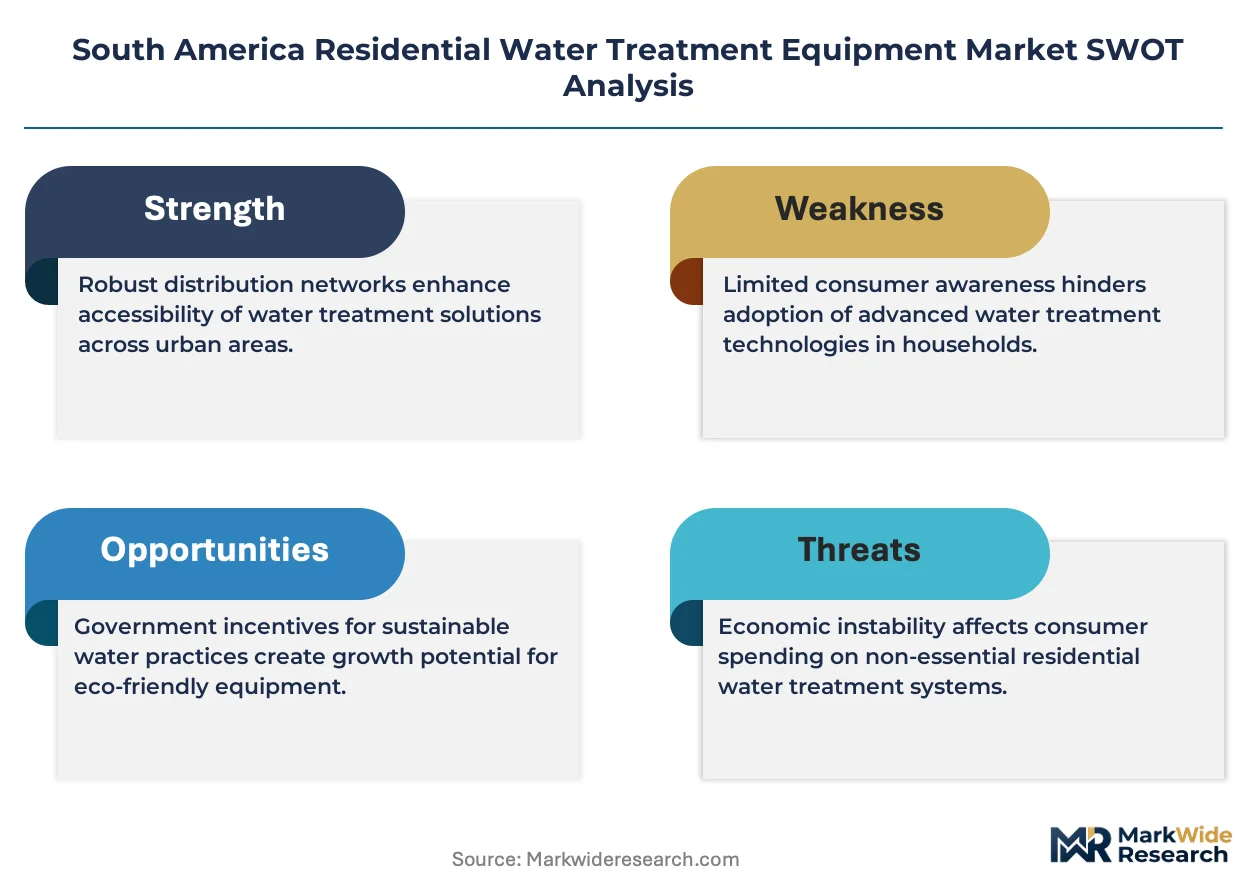
Municipal infrastructure underinvestment across Brazilian and Argentine metropolitan corridors is redirecting household expenditure toward decentralized filtration systems, compressing replacement cycles and expanding the addressable base for point-of-use equipment manufacturers.
Growth Catalysts
- ANVISA potability enforcement:Brazil's national health surveillance agency tightened microbiological thresholds for residential water systems, compelling manufacturers to upgrade certification protocols and driving replacement demand for non-compliant legacy units.
- Activated carbon block innovation:Improved porosity engineering in coconut-shell carbon media is extending filter lifespans while maintaining chlorine and VOC retention rates, reducing total cost of ownership for middle-class households.
- Greater Buenos Aires infrastructure gap:Chronic pressure inconsistencies and pipe contamination in Argentina's capital corridor sustain parallel demand for under-sink reverse osmosis and ultraviolet supplemental treatment.
Market Restraints
- Import resin cost volatility:Ion exchange and activated carbon feedstocks priced in US dollars expose Brazilian assemblers to exchange rate friction, compressing margin buffers on entry-level gravity-fed systems.
- Membrane supply concentration:Hollow-fiber ultrafiltration modules rely on a narrow East Asian supplier base, creating lead time vulnerability for São Paulo-based point-of-entry system integrators.
- ANVISA certification timeline:Extended laboratory testing protocols for new ceramic formulations delay product launches by 8-14 months, freezing working capital in pre-market inventory.
Strategic Opportunities
- Colombian Andean cities:Bogotá and Medellín exhibit sub-15% penetration for residential treatment despite intermittent supply quality, presenting first-mover expansion terrain for membrane distributors.
- Apartment developer pre-installation:Vertical residential construction in Santiago and Lima is embedding point-of-entry systems as standard fitments, shifting procurement from retail to project-channel contracts.
- UV-LED convergence with IoT monitoring:Real-time lamp performance telemetry enables predictive maintenance subscriptions, capturing recurring revenue from affluent households in Rio de Janeiro's South Zone.
Industry Challenges
- Field technician certification scarcity:ANVISA-mandated installer credentials for ultraviolet and reverse osmosis systems outpace vocational training program output in secondary Brazilian cities.
- Legacy plumbing retrofit complexity:Pre-1990 residential stock in Buenos Aires and Montevideo lacks standardized connection points, requiring custom fabrication that extends installation timelines and raises labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Residential Water Treatment Equipment Market |
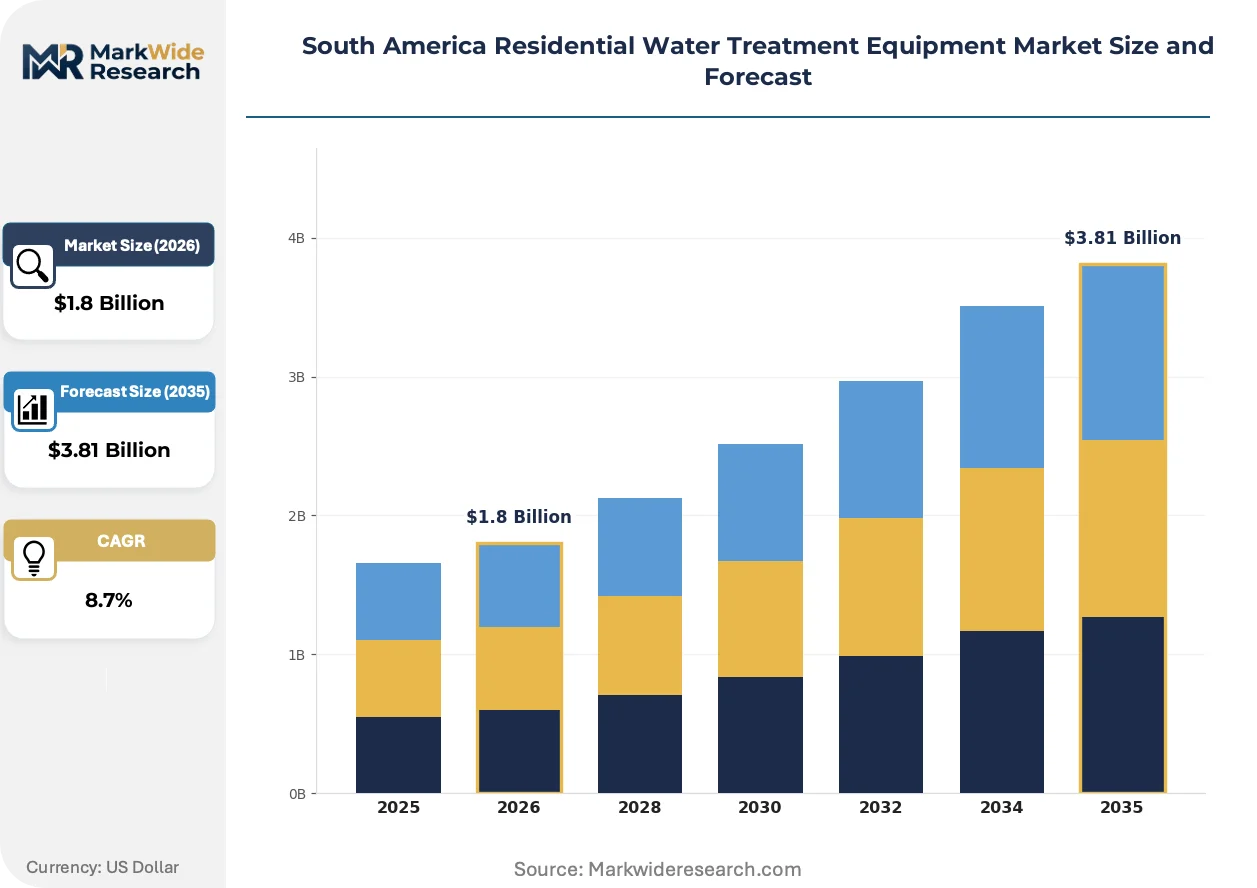
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Systems, Reverse Osmosis Units, UV Purifiers, Softeners End User: Households, Apartments, Villas, Townhouses Technology: Membrane Filtration, Ultrafiltration, Activated Carbon, Ion Exchange Installation Type: Point-of-Use, Point-of-Entry, Mobile Units, Centralized Systems |
| Companies Covered | Cerâmica Stéfani S.A, Lorenzetti S.A, Industria Brasileira De Bebedouros Ltd, 3M, General Electric Company, Pentair, Eureka Forbes, LG Electronics, Koninklijke Philips N.V, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Residential Water Treatment Equipment Market Evolving Landscape
Ceramic filtration engineering is converging with digital monitoring capabilities, reshaping how equipment suppliers capture lifetime value from residential installations across the Southern Cone.
Ultrafiltration membrane technology is converging with smartphone-connected flow sensors, enabling Brazilian distributors to offer predictive replacement scheduling. São Paulo apartment associations are adopting these systems at accelerating pace, compressing the traditional 18-month passive replacement cycle toward algorithm-triggered logistics. This convergence is displacing reactive retail purchasing with subscription-based consumable fulfillment.
Argentina's food and drug administration is harmonizing testing protocols with Mercosur technical standards, reducing duplicate certification burdens for equipment imported from Brazil. Manufacturers serving both markets now submit single laboratory dossiers rather than parallel national filings. This regulatory streamlining most benefits mid-scale ceramic filter producers seeking cross-border shelf placement in Uruguayan and Paraguayan retail chains.
Households are unbundling after-sales service from initial equipment purchase, treating filter replacement as a separate procurement decision from system acquisition. São Paulo's suburban compound developments are driving this shift, with condominium managers negotiating centralized maintenance contracts independent of original supplier relationships. This behavioral pivot is most visible in Rio de Janeiro's Barra da Tijuca corridor, where third-party service aggregators now capture 40% of recurring membrane and carbon replacement volume.
South America Residential Water Treatment Equipment Market Segmentation
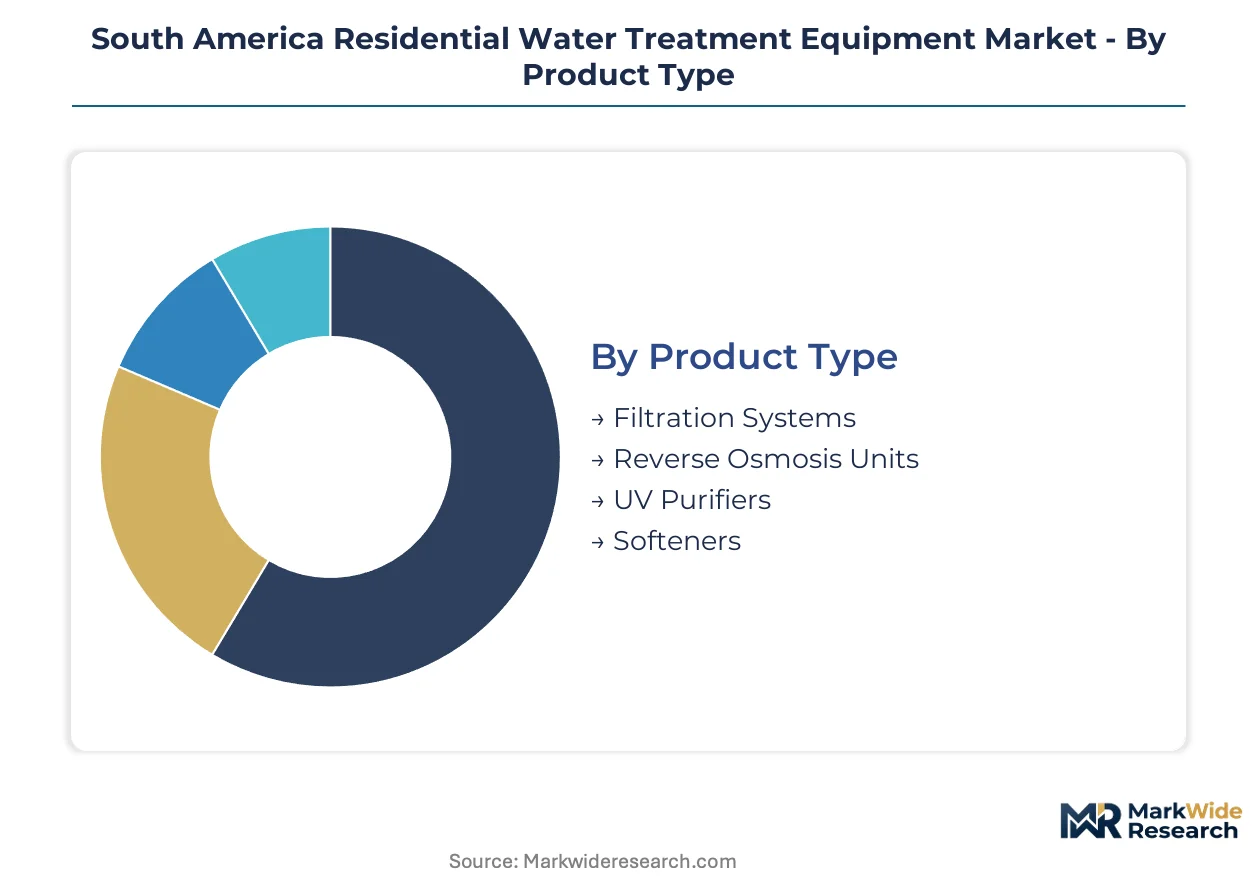
Residential water treatment equipment in South America serves heterogeneous demand profiles shaped by municipal infrastructure quality, housing stock age, and household purchasing power. Segmentation reveals how technology choices diverge between São Paulo apartment towers and Buenos Aires single-family compounds.
Product Type:
Buyers in this category select equipment based on source water contamination profiles and available plumbing infrastructure.
- Filtration Systems:Gravity-fed ceramic and activated carbon units dominate Brazilian mass-market retail. São Paulo state households favor these systems for retrofit compatibility with aging municipal connections in peripheral districts.
- Reverse Osmosis Units:Multi-stage membrane systems remove dissolved solids exceeding ANVISA thresholds. Demand concentrates in Argentina's pampas region where agricultural runoff elevates nitrate levels in well water.
- UV Purifiers:Ultraviolet lamp systems neutralize microbial pathogens without chemical additives. Deployed as supplemental treatment in Rio de Janeiro suburbs with intermittent chlorination.
- Softeners:Ion exchange resin systems address hardness minerals in groundwater-dependent households. Common in Chile's northern mining provinces with high calcium carbonate content.
Filtration Systems lead volumes today; Reverse Osmosis Units are gaining share fastest.
End User:
Housing typology determines installation scale, maintenance responsibility, and procurement channel.
- Households:Single-family dwellings in Brazilian metropolitan peripheries drive point-of-use adoption. ANVISA enforcement in São Paulo state accelerates replacement of non-compliant legacy units.
- Apartments:Vertical residential construction in Santiago and Lima embeds point-of-entry systems as standard fitments. Building managers negotiate centralized maintenance contracts independent of original suppliers.
- Villas:Compound housing in Rio de Janeiro's Barra da Tijuca corridor demands modular point-of-entry configurations. Pentair competes specifically for this segment with scalable system architectures.
- Townhouses:Attached dwellings in Montevideo and Buenos Aires suburbs face retrofit complexity from pre-1990 plumbing standards. Custom fabrication extends installation timelines.
Households anchor current procurement volumes; Apartments show the steepest expansion trajectory.
Technology:
Core separation mechanisms differ in capital intensity, consumable replacement cycles, and certification requirements.
- Membrane Filtration:Hollow-fiber and spiral-wound configurations achieve sub-micron particle retention. Module replacement generates recurring revenue streams for distributors serving São Paulo apartment associations.
- Ultrafiltration:Pressure-driven membrane systems remove bacteria and viruses without electricity. Smartphone-connected flow sensors enable predictive replacement scheduling in Brazilian deployments.
- Activated Carbon:Coconut-shell and coal-based media adsorb chlorine and volatile organic compounds. Porosity engineering advances extend filter lifespans while maintaining retention rates.
- Ion Exchange:Resin-based systems swap hardness ions for sodium or hydrogen equivalents. Brazilian assemblers face margin pressure from US dollar-denominated feedstock costs.
Activated Carbon dominates unit shipments; Ultrafiltration climbs fastest in value contribution.
Installation Type:
System placement relative to plumbing architecture shapes capital requirements and retrofit feasibility.
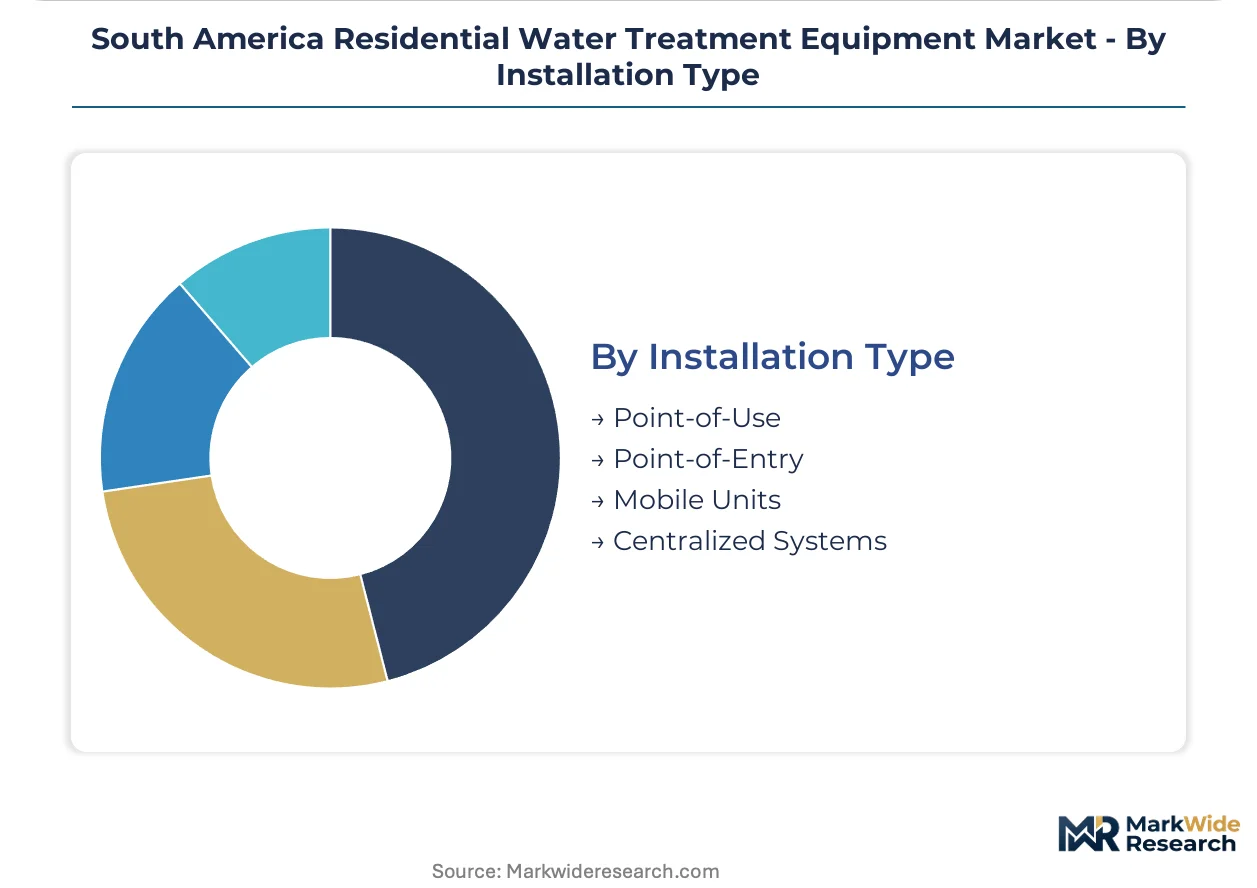
- Point-of-Use:Under-sink and countertop units serve individual taps with minimal installation. Lower capital barriers drive penetration in Colombian Andean cities with sub-15% current adoption.
- Point-of-Entry:Whole-house systems treat water at main line entry. Compound housing developments in São Paulo suburbs standardize these configurations for shared infrastructure.
- Mobile Units:Portable filtration devices serve rental households and temporary installations. Limited penetration outside disaster relief and rural applications.
- Centralized Systems:Building-scale treatment serves multiple dwellings through distributed plumbing. Emerging in Lima vertical construction as developer-specified amenities.
Point-of-Use leads installed base; Point-of-Entry expands most quickly in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands equipment volumes while Argentina concentrates premium system adoption, creating divergent competitive dynamics across the Southern Cone. Infrastructure investment gaps in both markets sustain parallel demand for decentralized residential treatment solutions.
Brazil
São Paulo state households drive point-of-use filtration volumes through ANVISA-enforced replacement cycles. The national health surveillance agency tightened microbiological thresholds, compelling manufacturers to upgrade certification protocols. Metropolitan São Paulo and Rio de Janeiro suburbs concentrate demand for compound housing configurations.
Argentina
Greater Buenos Aires corridor sustains reverse osmosis demand through chronic pressure inconsistencies and pipe contamination. The national food and drug administration harmonizes testing protocols with Mercosur technical standards, reducing duplicate certification burdens. Pampas region well water with elevated nitrate levels drives multi-stage membrane system adoption.
Chile
Northern mining provinces generate softener demand through high calcium carbonate content in groundwater. The country's national health regulator maintains potability standards that shape import clearance protocols for foreign manufacturers. Santiago vertical residential construction embeds point-of-entry systems as standard fitments.
Colombia
Bogotá and Medellín exhibit sub-15% penetration for residential treatment despite intermittent supply quality. Municipal infrastructure investment cycles in Andean cities sustain demand for decentralized solutions. First-mover membrane distributors target these metropolitan corridors for expansion.
Peru
Lima apartment developers specify centralized building-scale treatment as amenities in new vertical construction. The capital's delayed pipe network upgrades sustain parallel demand for independent residential systems. Project-channel procurement shifts volume from retail to developer contracts.
South America Residential Water Treatment Equipment Market Competitive Landscape
Brazilian producers anchor the mass-market tier; multinational specialists hold premium positioning through modular system architectures. The vendor base separates into three strategic tiers: domestic ceramic filter manufacturers, regional point-of-entry integrators, and global membrane technology suppliers. Competitive moves concentrate on certification protocol upgrades and project-channel procurement relationships with apartment developers.
Within the domestic ceramic fabrication tier, Cerâmica Stéfani S.A. and Lorenzetti S.A. occupy positions shaped by proprietary clay formulations and gravity-fed production scale. Among multinational equipment suppliers, Pentair exemplifies the compound housing specialist archetype through scalable system architectures. These named entities represent distinct competitive positions rather than exhaustive market coverage, with additional participants including Industria Brasileira De Bebedouros Ltd and regional affiliates of 3M, General Electric Company, Eureka Forbes, LG Electronics, Koninklijke Philips N.V, and others.
| Leading Market Players |
|---|
| Cerâmica Stéfani S.A |
| Lorenzetti S.A |
| Industria Brasileira De Bebedouros Ltd |
| 3M |
| General Electric Company |
| Pentair |
| Eureka Forbes |
| LG Electronics |
| Koninklijke Philips N.V |
| Others |
Value Network & Pricing Analysis
ANVISA-mandated certification upgrades for ceramic filter manufacturers are forcing Brazilian assemblers to absorb extended laboratory testing costs, compressing margin buffers on entry-level gravity-fed systems and pushing supply consolidation toward larger producers with captive testing infrastructure.
Pricing Analysis
Retailer markup layers in São Paulo's home improvement channels stratify across premium, standard, and economy tiers based on certification grade and membrane technology class. Price differentiation hinges on ANVISA compliance tier and coconut-shell carbon porosity engineering, with import resin cost volatility in US dollar terms intensifying cost compression for ion exchange system assemblers. Households in peripheral Brazilian districts exhibit highest price sensitivity, while compound housing developers in Rio de Janeiro's Barra da Tijuca corridor prioritize performance specifications over unit economics.
Supply Chain Analysis
Hollow-fiber ultrafiltration module supply rests on East Asian specialty manufacturers, creating lead time vulnerability for São Paulo-based point-of-entry system integrators. Activated carbon feedstocks draw from Southeast Asian coconut-shell processors and North American coal-based suppliers, while ceramic clay formulations source from Brazilian mining corridors in Minas Gerais. Single-source vulnerability in membrane supply concentrates risk, with distribution running through project-channel contracts for apartment developers and retail networks for household point-of-use replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through predictive maintenance subscription models and UV-LED IoT convergence, as consumable replacement revenue streams decouple from initial equipment sales and capture lifetime value from affluent Brazilian households.
For Market Incumbents: To counter third-party service aggregator capture of recurring membrane replacement volume, Cerâmica Stéfani S.A. and Lorenzetti S.A. should deepen backward integration into proprietary clay mining and accelerate ANVISA certification pre-clearance for new ceramic formulations. Channel control through exclusive technician training programs defends against independent maintenance contractors in São Paulo state. For New Entrants and Emerging Players: Launch via project-channel direct contracts with Lima and Santiago apartment developers specifying point-of-entry systems as standard amenities. Colombian Andean cities present the most penetrable geography given sub-15% current residential treatment penetration, with Bogotá's intermittent municipal supply quality supporting first-mover membrane distributor positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale ceramic filter producers holding Mercosur-harmonized certification dossiers enabling cross-border shelf placement in Uruguayan and Paraguayan retail chains. Long-term viability centers on recurring consumable revenue attachment rates rather than equipment shipment volumes. Watch ANVISA enforcement intensity in secondary Brazilian cities as inflection indicator for replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Clearance Investment | ANVISA laboratory dossier submission ahead of product launch freezes competitor working capital in pre-market inventory. |
| Predictive Maintenance Subscription Launch | UV-LED IoT telemetry in Rio de Janeiro's South Zone captures recurring revenue from algorithm-triggered filter logistics. |
| Project-Channel Direct Contracting | Lima apartment developer specifications shift procurement volume from retail networks to centralized building-scale treatment. |
| Backward Integration into Clay Mining | Captive supply of Minas Gerais ceramic formulations defends porosity control differentiation against resin cost volatility. |
| Mercosur Cross-Border Certification Harmonization | Single laboratory filing enables simultaneous Argentine and Brazilian market access for mid-scale producers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ceramic filter plant managers, ANVISA regulatory affairs leads, apartment developer procurement officers, and aftermarket service aggregators with secondary validation through ANVISA certification databases, Brazilian customs trade records for activated carbon imports, and SEC filings from multinational equipment suppliers. Bottom-up unit shipment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segment-weighting applied technology class, housing typology, and installation type dimensions alongside regional infrastructure quality tiers throughout the modeling period. CAGRs derived from logistic adoption curve fitting for membrane filtration penetration and replacement cycle compression assumptions. Forecast inputs incorporated municipal infrastructure investment pipeline delays in Colombian and Peruvian cities and ANVISA enforcement trajectory scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under exchange rate volatility for US dollar-denominated resin feedstocks and East Asian membrane supply disruption scenarios. Forecasts reflect documented assumptions on middle-class household formation rates and certification timeline standardization. A small set of triggers—ANVISA microbiological threshold revisions, Mercosur regulatory harmonization progress, and apartment developer pre-installation adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Home Water Softener System Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
US Water Purifier Market