
 MENA Point of Use Water Purifiers Market | 2026-2036
MENA Point of Use Water Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Point of Use Water Purifiers Market Foresight
UV-LED integration is reconfiguring purification system architectures across the MENA region, replacing mercury lamp assemblies with solid-state disinfection modules that reduce energy draw and eliminate warm-up latency. Eureka Forbes leverages extensive direct-sales networks to sustain penetration in Indian expatriate communities across the Gulf. Culligan International anchors its position through captive service infrastructure and cartridge replenishment contracts in Saudi commercial installations. LG Electronics competes on smart-home ecosystem integration, embedding purification units within connected kitchen appliance suites.
Point of use water purifiers are self-contained treatment devices installed at single taps or dispensers, typically incorporating sediment pre-filtration, activated carbon adsorption, and membrane or ultraviolet disinfection stages to reduce total dissolved solids, microbial load, and chlorine byproducts below potable thresholds. Their primary purpose is to deliver treated drinking water at the final consumption point without dependence on centralized distribution integrity. RO technology dominates value capture in the MENA landscape due to Gulf groundwater salinity exceeding 1,000 ppm TDS, where membrane rejection rates above 96% justify premium positioning. The household end user segment leads volume, though healthcare applications in Jeddah and Dubai are expanding fastest as dialysis clinics and pharmaceutical compounding facilities adopt pharmaceutical-grade water standards.
SFDA in Saudi Arabia and MOHAP in the UAE enforce separate product registration and water contact material compliance frameworks, while Gulf Standardization Organization harmonization efforts remain incomplete across member states. These regulatory layers elevate certification costs for new entrants but reinforce incumbent positions for manufacturers with established testing laboratory relationships and local authorized representative structures. Stakeholders must monitor desalination capacity expansion timelines and municipal blending ratios, as upstream supply improvements could compress the addressable market for premium in-home treatment systems in specific emirates and governorates.
Market Dynamics
UV-LED solid-state disinfection is virtualizing mercury-based purification architectures across Gulf Cooperation Council households, compressing energy consumption and warm-up latency while SFDA and MOHAP tighten material-contact compliance frameworks.
Growth Catalysts
- Groundwater Salinity Thresholds:TDS levels exceeding 1,000 ppm in Saudi Arabia and UAE aquifers mandate membrane-based treatment, pulling RO systems into residential standard configurations.
- SFDA Material Compliance:Saudi Arabia's water contact material registration framework elevates certified product premiums and locks out uncertified imports.
- Dialysis Clinic Standards:Healthcare facilities in Jeddah and Dubai are adopting pharmaceutical-grade water specifications, expanding demand for multi-stage purification beyond household use.
Market Restraints
- Membrane Replacement Cost Burden:RO cartridge replenishment cycles every 12-18 months impose recurring expenditure that suppresses adoption in price-sensitive Egyptian and Moroccan segments.
- GSO Harmonization Gaps:Incomplete Gulf Standardization Organization alignment across member states forces redundant certification testing, elevating market entry costs for manufacturers without established laboratory partnerships.
- Municipal Desalination Expansion:Upstream capacity additions in specific UAE emirates threaten to compress the addressable premium for in-home treatment where blending ratios improve.
Strategic Opportunities
- Smart-Home Ecosystem Integration:Connected kitchen appliance suites in UAE and Saudi households create attachment points for purification units with IoT-enabled filter monitoring and automated replenishment ordering.
- Commercial Service Contracts:Captive cartridge replenishment infrastructure in Saudi commercial installations offers recurring revenue streams distinct from one-time equipment sales.
- Direct-Sales Network Leverage:Indian expatriate communities across the Gulf present concentrated demand pockets accessible through established door-to-door demonstration models.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Parallel SFDA and MOHAP registration processes extend product launch windows by 8-14 months for manufacturers lacking pre-existing authorized representative structures.
- UV-LED Thermal Management:Solid-state module heat dissipation requirements in ambient Gulf temperatures above 45°C demand specialized engineering that strains mid-tier supplier capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Point of Use Water Purifiers Market |
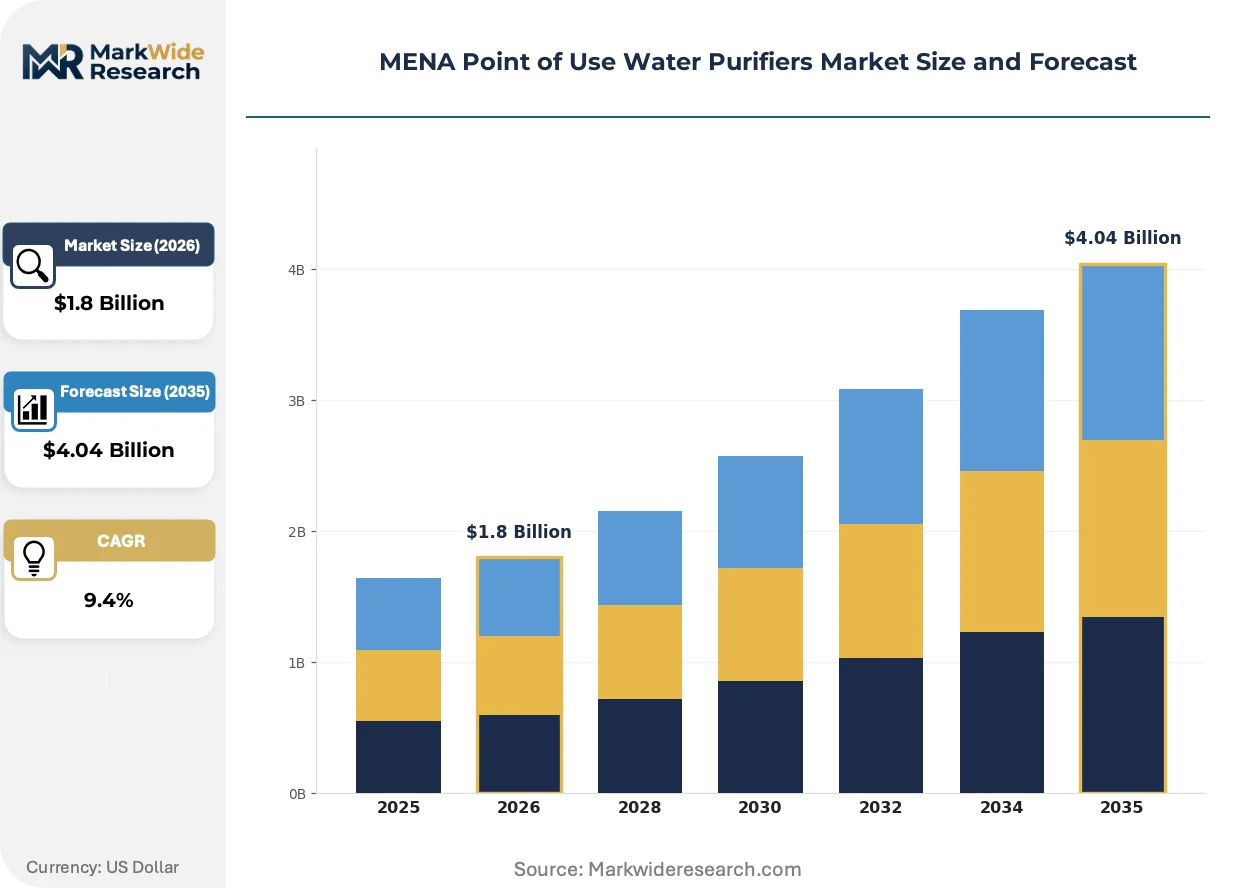
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity-based, Electric, RO, UV End User: Household, Commercial, Industrial, Healthcare Distribution Channel: Retail, Online, Direct Sales, Wholesalers Technology: Filtration, Distillation, Chemical Treatment, Others |
| Companies Covered | Pentair, Eureka Forbes, LG Electronics, Panasonic Corporation, Culligan International, Brita, Coway, A.O. Smith Corporation, 3M Company, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Point of Use Water Purifiers Market Shifts & Advancements
Mercury lamp assemblies are yielding to solid-state alternatives across MENA purification architectures, while regulatory material-contact frameworks harden and procurement patterns shift toward bundled service models.
UV-LED disinfection modules are virtualizing legacy mercury vapor systems in residential and light-commercial installations. Saudi and UAE households with elevated electricity tariffs are adopting these solid-state alternatives at accelerating pace. The technology is virtualizing traditional lamp replacement revenue streams while enabling compact under-sink form factors previously impractical with ballast-dependent assemblies.
SFDA and MOHAP are enforcing divergent water contact material compliance frameworks despite incomplete GSO harmonization. Manufacturers face redundant testing protocols for polymer components and sealing materials, fragmenting certification strategies. Healthcare and pharmaceutical compounding segments in Jeddah and Dubai are responding by demanding pre-certified component traceability from suppliers.
Filter replenishment procurement is consolidating toward subscription-based automatic shipment models. Traditional retail and distributor channels in UAE urban centers are losing share to direct-manufacturer relationships with IoT-enabled units. This behavioral shift is most visible in high-income Saudi households and Dubai expatriate communities where convenience premiums override upfront equipment cost sensitivity.
MENA Point of Use Water Purifiers Market Segmentation
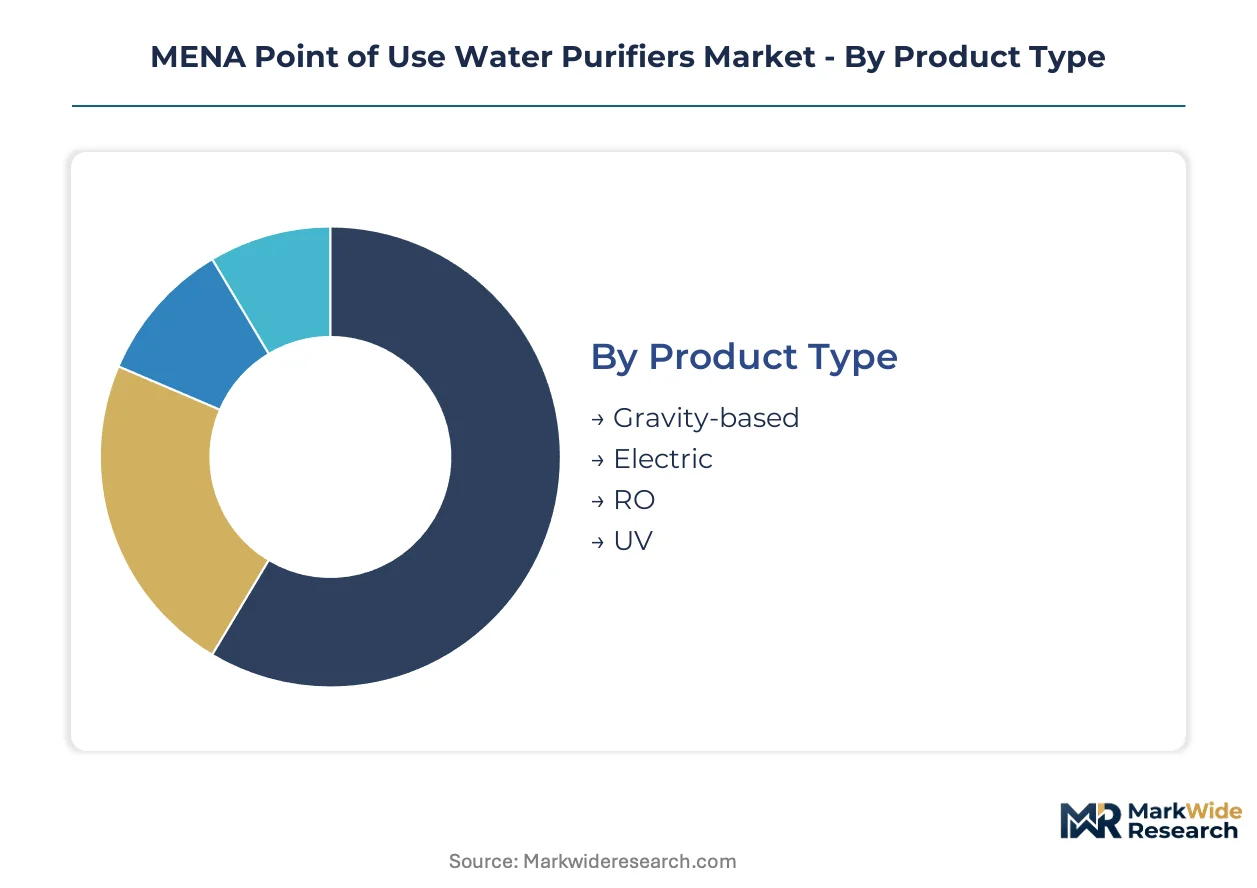
Segmentation in the MENA Point of Use Water Purifiers Market reveals how technology maturity, regulatory pressure, and distribution economics fragment addressable demand across distinct buyer profiles and procurement channels.
Product Type:
Mature electric and RO systems dominate Gulf Cooperation Council installations, while gravity-based units retain footholds in price-sensitive North African markets.
- RO:Reverse osmosis membranes achieve rejection rates above 96% for TDS levels exceeding 1,000 ppm in Saudi and UAE groundwater, commanding premium positioning in residential standard configurations. Jeddah and Dubai households with elevated salinity aquifers drive replacement cycles every 12-18 months.
- Electric:Pump-assisted systems integrate sediment pre-filtration, activated carbon adsorption, and pressure-boosted delivery for multi-point household distribution. Demand concentrates in Saudi urban centers where municipal blending ratios remain inconsistent.
- Gravity-based:Non-electric ceramic and carbon block units serve Egyptian and Moroccan segments with intermittent grid reliability.
- UV:Ultraviolet disinfection modules complement filtration stages in healthcare and light-commercial installations across the Gulf.
RO handles the majority of throughput; UV is the fastest mover on share as UV-LED solid-state modules displace legacy mercury assemblies.
End User:
Volume concentration splits between mass residential adoption and specialized healthcare procurement with divergent certification requirements.
- Household:Single-tap and under-sink installations constitute the primary volume driver, with Indian expatriate communities across the Gulf exhibiting concentrated demand for direct-sales demonstration models. SFDA material-contact compliance elevates certified product premiums in Saudi residential channels.
- Healthcare:Dialysis clinics and pharmaceutical compounding facilities in Jeddah and Dubai are adopting pharmaceutical-grade water specifications, expanding multi-stage purification demand beyond potable thresholds. MOHAP enforcement tightens traceability requirements for polymer components.
- Commercial:Restaurants, hotels, and office installations in UAE urban centers favor captive service contracts with automated cartridge replenishment.
- Industrial:Light-manufacturing and food processing facilities in Saudi industrial cities require pre-treatment for process water integration.
Household absorbs the dominant share of unit volume; Healthcare is expanding most quickly as clinical water standards harden.
Distribution Channel:
Procurement patterns diverge between relationship-heavy direct sales for expatriate communities and automated replenishment for digitally integrated households.
- Direct Sales:Door-to-door demonstration networks penetrate Indian expatriate concentrations across the Gulf, leveraging established trust relationships and in-home water quality testing. Eureka Forbes deploys this model extensively in Saudi Arabia and the UAE.
- Online:IoT-enabled units with automated filter monitoring and subscription replenishment are consolidating share among high-income Saudi households and Dubai expatriates where convenience premiums override upfront cost sensitivity.
- Retail:Big-box and specialty appliance channels in UAE urban centers face erosion from manufacturer-direct relationships.
- Wholesalers:Bulk procurement for commercial installations and project-based healthcare facility builds in Jeddah and Riyadh.
Direct Sales maintains the deepest penetration in established communities; Online is climbing the fastest as connected kitchen ecosystems proliferate.
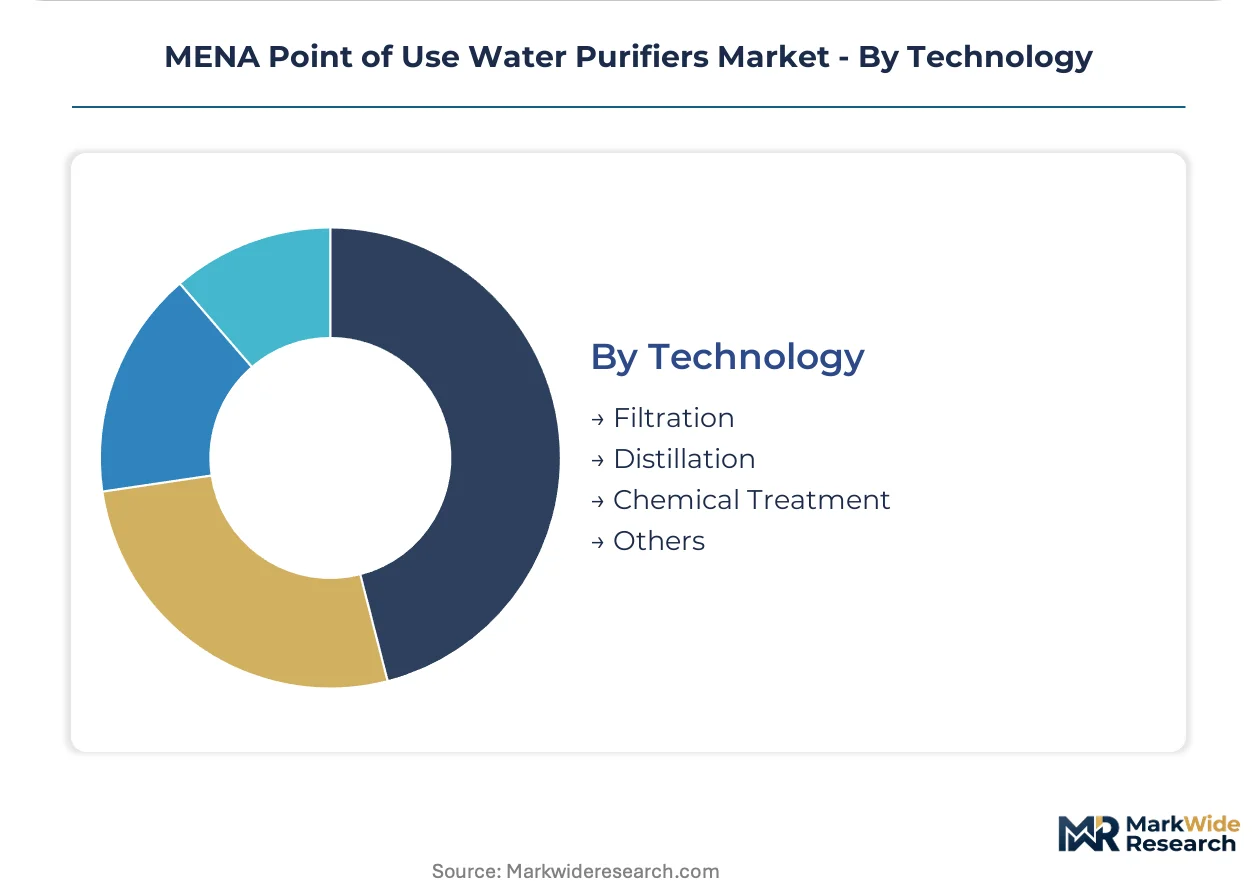
Technology:
Core treatment mechanisms stratify by contaminant target, with membrane and ultraviolet approaches gaining share against legacy chemical methods.
- Filtration:Sediment pre-filtration, activated carbon adsorption, and membrane rejection stages form the foundational architecture for residential and commercial installations. Saudi groundwater salinity mandates membrane-based configurations as standard.
- Chemical Treatment:Chlorine and iodine-based disinfection retains niche application in emergency and portable use cases with limited Gulf adoption.
- Distillation:Thermal vaporization and condensation systems serve specialized laboratory and pharmaceutical compounding requirements with high energy consumption limiting residential viability.
- Others:Emerging electrochemical and advanced oxidation processes remain experimental in MENA pilot deployments.
Filtration commands the installed base; UV integration within filtration architectures is gaining share fastest as solid-state modules mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for membrane modules and UV-LED components concentrates supply risk in Gulf Cooperation Council markets, while Egyptian and Moroccan demand relies on gravity-based units with minimal foreign exchange exposure. Domestic assembly operations in Saudi Arabia and the UAE are expanding to offset currency volatility and shorten replenishment cycles for cartridge components.
Saudi Arabia
Groundwater salinity exceeding 1,000 ppm TDS in Riyadh and Jeddah aquifers mandates RO membrane installations as residential standard. SFDA water contact material registration frameworks elevate certified product premiums and lock out uncertified imports. Dialysis clinics in Jeddah are adopting pharmaceutical-grade water specifications, expanding multi-stage purification demand beyond household thresholds.
United Arab Emirates
Inconsistent municipal blending ratios in Dubai and Sharjah drive pump-assisted electric system adoption for multi-point household distribution. MOHAP enforces divergent polymer component traceability requirements from SFDA, fragmenting certification strategies. Healthcare compounding facilities in Dubai are demanding pre-certified component documentation from suppliers.
Egypt
Intermittent grid reliability in Cairo and Alexandria sustains gravity-based ceramic and carbon block unit demand among price-sensitive households. The country's national standards body maintains basic safety requirements without material-contact specificity. Canal Zone industrial cities are piloting light-commercial pre-treatment systems for food processing integration.
Morocco
RO cartridge replacement costs every 12-18 months suppress penetration in Casablanca and Rabat price-sensitive segments. National water quality regulations emphasize centralized treatment without point-of-use certification mandates. Tangier-Med port logistics clusters are emerging as distribution hubs for Spanish and French component imports.
Kuwait
High-income households in Kuwait City exhibit convenience premiums for IoT-enabled filter monitoring and automated replenishment ordering. Gulf Standardization Organization alignment gaps force redundant testing protocols alongside Saudi and UAE requirements. Healthcare facilities are adopting UV-LED complement systems to mercury-based installations.
MENA Point of Use Water Purifiers Market Competitive Landscape
On the supply side, the industry is bifurcated between multinational appliance conglomerates with captive service infrastructure and specialized purification firms with direct-sales penetration. Tiered competitive positioning separates premium ecosystem-integrated vendors from mid-tier membrane assemblers and economy gravity-based suppliers. Strategic archetypes include smart-home platform anchors, cartridge replenishment contract holders, and door-to-door demonstration specialists. Dominant competitive moves encompass IoT-enabled subscription model deployment and backward integration into membrane manufacturing.
Among diversified electronics conglomerates, LG Electronics and Panasonic Corporation occupy positions as smart-home ecosystem anchors. Within the specialized purification tier, Eureka Forbes exemplifies direct-sales network leverage through door-to-door demonstration models. Culligan International represents the service-contract archetype with captive cartridge replenishment infrastructure.
| Leading Market Players |
|---|
| Pentair |
| Eureka Forbes |
| LG Electronics |
| Panasonic Corporation |
| Culligan International |
| Brita |
| Coway |
| A.O. Smith Corporation |
| 3M Company |
| Others |
Supply & Pricing Matrix
Jebel Ali port freight corridors dictate landed cost spreads between membrane suppliers and Gulf distributors, compressing margins for mid-tier assemblers while enabling premium-tier vendors to capture certification-grade price premiums through captive logistics arrangements.
Pricing Analysis
Legacy mercury-UV system pricing sits 40% below solid-state UV-LED equivalents, with next-generation smart-connected units commanding additional connectivity premiums. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-certified RO systems from uncertified imports and gravity-based units. Cost compression in the Egyptian and Moroccan gravity segment is intensifying because of Chinese ceramic filter imports. Price sensitivity peaks among Egyptian households with intermittent grid access; convenience premiums dominate Kuwaiti smart-home adopters.
Supply Chain Analysis
Tariff exposure between China and Saudi Arabia dominates procurement risk for UV-LED diode arrays and polyamide membrane sheets. Manufacturing concentrates in China, South Korea, and Japan for solid-state disinfection modules; Saudi Arabia and UAE host domestic assembly for cartridge housings. Component sourcing draws from German polymer compounders for medical-grade seals and Taiwanese foundries for LED drivers. Single-source vulnerability persists for 96%-rejection RO membranes. Distribution runs through Jeddah and Dubai wholesale hubs serving GCC retail networks and direct-sales demonstration fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected kitchen platform economics are reconfiguring procurement relationships as IoT-enabled filter monitoring creates subscription lock-in and displaces traditional retail intermediaries.
For Market Incumbents: Insulate cartridge replenishment revenue streams by embedding proprietary IoT protocols that resist third-party filter compatibility. SFDA pre-certification investments create regulatory moats against emerging Chinese entrants with faster product cycles but weaker authorized representative structures. Backward integration into membrane manufacturing reduces exposure to Korean and Japanese supply concentration. For New Entrants and Emerging Players: Moroccan price-sensitive segments with minimal certification mandates offer the most penetrable white-space for gravity-based ceramic units with simplified distribution. Egyptian industrial cities piloting food-processing pre-treatment present B2B entry points with shorter sales cycles than household channels. Partner with established Gulf direct-sales networks rather than building captive demonstration infrastructure. For Investors and Strategic Acquirers: Smart-home ecosystem specialists with existing kitchen appliance integration capabilities represent the highest-conviction acquisition archetype for platform positioning. Long-term viability hinges on subscription attach rates exceeding hardware margins across the analysis window. Monitor SFDA and MOHAP harmonization progress as the inflection signal for regulatory compliance cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | LG and Panasonic smart-kitchen ecosystems create filter monitoring attachment points with automated replenishment ordering. |
| Backward Integration into Membrane Manufacturing | Saudi domestic assembly operations shorten replacement cycles and reduce Korean supply concentration exposure. |
| SFDA Pre-Certification Investment | Early registration locks out uncertified imports and elevates premium positioning in Riyadh and Jeddah residential channels. |
| Direct-Sales Network Expansion | Eureka Forbes door-to-door demonstration models penetrate Indian expatriate concentrations across Dubai and Sharjah. |
| Healthcare Facility Partnership | Dialysis clinics in Jeddah and pharmaceutical compounding in Dubai demand pharmaceutical-grade water specifications beyond household thresholds. |
Research Methodology
Desk research of customs import records, SFDA registration databases, and MOHAP compliance filings preceded structured interviews with purification equipment procurement managers, direct-sales network supervisors, biomedical engineers at dialysis clinics, and polymer component suppliers. Primary fieldwork with Gulf distributor operations and secondary validation against GSO harmonization documentation established baseline market sizing. Bottom-up unit shipment estimates triangulated with top-down household penetration assumptions across Saudi Arabia, UAE, Egypt, Morocco, and Kuwait.
Fixed assumptions across the modeling period include SFDA and MOHAP maintaining divergent material-contact frameworks, municipal desalination capacity expanding at announced project timelines, and UV-LED thermal management costs declining gradually. Segmentation dimensions modeled encompass product type, end-user vertical, distribution channel, and technology architecture. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable water-stressed markets, with healthcare segment growth calibrated to dialysis clinic expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese membrane manufacturers with subsidized domestic production would shift outcomes through price compression in the standard tier. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Home Water Filtration Unit Market