
 Water Ionizers Market | 2026-2036
Water Ionizers Market Size, Share, and Industry Trends Forecast 2026-2036
Water Ionizers Market Outlook
Multi-source component procurement is expanding across the water ionizers supply base as manufacturers diversify electrode plate suppliers beyond traditional Japanese foundries. Enagic leverages direct-to-consumer channel control in North America to sustain premium positioning. Tyent USA anchors its competitive stance through in-house electrolysis chamber production. Fujiiryoki dominates high-end countertop configurations in East Asian markets through decades of brand equity.
A water ionizer is an electrolysis-based appliance that separates incoming tap water into alkaline and acidic streams using platinum-coated titanium electrode plates, typically operating at voltages between 100 and 240 volts depending on regional electrical standards. The device produces alkaline water with pH levels ranging from 8.5 to 9.5 for consumption and acidic water for sanitation purposes. Countertop units command the largest revenue share due to consumer familiarity and installation simplicity, while under-sink configurations represent the fastest-growing product type as kitchen aesthetics favor concealed appliances. Electrolysis technology leads the technology segmentation by installed base, though membrane filtration integration is gaining traction in systems targeting markets with variable municipal water quality.
The US FDA classifies water ionizers as general wellness devices rather than medical equipment, which limits health claim substantiation requirements but also constrains marketing language. Japan's PMDA and South Korea's MFDS maintain stricter electrical safety and materials compliance protocols that export-oriented manufacturers must satisfy for market access. China's SAMR enforces GB standards for household water treatment appliances that increasingly incorporate electrolysis performance testing. Stakeholders must monitor evolving alkaline water health claim regulations across multiple jurisdictions to anticipate compliance cost trajectories and positioning constraints.
Market Dynamics
Platinum supply concentration in South African and Russian mining operations is compressing electrode plate manufacturing economics and forcing manufacturers toward alternative coating technologies or long-term supply agreements.
Growth Catalysts
- Japan's PMDA certification standards:These rigorous electrical safety and materials protocols create a quality benchmark that certified manufacturers leverage for premium positioning in export markets. The certification signals reliability to wellness-focused consumers.
- Residential kitchen renovation cycles:North American suburban homeowners undergoing appliance upgrades increasingly specify under-sink ionizer configurations as standard fixtures rather than retrofits.
- Membrane filtration integration:Hybrid systems combining electrolysis with advanced filtration are capturing demand in municipalities with variable water quality, expanding addressable markets beyond traditional ionizer strongholds.
Market Restraints
- Platinum price volatility:Electrode plate production depends on platinum group metals whose spot market fluctuations directly impact component costs and finished goods pricing.
- Japanese foundry concentration:Traditional titanium electrode manufacturing clusters in specific Japanese industrial zones create geographic supply risk and limit supplier diversification.
- FDA wellness device classification:The US regulator's general wellness categorization prevents manufacturers from substantiating specific health claims, constraining marketing differentiation.
Strategic Opportunities
- South Korean MFDS compliance pathway:Meeting South Korea's electrical safety and materials standards opens access to a metropolitan consumer base with demonstrated willingness to pay premium prices for certified wellness appliances.
- Commercial hospitality integration:Boutique hotels and wellness resorts represent an underpenetrated application segment where alkaline water dispensing serves brand differentiation goals.
- China's SAMR GB standard evolution:The national regulator's expanding electrolysis performance testing requirements for household water treatment appliances create first-mover advantage for compliant manufacturers.
Industry Challenges
- Electrochemistry engineering talent scarcity:The specialized knowledge required for electrolysis chamber design and platinum-titanium interface optimization concentrates in aging workforce cohorts.
- Multi-jurisdiction certification timelines:Sequential compliance processes across Japan's PMDA, South Korea's MFDS, and China's SAMR extend product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Ionizers Market |
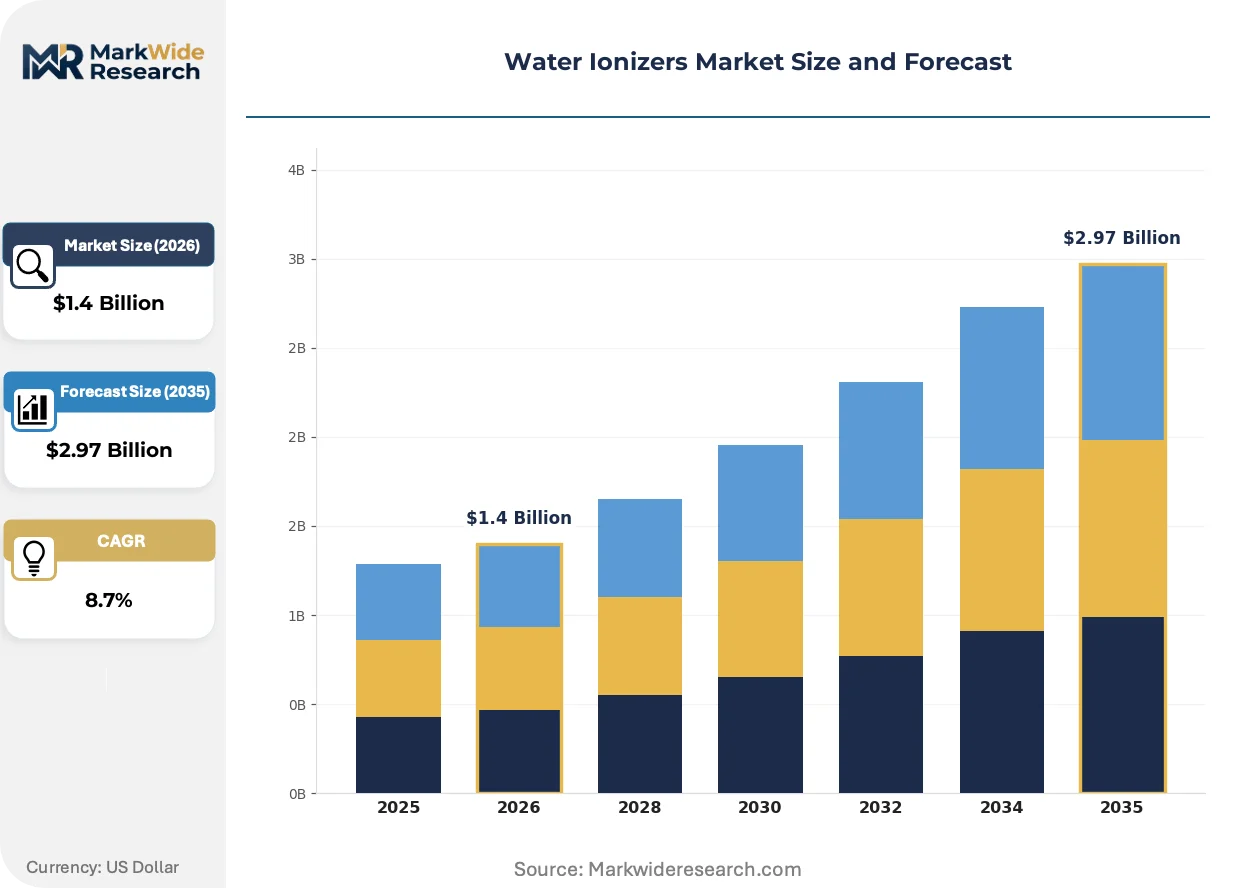
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Under-sink, Portable, Whole house Technology: Electrolysis, Membrane filtration, UV purification, Carbon block Application: Residential, Commercial, Industrial, Healthcare Distribution Channel: Online, Retail, Distributors, Wholesale |
| Companies Covered | Fujiiryoki, Chanson Water, Enagic, Vollara, KENT, Tyent USA, AlkaViva, Ayana Water, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Ionizers Market Strategic Shifts
Digital connectivity and sensor integration are transforming water ionizers from standalone appliances into data-generating household health infrastructure, altering how manufacturers monetize hardware and service relationships.
Smart monitoring technology is automating pH level calibration and filter replacement scheduling through embedded sensors and mobile application interfaces. Residential users in tech-forward metropolitan markets are adopting connected units at accelerated rates. This capability is automating the traditional after-sales service model and compressing manufacturer-customer interaction cycles.
REACH substance restrictions in the European Union are tightening permissible materials in water-contact components and driving reformulation of seals, gaskets, and housing polymers. Manufacturers serving EU export markets are accelerating compliance testing and supplier audits. Countertop unit configurations face the most intensive materials scrutiny due to higher surface area exposure.
Wellness-oriented consumers are fragmenting their appliance procurement across direct-to-consumer brand websites, specialized health retailers, and integrated smart home platforms rather than traditional big-box channels. The specialty wellness retail segment is consolidating shelf space around certified premium brands. This pattern is most pronounced in South Korean and Japanese metropolitan consumer bases where certification marks drive store-level assortment decisions.
Water Ionizers Market Segmentation
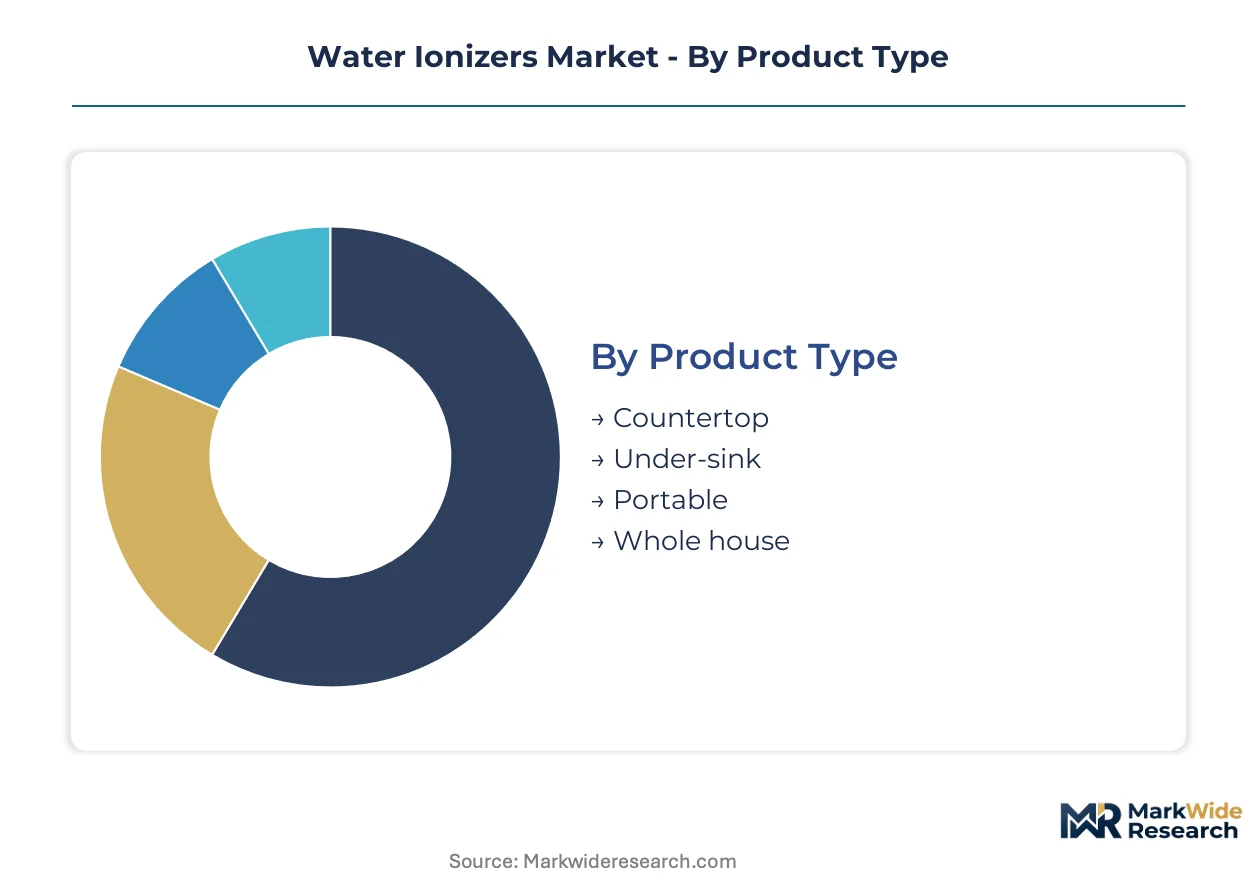
Water ionizer segmentation reveals how supply chain configuration and installation constraints shape purchasing patterns across consumer and institutional buyers. Each dimension exposes distinct margin structures and certification requirements that manufacturers navigate.
Product Type:
Electrode plate fabrication capacity concentrates among Japanese and South Korean foundries, directly influencing which product configurations manufacturers can profitably assemble.
- Countertop:These freestanding units house complete electrolysis systems in compact enclosures designed for kitchen surface placement. North American suburban households undergoing appliance refresh cycles favor countertop configurations for their plug-and-play installation. The segment absorbs the bulk of installed capacity; portable configurations are expanding most quickly.
- Under-sink:Concealed installation beneath kitchen counters requires separate faucet integration and professional plumbing connection. South Korean metropolitan consumers increasingly specify under-sink units during kitchen renovations to preserve minimalist aesthetics.
- Portable:Battery-operated or travel-sized units prioritize compact electrode chambers and reduced power draw for mobility. Wellness-focused consumers in Japan's urban centers purchase portable units for office and travel use.
- Whole house:Centralized systems install at main water entry points to treat all household water. These configurations demand higher-capacity electrolysis chambers and specialized installation expertise.
Countertop configurations absorb the bulk of installed capacity; portable units are expanding most quickly.
Technology:
Cost tier stratification separates premium electrolysis systems from filtration-focused alternatives, with hybrid approaches commanding intermediate price points.
- Electrolysis:Platinum-coated titanium electrode plates separate water into alkaline and acidic streams through controlled voltage application. Japan's PMDA-certified manufacturers dominate this technology tier for residential installations.
- Membrane filtration:Semi-permeable membranes remove dissolved solids and contaminants before or alongside pH adjustment. Municipalities with variable water quality in China are driving membrane-electrolysis hybrid adoption.
- UV purification:Ultraviolet light modules target microbiological contamination in pre-treatment or post-treatment stages. Healthcare applications specify UV integration for pathogen control.
- Carbon block:Activated carbon filtration addresses chlorine, volatile organic compounds, and taste issues. These systems serve as pre-filtration stages in multi-technology configurations.
Electrolysis systems command the largest revenue share; membrane filtration integration is climbing the fastest.
Application:
Volume concentration varies sharply between high-unit residential deployments and low-unit, high-value commercial specifications.
- Residential:Individual household installations span countertop, under-sink, and whole-house configurations. South Korea's wellness-oriented metropolitan consumer base demonstrates sustained willingness to pay premium prices for certified residential units.
- Commercial:Boutique hotels, wellness resorts, and corporate facilities install centralized or distributed alkaline water dispensing. Japan's hospitality sector leverages alkaline water as brand differentiation.
- Industrial:Manufacturing processes utilize ionized water for cleaning, cooling, or chemical processing applications. Electronics fabrication in East Asian industrial zones specifies precise pH-controlled water.
- Healthcare:Clinics and wellness centers deploy medical-grade ionizers with enhanced documentation and sterilization protocols. South Korea's MFDS certification pathway opens institutional procurement channels.
Residential applications absorb the bulk of installed capacity; commercial hospitality integration is gaining share fastest.
Distribution Channel:
Customer type fragmentation is reshaping how manufacturers build channel relationships, with direct engagement displacing traditional retail intermediaries.
- Online:Brand-controlled e-commerce and marketplace platforms enable direct consumer relationships and subscription filter replacement programs. Enagic's direct-to-consumer model in North America demonstrates this channel's margin potential.
- Retail:Specialty wellness retailers and big-box stores provide physical product demonstration and immediate fulfillment. South Korean and Japanese metropolitan markets concentrate certified brand shelf space in specialty wellness retail.
- Distributors:Regional wholesalers manage inventory, installation support, and after-sales service for local markets. These relationships prove essential for under-sink and whole-house configurations requiring technical expertise.
- Wholesale:Bulk procurement channels serve commercial and industrial buyers with volume pricing and project-based specifications. Hospitality developers source through wholesale channels for property-wide installations.
Online channels absorb the bulk of revenue growth; specialty wellness retail is expanding most quickly in certified markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential kitchen renovation cycles in North American suburbs and wellness-focused metropolitan consumption in East Asia concentrate demand for certified ionizer systems. Regulatory divergence across Japan's PMDA, South Korea's MFDS, and China's SAMR creates distinct compliance entry costs that shape manufacturer geographic prioritization.
United States
Suburban homeowners undergoing appliance upgrades increasingly specify under-sink configurations as standard fixtures during kitchen renovations. The FDA's general wellness device classification limits health claim substantiation requirements but constrains marketing differentiation against filtration alternatives. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate distributor networks serving residential retrofit demand.
Japan
Tokyo and Osaka metropolitan consumers demonstrate sustained willingness to pay premium prices for PMDA-certified residential units with decades-long brand equity. Japan's Ministry of Health, Labour and Welfare maintains alkaline water device certification standards that shape product development cycles for export-oriented manufacturers. Kanto and Kansai industrial zones concentrate titanium electrode foundry capacity that supplies domestic and regional assembly operations.
South Korea
Seoul Capital Area wellness-focused consumers drive demand for MFDS-certified appliances with connected monitoring capabilities. South Korea's electrical safety and materials compliance protocols create a quality benchmark that certified manufacturers leverage for premium positioning. Busan-Ulsan manufacturing corridors host assembly operations targeting both domestic metropolitan demand and export markets.
China
Yangtze River Delta and Pearl River Delta municipalities with variable water quality drive adoption of membrane-electrolysis hybrid systems. SAMR enforces GB standards for household water treatment appliances that increasingly incorporate electrolysis performance testing. Shenzhen and Shanghai industrial clusters concentrate component sourcing and final assembly for price-competitive configurations.
Germany
REACH substance restrictions tighten permissible materials in water-contact components and drive reformulation of seals and housing polymers. ECHA compliance requirements for EU export markets accelerate testing and supplier audits for countertop configurations facing intensive materials scrutiny. Bavaria and Baden-Württemberg engineering centers concentrate electrochemistry talent for electrolysis chamber design optimization.
Water Ionizers Market Competitive Environment
Direct-to-consumer channel control dominates the current landscape as manufacturers bypass traditional retail intermediaries to capture margin and customer data. The vendor base stratifies across three tiers: Japanese heritage brands with PMDA certification equity, North American direct-sales specialists with multi-level distribution networks, and Asian fabricators competing on electrode plate cost efficiency. Strategic archetypes include certification-driven premium positioners, channel-integrated margin capturers, and component-cost optimizers. Geographic expansion into South Korean and Chinese certification pathways and backward integration into electrolysis chamber production represent the dominant competitive moves.
Among Japanese heritage manufacturers, Fujiiryoki exemplifies the certification-driven premium archetype through decades of PMDA-aligned product development. Tyent USA occupies a position within the North American direct-sales specialist tier, leveraging in-house production capabilities to control electrolysis chamber supply. Enagic represents the channel-integrated margin capturer model, sustaining premium positioning through direct-to-consumer relationship control. Panasonic sits within the diversified electronics conglomerate archetype, drawing on cross-category appliance manufacturing scale.
| Leading Market Players |
|---|
| Fujiiryoki |
| Chanson Water |
| Enagic |
| Vollara |
| KENT |
| Tyent USA |
| AlkaViva |
| Ayana Water |
| Panasonic |
| Others |
Value Chain & Pricing Dynamics
Platinum group metal spot volatility cascades through electrode plate fabrication economics, compressing margins for manufacturers sourcing from South African and Russian mining operations while forcing tiered pricing stratification across certification-grade residential units.
Pricing Analysis
Volume concentration in countertop configurations trades margin for installed base capture, while under-sink and portable segments command premium pricing through installation complexity and mobility engineering. Price differentiation separates PMDA-certified Japanese heritage units from price-competitive Chinese assemblies, with South Korean MFDS compliance opening intermediate positioning. Cost compression in standard-tier configurations is intensifying because electrode plate suppliers are passing through platinum group metal volatility. Residential retrofit buyers in North American suburbs demonstrate highest price sensitivity; wellness-focused metropolitan consumers in Seoul and Tokyo exhibit lowest.
Supply Chain Analysis
Dual-sourcing requirements from major manufacturers are fragmenting electrode plate procurement beyond traditional Japanese foundries toward qualified South Korean and Chinese suppliers. Geographic supply concentration centers on Japan's Kanto and Kansai industrial zones for titanium electrode fabrication, South Korea's Busan-Ulsan corridor for assembly integration, and China's Shenzhen-Shanghai clusters for component cost optimization. Raw material dependencies rest on South African and Russian platinum group metal mining, Japanese titanium foundry capacity, and specialized polymer formulations for seals and housings. Single-source vulnerability in Japanese electrode manufacturing creates geographic concentration risk. Distribution runs through direct-to-consumer brand platforms, specialty wellness retailers, and regional distributors managing installation-heavy configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where Japan's PMDA certification standards erect barrier-to-entry moats that certified incumbents exploit for sustained premium positioning against uncertified competitors.
For Market Incumbents: Anticipate membrane filtration hybrid technologies displacing pure electrolysis architectures in municipalities with variable water quality. Defend position by deepening backward integration into electrolysis chamber production to capture margin and control supply continuity. Prioritize sequential certification across Japan's PMDA, South Korea's MFDS, and China's SAMR to maintain geographic optionality against regulatory divergence.
For New Entrants and Emerging Players: Launch via direct-to-consumer digital platforms to bypass entrenched distributor relationships and capture customer data for subscription filter replacement monetization. Target commercial hospitality integration in boutique hotels and wellness resorts as the most penetrable white-space segment with low incumbent saturation. Exploit certification arbitrage by engineering for China's evolving SAMR GB standards ahead of full electrolysis performance testing mandates.
For Investors and Strategic Acquirers: MFDS certification timeline compression in South Korea is the leading indicator that regulatory capacity constraints are easing, enabling faster market entry for compliant players. Long-term viability over the next decade favors manufacturers with captive electrode plate supply and multi-jurisdiction certification equity. Acquisition target archetype: mid-scale assemblers with established PMDA compliance and underutilized capacity in Busan-Ulsan manufacturing corridors. Watch for platinum group metal price stabilization as the inflection signal for margin expansion resumption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Plate Production | Captive titanium-platinum interface manufacturing insulates margin from South African and Russian mining volatility. |
| Multi-Jurisdiction Certification Sequencing | PMDA-MFDS-SAMR compliance stacking accelerates geographic expansion into East Asian wellness markets. |
| Membrane-Electrolysis Hybrid System Launch | Filtration integration captures demand in Chinese municipalities with variable municipal water quality. |
| Direct-to-Consumer Channel Development | Brand-controlled e-commerce displaces retail intermediaries and enables subscription filter replacement revenue. |
| Commercial Hospitality Vertical Penetration | Boutique hotel and wellness resort installations serve brand differentiation goals with low competitive density. |
Study Parameters
Independent corroboration across electrolysis equipment manufacturers, specialty wellness retailers, platinum group metal traders, and municipal water quality regulators underwrites the qualitative findings presented. Primary interviews with product development executives at Japanese heritage brands, procurement leads at South Korean assembly operations, and regulatory affairs specialists navigating PMDA-MFDS-SAMR pathways combined with secondary validation from FDA device classification filings, Japan's Ministry of Health certification databases, South Korean MFDS approval registries, and Chinese SAMR GB standard evolution notices. Bottom-up unit shipment estimates and top-down category spend analysis triangulate market sizing.
Comparable-period anchoring to historical residential kitchen renovation cycles and wellness appliance adoption curves in East Asian metropolitan markets structured the projection horizon. The analytical framework segments by product configuration, technology integration level, application intensity, and distribution channel control, with CAGRs derived from installed base turnover rates and replacement demand elasticity. Platinum price trajectory assumptions and certification timeline estimates constitute industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for membrane filtration dominance over pure electrolysis architectures would alter the outlook. Deviation in Japanese foundry capacity utilization or South Korean MFDS certification processing speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Zero Liquid Discharge Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Portable Water Purifier Market
Water Treatment Systems
Home Water Filtration Unit Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Water Desalination Equipment Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
GCC Water Purifier Market