
 Non-Residential Green Building Market | 2026-2036
Non-Residential Green Building Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Residential Green Building Market Analysis
Green leasing and energy-as-a-service contracting is fragmenting capital deployment across non-residential construction, allowing asset-light entrants to bid alongside balance-sheet-heavy incumbents. Turner Construction Company anchors its competitiveness through integrated project delivery models that compress design-build timelines. Skanska differentiates via its deep Nordic heritage in low-carbon concrete specification. Lendlease Corporation extends its green bond financing platform into build-to-core office developments across multiple continents.
Non-residential green buildings are commercial and institutional structures engineered to minimize environmental impact through specified energy performance thresholds, material life-cycle assessments, and operational carbon budgets; these structures typically integrate high-performance envelopes, on-site renewable generation, and automated building management systems to achieve certification benchmarks while reducing utility expenditures over extended holding periods. Office and healthcare segments lead certification volume, with healthcare margin pools concentrating in infection-control-compatible low-VOC material packages. Educational buildings represent the fastest-growing typology as municipal bond issuances increasingly embed climate performance covenants.
The US EPA's ENERGY STAR program and the EU's Energy Performance of Buildings Directive collectively shape product standards by mandating disclosed operational metrics at transaction and retrofit trigger points, while LEED and BREEAM certification protocols filter market access for design firms and general contractors unable to document embodied carbon inventories. China's GB standards and its Ministry of Ecology and Environment enforcement actions add a third compliance layer for multinational firms operating across jurisdictions. Stakeholders must monitor how converging disclosure requirements between the EU Green Deal taxonomy and emerging SEC climate rules reshape competitive qualification criteria for project pipelines.
Market Dynamics
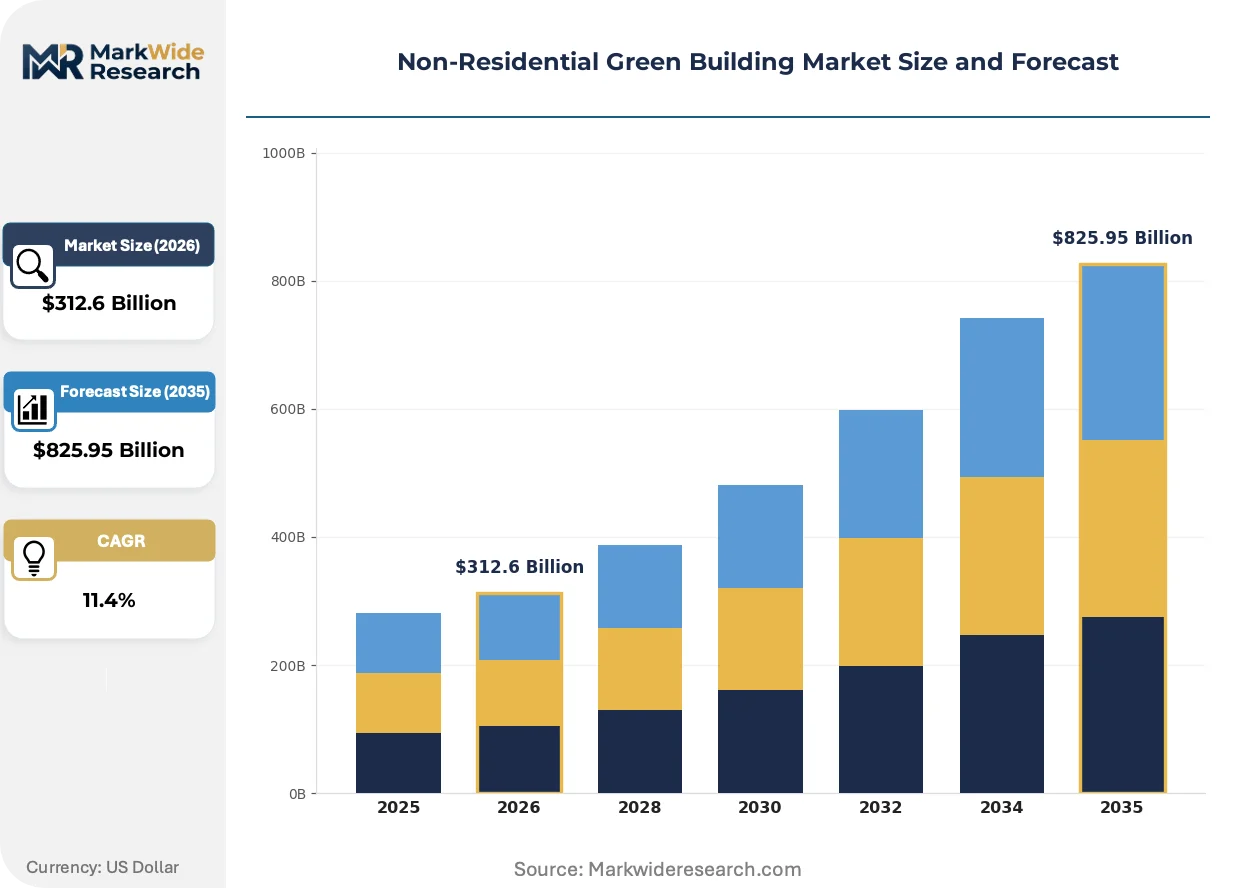
Capital deployment in non-residential green construction is fragmenting as energy-as-a-service contracting separates operational performance risk from asset ownership, compressing traditional design-bid-build cycles and enabling new entrants to bid against established balance-sheet-heavy contractors.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Mandated disclosure of operational metrics at transaction and retrofit trigger points is accelerating certification uptake across commercial portfolios in Germany and the Nordics.
- Low-carbon concrete specification:Nordic public infrastructure corridors are embedding embodied carbon thresholds in procurement contracts, creating dedicated demand pools for material suppliers with verified Environmental Product Declarations.
- Healthcare infection-control standards:Low-VOC material packages compatible with stringent clinical protocols are opening premium margin pools in hospital and laboratory construction segments.
Market Restraints
- Skilled MEP commissioning engineer scarcity:Talent shortages in building systems integration are extending project handover timelines and inflating soft costs for complex envelope-technology combinations.
- Copper and rare earth price volatility:Electrification of building systems and on-site renewable generation is exposing developers to raw material cost swings that fixed-price contracts cannot absorb.
- Cross-jurisdiction compliance layering:China's GB standards and Ministry of Ecology and Environment enforcement actions create duplicate documentation burdens for multinational firms operating across EU and Asia-Pacific markets.
Strategic Opportunities
- Educational building municipal bonds:Climate performance covenants embedded in US school district financings are creating the fastest-growing certification volume typology.
- Building-integrated photovoltaics convergence:High-performance envelope manufacturers partnering with thin-film solar producers can capture vertical integration premiums in build-to-core office developments.
- Green lease standardization:The EU Green Deal taxonomy alignment with emerging SEC climate disclosure rules is creating qualification arbitrage for design firms with multi-jurisdiction documentation capabilities.
Industry Challenges
- LEED v4.1 embodied carbon documentation:Supply chain data collection for whole-building life-cycle assessment is forcing contractors to reconfigure procurement relationships with concrete, steel, and aluminum suppliers.
- Legacy HVAC-BMS integration:Automated building management system retrofits in existing commercial stock are encountering proprietary protocol incompatibilities that require custom middleware development.
- Certification timeline compression:ASHRAE 90.1-2022 compliance deadlines are colliding with extended lead times for high-performance glazing and advanced insulation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Residential Green Building Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $825.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Office, Retail, Educational, Healthcare Material Used: Recycled Steel, Solar Panels, Low-VOC Paint, Green Insulation Technology: Energy Management Systems, HVAC Optimization, Smart Lighting, Water Conservation Systems Certification Type: LEED, BREEAM, Green Globes, Energy Star |
| Companies Covered | Skanska, Turner Construction Company, AECOM, Clark Construction Group, Hensel Phelps, Gilbane Building Company, DPR Construction, Lendlease Corporation, Jacobs Engineering Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Residential Green Building Market Emerging Trajectories
Operational carbon budgeting is migrating upstream into design-phase decisions, compressing the traditional separation between architectural specification and facilities management and forcing new collaboration models across project delivery teams.
Mass timber structural systems are migrating from boutique showcase projects to mid-rise commercial typologies as code officials in Washington, Oregon, and British Columbia gain experience with Type IV construction. Institutional investors with net-zero portfolio commitments are accepting the 10-15% structural premium for cross-laminated timber in exchange for biogenic carbon accounting benefits. The technology is migrating from demonstration to standard specification in Pacific Northwest office and educational buildings.
The SEC's proposed climate disclosure rules are mandating Scope 3 emissions reporting for publicly traded real estate investment trusts, forcing asset managers to demand granular utility data from property managers and tenants. This regulatory pressure is accelerating sub-metering retrofits in Class B office stock that previously deferred capital investment. Smaller REITs without dedicated sustainability functions are outsourcing data aggregation to specialized service providers.
Tenant improvement allowances are increasingly tied to LEED or BREEAM certification thresholds rather than base building performance alone, shifting capital responsibility for green upgrades from landlords to occupiers. Law firms and professional services tenants in Manhattan and London are negotiating lease clauses that require third-party verification of indoor air quality and energy intensity. This behavioral shift is visible most acutely in prime central business district submarkets where vacancy rates remain elevated and tenant concessions are expanding.
Non-Residential Green Building Market Segmentation
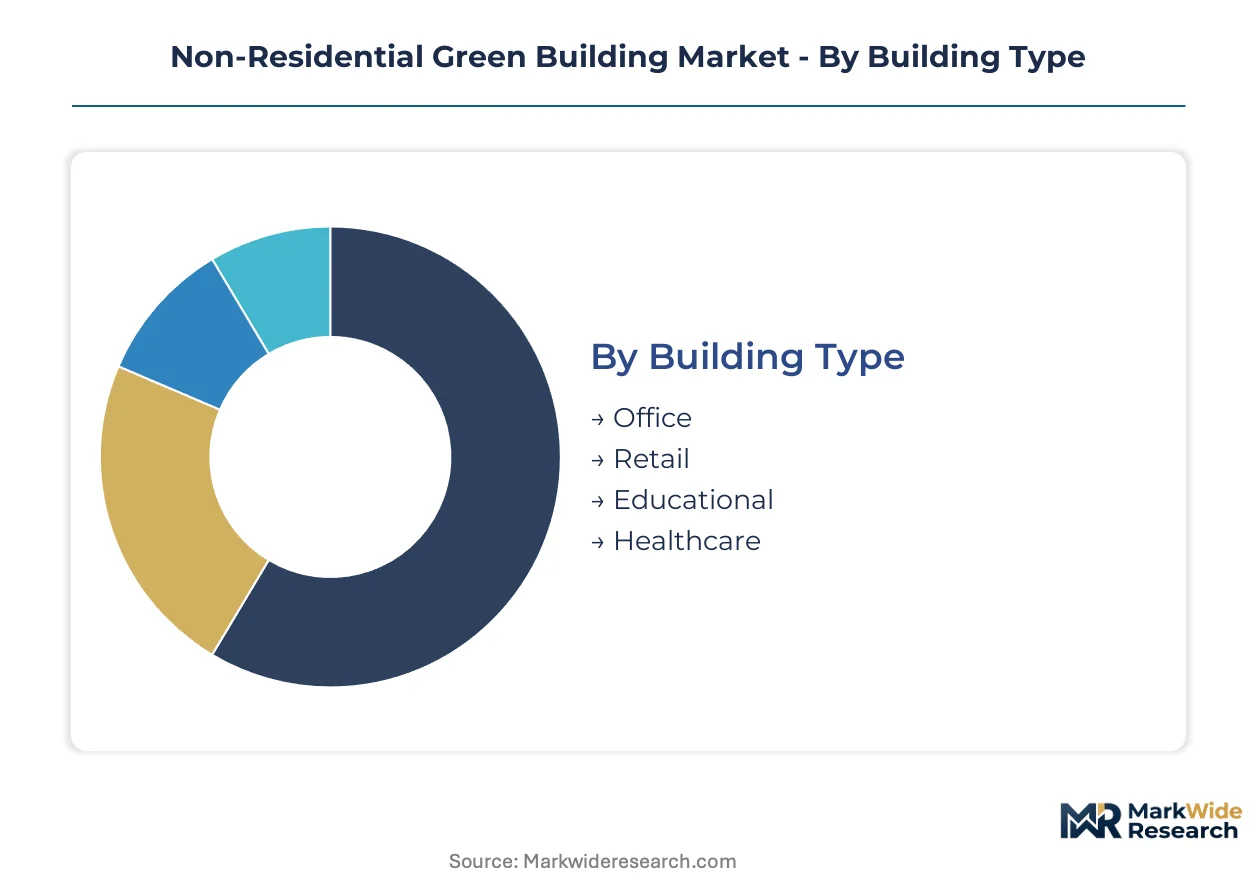
Segmentation in non-residential green building markets reveals how capital allocation, regulatory compliance burdens, and operational performance guarantees cluster around distinct asset classes and certification protocols. Understanding these divisions exposes where service intensity concentrates and which technology bundles command premium pricing.
Building Type:
Service intensity varies sharply across building types, with healthcare and educational assets requiring sustained commissioning support that extends revenue streams for MEP contractors well beyond handover.
- Office:Corporate portfolio retrofits dominate certification volume as ENERGY STAR disclosure mandates compress upgrade timelines. German commercial districts and Manhattan Class A towers anchor demand for integrated design-build contracts with performance guarantees.
- Healthcare:Infection-control-compatible low-VOC material packages and continuous air quality monitoring create the highest service attachment rates. Hospital construction in Nordic corridors embeds stringent embodied carbon thresholds that extend procurement cycles.
- Educational:Municipal bond issuances with climate performance covenants are expanding certification volume fastest across US school districts and British Columbia campuses.
- Retail:Big-box and shopping center green retrofits concentrate in jurisdictions with aggressive operational disclosure requirements, though tenant turnover complicates long-term performance contracting.
Office holds the largest share; momentum sits with educational buildings as bond financing structures mature.
Material Used:
Cost tier differentiation separates commodity-specified materials from certified products carrying verified Environmental Product Declarations that unlock green bond eligibility.
- Recycled Steel:Structural specification with mass timber hybrid systems is gaining traction in Pacific Northwest commercial projects. Supply concentration among electric-arc-furnace producers in Germany and the US creates regional cost disparities that procurement teams must navigate.
- Solar Panels:Building-integrated photovoltaics convergence with high-performance envelopes enables net-zero energy claims in build-to-core office developments. Thin-film partnerships with glazing manufacturers are capturing vertical integration premiums.
- Low-VOC Paint:Healthcare and educational procurement mandates in California and EU member states have elevated this from aesthetic specification to compliance requirement.
- Green Insulation:Cellulose and mineral wool alternatives with biogenic content are displacing conventional foam in Nordic public infrastructure contracts with embodied carbon scoring.
Recycled steel holds the largest share; solar panels are climbing fastest as building-integrated configurations standardize.
Technology:
Customer type stratification separates owner-operated assets pursuing deep operational integration from developer-held properties optimizing for certification speed and capital efficiency.
- Energy Management Systems:Automated building management platforms with sub-metering granularity are becoming mandatory for REITs facing SEC climate disclosure requirements. Class B office retrofits in US secondary markets represent the fastest-expanding installation base.
- HVAC Optimization:Heat pump electrification and demand-controlled ventilation dominate new construction specification, though legacy protocol incompatibilities in existing stock require custom middleware development.
- Smart Lighting:Daylight harvesting and occupancy-based controls are standardizing across all certification tiers as LED costs compress and utility rebate programs tighten.
- Water Conservation Systems:Greywater recycling and low-flow fixture specification concentrate in drought-prone US states and Australian commercial developments with municipal water stress.
Energy management systems hold the largest share; momentum sits with HVAC optimization as electrification mandates tighten.
Certification Type:
Geography determines protocol dominance, with multinational firms maintaining parallel documentation capabilities to qualify for project pipelines across jurisdictional boundaries.
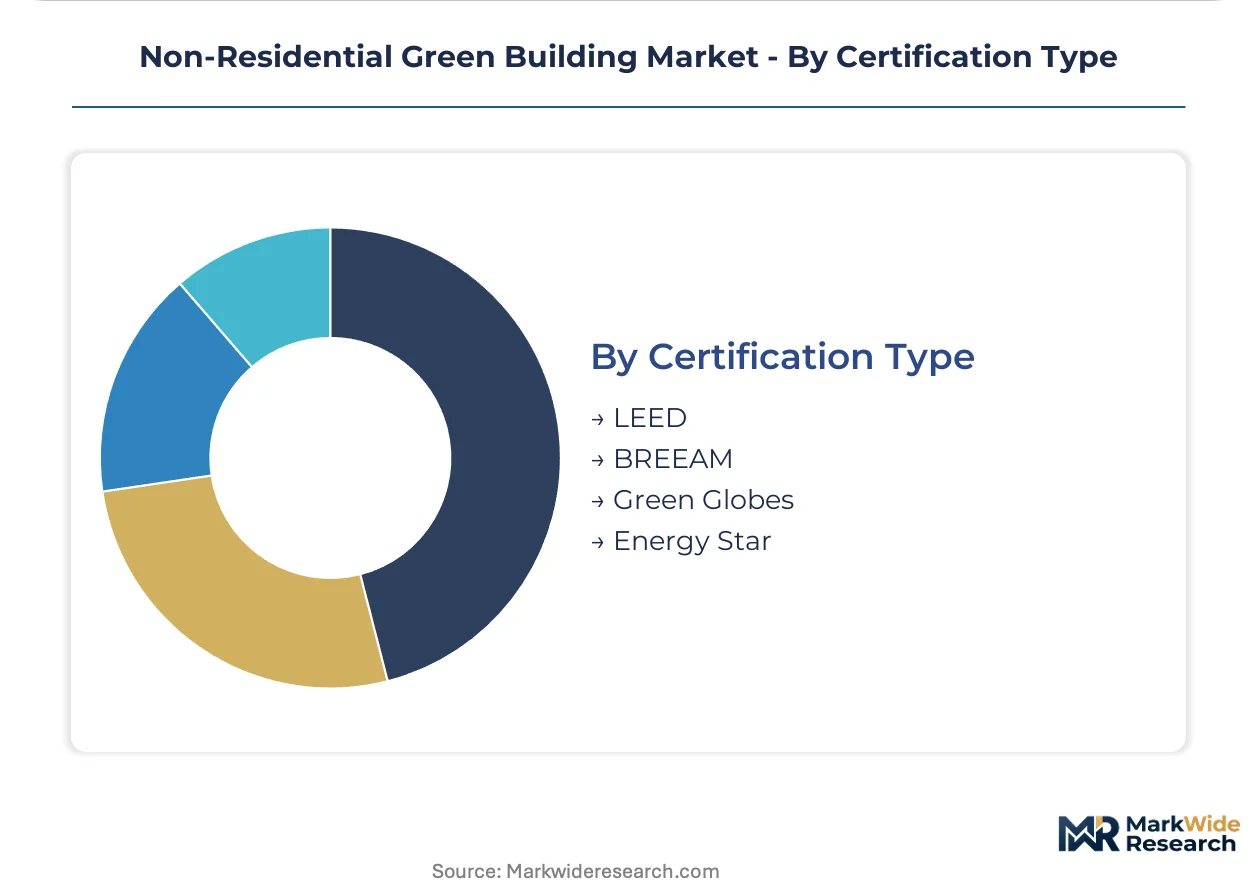
- LEED:The most widely recognized certification in North American commercial construction, with v4.1 embodied carbon documentation requirements forcing supply chain reconfiguration. Whole-building life-cycle assessment data collection is the primary compliance bottleneck.
- BREEAM:Dominates UK and EU commercial development, with alignment to EU Green Deal taxonomy creating qualification arbitrage for design firms with multi-jurisdiction capabilities.
- Green Globes:Alternative pathway in North American markets emphasizing operational performance over prescriptive material specifications, attracting industrial and warehouse developers.
- Energy Star:US EPA program focused on operational metrics disclosure, with transaction-triggered benchmarking requirements accelerating portfolio-wide certification in commercial real estate.
LEED holds the largest share; BREEAM is expanding most quickly as EU taxonomy alignment reshapes competitive qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German commercial districts command 15-20% construction cost premiums over comparable US office developments, while Nordic public infrastructure corridors extract stricter embodied carbon compliance without proportional price escalation.
United States
Corporate office portfolio retrofits and ENERGY STAR disclosure mandates drive certification volume in Manhattan Class A towers and secondary market Class B stock. The SEC's proposed climate disclosure rules force REITs to demand granular utility data from property managers. Pacific Northwest mass timber adoption accelerates in Washington and Oregon educational buildings.
Germany
Commercial district energy performance contracting and the EU Energy Performance of Buildings Directive compress upgrade timelines across Frankfurt and Munich office portfolios. The country's national building energy regulator enforces operational metric disclosure at transaction points. Berlin's public infrastructure procurement embeds stringent embodied carbon thresholds for concrete and steel specification.
China
GB standards enforcement by the Ministry of Ecology and Environment creates compliance layering for multinational firms operating across EU and Asia-Pacific markets. The dual carbon goals policy framework mandates disclosed operational metrics in Beijing-Tianjin-Hebei and Yangtze River Delta commercial corridors. Shanghai's commercial districts concentrate demand for integrated design-build contracts with performance guarantees.
United Kingdom
BREEAM certification alignment with EU Green Deal taxonomy creates qualification arbitrage for design firms with multi-jurisdiction documentation capabilities. The national building energy regulator mandates operational performance thresholds in London and Southeast commercial developments. Manchester and Birmingham office retrofits concentrate demand for automated building management system integration.
Sweden
Nordic heritage in low-carbon concrete specification and public infrastructure embodied carbon thresholds drive procurement cycle extensions. The national environmental protection agency enforces Environmental Product Declaration verification for structural materials. Stockholm's commercial districts anchor demand for mass timber hybrid systems in mid-rise office typologies.
Non-Residential Green Building Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in envelope technology and building-integrated photovoltaics. The vendor base organizes around three strategic archetypes: balance-sheet-heavy incumbents with integrated project delivery capabilities, asset-light energy-as-a-service entrants, and regional specialists in mass timber or low-carbon concrete specification. Competitive moves concentrate on strategic partnerships for technology convergence and geographic expansion into municipal bond-financed educational building corridors.
Within the integrated delivery tier, Turner Construction Company and Skanska occupy positions that exemplify divergent geographic anchoring strategies. Turner Construction Company represents North American platform scale with design-build timeline compression capabilities. Skanska anchors Nordic low-carbon material specification heritage extending into continental European public infrastructure. Lendlease Corporation sits within the green bond financing archetype, with build-to-core office development positioning across multiple continents.
| Leading Market Players |
|---|
| Skanska |
| Turner Construction Company |
| AECOM |
| Clark Construction Group |
| Hensel Phelps |
| Gilbane Building Company |
| DPR Construction |
| Lendlease Corporation |
| Jacobs Engineering Group |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's carbon-adjusted logistics costs transmit directly into Nordic low-carbon concrete premiums and German commercial district construction bids, compressing margins for contractors without captive material sourcing while enabling price tiering based on embodied carbon verification.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures that stratify across LEED Platinum, Gold, and Certified tiers. Price differentiation hinges on Environmental Product Declaration verification depth and after-sales commissioning support duration. Cost compression in mid-tier specifications intensifies as Chinese GB-standard materials enter EU procurement channels. Healthcare developers demonstrate lowest price sensitivity due to infection-control compliance mandates, while retail retrofitters face acute margin pressure from tenant turnover risk.
Supply Chain Analysis
Specialized envelope manufacturers and thin-film solar producers hold concentrated capacity in Germany, Sweden, and China. Supply draws from electric-arc-furnace steel mills, cross-laminated timber fabricators, and advanced glazing foundries. Single-source vulnerability concentrates in rare earth elements for building-integrated photovoltaics. Distribution runs through integrated design-build contractors and energy-as-a-service platforms that separate operational performance risk from asset ownership.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of MEP commissioning engineers capable of integrating high-performance envelopes with automated building management systems constrains project delivery velocity and inflates soft costs for complex retrofits.
For Market Incumbents: Pre-empt asset-light energy-as-a-service entrants by embedding performance guarantees into design-build contracts and acquiring regional low-carbon concrete specialists with verified Environmental Product Declaration capabilities. Balance-sheet-heavy contractors must compress handover timelines before talent shortages extend project schedules further. For New Entrants and Emerging Players: Pursue municipal bond-financed educational building corridors in US school districts and British Columbia campuses, where climate performance covenants create procurement windows for certification-capable contractors. Position through green lease standardization expertise that bridges EU Green Deal taxonomy and emerging SEC disclosure requirements. For Investors and Strategic Acquirers: Regional specialists in mass timber hybrid systems and automated building management middleware represent priority acquisition targets given their scarcity value in net-zero portfolio commitments. Monitor ASHRAE compliance deadline collisions with high-performance glazing lead times as an inflection signal for distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Design-Build Contracting | Turner Construction and Skanska compress timelines through single-source accountability for ENERGY STAR compliance. |
| Low-Carbon Concrete Specification | Swedish and German procurement mandates reward suppliers with verified Environmental Product Declarations. |
| Building-Integrated Photovoltaics Partnerships | Thin-film solar producers capture vertical premiums through envelope manufacturer alliances in build-to-core offices. |
| Green Bond Financing Platform Extension | Lendlease Corporation leverages certification pipelines across multiple continents for institutional capital access. |
| MEP Commissioning Capability Buildout | Talent acquisition in building systems integration addresses the primary bottleneck for complex envelope-technology projects. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with MEP commissioning engineers, green bond portfolio managers, municipal procurement officers, and low-carbon concrete specification specialists. Secondary validation drew from EPA ENERGY STAR benchmarking databases, EU Energy Performance of Buildings Directive implementation reports, ASHRAE standard revision documentation, and SEC climate disclosure rulemaking filings. Bottom-up project pipeline tracking triangulated with top-down construction spend forecasts across the analysis window.
Calibration against historical certification volume data and disclosed green bond issuance flows anchored growth trajectory modeling across building type, material specification, technology integration, and certification protocol dimensions. CAGRs derived from segment-level construction cost indices and regulatory compliance timeline compression. Key inputs included embodied carbon threshold evolution in Nordic public infrastructure procurement and electrification mandate acceleration in US commercial building codes.
Sensitivities concentrate around copper and rare earth price volatility, skilled MEP engineer availability, and cross-jurisdiction compliance layering between EU, US, and Chinese regulatory frameworks. Quarterly review of ENERGY STAR disclosure mandate enforcement intensity and municipal bond climate covenant adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Global Green Walls Market
Green Building Materials
North America Green Cement Market
Green Building Materials
Green Concrete Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Outdoor Flooring Market
Green Building Materials
Solar Frames Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Green Building Materials Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Green Roof Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
GCC Green Cement Market