
 Solar Aerators Market | 2026-2036
Solar Aerators Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Aerators Market Insights
The EPA's Clean Water Act enforcement tightening is consolidating demand around solar-powered aeration as municipalities seek compliance without grid dependency. Kasco Marine leverages its marine equipment heritage to dominate floating platform deployments across Midwest lake restoration projects. Solaer anchors its position through proprietary solar array integration that sustains oxygen output during low-light conditions. American Aeration competes on diaphragm pump specialization for shallow aquaculture ponds, while Airmax controls retail distribution channels for private waterbody owners.
Solar aerators are photovoltaic-driven mechanical oxygenation devices that transfer atmospheric oxygen into water columns through subsurface diffusers or surface agitators, typically operating at 2-5 cubic feet per minute per unit depending on diffuser depth and basin geometry. Their primary industrial purpose is maintaining dissolved oxygen above regulatory thresholds in wastewater lagoons, aquaculture ponds, and nutrient-impaired reservoirs without electrical infrastructure. Floating technology leads installation volumes due to minimal site preparation requirements, while subsurface configurations command premium positioning for aesthetic-sensitive applications like golf course water features. The diaphragm product type occupies the largest margin pool owing to seal longevity and repair simplicity, whereas centrifugal designs represent the fastest-growing category in large-scale aquaculture oxygenation where higher throughput justifies capital intensity.
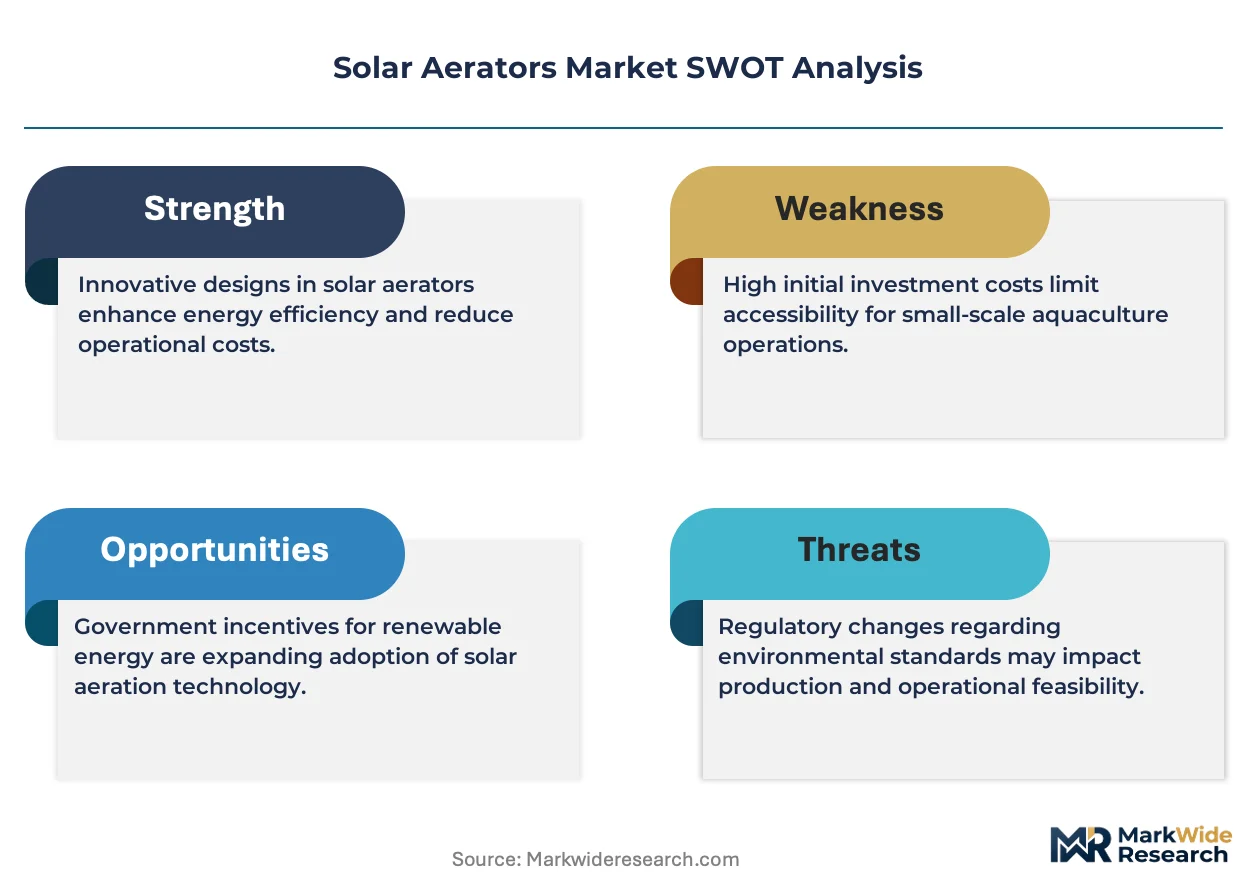
The EPA sets effluent dissolved oxygen minimums that shape equipment sizing standards, while state-level nutrient management plans in Iowa and Wisconsin mandate aerator coverage ratios for confined animal feeding operations. ISO 14001 environmental management certification increasingly gates vendor qualification for municipal procurement, and the USDA's Environmental Quality Incentives Program subsidizes solar aerator installation on agricultural wastewater systems. Stakeholders must monitor how state renewable energy credit programs evolve their treatment-equipment eligibility criteria, as this determines effective payback periods for capital-intensive hybrid configurations.
Market Dynamics
EPA enforcement of dissolved oxygen effluent standards is forcing municipal wastewater operators to retrofit aging lagoon infrastructure with off-grid oxygenation systems, consolidating procurement around photovoltaic-driven mechanical aeration that eliminates electrical infrastructure dependency.
Growth Catalysts
- Clean Water Act compliance mandates:The EPA's tightening enforcement of effluent dissolved oxygen minimums drives equipment sizing standards across municipal wastewater facilities.
- Dairy lagoon remediation requirements:California's Central Valley agricultural corridor sustains equipment pull through confined animal feeding operation nutrient management mandates.
- USDA Environmental Quality Incentives Program:Federal subsidies for agricultural wastewater system solar aerator installation compress capital payback periods for dairy and livestock operators.
Market Restraints
- Photovoltaic module cost volatility:Solar panel input price fluctuations compress margin predictability for integrated system manufacturers dependent on crystalline silicon supply chains.
- Diaphragm seal replacement cycles:Wear-component longevity limitations in high-salinity aquaculture environments elevate total cost of ownership calculations against centrifugal alternatives.
- State renewable energy credit eligibility fragmentation:Inconsistent treatment-equipment qualification criteria across jurisdictions extends effective payback period uncertainty for hybrid configuration buyers.
Strategic Opportunities
- Golf course water feature aesthetics:Subsurface diffuser configurations command premium positioning in recreational waterbody applications where surface agitation visibility is unacceptable.
- ISO 14001 certification gating:Environmental management system compliance increasingly determines vendor qualification for municipal procurement, favoring certified integrated system providers.
- Low-light solar array optimization:Proprietary photovoltaic integration sustaining oxygen output during dawn/dusk periods opens competitive differentiation in high-latitude installations.
Industry Challenges
- Field technician photovoltaic-electromechanical cross-training:Dual competency requirements in solar array diagnostics and diaphragm pump maintenance strain rural service network deployment.
- Legacy lagoon geometry retrofit compatibility:Irregular basin depths and liner conditions in aging municipal infrastructure complicate standardized floating platform anchoring system design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Aerators Market |
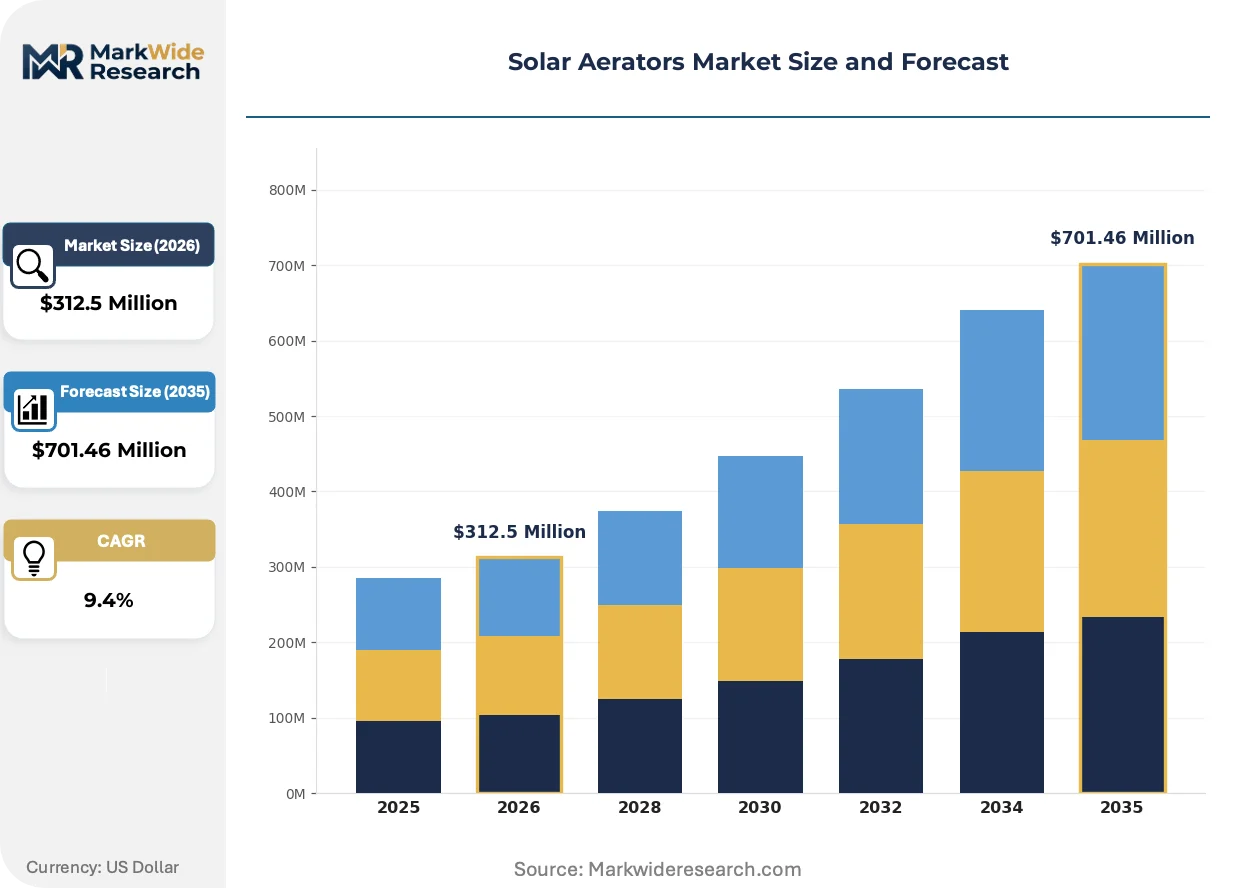
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $701.46 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Floating, Subsurface, Solar-Powered, Hybrid End User: Aquaculture, Wastewater Treatment, Water Parks, Golf Courses Product Type: Diaphragm, Piston, Centrifugal, Linear Application: Oxygenation, Mixing, De-stratification, Nutrient Distribution |
| Companies Covered | American Aeration, Solitude Lake Management, HQUA, Lancoon, NFESOLAR, Kasco Marine, Solaer, Night Air, Airmax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Aerators Market Trends and Innovations
Photovoltaic array efficiency gains and diffuser material advances are compressing unit economics for off-grid oxygenation, while regulatory enforcement timelines accelerate replacement cycles for grid-dependent legacy equipment.
Perovskite-enhanced photovoltaic cells are absorbing incremental irradiance during overcast conditions, extending daily operational windows for floating platform deployments. Municipal wastewater operators in the Pacific Northwest are piloting these arrays to maintain dissolved oxygen thresholds through extended cloud cover periods. The technology is absorbing market share from conventional crystalline silicon configurations in high-latitude, low-insolation geographies where seasonal output consistency determines specification.
The EPA's effluent limitation guidelines revision for concentrated animal feeding operations is mandating aerator coverage ratios that shape equipment sizing standards. Iowa and Wisconsin state nutrient management plans now prescribe minimum oxygen transfer rates per lagoon surface acre, compressing procurement evaluation cycles. Dairy cooperatives are responding by consolidating equipment purchases through multi-facility master service agreements to secure volume pricing on standardized floating platform configurations.
After-sales service unbundling is fragmenting buyer-supplier relationships as municipal procurement officers separate capital equipment acquisition from multi-year maintenance contracts. Third-party solar field service networks are displacing manufacturer-direct technician deployment in the Midwest lake restoration segment. This pattern is most visible across Minnesota and Wisconsin county water quality districts, where independent photovoltaic maintenance contractors now handle array cleaning and electrical diagnostics while diaphragm pump rebuilds remain with original equipment specialists.
Solar Aerators Market Segmentation
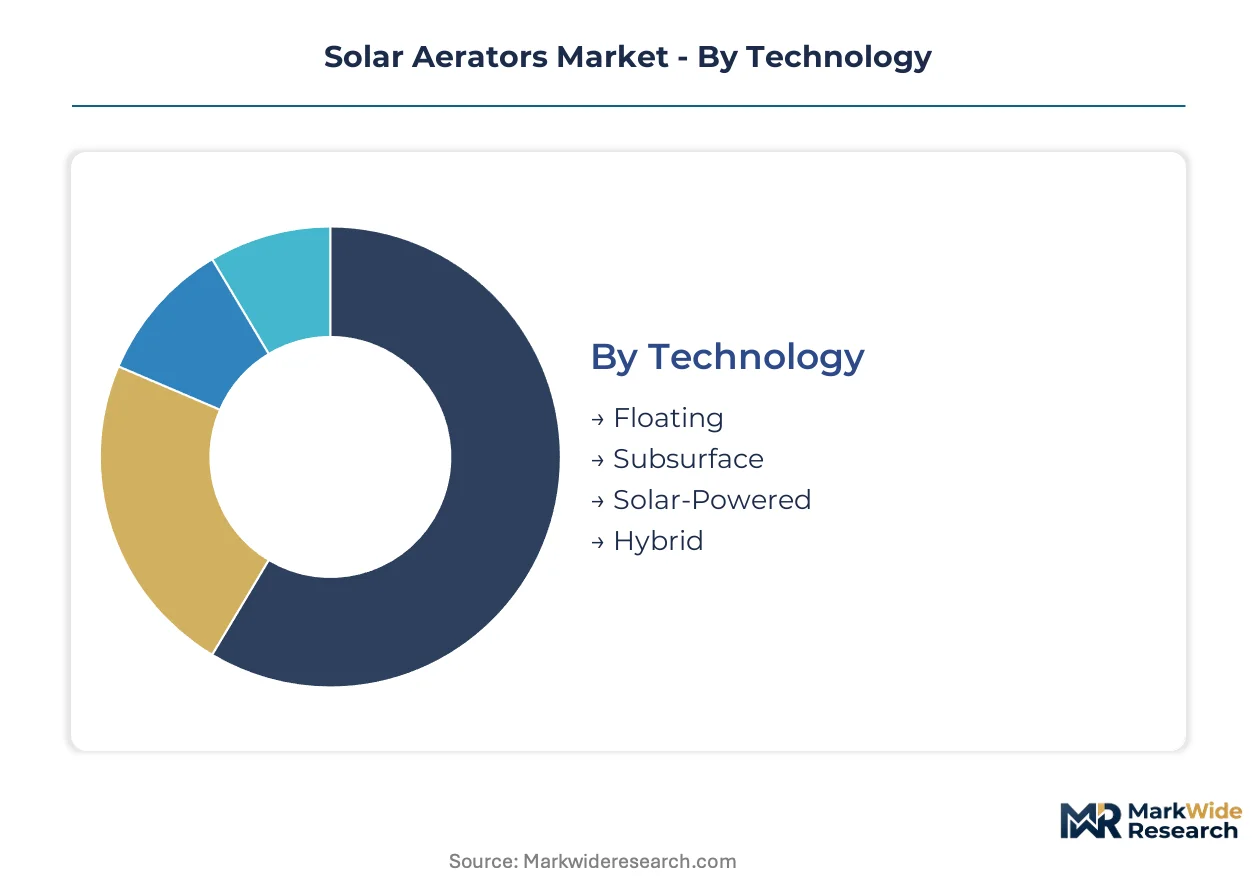
Segmentation in solar aerators reveals how equipment specifications align with site constraints and regulatory requirements. Technology choice determines installation feasibility, while end-use dictates oxygen transfer rate specifications and maintenance protocols.
Technology:
Retrofit cycles in aging lagoon infrastructure are accelerating technology selection decisions as operators balance capital constraints against performance guarantees.
- Floating:Surface-deployed platforms with minimal site preparation requirements anchor deployment volumes across Midwest municipal wastewater lagoons. Operators favor these configurations where irregular basin geometries complicate fixed installation.
- Subsurface:Below-surface diffuser arrays eliminate surface agitation visibility for golf course water features and recreational reservoirs. Premium positioning reflects aesthetic compliance requirements in high-amenity settings.
- Solar-Powered:Standalone photovoltaic arrays with integrated battery storage serve remote aquaculture ponds lacking grid connectivity.
- Hybrid:Grid-tied backup systems with automatic switching maintain oxygenation during extended low-light periods in high-latitude dairy operations.
Volume placements concentrate in Floating; the faster expansion belongs to Hybrid.
End User:
Cost tier differentiation separates capital-intensive municipal procurement from subsidy-dependent agricultural installations.
- Aquaculture:High-density shrimp and finfish operations in the Gulf Coast region specify centrifugal configurations for continuous oxygen transfer. USDA Environmental Quality Incentives Program subsidies compress payback periods for certified producers.
- Wastewater Treatment:Municipal lagoon operators in Iowa and Wisconsin face state nutrient management plan mandates prescribing minimum aerator coverage ratios. EPA Clean Water Act enforcement timelines are compressing procurement evaluation cycles.
- Water Parks:Recreational facilities prioritize subsurface configurations to maintain visual clarity for visitor experience.
- Golf Courses:Superintendents select low-profile floating units where water features border playing corridors.
Procurement volume clusters in Wastewater Treatment; Aquaculture climbs the fastest as intensification drives oxygen demand.
Product Type:
Margin structure varies sharply across mechanical designs as seal longevity and repair accessibility determine lifetime cost calculations.
- Diaphragm:Elastomer-sealed positive displacement pumps dominate installed base owing to field-repair simplicity and parts availability. The largest margin pool reflects standardized rebuild kits and technician familiarity.
- Centrifugal:Impeller-driven high-throughput designs justify capital intensity in large-scale aquaculture where cubic-feet-per-minute requirements exceed diaphragm practical limits. Steepest expansion trajectory follows recirculating aquaculture system adoption.
- Piston:Robust compression mechanics serve high-salinity environments where diaphragm elastomers degrade prematurely.
- Linear:Oscillating magnetic drive configurations reduce moving parts for remote installations with limited service access.
Revenue concentration sits with Diaphragm; Centrifugal gains share fastest on throughput advantages.
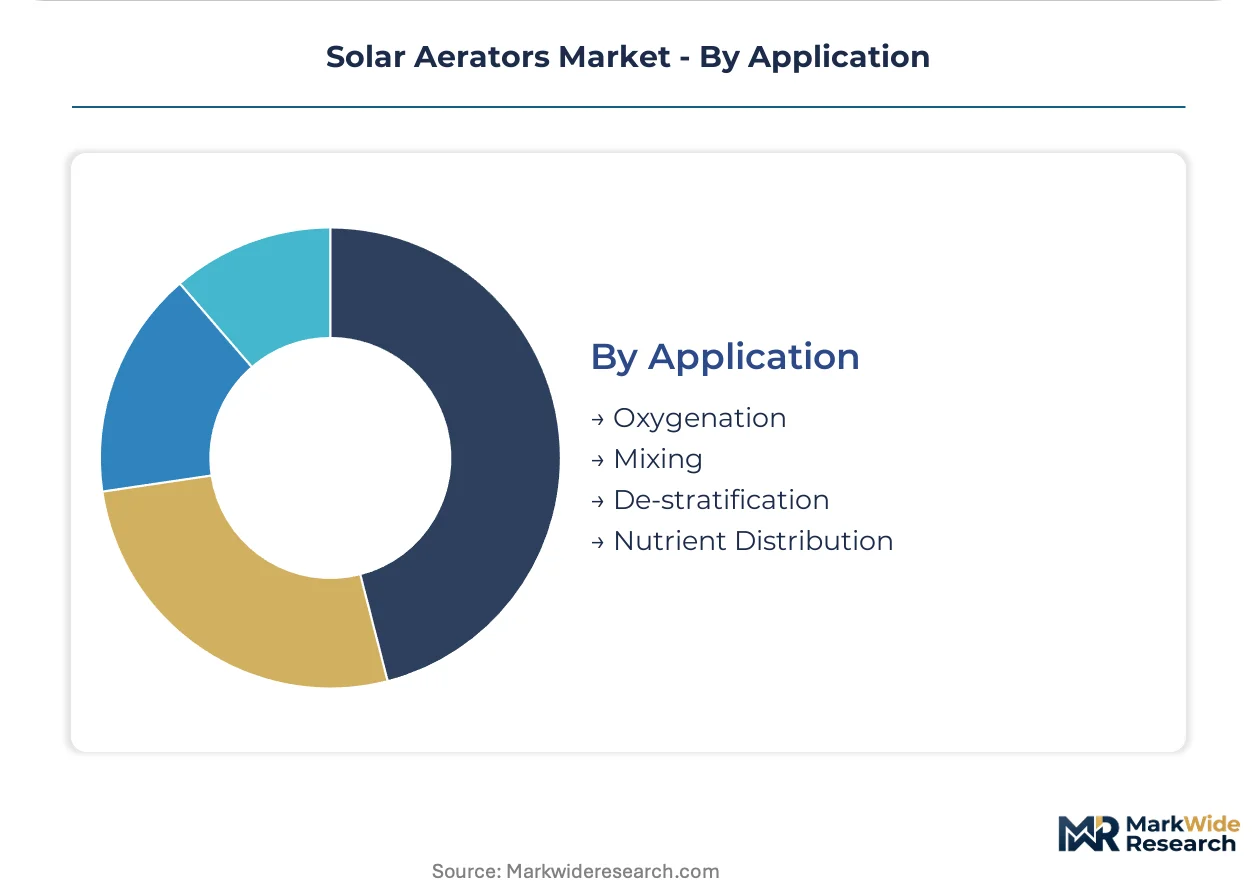
Application:
Functional specification depth determines equipment sizing standards as regulators tighten effluent thresholds across discharge categories.
- Oxygenation:Dissolved oxygen maintenance above regulatory minimums constitutes the core functional requirement shaping all equipment specifications. EPA effluent limitation guidelines prescribe performance thresholds that cascade into mechanical sizing calculations.
- Mixing:Circulation patterns prevent thermal stratification and distribute oxygenated water columns throughout basin volumes. Municipal operators in California's Central Valley deploy mixing-optimized configurations for dairy lagoon remediation mandates.
- De-stratification:Thermal layer disruption prevents anoxic bottom conditions in deep reservoirs.
- Nutrient Distribution:Phosphorus and nitrogen dispersion supports biological treatment processes in constructed wetlands.
Deployment volume centers on Oxygenation; Nutrient Distribution expands most quickly on constructed wetland proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley agricultural corridor anchors procurement intensity for solar aerators, where dairy lagoon remediation mandates sustain equipment pull across concentrated animal feeding operations. Municipal wastewater operators in Iowa and Wisconsin retrofit aging infrastructure under state nutrient management plans. Aquaculture intensification along the Gulf Coast drives centrifugal configuration demand.
United States
EPA Clean Water Act enforcement tightening consolidates demand around off-grid oxygenation systems as municipalities eliminate grid dependency. The USDA Environmental Quality Incentives Program subsidizes agricultural wastewater installations, compressing capital payback periods for dairy operators. Minnesota and Wisconsin county water quality districts fragment buyer-supplier relationships through third-party solar field service networks.
Canada
Health Canada and PMRA nutrient discharge guidelines shape equipment sizing standards for agricultural wastewater lagoons in Ontario and Quebec. Provincial renewable energy credit programs determine effective payback periods for hybrid configuration buyers. The Prairie Provinces sustain floating platform deployments where irregular basin geometries complicate fixed installations.
Germany
ECHA REACH compliance and EU Green Deal water quality targets accelerate municipal lagoon retrofit cycles across Bavaria and North Rhine-Westphalia. CE marking gates vendor qualification for public procurement. The country's dual competency requirements in solar array diagnostics strain rural service network deployment.
China
MEE effluent limitation guidelines mandate aerator coverage ratios for intensive aquaculture operations in the Yangtze River Delta. NMPA environmental management certification increasingly determines vendor qualification for state-owned facility procurement. Shandong Peninsula shrimp farming clusters specify centrifugal configurations for continuous oxygen transfer.
Australia
TGA-aligned state environmental regulators prescribe minimum oxygen transfer rates for constructed wetlands treating agricultural runoff in New South Wales and Victoria. ISO 14001 certification favors integrated system providers in municipal procurement. Queensland aquaculture intensification drives diaphragm pump specialization for remote installations with limited service access.
Solar Aerators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier and service-integration dimensions, with ISO 14001 compliance and bundled maintenance contracts separating pricing tiers. The vendor base clusters around three strategic archetypes: marine equipment heritage firms leveraging floating platform expertise, proprietary solar array integrators sustaining low-light output, and diaphragm pump specialists optimizing shallow aquaculture applications. Dominant competitive moves include after-sales service unbundling to capture third-party maintenance revenue and perovskite photovoltaic licensing to extend operational windows in high-latitude geographies.
Within the heritage-marine tier, Kasco Marine and Solaer occupy positions shaped by equipment legacy and proprietary integration respectively. American Aeration exemplifies the diaphragm-specialist archetype, while Airmax anchors retail distribution positioning for private waterbody owners. These firms represent competitive positioning patterns rather than discrete strategic actions, with each archetype responding to distinct procurement evaluation criteria across municipal, agricultural, and recreational end-use segments.
| Leading Market Players |
|---|
| American Aeration |
| Solitude Lake Management |
| HQUA |
| Lancoon |
| NFESOLAR |
| Kasco Marine |
| Solaer |
| Night Air |
| Airmax |
| Others |
Pricing and Supply Chain Analysis
ISO 14001 certification divergence separates premium-integrated system providers from commodity diaphragm pump assemblers, with this bifurcation manifesting in both pricing power concentration among certified vendors and supply chain tiering that sources crystalline silicon arrays from tier-1 photovoltaic manufacturers while relegating uncertified competitors to spot-market module procurement.
Pricing Analysis
Oxygen-transfer-rate guarantees anchor value-based pricing as municipalities and aquaculture operators contract for dissolved oxygen outcomes rather than equipment ownership. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 14001 certification status, after-sales service bundling, and photovoltaic array efficiency ratings. Pricing pressure stems from crystalline silicon module cost volatility compressing margin predictability for integrated system manufacturers. Agricultural buyers subsidized through USDA Environmental Quality Incentives Program exhibit lowest price sensitivity, while municipal procurement officers facing fixed capital budgets demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese crystalline silicon photovoltaic cell suppliers dominating upstream array production. Crystalline silicon wafers, elastomer diaphragm seals, and submersible-grade stainless steel housings draw from concentrated manufacturing bases in China, Germany, and Japan. Tariff exposure on imported photovoltaic modules constitutes the primary structural risk for North American system integrators. Distribution runs through manufacturer-direct sales for municipal wastewater contracts and agricultural equipment dealers for dairy lagoon retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar aerators market sits in a technology-transition phase as perovskite-enhanced photovoltaic arrays displace conventional crystalline silicon configurations in high-latitude, low-insolation geographies where seasonal output consistency determines specification.
For Market Incumbents: Anticipate perovskite photovoltaic licensing agreements from materials science specialists eroding crystalline silicon efficiency advantages within premium municipal procurement segments. Defend position by deepening backward integration into diaphragm seal manufacturing to control wear-component replacement revenue streams. Prioritize ISO 14001 certification maintenance as procurement gating tightens across Iowa and Wisconsin county water quality districts. For New Entrants and Emerging Players: Direct-to-farmer digital channels offer lowest customer acquisition cost entry into California Central Valley dairy cooperative procurement networks. Target unpenetrated golf course water feature segments in the Pacific Northwest where subsurface diffuser aesthetic requirements command premium positioning. Pursue third-party solar field service network partnerships to bypass capital-intensive technician deployment infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with proprietary solar array integrators sustaining low-light oxygen output given perovskite technology licensing momentum. Five-to-ten-year viability favors vendors with bundled maintenance contract revenue visibility exceeding equipment sale cyclicality. Monitor state renewable energy credit program treatment-equipment eligibility expansion as inflection signal for hybrid configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Photovoltaic Licensing | Extends operational windows in Pacific Northwest municipal procurement where cloud cover limits conventional array output. |
| Backward Integration into Diaphragm Manufacturing | Captures recurring replacement kit revenue from high-salinity aquaculture environments with accelerated seal degradation. |
| ISO 14001 Certification Investment | Gates vendor qualification for Iowa and Wisconsin municipal lagoon retrofit contracts under tightening environmental management standards. |
| Third-Party Service Network Partnership | Fragments buyer-supplier relationships across Minnesota county water quality districts through independent photovoltaic maintenance contractor deployment. |
| Master Service Agreement Consolidation | Secures volume pricing for California dairy cooperatives responding to state nutrient management plan coverage ratio mandates. |
Research Methodology
EPA enforcement documentation, USDA Environmental Quality Incentives Program subsidy records, and state nutrient management plan filings formed the secondary backbone, cross-referenced with primary interviews involving municipal wastewater operations managers, dairy lagoon compliance officers, aquaculture facility engineers, and photovoltaic array field service technicians. Bottom-up equipment shipment data triangulated against top-down regulatory mandate coverage ratio calculations.
Historical lagoon retrofit cycle analysis established baseline replacement rates across Midwest municipal infrastructure. Segmentation modeling incorporated technology type, end-user category, product mechanical design, and oxygenation application function throughout the forecast period. CAGRs derived from regulatory enforcement timeline acceleration and photovoltaic efficiency improvement curves. Forecast inputs included crystalline silicon price volatility scenarios and perovskite commercialization trajectory assumptions.
The model holds under sustained EPA Clean Water Act enforcement intensity and crystalline silicon supply chain stability; deviation in renewable energy credit program eligibility expansion or diaphragm seal material breakthroughs would shift replacement cycle assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Zero Liquid Discharge Market
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Portable Filtration System Market